
 North America Snack Food Market | 2026-2036
North America Snack Food Market Size, Share, and Industry Trends Forecast 2026-2036
North America Snack Food Market Analytics
Asset-light co-manufacturing and third-party production leasing is fragmenting competitive dynamics in the North America snack food sector. PepsiCo Inc. leverages its captive distribution network and direct-store-delivery infrastructure to sustain shelf presence. Mondelez International anchors its position through specialized chocolate and biscuit manufacturing scale. General Mills Inc. competes via diversified brand portfolios spanning multiple flavor and texture platforms.
North America snack food encompasses processed, ready-to-eat consumables formulated from grains, oilseeds, tubers, or dairy substrates, typically shelf-stable at ambient temperatures with moisture content below four percent for crispy formats. These products serve impulse consumption occasions across retail, foodservice, and institutional channels. Chips within the product type dimension dominate absolute dollar contribution due to per-unit velocity and household penetration, while pouches within packaging type represent the fastest-expanding format driven by portion-control demand and e-commerce shipability. The savory flavor profile occupies the mature margin pool, whereas spicy variants command premium positioning.
The FDA governs ingredient safety declarations and allergen labeling under FALCPA, while the USDA oversees meat-containing snack formulations through FSIS inspection protocols. The EPA regulates industrial emissions from frying and baking operations, particularly affecting facility siting decisions. Stakeholders must monitor evolving sodium and added-sugar guidance from federal agencies, as anticipated rulemaking will determine reformulation investment timelines and clean-label claim defensibility.
Market Dynamics
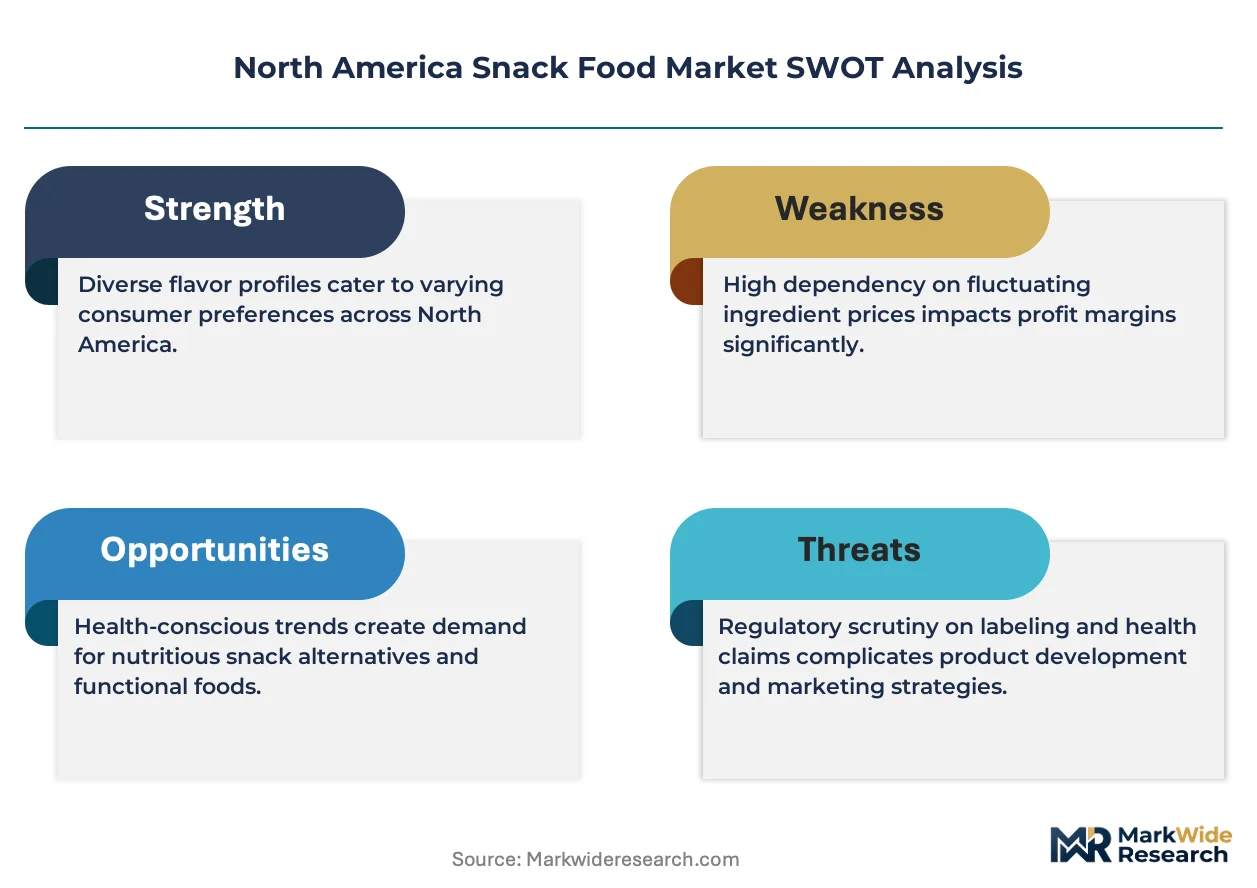
Co-manufacturing networks are fragmenting production economics across the North America snack food sector, eroding captive scale advantages and forcing established brands to defend shelf velocity through direct-store-delivery infrastructure rather than manufacturing dominance.
Growth Catalysts
- FDA Nutrition Facts Labeling:Reformulation investments triggered by updated sodium and added-sugar guidance are accelerating clean-label product pipelines across California and Texas metropolitan corridors.
- Portion-Control Pouch Demand:E-commerce shipability requirements are pulling flexible packaging formats into convenience store channels previously dominated by rigid containers.
- Spicy Flavor Premiumization:Heat-forward product development is capturing margin expansion in savory categories where mature price points have compressed returns.
Market Restraints
- Input Cost Volatility:Sunflower and canola oil price swings tied to Black Sea supply disruptions are compressing frying operation margins in US Midwest production clusters.
- EPA Emissions Protocols:Industrial frying and baking emission standards are constraining facility siting options in ozone non-attainment zones across the American Southwest.
- Meat-Containing Formulation Barriers:USDA FSIS inspection requirements for jerky and meat-inclusive snacks create regulatory friction that blocks rapid product pivots from plant-based manufacturers.
Strategic Opportunities
- Texas Corridor Expansion:Underpenetrated Hispanic flavor profiles in Dallas-Fort Worth and Houston metro areas offer white space for authentic chili-lime and tamarind product launches.
- Convenience Store Channel Innovation:Grab-and-go refrigerated snack sets are displacing ambient shelf-stable fixtures in Canadian petroleum retail locations.
- Dual Carbon Alignment:Mexico's clean energy transition incentives are creating co-manufacturing cost advantages for brands sourcing renewable-powered production in Baja California.
Industry Challenges
- Reformulation Talent Scarcity:Food scientists capable of sodium reduction without taste degradation command premium compensation in California's competitive labor market.
- Legacy DSD Integration:Direct-store-delivery route optimization software from PepsiCo and similar operators resists interoperability with third-party logistics platforms.
- FALCPA Compliance Timelines:Allergen labeling verification protocols extend new product introduction cycles by four to six months in multi-facility production networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Snack Food Market |
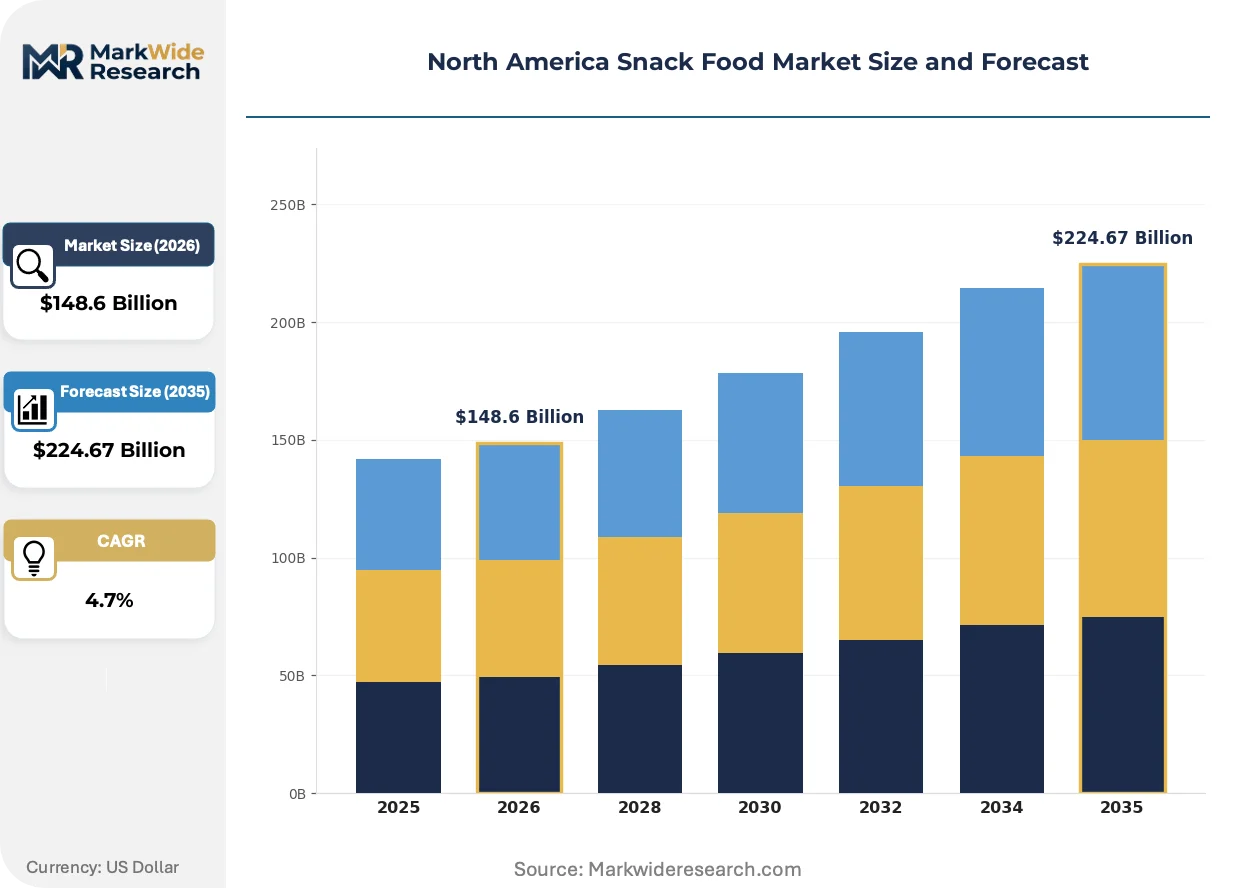
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $224.67 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Crackers, Popcorn, Nuts Flavor Profile: Sweet, Savory, Spicy, Cheesy Packaging Type: Bags, Boxes, Pouches, Tubs Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores |
| Companies Covered | General Mills Inc., Mondelez International, PepsiCo Inc., Clif Bar & Company, Kraft Heinz Company, Nestle SA, Conagra Brands Inc., McCain Foods, Kellogg Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Snack Food Market Evolving Landscape
Pulse-based protein extrusion and precision fermentation are converging to reshape ingredient sourcing economics, while regulatory pressure on sodium thresholds forces simultaneous investment in taste-masking technologies and front-of-pack communication strategies.
High-moisture extrusion of pea and lentil proteins is rendering obsolete traditional dry-extruded corn and potato bases in better-for-you puffed snacks. California-based natural product startups are adopting these systems at pilot scale within eighteen-month capital cycles. The technology is rendering obsolete legacy texture standards that relied on fat content for mouthfeel, compressing reformulation timelines for brands targeting clean-label positioning.
The FDA's anticipated added-sugar disclosure rules are forcing carbohydrate-based snack categories to retool sweetness delivery through monk fruit and allulose systems. Manufacturers face eighteen-to-twenty-four-month reformulation windows to maintain shelf placement under revised Nutrition Facts panels. Meat-containing snack segments governed by USDA FSIS protocols are responding through savory umami builds that reduce dependence on sweet barbecue and honey flavor profiles.
Canadian petroleum retail operators are unbundling snack procurement from fuel supply contracts, enabling direct brand negotiations previously blocked by distributor exclusivity. Ontario and Alberta convenience store chains are establishing private-label snack programs that bypass legacy wholesale intermediaries. This disintermediation is most visible in Quebec, where Couche-Tard's vertical integration into snack manufacturing has compressed third-party brand margins in core metropolitan markets.
North America Snack Food Market Segmentation
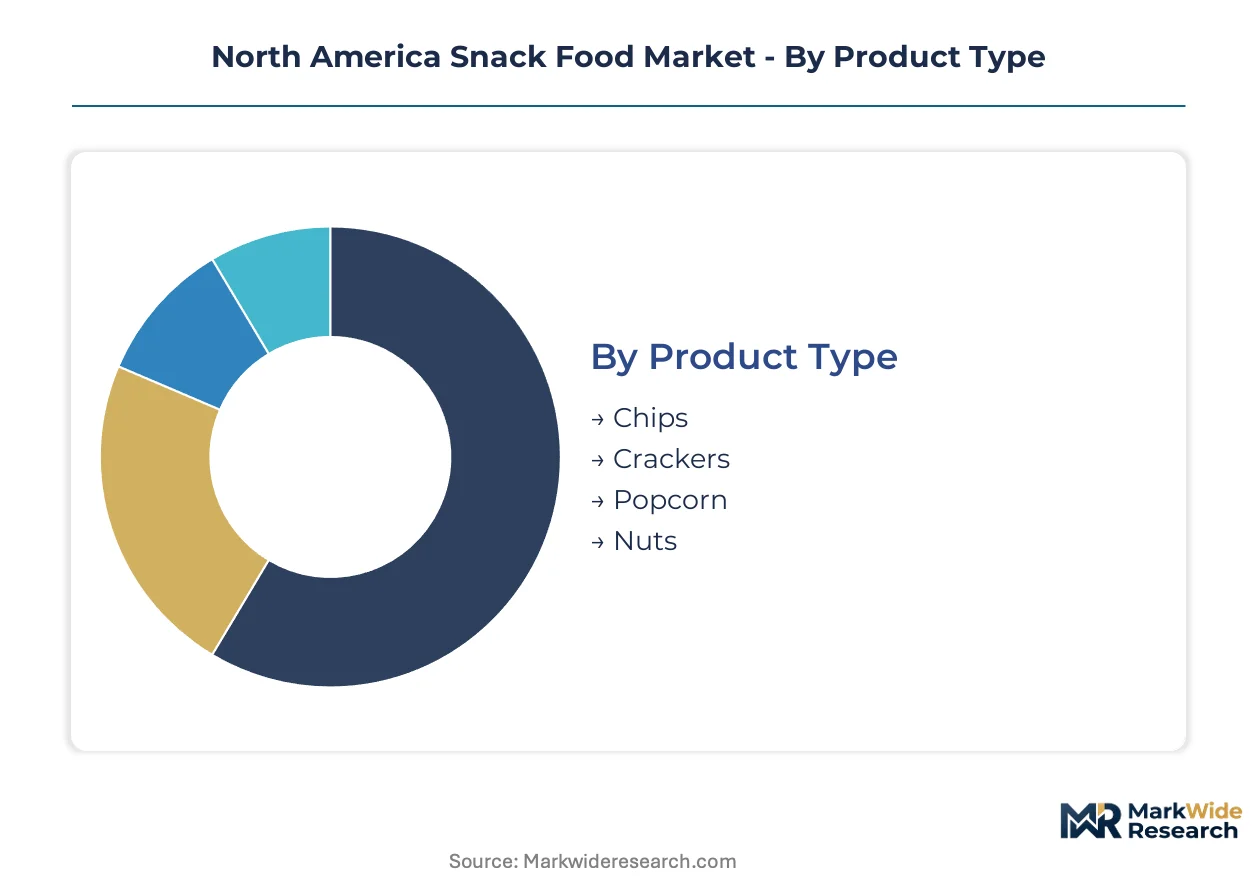
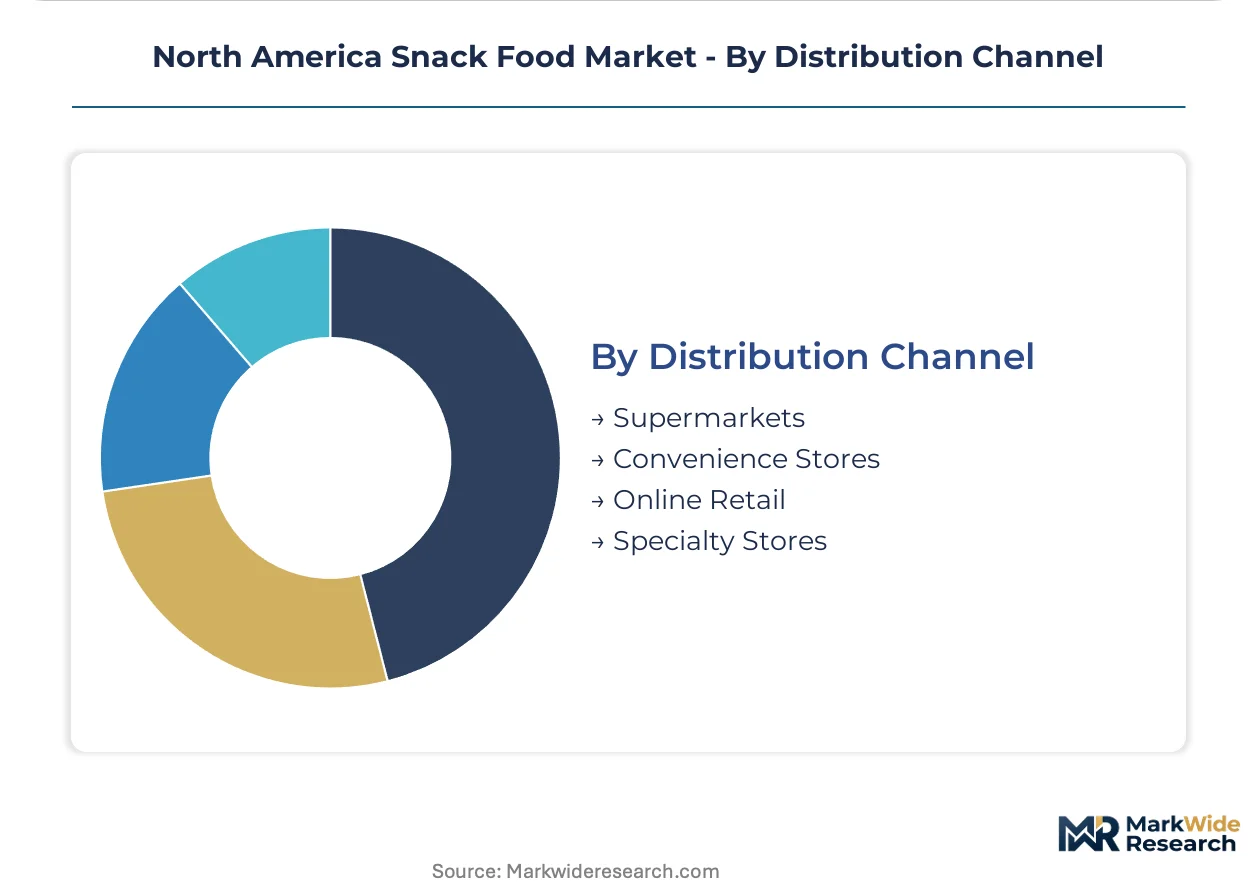
Snack food segmentation in North America reflects divergent consumption occasions, from impulse convenience store purchases to planned e-commerce pantry stocking. Understanding these dimensional splits enables targeted reformulation and channel-specific packaging investments.
Product Type:
Consumption occasions span from solitary desk snacking to social sharing environments, driving distinct texture and format requirements across substrate categories.
- Chips:Thin-sliced potato, corn, or alternative tuber bases fried or baked to sub-four-percent moisture content. Dollar velocity concentrates in California and Texas metropolitan corridors where Hispanic flavor innovation commands shelf space.
- Crackers:Laminated or chemically leavened wheat-based formats with moisture content typically eight to twelve percent. Demand clusters in Northeast US commuter corridors for portable protein pairings.
- Popcorn:Air-popped or oil-popped whole grain with expanding better-for-you positioning through minimal oil and clean-label seasoning systems.
- Nuts:Roasted or raw tree nuts and legumes, often dry-roasted or oil-roasted with salt or flavor coatings.
The dominant share belongs to Chips, while Popcorn is closing the gap fastest through health-positioned innovation.
Flavor Profile:
Margin structures vary sharply across taste architectures, with premium pricing achievable in heat-forward and artisanal savory builds.
- Savory:Salt, onion, garlic, and herb-based seasoning systems representing the mature volume base. Reformulation pressure from FDA sodium guidance is accelerating clean-label salt replacer adoption.
- Spicy:Chili, pepper, and heat-forward builds commanding fifteen to twenty-five percent price premiums in Texas and Southwest US markets. Authentic Hispanic profiles in Dallas-Fort Worth and Houston metro areas drive white-space expansion.
- Sweet:Sugar, honey, and confectionery-based coatings facing compressed margins from anticipated added-sugar disclosure rules.
- Cheesy:Natural and artificial cheese powders delivering umami depth, particularly dominant in Midwest US consumption patterns.
Savory holds the volume anchor position, though Spicy claims the steepest expansion trajectory through demographic flavor preference shifts.
Packaging Type:
Shipability and portion-control demands are restructuring format economics across retail and e-commerce channels.
- Pouches:Flexible multilayer films with resealable zipper closures, optimized for e-commerce shipability and single-serve portioning. Convenience store channel adoption is displacing rigid formats previously dominant in petroleum retail.
- Bags:Traditional pillow pouches and stand-up bags for family-size and value-tier offerings.
- Boxes:Rigid paperboard for premium gift sets and multi-pack assortments.
- Tubs:Rigid plastic containers for bulk nuts and popcorn, facing sustainability pressure from extended producer responsibility schemes.
Pouches are gaining share fastest in convenience and online channels, while Bags retain absolute volume leadership.
Distribution Channel:
Route-to-market configuration determines margin capture and brand control intensity.
- Convenience Stores:Impulse-driven petroleum retail and urban grab-and-go locations. Canadian operators are unbundling snack procurement from fuel supply contracts, enabling direct brand negotiations.
- Supermarkets:Planned-purchase environments with extensive shelf sets and promotional intensity.
- Online Retail:E-commerce platforms requiring ship-optimized packaging and subscription replenishment models.
- Specialty Stores:Natural product and ethnic-focused retailers curating premium and import-positioned offerings.
Supermarkets maintain the dominant channel position, while Convenience Stores are expanding fastest through format innovation and procurement restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's clean energy transition incentives and Mexico's manufacturing cost advantages are reshaping production siting decisions across the North American snack food sector. The United States maintains demand concentration in coastal metropolitan corridors, while regulatory fragmentation across the three countries creates distinct operational constraints.
United States
California and Texas metropolitan corridors drive Hispanic flavor innovation and clean-label product launches. The FDA's updated Nutrition Facts labeling requirements for sodium and added-sugar disclosures are accelerating reformulation investments. Dallas-Fort Worth and Houston anchor expanding spicy flavor development clusters targeting underpenetrated demographic segments.
Canada
Ontario and Quebec convenience store chains are establishing private-label snack programs that bypass legacy wholesale intermediaries. Health Canada and PMRA oversee ingredient safety and pesticide residue standards for agricultural inputs. Couche-Tard's captive manufacturing presence in Quebec has compressed third-party brand margins in core metropolitan markets.
Mexico
Baja California co-manufacturing facilities leverage renewable energy incentives to serve cross-border brand requirements. The country's national food safety regulator enforces labeling standards aligned with US export protocols. Northern border states concentrate maize and oilseed processing infrastructure supporting tortilla chip and extruded snack production.
North America Snack Food Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented production economics. The vendor base spans multinational conglomerates with captive distribution networks, mid-scale brand houses with diversified flavor platforms, and emerging natural-product specialists with clean-label positioning. Three archetypes dominate: direct-store-delivery operators, co-manufacturing-dependent brand marketers, and vertically integrated private-label producers. Consolidation pressure operates through strategic partnerships and portfolio diversification rather than capacity-driven mergers.
Within the diversified-snack conglomerate tier, PepsiCo Inc., Mondelez International, and General Mills Inc. exemplify distinct competitive positioning. PepsiCo represents the channel-control archetype through petroleum retail and convenience store penetration. Mondelez International occupies the chocolate and biscuit specialization position with manufacturing scale concentration. General Mills Inc. anchors the multi-platform brand portfolio approach spanning savory, sweet, and better-for-you segments.
| Leading Market Players |
|---|
| General Mills Inc. |
| Mondelez International |
| PepsiCo Inc. |
| Clif Bar & Company |
| Kraft Heinz Company |
| Nestle SA |
| Conagra Brands Inc. |
| McCain Foods |
| Kellogg Company |
| Others |
Value Network & Pricing Analysis
Overcapacity in US Midwest frying operations is compressing supplier margins and forcing co-manufacturers toward aggressive contract terms, while simultaneously enabling buyers to extract price concessions on volume commitments. This utilization dynamic feeds directly into pouch format economics, where shipability premiums now determine supplier selection more than unit production cost.
Pricing Analysis
Certification level (FDA-grade clean-label positioning) creates the primary spread between premium and economy tiers, with reformulation-compliant products commanding shelf placement premiums in California and Texas metropolitan corridors. Three-tier pricing structure across premium, standard, and economy levels reflects sodium reduction investment depth and front-of-pack claim defensibility. Price erosion runs through standard-tier savory formats as co-manufacturing fragmentation intensifies bidding wars for convenience store contracts. Dollar-store channels exhibit highest price sensitivity, while specialty retailers absorb premium positioning for authentic Hispanic flavor profiles.
Supply Chain Analysis
Co-manufacturing concentration among third-party extrusion operators in Mexico's Baja California corridor and US Midwest production clusters shapes regional cost competitiveness. Raw material sourcing draws from Black Sea sunflower oil networks, Canadian pulse protein suppliers, and domestic corn processing infrastructure. Single-source vulnerability in frying oil supply creates margin volatility exposure when geopolitical disruptions interrupt seed oil flows. Distribution runs through PepsiCo and Mondelez captive direct-store-delivery networks, with emerging brands forced into third-party logistics partnerships lacking route density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reformulation-as-a-service and ongoing FDA compliance consulting represent the fastest-expanding recurring revenue layer, outpacing base product manufacturing margins as brands face compressed eighteen-to-twenty-four-month retooling windows.
For Market Incumbents: Pre-empt co-manufacturer poaching of convenience store shelf space by accelerating sodium-reduction R&D investment in California talent clusters. Lock in multi-year sunflower and canola oil offtake agreements before Black Sea supply volatility intensifies. Defend against private-label encroachment through exclusive direct-store-delivery route access in Texas metropolitan corridors.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated Hispanic flavor profiles across Dallas-Fort Worth and Houston metro areas, where authentic chili-lime and tamarind positioning commands premium shelf placement. Target Canadian petroleum retail locations undergoing procurement unbundling from fuel supply contracts. Leverage Baja California renewable-powered co-manufacturing to meet cross-border clean-label demand with cost advantages.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pulse-protein extrusion equipment as pilot-scale systems compress eighteen-month deployment cycles. Long-term viability favors brands with captive FDA reformulation expertise and direct convenience store negotiation access over pure manufacturing scale. Watch for inflection signals in Health Canada sodium guidance alignment with FDA disclosure timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Monk fruit and allulose adoption accelerates ahead of FDA added-sugar disclosure enforcement. |
| Pulse-Protein Extrusion Scale-Up | Pea and lentil protein systems displace legacy corn and potato bases in better-for-you puffed snacks. |
| Convenience Store Channel Expansion | Direct procurement negotiations in Canadian petroleum retail bypass legacy wholesale intermediaries. |
| Co-Manufacturing Network Partnership | Baja California renewable-powered facilities serve cross-border brands with carbon-aligned production. |
| Spicy Flavor Premium Tier Launch | Heat-forward product development captures margin expansion in Texas and Southwest US markets. |
Research Methodology
A standing panel of snack food brand managers, convenience store category buyers, co-manufacturing operations directors, and FDA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from Nielsen retail audit data, USDA FSIS inspection protocols, EPA emissions filings, and customs records tracking oilseed and pulse protein trade flows. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Scenario-bracketing across base, accelerated reformulation, and delayed regulatory enforcement cases bounded volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, flavor profile, packaging format, and distribution channel, with regulatory compliance tier as an industry-specific overlay. CAGRs derived from iterative reconciliation of historical velocity trends, demographic flavor preference shifts, and channel penetration rates against input cost trajectory assumptions.
Stress conditions across sunflower oil price volatility, FDA sodium guidance timing, and EPA ozone non-attainment zone expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding clean-label adoption curves and co-manufacturing capacity absorption. Quarterly review of Health Canada sodium guidance alignment and Couche-Tard vertical manufacturing expansion indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Calorie Dip Market
Snacks
Oat-Based Snacks Market
Snacks
Spain Snack Bar Market
Snacks
Instant Meat Marinated Snacks Market
Snacks
Extruded Cereals Market
Snacks
Baked Chips Market
Snacks
Snack Pellets Market
Snacks
Middle East Snack Bar Market
Snacks
Europe Snacks Food Market
Snacks
Packaged Rice Snacks Market
Snacks
Asia-Pacific Cereal Bar Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Seafood Snacks Market
Snacks
South America Cereal Bar Market
Snacks
High-Fat Low-Protein Snacks Market
Snacks
Europe Energy Bar Market