
 Specialty Syrup Market | 2026-2036
Specialty Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Syrup Market Insights
Specialty foodservice distribution is fragmenting as boutique roasters and craft cocktail bars bypass traditional broadline distributors to source directly from flavor houses. Monin leverages its European manufacturing footprint to sustain supply relationships with independent cafés across France and Italy. Kerry Group anchors its position through R&D intensity in natural extraction technologies for botanical syrups. Archer Daniels Midland competes on agricultural origination, controlling cane sugar and agave supply streams that feed downstream syrup refinement.
Specialty syrup denotes a concentrated aqueous solution of sucrose, fructose, or alternative sweeteners infused with fruit extracts, essential oils, botanical compounds, or spice oleoresins, typically standardized to 65-75 Brix and pasteurized for shelf stability; it functions as a flavor-delivery vehicle and sweetness modulator across commercial food and beverage preparation. Fruit-based formulations dominate volume due to their versatility in smoothies and sodas, while botanical and herbal variants capture expanding margin pools as wellness-positioned beverages multiply. Glass bottles retain preference among premium food service providers, though resin bottles gain traction in personal consumer channels seeking lighter logistics.
The FDA governs labeling and GRAS status for flavor additives entering the U.S. food supply, while the EU Green Deal and REACH framework restrict synthetic preservative use and mandate supply chain traceability for botanical raw materials. These regulatory layers elevate compliance costs for smaller compounders but simultaneously advantage scaled producers with dedicated regulatory affairs functions. Stakeholders must monitor evolving clean-label definitions and alternative sweetener approval pathways to anticipate reformulation cycles and procurement adjustments.
Market Dynamics
Clean-label mandates from the FDA and EU Green Deal are forcing simultaneous reformulation across botanical extraction, sweetener substitution, and supply chain traceability, compressing margins for compounders lacking scaled regulatory infrastructure.
Growth Catalysts
- EU Green Deal traceability mandates:Large flavor houses with dedicated compliance teams capture shelf space as smaller compounders exit. Premium coffee chains in Italy and France accelerate direct sourcing.
- Craft cocktail bar proliferation:Independent mixology venues in the United States drive small-batch botanical syrup demand, bypassing traditional broadline distributors for flavor house relationships.
- Natural extraction technologies:Supercritical CO2 and cold-press methods reduce thermal degradation of volatile compounds, enabling cleaner ingredient decks that satisfy clean-label positioning.
Market Restraints
- Agave supply concentration:Mexican highland agave harvest volatility creates input cost spikes for premium tequila-flavored and agave-based syrup portfolios.
- REACH synthetic preservative restrictions:ECHA limitations on benzoate and sorbate use force accelerated natural preservation R&D with uncertain shelf-life outcomes.
- Cane sugar price cyclicality:Brazilian and Indian harvest fluctuations transmit directly to base syrup cost structures, squeezing mid-tier private-label margins.
Strategic Opportunities
- Wellness-positioned functional beverages:Adaptogen and nootropic syrup infusions target stress-reduction and cognitive clarity claims in United States coastal metros.
- Direct-to-café distribution platforms:Digital procurement portals enable independent roasters in Germany and Spain to configure custom flavor profiles without distributor markups.
- USDA Organic and Non-GMO Project certification:Third-party verified supply chains command placement premiums in specialty grocery and natural channel retail.
Industry Challenges
- Flavor chemist talent scarcity:Natural extraction expertise and botanical sourcing knowledge concentrate at established houses, constraining new entrant formulation capabilities.
- Legacy ERP integration with traceability systems:Batch-level ingredient tracking requirements from EU Green Deal conflict with decades-old manufacturing software at mid-size compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Syrup Market |
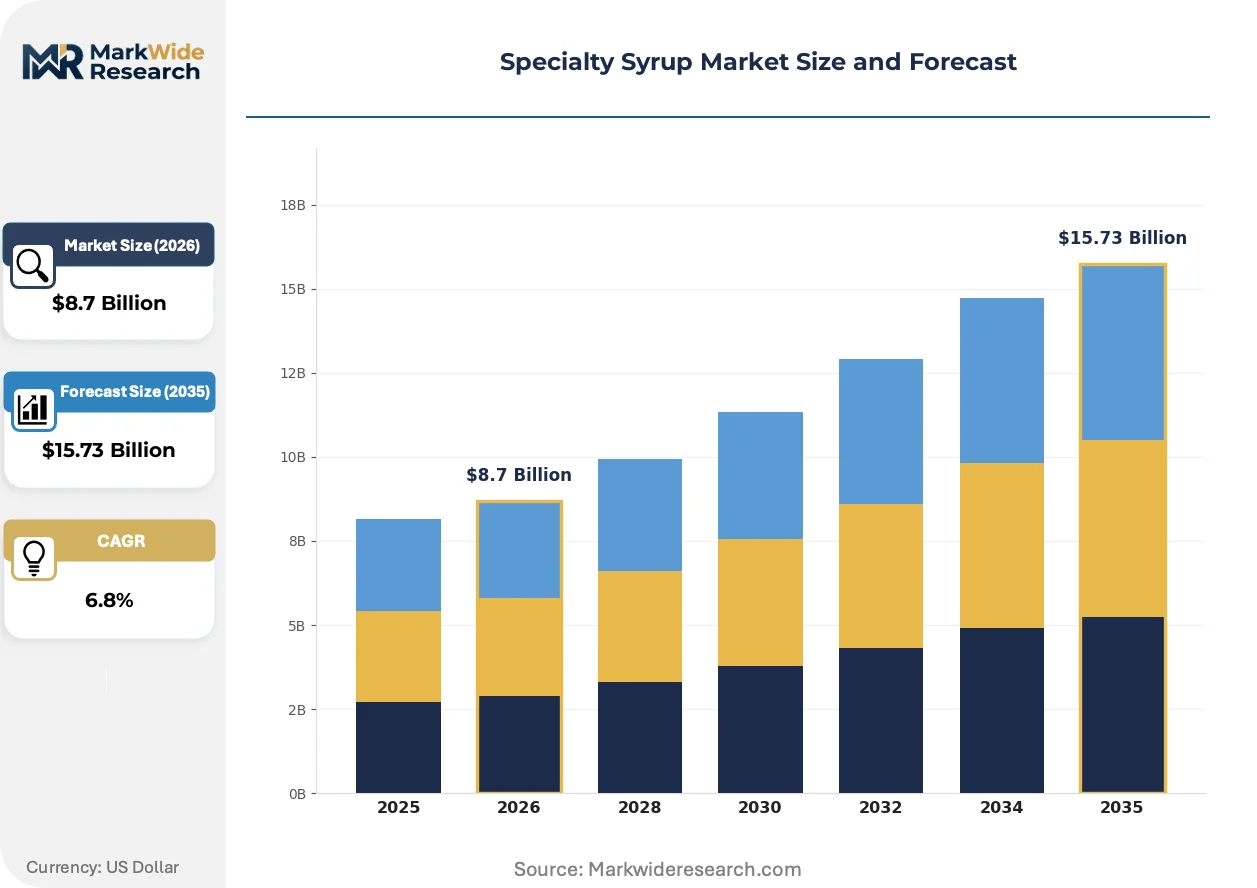
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit-based, Herbal, Floral, Spiced, Nut-flavored, Botanical Application: Beverages, Confectionery, Bakery, Pharmaceuticals, Cosmetics, Sweeteners Packaging Type: Glass Bottles, Plastic Bottles, Sachets, Tetra Pak, Metallic Cans, Resin Bottles Customer Type: Food Service Providers, Personal Consumers, Pharmacies, Cosmetic Manufacturers, Beverage Producers, Specialty Retailers |
| Companies Covered | Monin, Kerry Group, Archer Daniels Midland Company, Conagra Brands, The Hershey Company, The Kraft Heinz Company, The J.M. Smucker Company, Sensient Technologies, DaVinci Gourmet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Syrup Market Trends and Innovations
Extraction technology advances and regulatory transparency mandates are converging to reshape how flavor houses develop, manufacture, and distribute specialty syrups across foodservice and retail channels.
Supercritical CO2 extraction technology is hybridizing traditional heat-based methods to preserve volatile terpenes in botanical syrups. Premium coffee roasters in Copenhagen and Melbourne adopt these cold-processed inputs for signature seasonal offerings. The technology is compressing acceptable shelf-life windows while commanding 40-60% raw material premiums over conventional extracts.
REACH substance restrictions and EU Green Deal due diligence requirements are mandating supply chain documentation for all botanical raw materials entering European food manufacturing. Flavor houses must now maintain geolocation tagging and harvest-date records for vanilla from Madagascar, cinnamon from Sri Lanka, and citrus from Calabria. Small Mediterranean compounders without dedicated regulatory affairs functions are outsourcing compliance to specialized consultancies.
Foodservice procurement teams are consolidating supplier relationships around full-flavor-system vendors rather than maintaining discrete syrup, sauce, and topping contracts. Large United States quick-service chains now specify integrated beverage platforms where syrup formulation, equipment calibration, and staff training bundle under single-source agreements. This behavior concentrates purchasing power with houses capable of technical service deployment across multiple beverage categories.
Specialty Syrup Market Segmentation
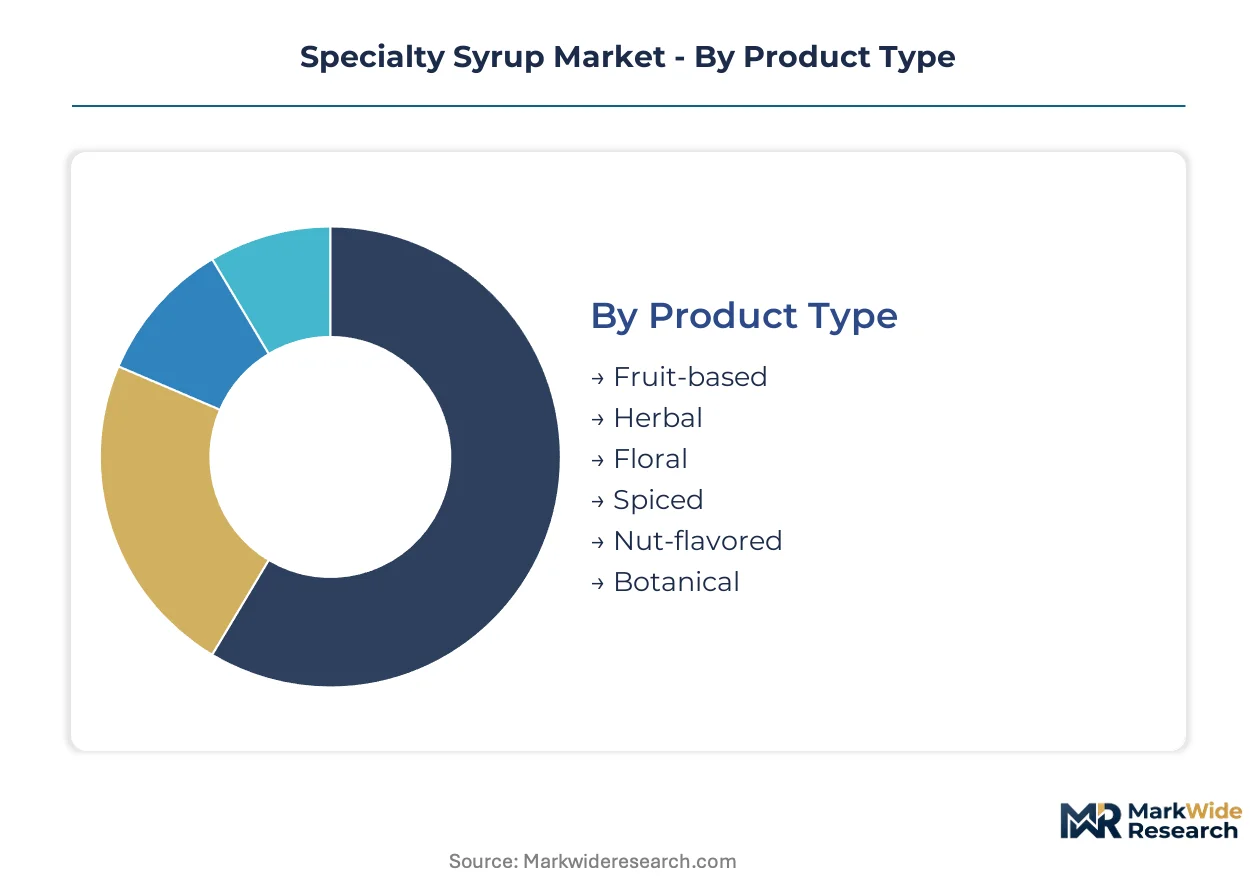
Specialty syrup segmentation reveals distinct technical requirements and procurement patterns across flavor chemistry, end-use application, and distribution format. Each dimension carries implications for formulation stability, regulatory compliance, and margin architecture that compounders must navigate simultaneously.
Product Type:
After-sales service intensity varies sharply across flavor categories, with botanical and herbal variants demanding technical consultation on extraction degradation while fruit-based formulations require minimal post-sale support.
- Fruit-based:Concentrated aqueous solutions of sucrose or fructose infused with citrus, berry, or tropical fruit extracts, standardized to 65-75 Brix. Demand concentrates in United States smoothie chains and European carbonated beverage producers seeking clean-label alternatives to artificial flavor systems.
- Botanical:Complex infusions of bark, root, and leaf extracts requiring supercritical CO2 or cold-press processing to preserve volatile terpenes. Copenhagen and Melbourne premium coffee roasters drive adoption for signature seasonal offerings, accepting compressed shelf-life windows for cleaner ingredient decks.
- Herbal:Formulations incorporating mint, basil, or rosemary oleoresins for wellness-positioned beverages.
- Floral:Lavender, rose, and elderflower extractions targeting mixology applications in craft cocktail bars.
- Spiced:Cinnamon, cardamom, and ginger infusions with concentrated demand in seasonal bakery and beverage applications.
- Nut-flavored:Hazelnut, almond, and pistachio syrups serving coffeehouse flavor systems across Italy and France.
By volume, fruit-based formulations lead. By growth pace, botanical variants are expanding most quickly.
Application:
Cost tier stratification separates commodity sweetener substitution from premium flavor-delivery systems, with beverages commanding formulation premiums and pharmaceuticals requiring excipient-grade certifications.
- Beverages:Primary revenue concentration spanning carbonated soft drinks, ready-to-drink teas, craft cocktails, and specialty coffee preparations. United States quick-service chains now specify integrated beverage platforms bundling syrup formulation, equipment calibration, and staff training under single-source agreements with full-flavor-system vendors.
- Pharmaceuticals:Excipient-grade syrups serving as carriers for pediatric and geriatric drug delivery, requiring compliance with pharmacopeial monographs and dedicated regulatory affairs documentation.
- Confectionery:Hard candy and chocolate flavoring applications with specific thermal stability requirements.
- Bakery:Moisture-retention and flavor-infusion functions in cake and pastry applications.
- Cosmetics:Masking agents and humectants in oral care and skincare formulations.
- Sweeteners:Direct table syrup and pancake topping applications competing with private-label alternatives.
Beverages dominate absolute volume. Pharmaceuticals exhibit the steepest expansion trajectory as drug delivery innovation accelerates.
Packaging Type:
Customer type dictates format selection, with foodservice providers prioritizing dispensing efficiency and personal consumers favoring portability and storage economics.
- Glass Bottles:Premium foodservice standard offering chemical inertness and brand differentiation through tactile and visual quality. Independent cafés across France and Italy specify glass for countertop display, accepting higher logistics costs for perceived value transmission.
- Resin Bottles:Lightweight polymer containers gaining traction in personal consumer channels and e-commerce fulfillment where shipping economics dominate. German and Spanish independent roasters configure custom flavor profiles through digital procurement portals, specifying resin for direct-to-café distribution efficiency.
- Plastic Bottles:Mass-market retail standard for grocery channel distribution.
- Sachets:Single-serve portions for hospitality and airline catering applications.
- Tetra Pak:Aseptic cartons for ambient-stable, high-volume institutional supply.
- Metallic Cans:Industrial-scale packaging for food manufacturing ingredient supply.
Glass bottles retain revenue leadership. Resin bottles are gaining share fastest as logistics optimization intensifies.
Customer Type:
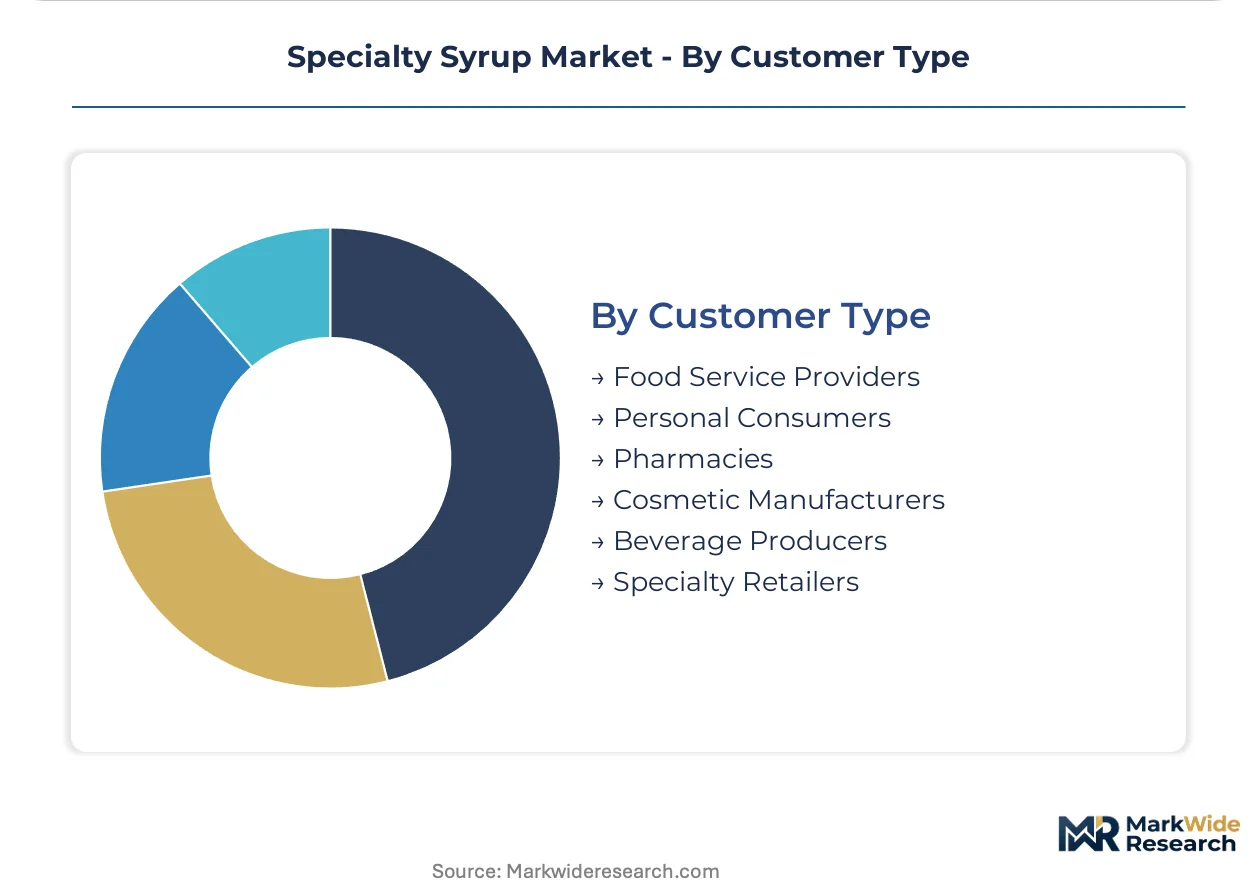
Supply concentration shapes procurement power, with beverage producers and foodservice providers consolidating around technical-service-capable houses while personal consumers fragment across retail channels.
- Beverage Producers:Integrated manufacturing operations requiring batch-scale consistency, regulatory documentation, and co-development partnerships for seasonal innovation. Large United States quick-service chains concentrate purchasing power with houses capable of technical service deployment across multiple beverage categories.
- Food Service Providers:Independent cafés, craft cocktail bars, and boutique roasters bypassing traditional broadline distributors to source directly from flavor houses, demanding smaller minimum order quantities and custom profile configuration.
- Personal Consumers:Retail channel purchasers through specialty grocery and natural product stores.
- Pharmacies:Institutional procurement of excipient-grade syrups for compounding operations.
- Cosmetic Manufacturers:Ingredient sourcing for oral care and skincare formulation.
- Specialty Retailers:Curated assortment operators emphasizing third-party certifications including USDA Organic and Non-GMO Project verification.
Beverage producers command the largest contract values. Food service providers are climbing the fastest as direct sourcing proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Italian and French specialty coffee chains, while United States craft cocktail bars extract value through direct sourcing relationships that bypass distributor markups entirely.
United States
Independent mixology venues in Brooklyn and Austin drive small-batch botanical syrup procurement through flavor house direct relationships. FDA GRAS status requirements for novel flavor additives elevate compliance costs for smaller compounders. Los Angeles and San Francisco wellness beverage startups pilot adaptogen-infused formulations targeting stress-reduction positioning.
France
Parisian premium coffee chains and independent cafés sustain glass bottle preference for countertop display value. EU Green Deal traceability mandates force harvest-date documentation for vanilla from Madagascar and citrus from Calabria. Lyon-based flavor houses expand natural extraction capacity to serve direct-to-café digital procurement platforms.
Italy
Milan and Rome specialty roasters configure custom flavor profiles through bypassed distributor relationships with European manufacturing houses. REACH restrictions on synthetic preservatives accelerate natural preservation R&D investment. Turin industrial clusters concentrate botanical extraction expertise for seasonal signature offerings.
Germany
Berlin and Hamburg independent roasters adopt resin bottle specifications for logistics-optimized direct distribution. ECHA substance restrictions on benzoates force reformulation cycles across mid-size compounders. Bavarian technical service providers bundle equipment calibration with syrup supply for integrated beverage platforms.
United Kingdom
London craft cocktail bars and specialty coffee chains consolidate purchasing around full-flavor-system vendors rather than discrete syrup contracts. FSA alignment with EU Green Deal traceability requirements elevates documentation burdens for botanical raw materials. Manchester and Birmingham distribution hubs optimize resin bottle fulfillment for e-commerce channels.
Specialty Syrup Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying extraction technologies and agricultural inputs. The vendor base stratifies across three tiers: full-flavor-system houses bundling technical service, mid-size compounders with regional formulation expertise, and agricultural originators controlling cane sugar and agave supply streams. Dominant competitive moves include backward integration into botanical sourcing and geographic expansion of manufacturing footprints to reduce logistics costs for direct-to-café channels.
Within the full-flavor-system tier, Monin exemplifies European manufacturing scale deployed across independent café relationships. Kerry Group occupies a position representing R&D intensity in natural extraction technologies. Archer Daniels Midland anchors the agricultural origination archetype through upstream control over cane sugar and agave supply streams feeding downstream refinement operations.
| Leading Market Players |
|---|
| Monin |
| Kerry Group |
| Archer Daniels Midland Company |
| Conagra Brands |
| The Hershey Company |
| The Kraft Heinz Company |
| The J.M. Smucker Company |
| Sensient Technologies |
| DaVinci Gourmet |
| Others |
Pricing and Supply Chain Analysis
Mexican highland agave harvests in Jalisco and Oaxaca transmit volatility directly to premium syrup portfolios, concentrating pricing power with agricultural originators who control upstream supply streams while downstream compounders absorb margin compression from input cost spikes.
Pricing Analysis
Configured-to-order pricing for custom botanical extractions commands 40-60% premiums over standard fruit-based formulations. Three-tier pricing structure across premium, standard, and economy levels separates supercritical CO2-processed botanicals from heat-extracted variants and private-label commodity syrups. Cost compression in mid-tier private-label segments is intensifying because Brazilian and Indian cane sugar harvest fluctuations transmit directly to base syrup cost structures. Beverage producers exhibit the lowest price sensitivity due to integrated platform contracts, while independent cafés and craft cocktail bars negotiate aggressively on minimum order quantities.
Supply Chain Analysis
Extended payment terms from large flavor houses to Madagascar vanilla cooperatives and Calabria citrus growers stabilize raw material access during harvest volatility. Supply concentration rests on Mexico for agave, Brazil and India for cane sugar, and Madagascar for vanilla. Botanical sourcing draws from Sri Lankan cinnamon estates and Calabrian citrus groves under EU Green Deal traceability mandates. Single-source vulnerability concentrates in Mexican highland agave where harvest cycles create multi-year supply gaps. Distribution runs through direct-to-café digital portals for independent roasters and broadline foodservice distributors for quick-service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty syrup market fragmentation creates entry niches as boutique roasters and craft cocktail bars bypass traditional distributors to source directly from flavor houses, splintering procurement concentration.
For Market Incumbents: Pre-empt direct-sourcing proliferation by acquiring digital procurement platform capabilities and embedding technical service teams within top-tier independent café accounts. Consolidate backward integration into botanical sourcing to defend against agave and vanilla supply volatility. Capture regulatory compliance scale advantages as EU Green Deal and REACH documentation burdens force smaller compounders toward exit. For New Entrants and Emerging Players: Adaptogen-infused wellness syrups for United States coastal metros represent the most penetrable entry point, with stress-reduction and cognitive clarity claims commanding formulation premiums. German and Spanish independent roasters seeking resin-bottle logistics optimization offer secondary white-space access. Deploy direct-to-café digital configuration tools as the primary go-to-market angle, bypassing distributor markups entirely. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors natural extraction specialists with supercritical CO2 and cold-press capabilities that preserve volatile terpenes for clean-label positioning. Acquisition targets should demonstrate established regulatory affairs functions capable of navigating FDA GRAS pathways and EU Green Deal traceability mandates. Watch for inflection when REACH substance restrictions expand beyond benzoates and sorbates to additional preservative classes, accelerating R&D consolidation toward scaled houses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Sourcing | Madagascar vanilla and Calabria citrus harvest-date documentation secures EU Green Deal compliance advantage. |
| Supercritical CO2 Capacity Expansion | Copenhagen and Melbourne premium roasters pay 40-60% raw material premiums for cold-processed terpene preservation. |
| Direct-to-Café Digital Platform Launch | German and Spanish independent roasters configure custom profiles without distributor markups through procurement portals. |
| Regulatory Affairs Function Buildout | Dedicated FDA and ECHA compliance teams capture shelf space as smaller compounders exit under traceability mandates. |
| Adaptogen Infusion R&D Program | Los Angeles and San Francisco wellness startups pilot stress-reduction formulations targeting coastal metro demand concentration. |
Research Methodology
Desk research of trade customs data, botanical sourcing registries, and foodservice procurement databases preceded structured interviews with flavor house R&D directors, independent café procurement managers, craft cocktail bar owners, regulatory affairs specialists at compounders, and broadline distributor category buyers. Secondary validation drew from FDA GRAS notifications, ECHA substance restriction filings, EU Green Deal implementation guidance, and agricultural harvest reports from cane sugar and agave producing regions. Bottom-up volume modeling across product type, application, packaging format, and customer type segments was triangulated against top-down value estimates from foodservice and retail channel audits.
Assumptions held fixed include current FDA and EU regulatory frameworks, existing supercritical CO2 technology diffusion rates, and prevailing agricultural harvest volatility patterns across the analysis window. Modeled segmentation dimensions encompass flavor chemistry category, end-use application tier, packaging material type, and distribution channel structure. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated botanical raw material cost indices and clean-label certification penetration rates by geography.
Stress conditions across agave harvest cyclicality, cane sugar price volatility, and REACH substance restriction expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and technology diffusion. Macroeconomic contraction, accelerated synthetic preservative bans, or breakthrough natural preservation technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Middle East and Africa Specialty Food Ingredients Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Personal Care Specialty Ingredients Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Global Sea Buckthorn Oil Market
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
South America Specialty Food Ingredient Market
Specialty Ingredients
Marine Spicules Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Vanilla Extract Alternatives Market