
 South America Specialty Food Ingredient Market | 2026-2036
South America Specialty Food Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
South America Specialty Food Ingredient Market Analytics
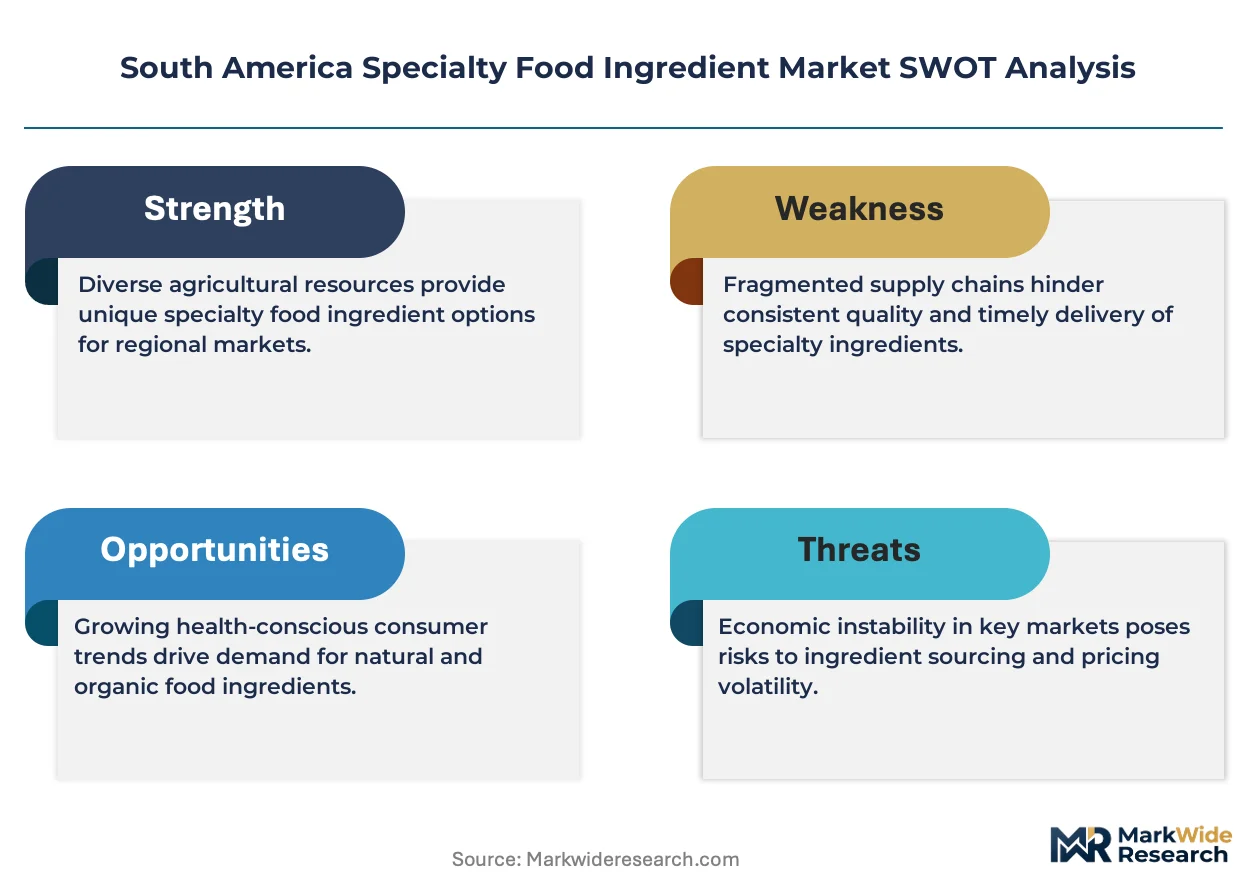
The gap between premium functional ingredients and commodity-grade inputs is expanding across South America. Cargill Incorporated leverages its integrated oilseed processing network to dominate specialty lipid supply. DSM-Firmenich AG differentiates through fermentation-derived nutritional actives. Kerry Group plc anchors its position via taste and nutrition systems tailored for regional palates.
Specialty food ingredients comprise functionally active compounds—emulsifiers with specific hydrophilic-lipophilic balance values, modified starches with controlled amylose ratios, and high-intensity sweeteners exceeding 200x sucrose potency—engineered to deliver texture stability, shelf-life extension, or sensory modulation in processed foods. Emulsifiers command concentrated margin pools due to technical complexity and limited regional manufacturing capacity. Sweeteners gain traction as beverage producers reformulate around sugar reduction targets. Thickeners remain mature across sauces and dairy applications where formulation flexibility requirements are lower.
ANVISA governs additive approval and maximum usage levels, while MERCOSUR technical regulations harmonize standards across member states, creating both compliance obligations and cross-border market access pathways. Brazil's National Health Surveillance Agency periodically updates its positive list of permitted additives, forcing reformulation cycles among suppliers. Stakeholders must monitor regulatory divergence between MERCOSUR harmonized standards and Chile's autonomous food code, which maintains stricter preservative limits.
Market Dynamics
ANVISA's additive approval backlog and MERCOSUR harmonization delays are compressing product launch timelines, forcing suppliers to pre-position regulatory dossiers ahead of reformulation cycles. This structural friction concentrates advantage among incumbents with established compliance infrastructure.
Growth Catalysts
- Clean-label mandates:Brazil's updated positive list for natural-derived emulsifiers accelerates replacement of synthetic alternatives in dairy and bakery formulations. Reformulation pipelines at major processors now prioritize plant-sourced hydrocolloids.
- Sugar reduction targets:Beverage producers across Argentina and Chile face reformulation deadlines tied to front-of-pack labeling laws, pulling high-intensity sweeteners into mainstream applications previously dominated by sucrose.
- Southeastern industrial corridor concentration:São Paulo state's processed food hub generates concentrated demand pull for texture-modifying starches, with local blending facilities reducing lead times versus imported alternatives.
Market Restraints
- Import dependency for fermentation-derived actives:Regional production of vitamins and nutritional lipids remains limited, exposing formulators to currency volatility and extended supply chains from European and Asian fermentation facilities.
- ANVISA registration timelines:Novel additive approvals stretch 18-24 months, freezing innovation pipelines for suppliers without grandfathered ingredient portfolios or established Brazilian legal entities.
- Technical workforce scarcity:Formulation chemists with dual competency in food science and regulatory navigation command premium compensation, constraining mid-tier ingredient distributors from building technical service capabilities.
Strategic Opportunities
- Colombia's underdeveloped specialty ingredient channel:Bogotá and Medellín processed food clusters rely heavily on commodity inputs, creating white space for technical suppliers offering application-specific blends with localized technical support.
- Precision fermentation convergence:Integration of synthetic biology with regional sugarcane feedstock streams could enable domestic production of high-value proteins and lipids currently imported.
- MERCOSUR cross-border harmonization:Streamlined technical regulations reduce redundant testing costs, allowing Argentine suppliers to access Brazilian industrial buyers with simplified registration pathways.
Industry Challenges
- Reformulation cycle compression:ANVISA's periodic positive list updates force simultaneous label and process changes across multiple product lines, straining R&D bandwidth at mid-sized food manufacturers.
- Application-specific certification delays:Kosher and halal certifications for modified starches and emulsifiers require separate facility audits, extending time-to-market for suppliers targeting diverse consumer segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Specialty Food Ingredient Market |
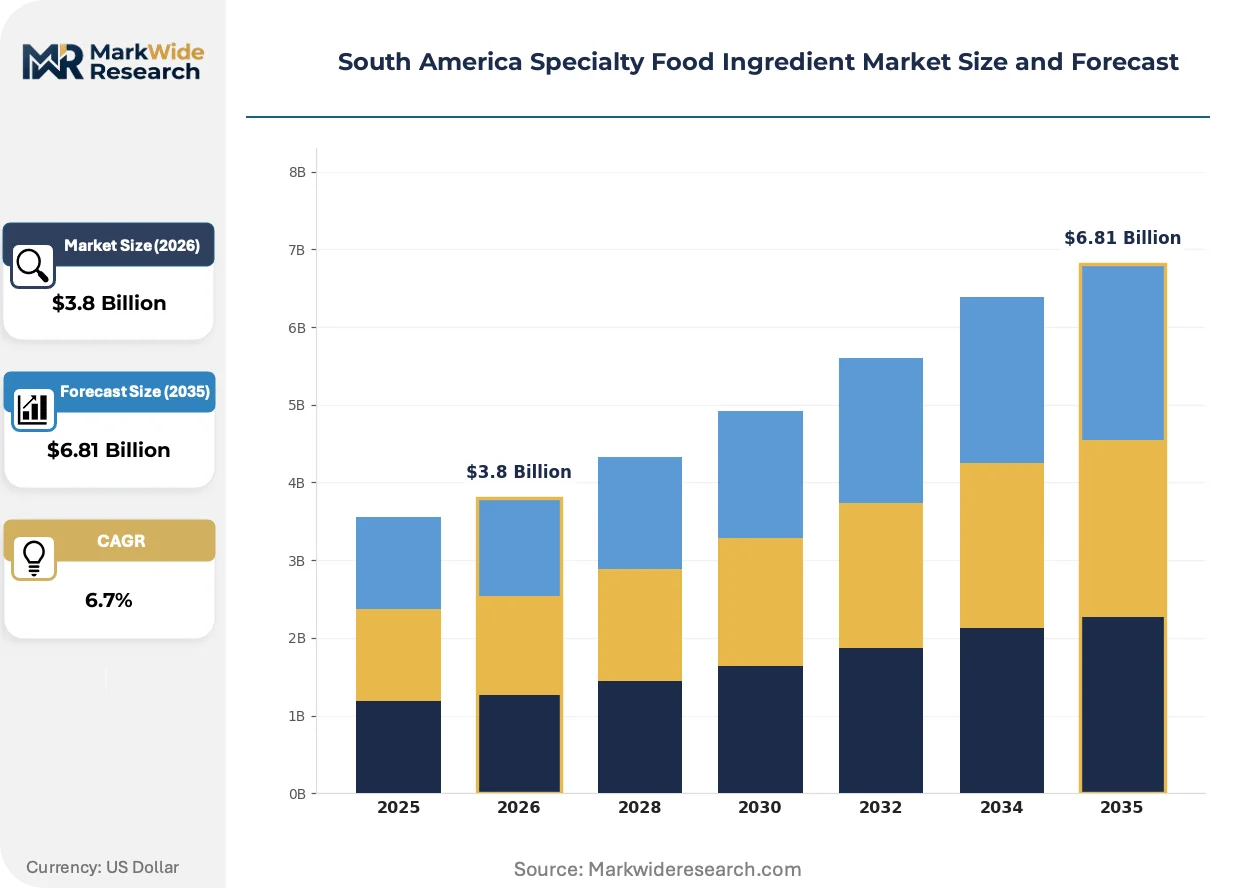
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweeteners, Emulsifiers, Starches, Thickeners End User: Food Manufacturers, Beverage Producers, Bakery Industry, Dairy Sector Application: Confectionery, Sauces, Snacks, Dairy Products Form: Powder, Liquid, Granular, Gel |
| Companies Covered | Cargill Incorporated, Archer-Daniels-Midland Company, Ingredion Incorporated, Kerry Group plc, DSM-Firmenich AG, BASF SE, International Flavors & Fragrances Inc., Tate & Lyle PLC, Givaudan, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Specialty Food Ingredient Market Evolving Landscape
Biotechnology-enabled ingredient production and regulatory data transparency requirements are restructuring competitive advantage around technical capability rather than commodity scale. Suppliers now differentiate through fermentation expertise and dossier completeness.
Enzymatic modification of native starches is overtaking chemical cross-linking as the preferred route to controlled viscosity profiles. Brazilian sauce and dairy processors are adopting these ingredients at accelerating rates, compressing margins for legacy chemically modified alternatives while enabling cleaner ingredient statements that satisfy retail buyer requirements.
MERCOSUR's accelerated timeline for additive maximum-level harmonization is forcing alignment between Brazilian and Argentine usage standards. Industrial formulators operating cross-border production lines must consolidate specifications, driving demand for ingredients with broad regulatory acceptance across member states rather than country-optimized variants.
Consolidation among São Paulo-based beverage and dairy processors has concentrated procurement authority at fewer technical buyers. These purchasers now demand integrated ingredient-plus-application-service packages, displacing transactional spot purchasing and favoring suppliers with localized R&D facilities and on-site formulation support teams.
South America Specialty Food Ingredient Market Segmentation
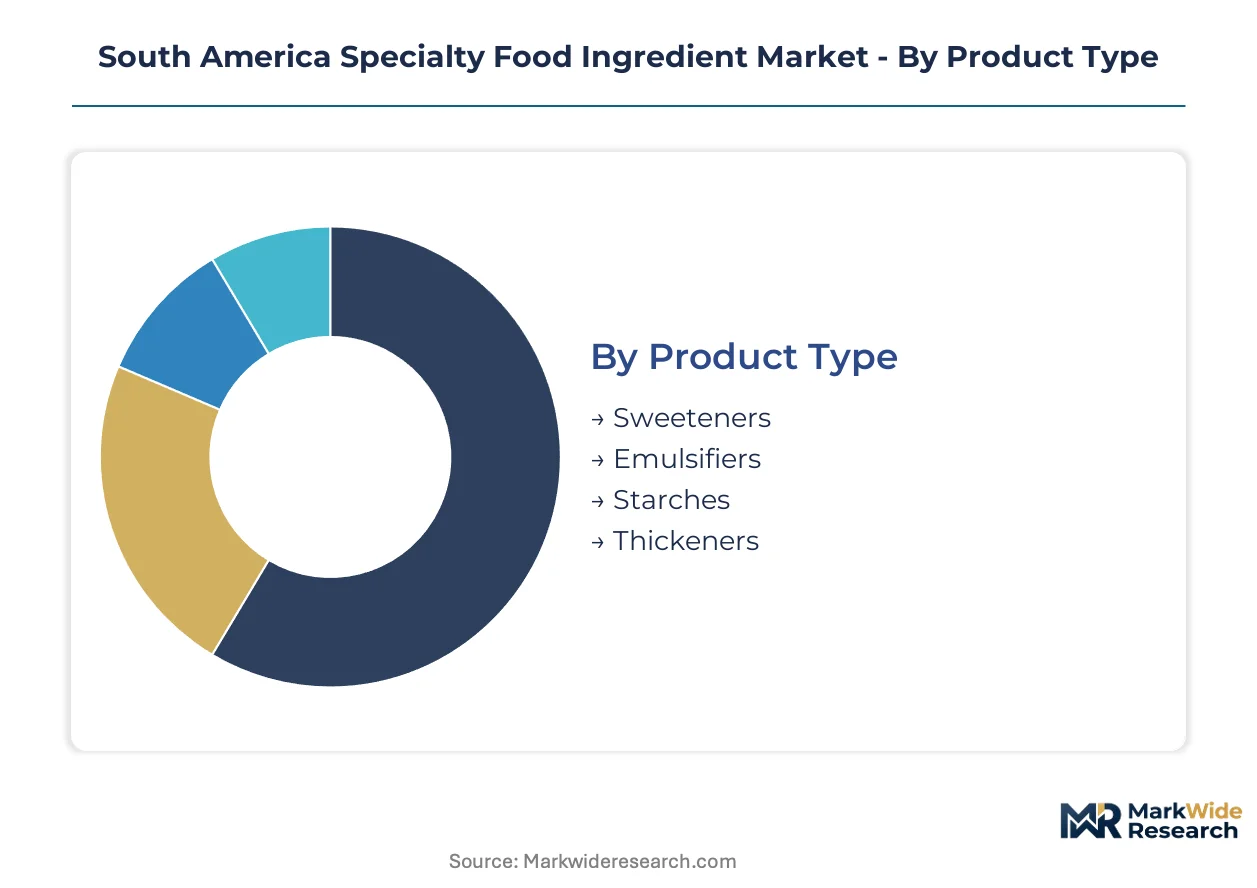
Segmentation in South America's specialty food ingredient market reveals divergent margin profiles and regulatory exposure across product categories. Distinct formulation requirements in Brazil's processed food corridor versus Argentina's beverage sector create heterogeneous demand patterns that suppliers must navigate.
Product Type:
Volume concentrates in mature hydrocolloid categories while premium capture shifts toward technically complex emulsifiers and fermentation-derived sweeteners with higher specification barriers.
- Emulsifiers:Surface-active agents with precisely tuned hydrophilic-lipophilic balance values stabilize oil-water interfaces in dairy and sauce applications. São Paulo's industrial dairy processors drive concentrated demand for lecithin and mono-diglyceride variants as clean-label reformulation accelerates replacement of synthetic alternatives.
- Sweeteners:High-intensity compounds exceeding 200x sucrose potency enable beverage reformulation around ANVISA's evolving sugar reduction frameworks. Argentine and Chilean front-of-pack labeling mandates pull stevia and sucralose into mainstream carbonated and juice applications previously dominated by sucrose.
- Starches:Modified native starches with controlled amylose ratios deliver viscosity stability across thermal processing cycles.
- Thickeners:Hydrocolloid systems including xanthan and guar gums mature across sauce and bakery segments where formulation flexibility demands remain lower.
Today's leader: Emulsifiers. Tomorrow's challenger: Sweeteners.
End User:
Procurement authority concentrates at large-scale manufacturers with integrated R&D capabilities, displacing transactional purchasing patterns among smaller formulators.
- Food Manufacturers:Integrated processed food conglomerates across Brazil's southeastern corridor command ingredient specification authority. These buyers demand bundled technical service packages including on-site formulation support and regulatory dossier management.
- Beverage Producers:Consolidated soft drink and juice processors in Argentina and Chile face compressed reformulation timelines tied to labeling law implementation. Procurement teams prioritize high-intensity sweeteners with pre-established ANVISA registration and MERCOSUR-wide acceptance.
- Bakery Industry:Regional bread and pastry manufacturers rely on emulsifier and enzyme blends for dough conditioning and shelf-life extension.
- Dairy Sector:Yogurt and cheese processors leverage texture-modifying starches and hydrocolloids for mouthfeel control and syneresis prevention.
Food manufacturers anchor current volume. Beverage producers are climbing the fastest as regulatory pressure intensifies.
Application:
Application-driven formulation requirements determine ingredient selection criteria, with thermal stability and pH tolerance filtering viable technical solutions.
- Dairy Products:Fermented milk and fresh cheese applications demand emulsifiers and stabilizers with precise protein interaction characteristics. Brazilian processors prioritize clean-label hydrocolloids that withstand UHT treatment while maintaining viscosity through refrigerated distribution.
- Sauces:Emulsion stability under thermal processing and freeze-thaw cycles drives specification for modified starches and lecithin blends. Argentine industrial sauce producers favor enzymatically modified starches over chemically cross-linked alternatives to satisfy retail buyer ingredient statement requirements.
- Confectionery:Sugar-free and reduced-sugar candy formulations pull high-intensity sweeteners and polyols into chocolate and hard candy segments.
- Snacks:Seasoning adhesion and oil migration control in extruded and fried products utilize specialized emulsifier systems.
Dairy products dominate current formulation complexity. Sauces are gaining share fastest as clean-label starch modification advances.
Form:
Physical presentation determines handling infrastructure requirements and dissolution kinetics, with powder formats offering logistics efficiency against liquid systems' dosing precision.
- Powder:Spray-dried and agglomerated formats dominate high-volume emulsifier and sweetener distribution. Brazilian blending facilities favor powder starches and hydrocolloids for dry-mix incorporation efficiency and extended ambient storage stability.
- Liquid:Pumpable emulsifier concentrates and high-intensity sweetener solutions enable precise inline dosing at beverage production lines. Chilean juice processors increasingly specify liquid formats to eliminate dust exposure and improve batch-to-batch consistency.
- Granular:Free-flowing crystalline sweeteners and specialty salts target tabletop and small-scale manufacturing applications.
- Gel:Pre-hydrated hydrocolloid systems reduce processing time for sauce and dairy manufacturers lacking high-shear mixing equipment.
Powder leads operational scale. Liquid is expanding most quickly as beverage automation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands substantially larger specialty food ingredient volumes than Argentina, though Chilean regulatory stringency creates premium positioning opportunities that Brazilian scale cannot replicate.
Brazil
São Paulo's southeastern industrial corridor concentrates demand for texture-modifying starches and clean-label emulsifiers as dairy and sauce processors accelerate reformulation cycles. ANVISA's evolving positive list for natural-derived additives forces simultaneous label and process changes across multiple product lines. Campinas and Ribeirão Preto host blending facilities that reduce lead times versus imported alternatives.
Argentina
Buenos Aires beverage producers drive high-intensity sweetener uptake as front-of-pack labeling laws compress reformulation timelines for carbonated and juice applications. The national food code maintains alignment with MERCOSUR technical regulations while preserving stricter enforcement protocols than regional minimums. Córdoba's industrial dairy cluster demands hydrocolloid systems with precise protein interaction characteristics for fermented milk applications.
Chile
Santiago-based processors specify enzymatically modified starches over chemically cross-linked alternatives to satisfy retail buyer ingredient statement requirements. The autonomous food code maintains stricter preservative limits than MERCOSUR harmonized standards, creating compliance obligations for cross-border suppliers. Valparaíso's logistics hub facilitates liquid format distribution for automated beverage production lines.
Colombia
Bogotá and Medellín processed food clusters rely heavily on commodity inputs, creating white space for technical suppliers offering application-specific blends. The national health regulator periodically updates additive maximum usage levels, though approval timelines remain shorter than ANVISA's backlog. Cali's emerging dairy sector generates nascent demand for stabilizer systems.
South America Specialty Food Ingredient Market Competitive Landscape
Top-tier vendors anchor integrated supply chains, while mid-tier distributors compete on technical service proximity. The market structure concentrates advantage among incumbents with established ANVISA compliance infrastructure and localized R&D facilities. Three archetypes dominate: integrated agribusiness conglomerates with oilseed processing networks, fermentation specialists leveraging biotechnology platforms, and taste-and-nutrition system providers with regional formulation labs. M&A activity targets technical workforce acquisition, while strategic partnerships with São Paulo-based processors secure procurement authority at consolidated buyers.
Within the integrated agribusiness tier, Cargill Incorporated anchors supply security through captive oilseed processing infrastructure. DSM-Firmenich AG and Kerry Group plc occupy differentiated positions across fermentation-derived actives and regional taste systems respectively. These three exemplify how competitive advantage now derives from regulatory dossier completeness and on-site formulation support capabilities rather than commodity scale alone.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer-Daniels-Midland Company |
| Ingredion Incorporated |
| Kerry Group plc |
| DSM-Firmenich AG |
| BASF SE |
| International Flavors & Fragrances Inc. |
| Tate & Lyle PLC |
| Givaudan |
| Others |
Value Network & Pricing Analysis
Family-owned Brazilian mid-cap ingredient distributors anchor regional supply networks, their conservative capital structures enabling patient pricing discipline even as multinational competitors compress service bundles to defend share.
Pricing Analysis
Bundled ingredient-plus-technical-service packages command premium positioning against unbundled commodity spot transactions. Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived actives from commodity hydrocolloids from imported generic alternatives. Cost compression in standard-grade emulsifiers is intensifying because Campinas blending facilities expanded regional manufacturing capacity. Mid-sized food manufacturers exhibit highest price sensitivity, while consolidated São Paulo dairy processors prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-processor channels handle consolidated buyer demand from Brazil's southeastern industrial corridor, while distributor networks serve fragmented bakery and small-scale dairy operations. Supply concentrates in Brazil, Argentina, and imported European fermentation facilities. Regional production draws from soy lecithin feedstock, corn starch derivatives, and imported vitamin precursors. Single-source vulnerability for high-intensity sweeteners creates exposure to ANVISA registration delays. Distribution runs through São Paulo-based technical distributors with localized blending capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where ANVISA's evolving positive list for natural-derived additives forces recurring reformulation cycles that lock in technical supplier relationships.
For Market Incumbents: Deploy on-site formulation support teams as the anchor retention mechanism. Cargill and DSM-Firmenich should expand Campinas R&D facilities to compress response times for Brazilian dairy processors facing simultaneous label and process changes. Certification investment in kosher and halal standards creates switching costs against emerging Argentine suppliers.
For New Entrants and Emerging Players: Mid-sized Colombian sauce manufacturers represent the most penetrable buyer archetype currently underserved by technical distributors. Bogotá processors rely on commodity hydrocolloids without localized application support, creating white space for suppliers offering enzymatically modified starch blends with on-site viscosity optimization. A technical service-led go-to-market angle bypasses incumbent price advantages.
For Investors and Strategic Acquirers: Valuations sit cheapest among Argentine distributors with MERCOSUR-wide registration portfolios but limited Brazilian physical presence. Long-term viability hinges on regulatory dossier completeness rather than commodity scale. The signal to watch is ANVISA approval timeline compression for novel fermentation-derived actives, which would elevate domestic production economics.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Pre-Positioning | Early dossier submission secures first-mover advantage ahead of positive list updates. |
| Precision Fermentation Facility Investment | Domestic biotechnology capacity reduces import dependency for high-value nutritional lipids. |
| Technical Service Team Localization | On-site formulation support locks in procurement authority at consolidated São Paulo processors. |
| Enzymatic Modification Capability Buildout | Clean-label starch processing satisfies retail buyer ingredient statement requirements in Chile. |
| MERCOSUR Cross-Border Harmonization | Simplified registration pathways enable Argentine suppliers to access Brazilian industrial buyers. |
Research Methodology
Direct dialogue with ANVISA regulatory consultants, formulation chemists at São Paulo dairy processors, procurement directors at Argentine beverage conglomerates, and technical sales managers at regional distributors grounded qualitative insights. Secondary validation drew from ANVISA additive registration databases, MERCOSUR technical regulation harmonization documents, Brazilian customs trade data, and SEC filings from listed ingredient suppliers. Bottom-up demand modeling across end-use segments triangulated against top-down market sizing from production capacity assessments.
Bottom-up volume estimates aggregated individual application consumption patterns across dairy, beverage, sauce, and bakery segments, while top-down analysis calibrated against regional production capacity and import penetration rates. Modeled dimensions include product type, end-user industry, application category, and physical form. CAGRs were derived from regression analysis of historical consumption trends and regulatory-driven reformulation cycle timing. Forecast inputs incorporated ANVISA approval pipeline velocity and front-of-pack labeling law implementation schedules.
Underlying measurement precision varies by segment; emulsifiers and fermentation-derived sweeteners carry tighter precision than mature hydrocolloid categories due to concentrated supplier disclosure. Forecasts reflect assumptions around regulatory timeline stability and currency volatility exposure for import-dependent categories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Specialty Ingredients Market
Specialty Ingredients
Evening Primrose Oil Market
Specialty Ingredients
Global Sea Buckthorn Oil Market
Specialty Ingredients
Mangosteen Extract Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
North America Specialty Food Ingredient Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Aromatherapy Carrier Oil Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Pomegranate Seed Oil Nutricosmetic Ingredients Market
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Food Decorations and Inclusions Market
Specialty Ingredients
Mangosteen Market