
 Middle East and Africa Specialty Food Ingredients Market | 2026-2036
Middle East and Africa Specialty Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Specialty Food Ingredients Market Foresight
Clean-label beverage manufacturers and artisanal bakery chains is bifurcating demand away from legacy industrial food processors across the Middle East and Africa. Cargill Incorporated anchors its regional position through backward integration into specialty starch production for emulsifier applications. Kerry Group differentiates via localized R&D facilities that formulate heat-stable flavoring agents for Gulf climate conditions. Tate & Lyle PLC leverages its global technical service network to sustain reformulation partnerships with Saudi dairy processors seeking reduced-sugar solutions.
Specialty food ingredients comprise functionally active compounds—including emulsifiers, stabilizers, thickeners, and flavoring agents—engineered to deliver specific textural, sensory, or preservation outcomes at dosage rates typically below two percent of finished product weight. These ingredients enable shelf-life extension, mouthfeel modification, and nutritional enhancement in processed foods subject to regional climatic stressors such as heat and humidity. Flavoring agents command the deepest margin pools as Gulf beverage brands prioritize localized taste profiles and sugar-reduction compliance. Stabilizers and thickeners are gaining fastest in dairy applications, where ambient distribution networks require enhanced viscosity control and phase stability. Emulsifiers remain mature in bakery and confectionery, though premium plant-derived lecithin alternatives are displacing conventional soy-based grades in South African clean-label segments.
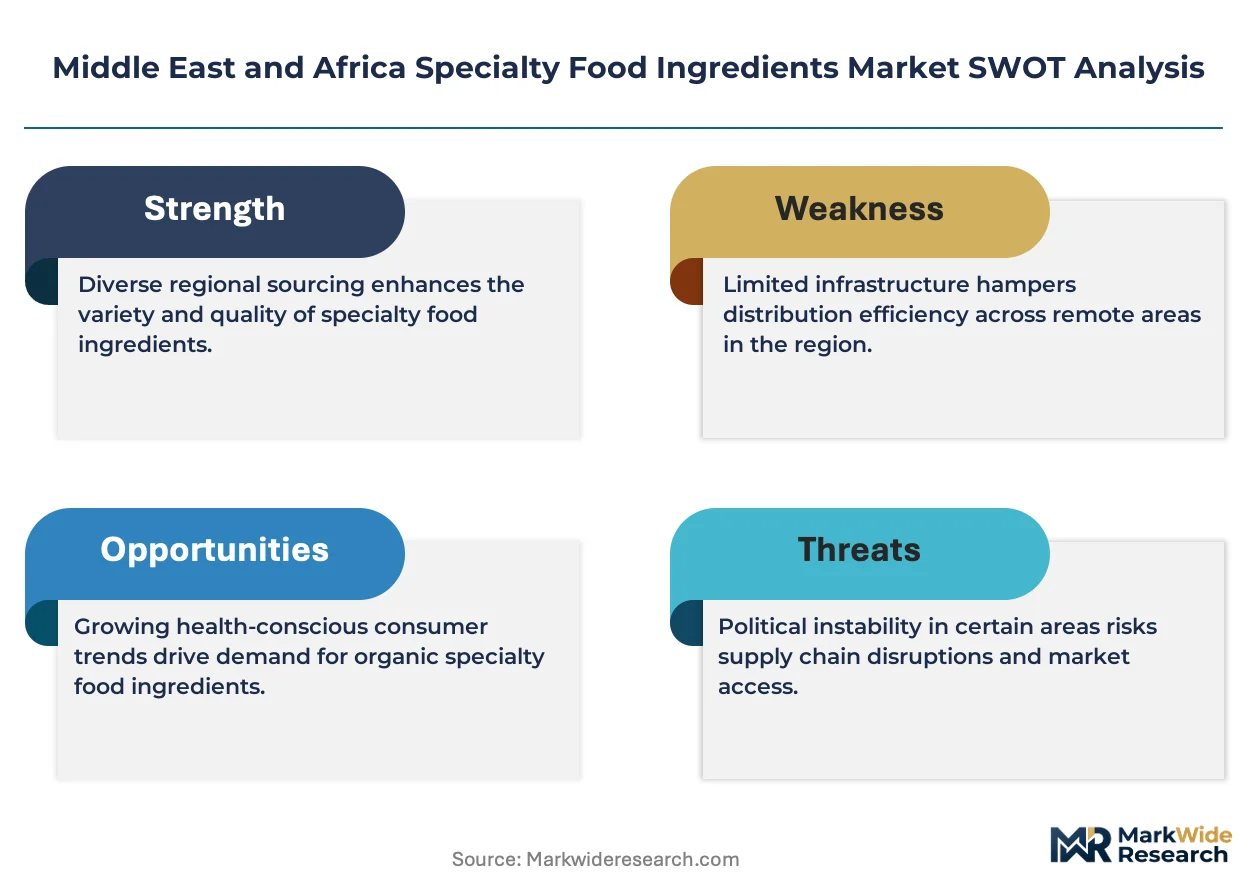
Saudi Food and Drug Authority standards and South Africa's Department of Health fortification mandates are tightening additive disclosure requirements and pushing suppliers toward third-party halal and safety certifications. EMA-aligned technical standards influence import acceptance for European-originated specialty ingredients entering North African markets through EU trade agreements. Gulf regulators are scrutinizing artificial flavoring agent registrations, creating compliance bottlenecks for non-certified suppliers. Stakeholders must monitor divergence between Gulf harmonization initiatives and sub-Saharan national food codes when allocating regulatory affairs resources across the region.
Market Dynamics
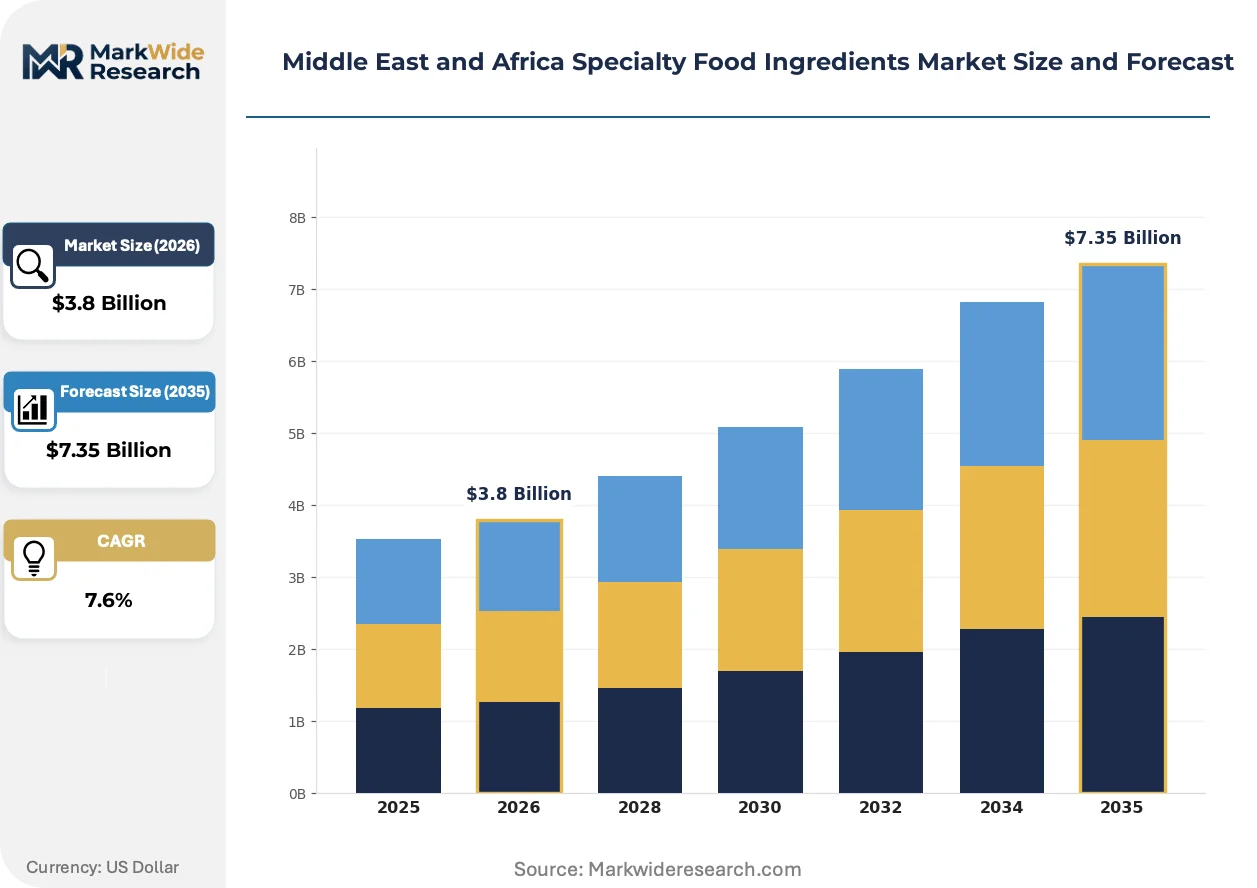
Clean-label reformulation mandates across Gulf Cooperation Council states and South Africa's fortified food regulations are forcing ingredient suppliers to restructure certification portfolios and relocate technical service capabilities closer to dairy and beverage processing clusters.
Growth Catalysts
- South Africa's Food Fortification Regulations:Mandatory micronutrient enrichment in maize meal and wheat flour drives demand for certified premixes and encapsulation technologies from domestic millers.
- Ambient Dairy Distribution Networks:Gulf states' heat-stressed cold-chain gaps require advanced stabilizer systems for UHT milk and laban with extended shelf stability.
- Halal Certification Harmonization:Saudi Food and Drug Authority alignment with UAE's Emirates Authority for Standardization and Metrology streamlines cross-border ingredient approvals for multinational suppliers.
Market Restraints
- Input Cost Volatility in Natural Extracts:Weather-driven supply fluctuations for vanilla, citrus oils, and gum acacia sourced from East African cooperatives compress margin predictability for flavor houses.
- European Supply Concentration:Over-reliance on EMA-aligned technical documentation for North African import acceptance creates bottlenecks when EU regulatory timelines lag.
- Technical Limitations in Heat-Stable Proteins:Plant-derived emulsifiers underperform in high-temperature Gulf bakery applications, slowing soy lecithin displacement.
Strategic Opportunities
- Egypt's Underpenetrated Confectionery Sector:Local artisanal chocolate producers lack access to premium couverture stabilizers, creating white space for technical ingredient partnerships.
- Regulatory Tailwind from UAE's National Food Security Strategy:Domestic production incentives for processed dairy attract regional R&D investment in localized emulsifier manufacturing.
- Direct-to-Processor Digital Platforms:B2B ingredient marketplaces bypass traditional distributor markups for mid-sized Saudi juice manufacturers seeking clean-label flavor systems.
Industry Challenges
- Halal Certification Timeline Compression:Gulf regulators' accelerated review cycles for novel flavoring agents strain supplier documentation teams and delay product launches.
- Legacy ERP Integration Friction:South African millers' outdated traceability systems conflict with EU-export compliance requirements for fortified ingredient lot tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Specialty Food Ingredients Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
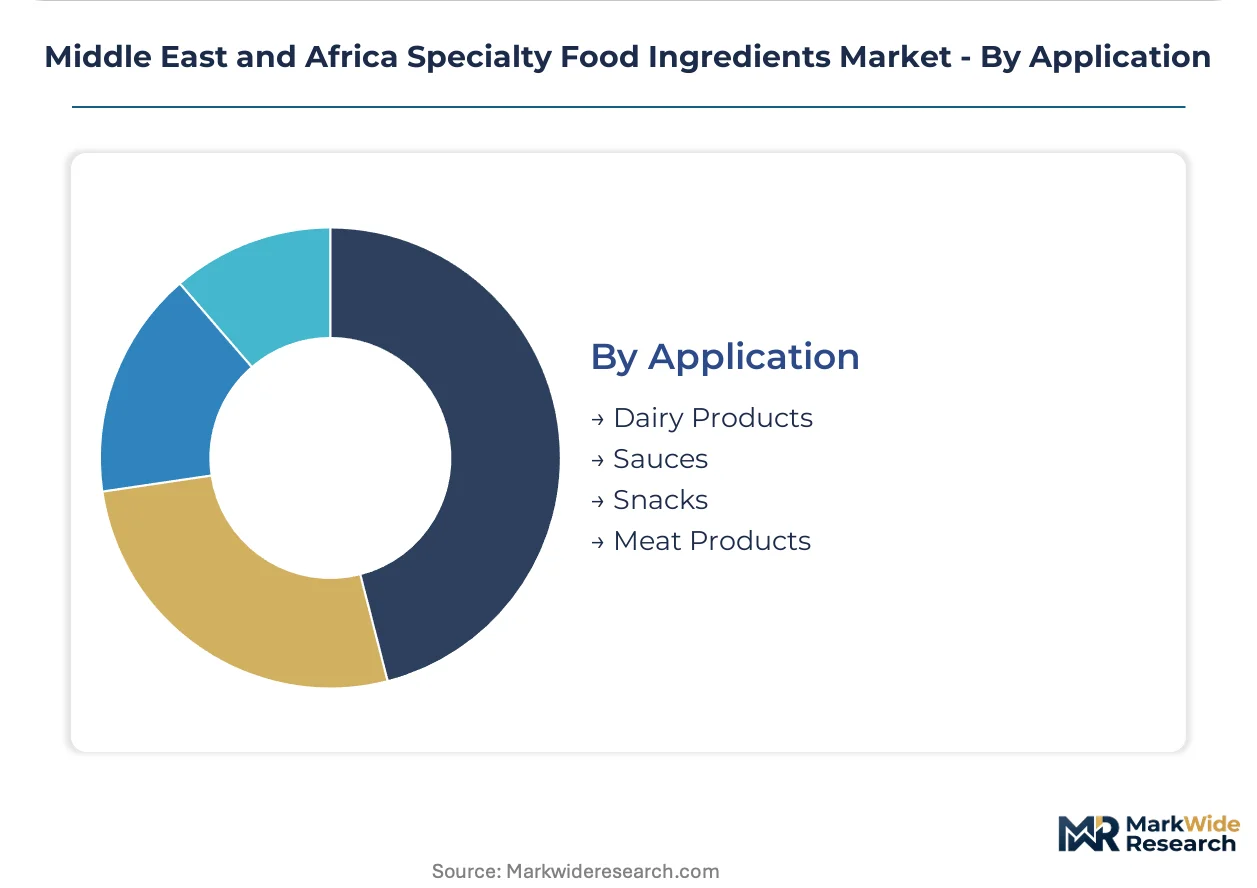
| Segmentation | Product Type: Emulsifiers, Stabilizers, Thickeners, Flavoring Agents End Use Industry: Food Processing, Beverage, Bakery, Confectionery Form: Powder, Liquid, Granules, Paste Application: Dairy Products, Sauces, Snacks, Meat Products |
| Companies Covered | Tate & Lyle PLC, Ingredion Incorporated, Cargill Incorporated, Roquette Frères, Givaudan Flavors, Archer Daniels Midland Company, Kerry Group, Kemin Industries, Inc, DSM-Firmenich, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Specialty Food Ingredients Market Shifts & Advancements
Ingredient functionality is being redefined by climate-adaptive formulation science, regulatory disclosure tightening, and procurement decentralization toward regional processing clusters.
Fermentation-derived natural flavoring agents is displacing solvent-extracted botanicals in Gulf beverage applications. Saudi juice manufacturers and UAE functional drink startups adopt these bioprocessed alternatives for cleaner label declarations. This shift compresses demand for conventional extraction capacity while rewarding suppliers with captive fermentation assets.
Saudi Food and Drug Authority's expanded additive disclosure requirements now mandate quantitative labeling for artificial flavoring agents in children's food categories. Industrial consequence includes reformulation sprint cycles for regional confectionery producers. Dairy and bakery segments are responding by accelerating natural flavor migration timelines and pre-qualifying alternative suppliers.
Ingredient procurement is fragmenting from centralized distributor contracts toward direct technical partnerships with regional dairy cooperatives. Saudi Arabia's Almarai and UAE-based dairy collectives now negotiate bespoke stabilizer formulations with technical service commitments. This behavioral shift is most visible in the Gulf where ambient distribution complexity demands localized viscosity optimization support.
Middle East and Africa Specialty Food Ingredients Market Segmentation
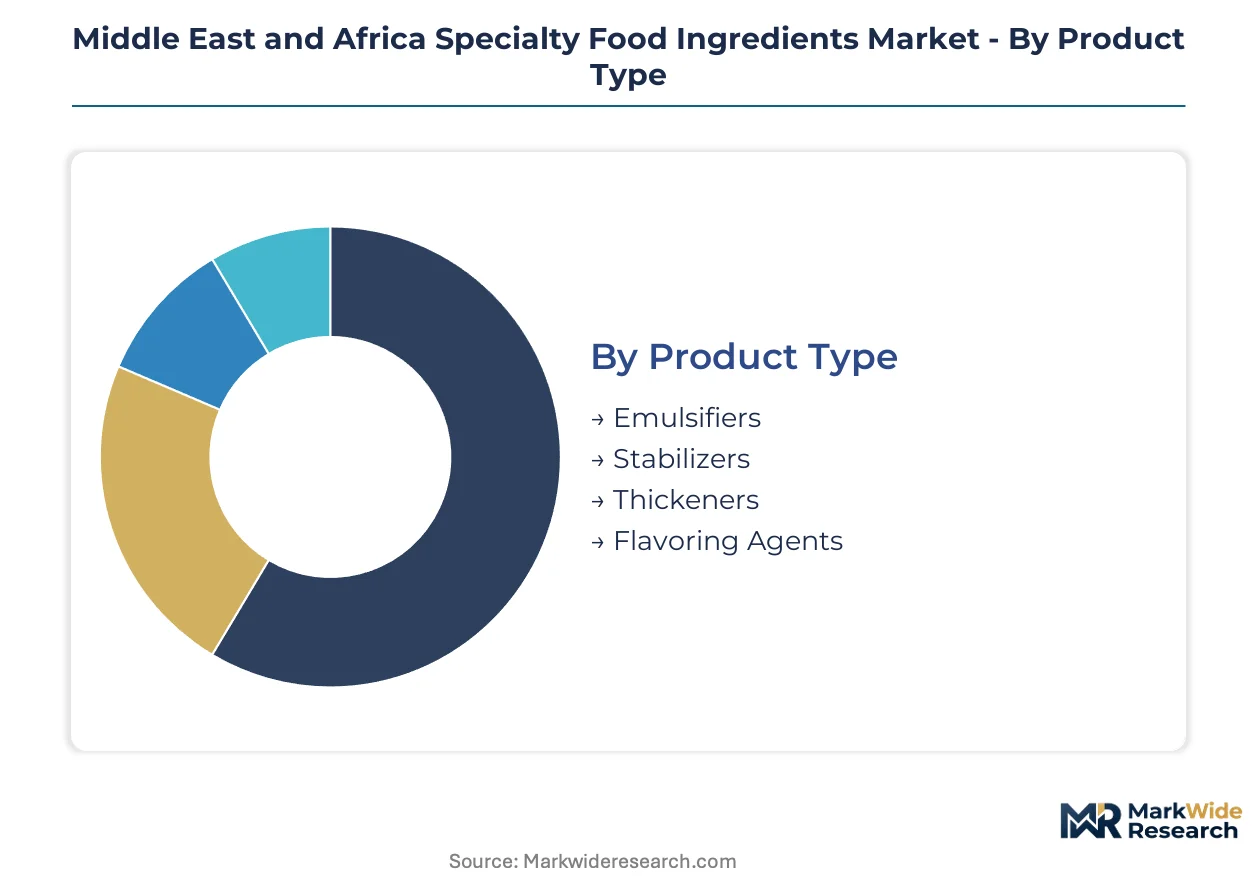
Specialty food ingredient suppliers in the Middle East and Africa must align product portfolios with divergent regulatory regimes across Gulf Cooperation Council states and sub-Saharan markets. Segmentation reveals where halal certification complexity, ambient distribution requirements, and fortification mandates concentrate commercial opportunity.
Product Type:
SFDA disclosure standards and UAE Emirates Authority for Standardization and Metrology protocols differentiate compliance burdens across ingredient classes, reshaping supplier certification investments.
- Flavoring Agents:Natural and nature-identified compounds delivering sensory profiles at sub-one-percent dosage rates. Gulf beverage manufacturers in Saudi Arabia and UAE prioritize these for sugar-reduction compliance and clean-label positioning in functional drinks. Heat stability requirements for ambient distribution networks favor suppliers with localized formulation support.
- Stabilizers:Hydrocolloid and protein-based systems controlling viscosity and phase separation in processed foods. Demand concentrates in Saudi and UAE dairy applications where UHT milk and laban require extended shelf stability under heat-stressed cold-chain gaps. Almarai and regional cooperatives negotiate bespoke formulations directly with technical service teams.
- Emulsifiers:Surface-active agents enabling fat-water dispersion in processed matrices.
- Thickeners:Rheology modifiers providing mouthfeel and suspension in sauces and dressings.
Established volume favors stabilizers; emerging adoption favors flavoring agents.
End Use Industry:
Customer procurement patterns split between multinational processors with centralized technical partnerships and mid-sized regional players accessing ingredients through digital B2B platforms.
- Beverage:Juice, functional drink, and dairy beverage processors driving natural flavor migration and sugar-reduction reformulation. Saudi juice manufacturers and UAE startups adopt fermentation-derived alternatives to solvent-extracted botanicals for cleaner label declarations.
- Food Processing:Ambient-stable dairy and sauce manufacturers requiring heat-adaptive stabilizer systems. South African millers source certified premixes for maize meal and wheat flour fortification under Department of Health mandates.
- Bakery:Bread and pastry producers utilizing emulsifiers for dough conditioning and shelf-life extension.
- Confectionery:Chocolate and candy manufacturers seeking premium couverture stabilizers for localized taste profiles.
Procurement scale favors food processing; reformulation velocity favors beverage.
Form:
Handling characteristics and dissolution kinetics determine suitability for automated processing lines versus artisanal production environments across regional manufacturing clusters.
- Powder:Free-flowing particulate formats with extended shelf stability and precise dosing control. Dominates South African milling and fortification applications where lot tracking compliance meets EU-export requirements.
- Liquid:Pre-dispersed solutions enabling rapid incorporation without hydration delays. Preferred in Gulf beverage manufacturing for streamlined batch processing and reduced dust exposure in high-temperature environments.
- Granules:Intermediate particle size for controlled dissolution in meat processing applications.
- Paste:High-concentration formats for confectionery and sauce applications requiring minimal water activity.
Processing efficiency favors liquid; storage stability favors powder.
Application:
Climate-adaptive formulation requirements and distribution infrastructure gaps concentrate demand for specific functional ingredient combinations in heat-stressed markets.
- Dairy Products:UHT milk, yogurt, and laban requiring viscosity control and protein stabilization under ambient distribution. Saudi Arabia's Almarai and UAE cooperatives drive direct technical partnerships for localized optimization.
- Sauces:Emulsified dressings and condiments demanding freeze-thaw stability and pour viscosity. South African processors reformulate for clean-label positioning while maintaining texture under variable retail refrigeration.
- Snacks:Coated and seasoned products utilizing flavor encapsulation for heat resistance.
- Meat Products:Processed and cured applications requiring moisture retention and texture modification.
Technical complexity favors dairy; reformulation activity favors sauces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jeddah Islamic Port's expanded cold-chain infrastructure underwrites Saudi Arabia's position as the Gulf's primary entry point for temperature-sensitive specialty ingredients, connecting Red Sea shipping lanes to Riyadh's dairy processing corridor.
Saudi Arabia
Almarai's centralized procurement drives demand for heat-stable stabilizers in UHT milk and laban applications. SFDA's expanded additive disclosure requirements for children's food categories accelerate reformulation cycles among Riyadh-based confectionery producers. The Eastern Province's dairy cooperatives negotiate direct technical partnerships for localized viscosity optimization.
United Arab Emirates
Dubai's functional beverage startups adopt fermentation-derived flavoring agents for clean-label positioning in ambient distribution networks. MOHAP alignment with Emirates Authority for Standardization and Metrology streamlines cross-border ingredient approvals for multinational suppliers. Abu Dhabi's dairy collectives source bespoke emulsifier formulations with embedded technical service commitments.
South Africa
Domestic millers source certified premixes for maize meal and wheat flour fortification under Department of Health mandates. EU-export compliance requirements for lot tracking strain legacy ERP systems at Johannesburg processing facilities. The Western Cape's artisanal bakery chains bifurcate procurement toward clean-label distributors away from legacy industrial suppliers.
Egypt
Cairo's artisanal chocolate producers lack access to premium couverture stabilizers, creating partnership opportunities for technical ingredient suppliers. The country's national food regulator maintains import documentation standards influenced by EMA-aligned technical specifications. Alexandria's port infrastructure handles European-originated specialty ingredients entering North African markets.
Nigeria
Lagos-based beverage manufacturers expand use of natural flavoring agents for sugar-reduction compliance in regional juice processing. The country's national standards body develops food additive disclosure frameworks modeled on Gulf harmonization initiatives. Kano's milling clusters drive demand for encapsulated micronutrient premixes in fortified flour applications.
Middle East and Africa Specialty Food Ingredients Market Competitive Landscape
Concentration sits with diversified multinationals possessing captive fermentation assets and localized technical service networks. The supplier base organizes around three archetypes: global ingredient conglomerates with backward integration into specialty starch production, regional formulation specialists operating captive R&D facilities, and digital-native distributors bypassing traditional procurement channels. Dominant competitive moves include strategic partnerships with dairy cooperatives for bespoke stabilizer development and geographic expansion of halal-certified production capacity.
Among the integrated multinationals, Cargill Incorporated exemplifies the conglomerate archetype through its regional specialty starch operations. Kerry Group occupies a position representing the localized R&D model with climate-adaptive formulation capabilities. Tate & Lyle PLC anchors the technical service tier, sustaining reformulation partnerships with Saudi dairy processors. These three patterns illustrate how competitive positioning depends on proximity to Gulf processing clusters and certification portfolio breadth.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Cargill Incorporated |
| Roquette Frères |
| Givaudan Flavors |
| Archer Daniels Midland Company |
| Kerry Group |
| Kemin Industries, Inc |
| DSM-Firmenich |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for gum acacia and vanilla extracts concentrate working capital pressure on flavor houses while amplifying price volatility transmission to Gulf beverage processors. This lead-time exposure shapes supplier-buyer power dynamics across the Middle East and Africa specialty food ingredients landscape.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts for specialty food ingredients. Price differentiation rests on halal certification grade and volume scale, with multinational dairy processors commanding 15-20 point spreads over mid-sized Saudi juice manufacturers. Pricing pressure stems from weather-driven supply fluctuations for East African natural extracts. Mid-sized regional processors exhibit highest price sensitivity, while Almarai and UAE dairy collectives absorb premium tiers for embedded technical service.
Supply Chain Analysis
Strategic stockpile preferences dominate inventory strategy for heat-sensitive stabilizers, contrasting with just-in-time approaches for commodity emulsifiers. Supply concentrates in France and Germany for EMA-aligned technical documentation, India for fermentation-derived flavoring agents, and East African cooperatives for gum acacia and vanilla. Raw material dependencies include citrus oils, specialty starches, and plant-derived lecithin alternatives. Single-source vulnerability runs through EU regulatory approval bottlenecks for North African import acceptance. Distribution runs through Jeddah Islamic Port's cold-chain infrastructure for temperature-sensitive ingredients, with secondary channels via Dubai's re-export hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated dairy cooperatives in Saudi Arabia and the UAE, fragmenting procurement from legacy distributor relationships toward direct technical partnerships. This consolidation compresses margin capture for traditional ingredient suppliers.
For Market Incumbents: Secure captive fermentation capacity for natural flavoring agents to defend against bioprocessed alternatives displacing solvent-extracted botanicals. Anchor backward integration into specialty starch production for emulsifier applications, mirroring Cargill's regional model. Expand halal-certified production capacity in Gulf-adjacent geographies to compress certification timeline exposure. For New Entrants and Emerging Players: Technical service gaps in ambient dairy viscosity optimization present entry points for regional formulation specialists. Egypt's artisanal chocolate producers lack access to premium couverture stabilizers, offering the most penetrable white-space target. Deploy direct-to-processor digital platforms bypassing traditional distributor markups for mid-sized Saudi juice manufacturers seeking clean-label flavor systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with under-monetized food-grade specialty ingredient divisions. Long-term viability favors suppliers with localized R&D infrastructure and climate-adaptive formulation capabilities. Watch for inflection when SFDA accelerates novel flavoring agent review cycles, compressing launch timelines for non-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Starch | Cargill's regional model secures emulsifier supply chain control for Gulf dairy processors. |
| Localized R&D Facility Expansion | Kerry Group's climate-adaptive formulation capabilities capture heat-stable flavoring agent demand. |
| Halal Certification Portfolio Restructuring | Suppliers aligning with SFDA-ESMA harmonization streamline cross-border ingredient approvals. |
| Direct-to-Processor Digital Platform Launch | B2B marketplaces bypass distributor markups for Saudi juice manufacturers seeking clean-label systems. |
| Technical Partnership with Dairy Cooperatives | Bespoke stabilizer development with Almarai and UAE collectives locks in ambient distribution demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SFDA regulatory filings, and EU import documentation standards for North African markets. Interviews with procurement directors at Saudi dairy processors, technical R&D leads at UAE beverage startups, and category managers at South African milling operations inform demand-side validation. Secondary sources include Department of Health fortification mandate records, Emirates Authority for Standardization and Metrology protocols, and trade flow databases. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled span product type, end-use industry, form, and application, with cross-cutting analysis of regulatory regime clusters across Gulf Cooperation Council states and sub-Saharan markets. CAGRs derive from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Industry-specific forecast inputs include ambient distribution network expansion rates and halal certification timeline compression effects.
Underlying assumptions cover sustained Gulf dairy consumption growth and South African fortification mandate enforcement, with deviation risk concentrated in EU regulatory approval delays for North African import acceptance and weather-driven natural extract supply disruptions. Revision becomes warranted when SFDA-ESMA harmonization timelines diverge or East African cooperative output volatility crosses threshold levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
North America Specialty Food Ingredient Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Global Sea Buckthorn Oil Market
Specialty Ingredients
Europe Specialty Food Ingredients Market
Specialty Ingredients
Flavanols Market
Specialty Ingredients
Marine Spicules Market
Specialty Ingredients
Food Decorations and Inclusions Market
Specialty Ingredients
Global Fruit and Vegetable Powder Market
Specialty Ingredients
Gentian Market
Specialty Ingredients
Aromatherapy Oils Market
Specialty Ingredients
Madecassoside Market
Specialty Ingredients
Global Pet Food Flavors Market
Specialty Ingredients
Benzoe Siam Market
Specialty Ingredients
Aromatherapy Carrier Oil Market