
 Global Sea Buckthorn Oil Market | 2026-2036
Global Sea Buckthorn Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sea Buckthorn Oil Market Outlook
Multi-source procurement of sea buckthorn berries is hardening across European and North American processors. SIBU leverages its Rocky Mountain sourcing network to sustain year-round cold-pressed oil output. WELEDA anchors German demand through biodynamic certification requirements that exclude conventional supply chains.
Sea buckthorn oil is a fixed oil extracted from Hippophae rhamnoides seeds and pulp, typically containing 30-35% palmitoleic acid and notable concentrations of tocopherols and carotenoids, produced through cold pressing, solvent extraction, or supercritical CO2 methods for use in topical formulations and oral supplements. Cold pressed variants dominate margin pools in cosmetics due to consumer preference for unaltered phytochemical profiles, while refined grades occupy cost-sensitive pharmaceutical encapsulation contracts. Supercritical CO2 extracts represent the fastest-growing structural category as clean-label positioning in nutraceuticals intensifies.
EMA guidelines on herbal medicinal products and EU REACH registration requirements for novel botanical substances shape product standards and market access across European jurisdictions. China's NMPA and GB standards for edible oils govern import thresholds and domestic extraction facility licensing. Stakeholders must monitor divergence between EU cosmetic ingredient disclosure rules and China's evolving national food safety standards for oils used in dual-purpose skincare and supplement applications.
Market Dynamics
Supercritical CO2 extraction technology is concentrating production capacity among Chinese processors while REACH compliance in the European Union hardens purity thresholds for botanical extracts entering personal care supply chains.
Growth Catalysts
- REACH purity mandates:ECHA thresholds for novel botanical substances in cosmetics are forcing formulators toward certified cold-pressed grades, tightening supplier qualification criteria across German and French procurement offices.
- Nutraceutical clean-label positioning:Supercritical CO2 extraction methods are displacing solvent-based processes as NMPA-licensed Chinese facilities scale capacity to serve both domestic supplement brands and export contracts.
- Biodynamic certification requirements:WELEDA's procurement standards in Germany exclude conventional supply chains, creating dedicated demand corridors for Demeter-certified berry sourcing networks.
Market Restraints
- Raw material concentration risk:Wild harvest dependency in Mongolia and Siberia creates volume volatility as climate stress affects Hippophae rhamnoides berry yields in concentrated high-altitude zones.
- Input cost volatility:Organic certification premiums for berry procurement are compressing margins at mid-scale European processors unable to secure long-term alpine sourcing contracts.
- Substitution pressure:Rosehip oil and marula oil are capturing share in mass-market skincare formulations where palmitoleic acid content is secondary to price positioning.
Strategic Opportunities
- Underpenetrated Indian nutraceutical channel:FSSAI registration pathways for imported botanical oils remain underutilized by Chinese exporters, creating first-mover positioning for CO2-extracted grades in Ayurveda-aligned supplement lines.
- Technology convergence:Encapsulation technologies combining sea buckthorn oil with liposomal delivery systems are opening pharmaceutical-grade applications previously blocked by oxidation stability constraints.
- EU Green Deal bioeconomy incentives:CSRD-aligned sustainability reporting is driving cosmetic houses toward traceable, low-carbon extraction methods that supercritical CO2 facilities can document through certified carbon accounting.
Industry Challenges
- Phytochemical standardization gaps:ISO methods for tocopherol and carotenoid quantification remain inconsistently applied across laboratories, complicating contract specifications between processors and formulators.
- Capex intensity for extraction scale-up:Supercritical CO2 equipment requires seven-figure investments that fragment capacity ownership between state-subsidized Chinese facilities and undercapitalized European craft producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sea Buckthorn Oil Market |
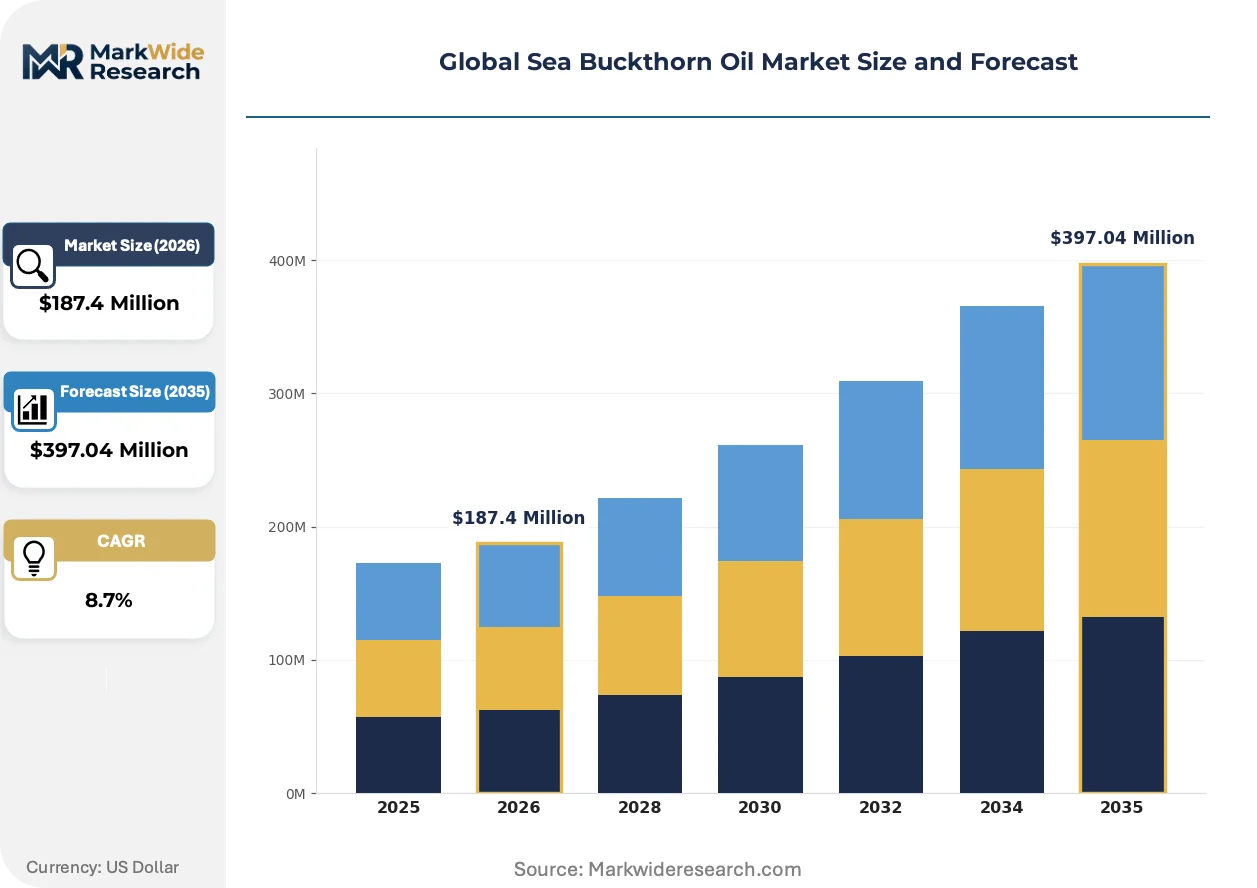
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Pressed, Refined, Unrefined, Extract End User: Cosmetics, Pharmaceuticals, Food & Beverage, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales Application: Skincare, Dietary Supplements, Hair Care, Beverage |
| Companies Covered | Natures Aid, W.S. Badger Company, SeabuckWonders, Lehberry, Erbology, SIBU, WELEDA, Connoils, Biosash, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sea Buckthorn Oil Market Strategic Shifts
Clean-label extraction methods are displacing conventional solvent processes across premium cosmetic and nutraceutical supply chains, while regulatory disclosure requirements in the European Union and China reshape competitive qualification criteria.
Supercritical CO2 extraction systems are expanding into high-margin cosmetic formulations as the technology preserves heat-sensitive carotenoids and tocopherols that cold pressing degrades. German and French formulators are adopting CO2 grades for anti-aging serums at triple the rate of solvent-refined alternatives. The technology is expanding into pharmaceutical encapsulation contracts previously reserved for synthetic lipid carriers, compressing the addressable market for refined grades.
EU REACH registration requirements for novel botanical substances are tightening substance identity documentation and impurity profiling for personal care applications. ECHA compliance costs are filtering out small-scale importers lacking in-house regulatory affairs capacity. German cosmetic houses are responding by consolidating supplier panels around three to five REACH-registered processors with dedicated dossier maintenance teams.
Direct procurement relationships between cosmetic formulators and extraction facilities are displacing traditional botanical oil traders across European supply chains. Large German skincare houses are negotiating multi-year offtake agreements with Chinese CO2 processors, bypassing Rotterdam and Hamburg commodity brokers. This pattern is most visible in France, where ANSM cosmetic notification requirements favor documented supply chain traceability that trader opacity cannot satisfy.
Global Sea Buckthorn Oil Market Segmentation
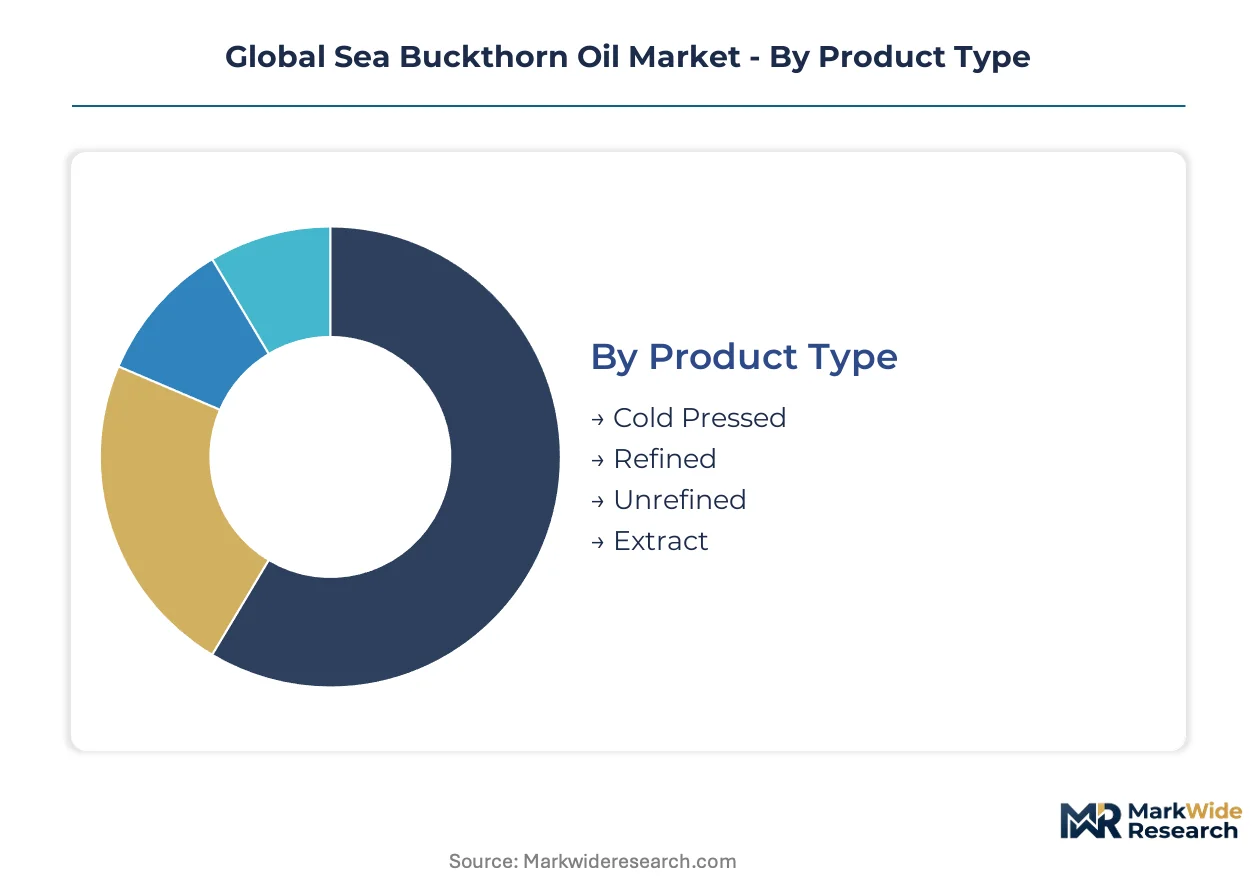
Sea buckthorn oil's phytochemical variability across extraction methods creates distinct value tiers that reshape procurement patterns. Formulators segment supply by thermal history and solvent exposure to match regulatory thresholds in target markets.
Product Type:
Supply concentration tilts toward mechanically processed grades as European cosmetic houses enforce cold-chain documentation.
- Cold Pressed:Mechanical extraction at temperatures below 40°C preserves heat-labile carotenoids and tocopherols in ratios exceeding 30% palmitoleic acid. German and French premium skincare lines specify this grade exclusively under REACH substance identity requirements.
- Refined:Degummed and deodorized through steam stripping or bleaching clays, yielding neutral odor profiles suitable for pharmaceutical soft-gel encapsulation. Cost-sensitive nutraceutical contracts in India and Southeast Asia default to this tier despite tocopherol loss.
- Unrefined:Filtered only for particulates, retaining full phenolic complexity and characteristic amber coloration. Artisan cosmetic producers in Alpine Europe and Pacific Northwest North America favor this grade for clean-label positioning.
- Extract:Supercritical CO2 or solvent-derived concentrates with standardized phytosterol content. Chinese processors dominate capacity expansion here, serving both domestic NMPA-licensed supplement brands and export nutraceutical contracts.
Today's leader: Cold Pressed. Tomorrow's challenger: Extract.
End User:
Margin capture diverges sharply between topical formulators seeking unaltered phytochemical profiles and oral supplement manufacturers prioritizing oxidation stability.
- Cosmetics:Facial serums and barrier-repair creams leverage palmitoleic acid's skin-identical lipid structure. ECHA purity mandates are disqualifying solvent-extracted grades from German and French procurement panels.
- Pharmaceuticals:Wound-healing ointments and mucosal repair formulations exploit sea buckthorn oil's regenerative properties. Clinical trial documentation requirements favor CO2-extracted grades with batch-consistent carotenoid specifications.
- Food & Beverage:Functional beverage fortification and culinary oil blends in Nordic and Central Asian markets. Flavor volatility limits penetration outside traditional consumption zones.
- Nutraceuticals:Omega-7 capsules and cardiovascular health supplements driving volume growth. China's domestic brands are scaling CO2 extraction capacity to displace imported refined grades.
Cosmetics commands premium pricing. Nutraceuticals scales fastest.
Distribution Channel:
Channel selection reflects buyer sophistication and batch traceability requirements rather than simple price sensitivity.
- Online Retail:Direct-to-consumer platforms enable small-batch cold-pressed producers to bypass conventional wholesale markups. EU cosmetic ingredient disclosure rules favor documented supply chains that aggregator platforms struggle to verify.
- Supermarkets:Mass-market skincare and culinary oil placement requires shelf-stable packaging and standardized labeling. Refined grades dominate this channel due to extended best-before dating.
- Health Stores:Specialty retailers in Germany, Austria, and Switzerland stock biodynamic-certified oils meeting Demeter or BioSuisse standards. WELEDA's retail presence anchors this channel's premium positioning.
- Direct Sales:Multi-year offtake agreements between Chinese CO2 processors and European cosmetic houses are displacing Rotterdam commodity brokers. ANSM traceability requirements favor this channel for French formulators.
Health Stores sustain premium tiers. Direct Sales captures B2B volume.
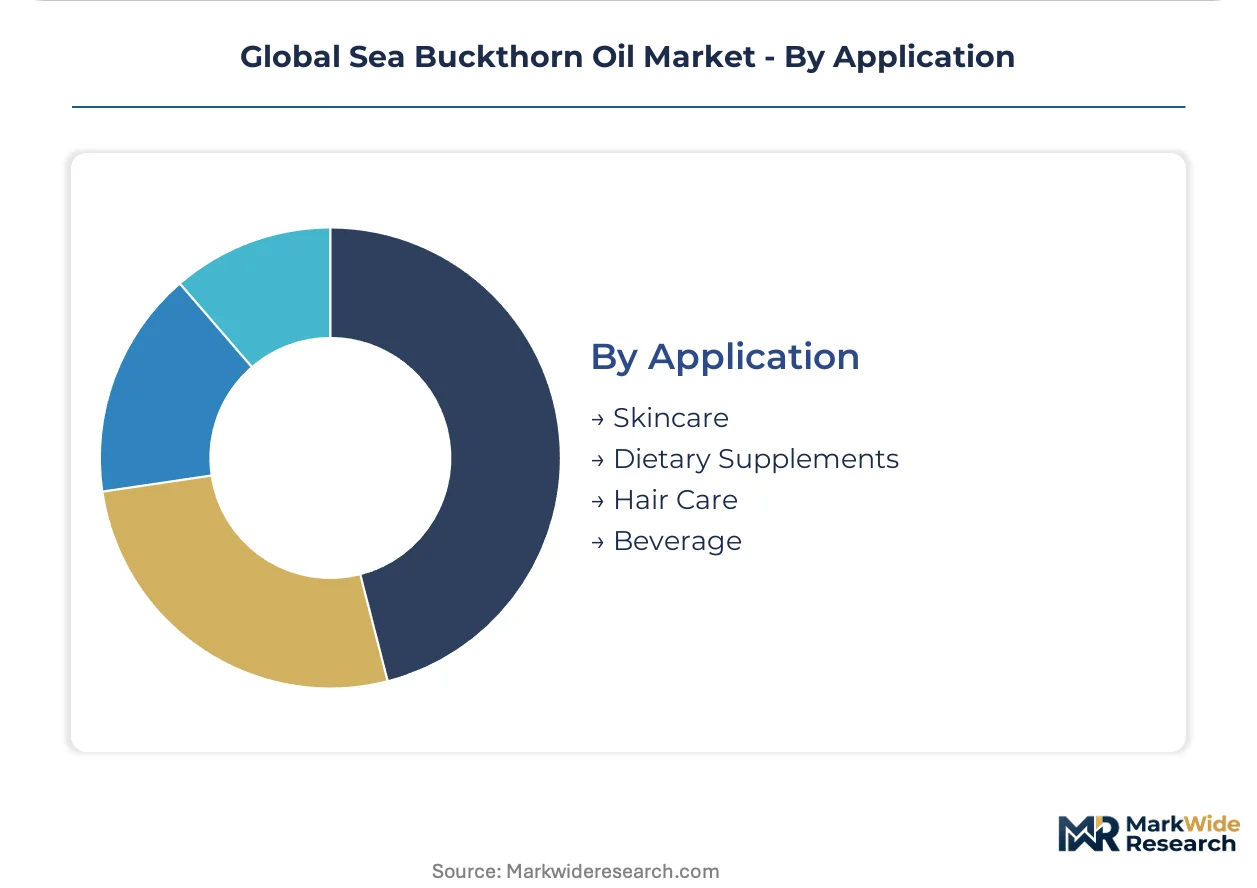
Application:
Functional claims and regulatory classification determine whether oil enters cosmetic, food, or pharmaceutical compliance pathways.
- Skincare:Anti-aging serums and barrier-repair formulations exploit carotenoid photoprotection. CO2 grades are displacing cold-pressed alternatives in French luxury lines due to superior oxidative stability.
- Dietary Supplements:Soft-gel capsules and functional food fortification targeting omega-7 intake. NMPA licensing in China and FDA notification pathways in the US create divergent specification requirements.
- Hair Care:Scalp treatments and conditioning agents leveraging palmitoleic acid's emollient properties. Niche positioning relative to argan and coconut oil alternatives constrains volume.
- Beverage:Functional drink fortification concentrated in Nordic, Mongolian, and Tibetan traditional consumption zones. Flavor compatibility limits expansion into mainstream beverage formulations.
Skincare anchors value creation. Dietary Supplements drives volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ningxia and Xinjiang processing clusters dominate supercritical CO2 extraction capacity expansion for sea buckthorn oil, serving both domestic nutraceutical brands and export contracts to European cosmetic houses. Regulatory divergence between EU REACH purity mandates and China's GB standards creates compliance complexity for cross-border suppliers.
China
NMPA-licensed facilities in Ningxia Hui Autonomous Region scale CO2 extraction lines to meet omega-7 capsule demand from domestic supplement brands. GB standards for edible oils govern import thresholds for berry feedstock entering coastal processing zones. Qinghai and Xinjiang high-altitude harvesting zones supply raw material to state-subsidized extraction plants concentrated in Yinchuan and Xining industrial corridors.
Germany
WELEDA's biodynamic procurement standards in Schwäbisch Gmünd exclude conventional supply chains, creating dedicated demand corridors for Demeter-certified cold-pressed grades. ECHA REACH registration requirements for novel botanical substances tighten substance identity documentation for personal care applications. Bavarian and Baden-Württemberg cosmetic formulators consolidate supplier panels around REACH-registered processors with dedicated dossier maintenance teams.
France
ANSM cosmetic notification requirements favor documented supply chain traceability that bypasses traditional Rotterdam commodity brokers. Paris and Lyon-based skincare houses negotiate multi-year offtake agreements with Chinese CO2 processors for anti-aging serum formulations. Provence-Alpes-Côte d'Azur artisan producers maintain niche positions in unrefined cold-pressed grades for clean-label positioning.
United States
FDA notification pathways for dietary supplements create divergent specification requirements from EU cosmetic compliance routes. SIBU leverages Rocky Mountain sourcing networks in Utah and Idaho to sustain year-round cold-pressed output for domestic nutraceutical brands. Pacific Northwest extraction facilities in Oregon and Washington serve artisan cosmetic producers targeting clean-label retail channels.
India
FSSAI registration pathways for imported botanical oils remain underutilized by Chinese exporters, creating positioning opportunities for CO2-extracted grades in Ayurveda-aligned supplement lines. Maharashtra and Gujarat-based nutraceutical formulators seek alternative omega-7 sources to reduce import dependency. Himalayan wild harvest zones in Ladakh and Himachal Pradesh supply raw berry material to domestic cold-press operators concentrated in Delhi-NCR processing hubs.
Global Sea Buckthorn Oil Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue supercritical CO2 specialization and biodynamic certification corridors. The vendor base organizes around three strategic archetypes: alpine-sourced cold-press specialists, Chinese state-subsidized CO2 scale operators, and biodynamic-certified integrated producers. Competitive intensity concentrates on long-term offtake negotiations with European cosmetic houses and capacity expansion in Ningxia extraction zones. Technology licensing agreements between Chinese equipment fabricators and European processors accelerate CO2 adoption curves.
Within the integrated biodynamic tier, WELEDA and SIBU occupy positions that exemplify certification-driven procurement separation from commodity supply chains. Among extraction-technology specialists, Connoils represents the toll-processing archetype serving brands lacking in-house CO2 capacity. Chinese scale operators including Lehberry sit within the state-subsidized capacity expansion cluster targeting export nutraceutical contracts. These three archetypes—certified integrated, toll-processing service, and subsidized scale—capture distinct margin pools based on regulatory qualification depth rather than volume alone.
| Leading Market Players |
|---|
| Natures Aid |
| W.S. Badger Company |
| SeabuckWonders |
| Lehberry |
| Erbology |
| SIBU |
| WELEDA |
| Connoils |
| Biosash |
| Others |
Value Chain & Pricing Dynamics
State-subsidized Chinese processors anchor capacity ownership in sea buckthorn oil, compressing margin structures for European craft producers while concentrating pricing power among Ningxia extraction clusters with seven-figure CO2 equipment investments.
Pricing Analysis
Input-cost pass-through from organic berry procurement premiums is intensifying margin compression at mid-scale European processors lacking long-term alpine sourcing contracts. Three-tier pricing structure across premium, standard, and economy levels separates Demeter-certified cold-pressed grades from CO2-extracted nutraceutical tiers and refined pharmaceutical encapsulation contracts. Pricing pressure stems from rosehip oil substitution in mass-market skincare where palmitoleic acid content becomes secondary to price positioning. Mass-market nutraceutical buyers exhibit highest price sensitivity, while German biodynamic cosmetic houses tolerate certification premiums.
Supply Chain Analysis
Single-source vulnerability sits with Mongolian and Siberian wild harvest zones where climate stress on Hippophae rhamnoides berry yields creates volume volatility. Supply draws from China's Ningxia and Xinjiang processing clusters, Germany's Demeter-certified alpine networks, and Himalayan wild harvest corridors in India. Raw material dependencies include high-altitude berry feedstock, supercritical CO2 extraction equipment, and organic certification auditing services. Tariff exposure looms for Chinese CO2 grades entering European cosmetic supply chains under evolving REACH substance identity requirements. Distribution runs through direct multi-year offtake agreements between Chinese processors and European formulators, displacing Rotterdam commodity brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sea buckthorn oil has matured into a late-cycle quality story as ECHA purity mandates and clean-label nutraceutical positioning shift procurement toward certified cold-pressed and CO2-extracted specifications with documented phytochemical profiles.
For Market Incumbents: Lock in long-term offtake agreements with Ningxia CO2 processors before capacity scarcity hardens. Secure backward integration into Demeter-certified alpine berry sourcing networks to defend margin position against Chinese state-subsidized scale operators. Prioritize REACH dossier maintenance teams as ECHA compliance costs filter out small-scale importers lacking in-house regulatory affairs capacity.
For New Entrants and Emerging Players: Ayurveda-aligned supplement formulators in Maharashtra and Gujarat represent an underserved buyer archetype with FSSAI registration pathways still underutilized by Chinese exporters. Target CO2-extracted omega-7 capsule supply to Indian nutraceutical brands seeking import diversification away from European refined grades. Lead with NMPA-licensed facility documentation to accelerate FSSAI approval timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European cold-press operators facing organic certification premium compression without alpine sourcing contracts. Long-term viability over the projection horizon favors acquisition targets with captive berry networks or toll-processing relationships with Chinese CO2 facilities. Watch for divergence between EU cosmetic ingredient disclosure rules and China's evolving GB standards as inflection indicator for cross-border supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpine Berry Sourcing | Demeter-certified networks in Bavaria and Baden-Württemberg secure supply exclusivity for German cosmetic houses. |
| Supercritical CO2 Capacity Expansion | Ningxia state-subsidized facilities capture export nutraceutical contracts previously served by solvent-extracted imports. |
| REACH Registration Investment | ECHA-compliant dossier maintenance teams qualify processors for consolidated German and French supplier panels. |
| Direct Sales Channel Development | Multi-year offtake agreements with Chinese processors bypass Rotterdam brokers under ANSM traceability requirements. |
| Liposomal Encapsulation R&D | Pharmaceutical-grade applications previously blocked by oxidation stability constraints open through technology convergence. |
Study Parameters
Coverage spans China, Germany, France, India, and the United States, with primary inputs from each market cluster combined with secondary validation. Interviews with extraction facility technical directors, cosmetic formulator procurement leads, nutraceutical brand regulatory affairs managers, and organic certification auditors were triangulated against customs trade data, ECHA REACH registration databases, NMPA facility licensing records, and FSSAI import registration filings. Bottom-up capacity assessments across Ningxia and Xinjiang processing zones were reconciled with top-down demand estimates from European cosmetic house procurement disclosures.
Rate-of-change decomposition across the analysis window separates volume growth from price realization by extraction method tier. The analytical framework models segmentation across cold-pressed, refined, unrefined, and CO2-extracted product types; cosmetics, pharmaceuticals, food and beverage, and nutraceutical end users; and online retail, supermarkets, health stores, and direct sales channels. CAGRs were derived from capacity expansion timelines in Chinese industrial corridors and procurement pattern shifts in German and French cosmetic houses. Industry-specific inputs include berry yield volatility models for Mongolian and Siberian wild harvest zones and EMA guideline evolution timelines for herbal medicinal products.
Underlying measurement precision varies by segment; supercritical CO2 extraction capacity and REACH-registered processor counts carry tighter precision than wild harvest yield projections. Forecasts reflect assumptions about regulatory divergence between EU cosmetic ingredient disclosure rules and China's GB standards, with climate stress on high-altitude berry zones and substitution pressure from rosehip oil representing specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Gentian Market
Specialty Ingredients
Global Fruit and Vegetable Powder Market
Specialty Ingredients
Tamanu Oil Market
Specialty Ingredients
Fermentation Products Market
Specialty Ingredients
Sun-Care Natural Oils Market
Specialty Ingredients
Middle East and Africa Specialty Food Ingredients Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Dessert Variegates Market
Specialty Ingredients
Mangosteen Extract Market
Specialty Ingredients
Global Ayurvedic Herbs Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Asia-Pacific Specialty Food Ingredient Market
Specialty Ingredients
Marine Spicules Market
Specialty Ingredients
Agarwood Essential Oil Market
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
Aromatherapy Oils Market