
 Sun-Care Natural Oils Market | 2026-2036
Sun-Care Natural Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Sun-Care Natural Oils Market Analytics
Subscription-based replenishment services is restructuring how sun-care natural oils reach households, converting one-time buyers into recurring revenue streams. L'Oréal Paris leverages its digital beauty ecosystem to lock in repeat purchases through auto-delivery programs. Beiersdorf AG anchors its Nivea Sun portfolio in pharmacy loyalty schemes that sustain year-round engagement. Young Living Essential Oils competes through member-exclusive oil blends that differentiate its direct-to-consumer channel from mass retail.
Sun-care natural oils comprise plant-derived lipid formulations—typically cold-pressed coconut, carrot seed, or raspberry seed oils with tocopherol stabilizers—engineered to provide photoprotective, emollient, or erythema-repairing functions without synthetic UV filters. SPF Oils now command the largest revenue pool as consumers seek dual-function protection that eliminates separate sunscreen layering, while After-Sun Oils represent the fastest-growing segment driven by post-exposure soothing protocols among athletic and outdoor demographics. Distribution through Specialty Stores captures premium margin pools where trained staff educate buyers on comedogenic ratings and botanical provenance.
FDA sunscreen monograph enforcement shapes permissible SPF claims and active ingredient thresholds for products entering US commerce, while EU REACH and the EU Green Deal constrain petroleum-derived emollient use and mandate biodegradability testing for rinse-off formulations. ANVISA in Brazil enforces strict botanical origin documentation that elevates compliance costs for imported natural oil inputs. Stakeholders must monitor evolving regulatory divergence between jurisdictions to determine whether centralized or regionalized formulation strategies minimize certification burden.
Market Dynamics
Subscription-based replenishment services are restructuring how sun-care natural oils reach households, converting one-time buyers into recurring revenue streams and locking in year-round engagement through auto-delivery programs and pharmacy loyalty schemes.
Growth Catalysts
- EU REACH compliance:Tightening ingredient scrutiny in Europe pushes dermatology clinics toward broader SPF oil portfolios, elevating professional channel penetration.
- Brazilian ANVISA labeling rules:Mandatory transparent botanical documentation creates competitive advantage for brands with verified supply chains.
- Cold-pressed extraction technology:Advanced mechanical pressing preserves tocopherol stabilizers in carrot seed and raspberry seed oils, improving photoprotective efficacy claims.
Market Restraints
- Petroleum-derived emollient constraints:EU Green Deal mandates biodegradability testing for rinse-off formulations, forcing reformulation of legacy oil bases.
- Botanical input cost volatility:Weather-dependent coconut and carrot seed harvests in Southeast Asia create margin pressure during poor growing seasons.
- FDA sunscreen monograph friction:Permissible SPF claim thresholds and active ingredient limits restrict dual-function oil positioning in US commerce.
Strategic Opportunities
- Athletic after-sun protocols:Post-exposure soothing demand among outdoor demographics drives fastest-growing segment expansion for erythema-repairing oil blends.
- Specialty store education models:Trained staff explaining comedogenic ratings and botanical provenance capture premium margin pools unavailable in mass retail.
- Direct-to-consumer member exclusives:Personalized oil blend subscriptions bypass traditional distribution, building proprietary customer data assets.
Industry Challenges
- Cross-jurisdictional certification timelines:Divergent biodegradability testing standards between EU REACH and US EPA requirements delay unified product launches.
- Botanical provenance verification systems:ANVISA-mandated origin documentation demands expensive supply chain tracing infrastructure for imported natural inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sun-Care Natural Oils Market |
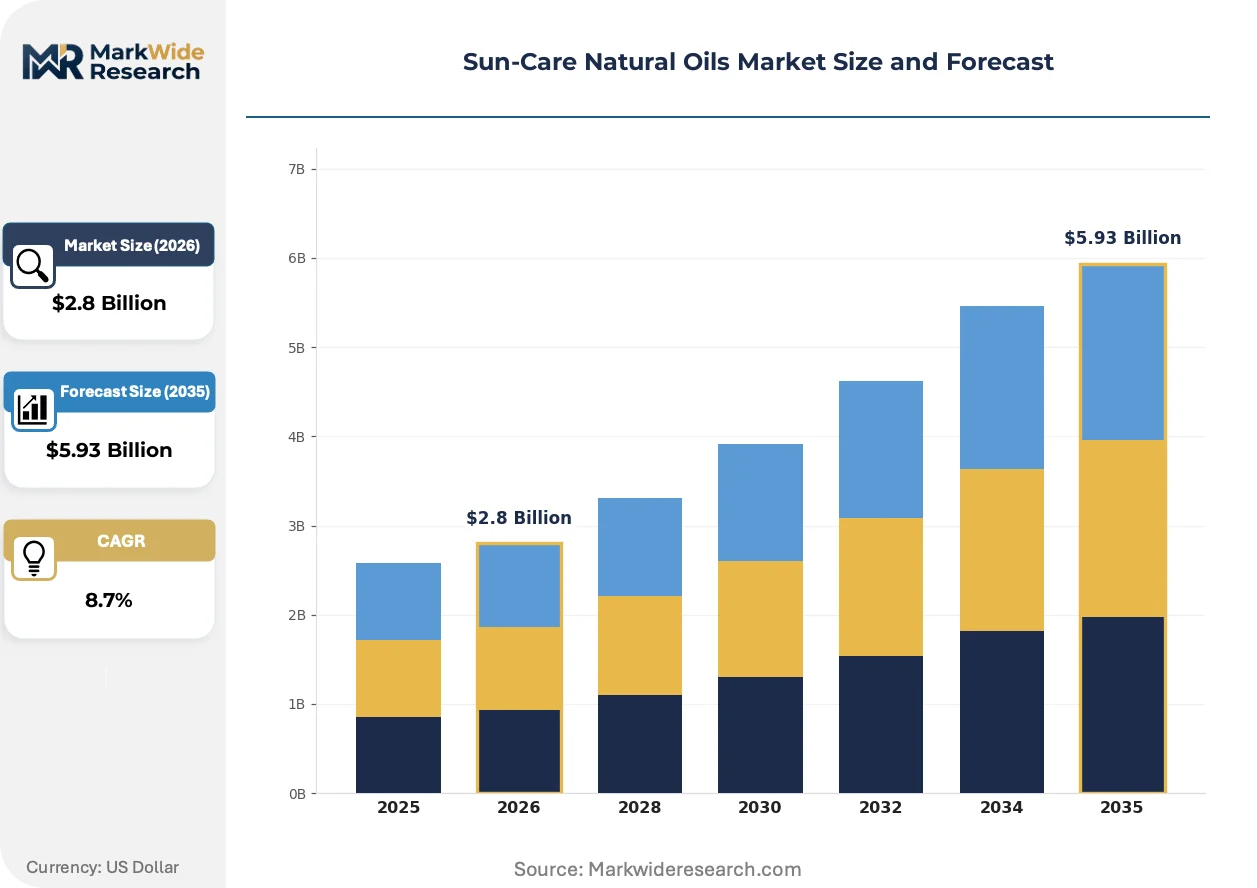
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SPF Oils, Moisturizing Oils, After-Sun Oils, Tanning Oils Application: Skin Protection, Tanning, Hydration, After-Sun Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies End User: Individuals, Salons, Dermatology Clinics, Fitness Centers |
| Companies Covered | Johnson & Johnson Services, Inc., L'Oréal Paris, Beiersdorf AG, Procter & Gamble, Unilever, Shiseido Co., Ltd., The Estée Lauder Companies, Burt's Bees, Young Living Essential Oils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sun-Care Natural Oils Market Evolving Landscape
Formulation science and distribution architecture are converging to redefine how photoprotective oils reach end-users, with regulatory pressure and behavioral shifts compressing traditional go-to-market timelines.
Encapsulated UV-filter technology is electrifying the SPF oil category by embedding mineral actives within lipid matrices that eliminate white-cast aesthetics. Premium cosmetic brands in Germany and South Korea are accelerating adoption for facial oil formats. This convergence is compressing the performance gap between synthetic chemical screens and mineral-based natural alternatives.
EU Green Deal biodegradability mandates are forcing rinse-off oil manufacturers to replace petroleum-derived emollients with plant-based alternatives. The regulation imposes aquatic toxicity testing that elevates R&D expenditure for mass-market portfolios. Specialty oil producers with existing botanical supply chains are capturing market position while reformulation lags plague conventional players.
Athletic and outdoor consumer segments are compressing purchase cycles through seasonal replenishment subscriptions that bundle SPF oils with after-sun recovery formulations. This behavior shift displaces sporadic retail purchasing with predictable direct relationships. Brazil and Australia show highest subscription penetration where year-round sun exposure sustains continuous usage patterns.
Sun-Care Natural Oils Market Segmentation
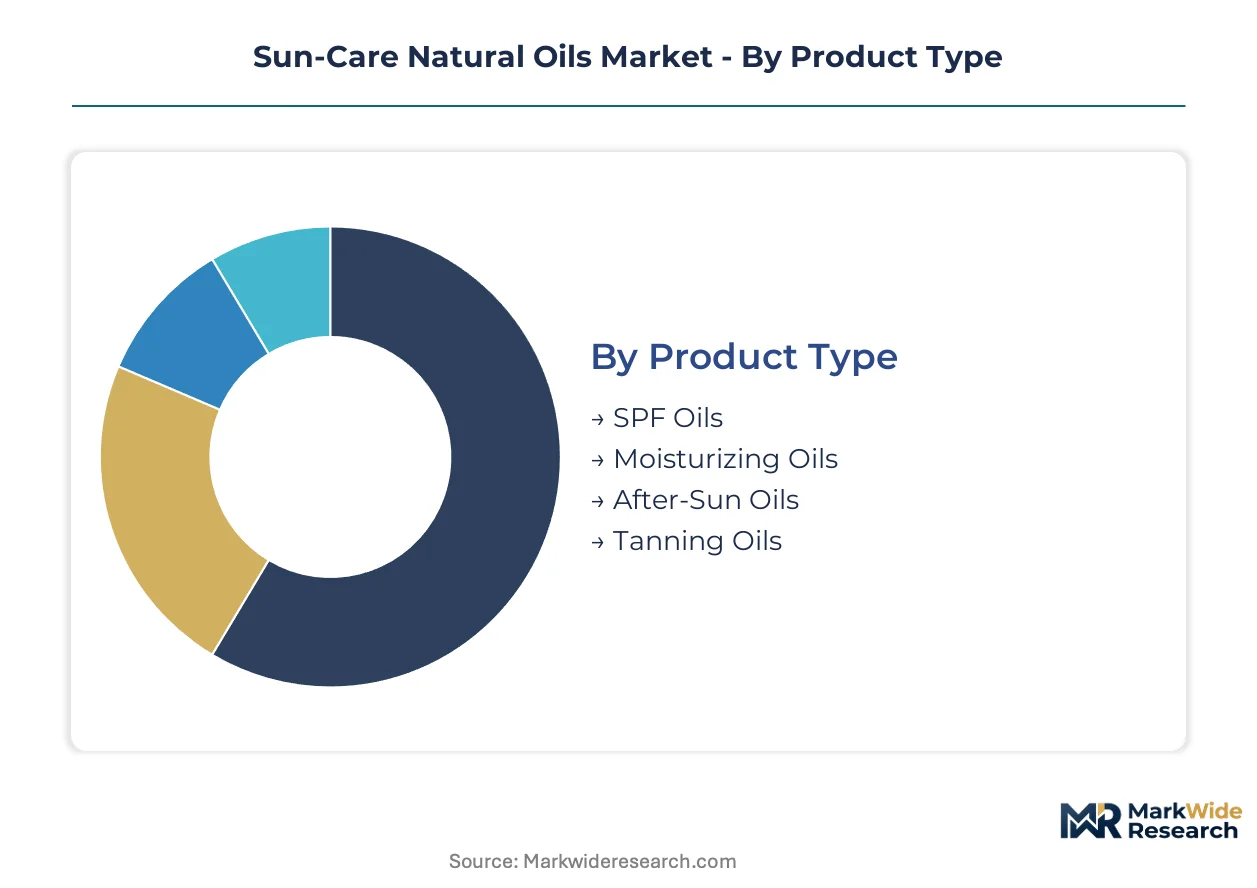
Segmentation in sun-care natural oils reveals how formulation chemistry, channel economics, and end-user protocols create distinct margin pools. Manufacturers must align cold-pressing capabilities and botanical sourcing with the specific performance claims each segment demands.
Product Type:
Supply concentration clusters around extraction technology sophistication, with cold-pressed operations capturing premium tocopherol preservation while solvent-extracted volumes serve mass-market price points.
- SPF Oils:Mineral-active lipid matrices embed zinc oxide or titanium dioxide within carrot seed or raspberry seed oil bases to deliver photoprotection without synthetic chemical filters. Demand concentrates in Germany where dermatology clinics stock broader portfolios under tightening EU REACH ingredient scrutiny. SPF Oils absorb the bulk of installed capacity; After-Sun Oils are expanding most quickly.
- After-Sun Oils:Erythema-repairing formulations combine high-linoleic safflower oil with bisabolol and vitamin E to accelerate barrier recovery after UV exposure. Athletic and outdoor demographics in Brazil and Australia drive steepest expansion through seasonal replenishment subscriptions.
- Moisturizing Oils:Emollient-focused blends prioritize occlusive plant butters and squalane for daily hydration maintenance.
- Tanning Oils:Low-SPF or SPF-free formulations accelerate melanin production through tyrosine precursors and carotenoid-rich botanicals.
SPF Oils command the dominant revenue position; After-Sun Oils are climbing the fastest among athletic demographics.
Application:
Cost tier stratification separates clinical-grade protocols from consumer self-care, with professional channels absorbing higher per-unit prices for documented botanical provenance.
- Skin Protection:Prophylactic UV defense applications require validated SPF claims and photostability testing under FDA monograph or EU COLIPA standards. Brazil's ANVISA labeling rules push brands toward transparent sourcing documentation.
- After-Sun Care:Post-exposure soothing protocols target erythema reduction and barrier repair through anti-inflammatory botanical actives. Fitness centers and outdoor recreation facilities in Australia stock recovery formulations for member retention programs.
- Tanning:Cosmetic bronzing applications emphasize even melanin development with minimal burning risk.
- Hydration:Daily emollient maintenance competes with mainstream body care through sensorial texture differentiation.
Skin Protection absorbs the bulk of installed capacity; After-Sun Care is gaining share fastest among institutional buyers.
Distribution Channel:
Margin structure varies sharply by channel control, with direct relationships capturing recurring revenue streams that mass retail cannot replicate.
- Specialty Stores:Trained staff educate buyers on comedogenic ratings, botanical provenance, and cold-press extraction markers. Germany's pharmacy-adjacent beauty retailers capture premium positioning through staff certification programs.
- Online Retail:Auto-delivery subscriptions convert one-time buyers into predictable revenue through algorithmic replenishment timing. Brazil and Australia show highest penetration where year-round sun exposure sustains continuous usage.
- Pharmacies:Professional endorsement channels require clinical validation documentation and stability testing.
- Supermarkets:Mass-market velocity depends on price positioning and seasonal promotional timing.
Specialty Stores absorb the bulk of installed capacity; Online Retail is expanding most quickly through subscription mechanics.
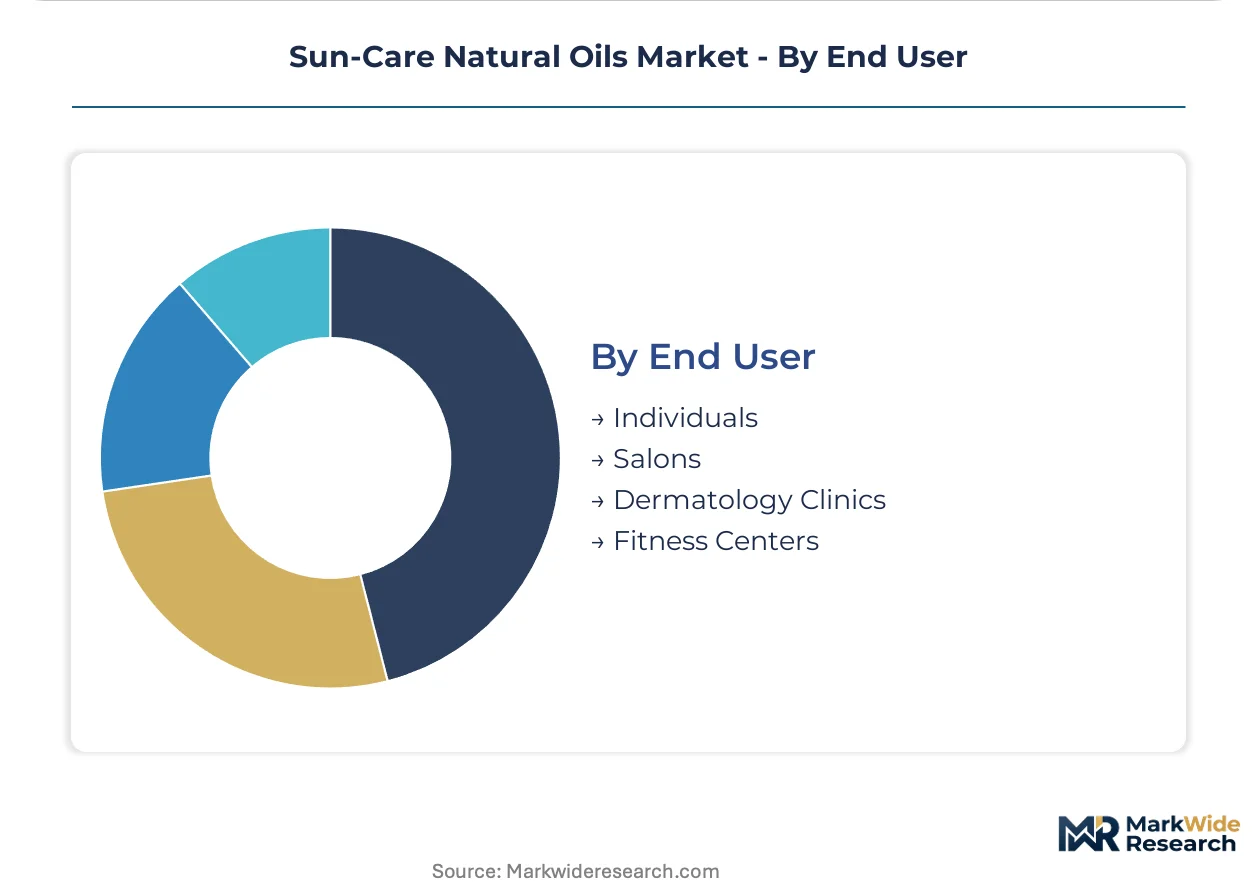
End User:
Customer type determines formulation complexity and compliance burden, with institutional buyers demanding batch-level traceability that individual consumers rarely request.
- Individuals:Direct consumers purchase through retail or subscription channels based on sensorial preference, SPF rating, and clean-label positioning. Brazilian ANVISA enforcement elevates preference for brands with verified supply chain documentation.
- Dermatology Clinics:Professional channels stock clinical-grade portfolios with documented stability data and allergen screening. EU REACH compliance tightening drives clinic procurement toward broader SPF oil selections with full ingredient transparency.
- Salons:Service-integrated retail depends on wholesale pricing and treatment protocol compatibility.
- Fitness Centers:Member amenity programs bundle sun care with recovery products for brand differentiation.
Individuals absorb the bulk of installed capacity; Dermatology Clinics are expanding most quickly under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of cold-pressed botanical oils concentrates in Southeast Asian processing hubs, while consumption gravitates toward high-SPF regulatory environments in Western Europe and sun-intensive climates in South America. This geographic split shapes formulation standards and compliance investments across the value chain.
Germany
Dermatology clinics in Berlin and Hamburg stock expanded SPF oil portfolios as EU REACH tightens ingredient disclosure requirements. The country's pharmacy-adjacent beauty retailers capture premium positioning through staff certification programs that explain comedogenic ratings to consumers. Bavaria hosts specialized cold-press extraction facilities serving cosmetic brands with tocopherol-preservation protocols.
Brazil
ANVISA labeling enforcement pushes brands toward transparent botanical sourcing documentation, elevating compliance costs for imported natural inputs. São Paulo and Rio de Janeiro anchor the fastest-growing after-sun oil segment among athletic demographics subscribing to seasonal replenishment services. Fitness centers in these metros bundle recovery formulations with membership retention programs.
United States
FDA sunscreen monograph restrictions on permissible SPF claims and active ingredient thresholds constrain dual-function oil positioning in mass retail channels. California's clean-beauty consumer base drives demand for mineral-active lipid matrices that eliminate synthetic chemical filters. Los Angeles-based specialty retailers train staff on botanical provenance verification to justify premium pricing.
Australia
TGA regulations align with stringent photoprotection standards that favor validated SPF testing for natural oil formulations. Sydney and Melbourne show highest subscription penetration for year-round sun care replenishment, where continuous UV exposure sustains usage continuity. Outdoor recreation facilities in Queensland stock institutional-grade after-sun protocols for member differentiation.
South Korea
MFDS cosmetic safety guidelines accelerate adoption of encapsulated mineral actives within facial oil formats that address white-cast aesthetics. Seoul's premium cosmetic brands lead formulation innovation for K-beauty export markets demanding photostable natural alternatives. Gyeonggi Province clusters R&D facilities developing lipid-matrix UV-filter technology for global brand licensing.
Sun-Care Natural Oils Market Competitive Landscape
Capital-heavy producers with captive cold-press extraction infrastructure compete with asset-light brand houses that outsource botanical processing to third-party manufacturers. The market structure fragments across three tiers: multinational consumer goods conglomerates with pharmacy distribution scale, mid-sized specialists with verified supply chain documentation, and direct-to-consumer subscription operators with proprietary member data assets. Dominant competitive moves include vertical integration into upstream botanical sourcing and algorithmic replenishment platform development that locks in recurring revenue streams.
Within the multinational tier, Johnson & Johnson Services, Inc. and L'Oréal Paris occupy positions anchored by pharmacy channel penetration and digital beauty ecosystem scale. Beiersdorf AG exemplifies the European specialist archetype with pharmacy loyalty schemes that sustain year-round engagement beyond seasonal purchasing patterns. Young Living Essential Oils represents the direct-to-consumer subscription model, competing through member-exclusive oil blends that bypass traditional retail distribution entirely.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| L'Oréal Paris |
| Beiersdorf AG |
| Procter & Gamble |
| Unilever |
| Shiseido Co., Ltd. |
| The Estée Lauder Companies |
| Burt's Bees |
| Young Living Essential Oils |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap cold-press operators in Bavaria and São Paulo anchor supply discipline through generational capital structures that resist short-term margin erosion. Their captive botanical sourcing contracts with Southeast Asian coconut and carrot seed cooperatives create pricing power insulation against commodity volatility, while EU REACH compliance investments force smaller competitors toward distressed asset sales.
Pricing Analysis
Margin tightening in mass-market SPF oils reflects petroleum-derived emollient replacement costs under EU Green Deal biodegradability mandates. Three-tier pricing structure across premium cold-pressed, standard mechanically-extracted, and economy solvent-processed grades separates dermatology clinic procurement from supermarket velocity. Certification tier under ANVISA documentation rules commands 15-25% premiums in Brazil. Cost compression accelerates because weather-dependent harvests in Southeast Asia create input volatility. Individual consumers through subscription channels show lowest price sensitivity; mass retail buyers exhibit highest elasticity.
Supply Chain Analysis
EU REACH and ANVISA certification gating concentrates qualified supply among cold-press facilities with documented tocopherol preservation protocols. Production gravity centers on Indonesia, Philippines, and Vietnam for coconut oil feedstock; Germany and South Korea for encapsulated mineral-active formulation. Raw material dependencies include cold-pressed carrot seed oil, raspberry seed oil, and zinc oxide mineral actives. Single-source vulnerability in Southeast Asian harvest seasons creates supply disruption risk. Distribution runs through specialty store and direct-to-consumer subscription channels that bypass traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sun-care natural oils is consolidating under regulatory compliance cost pressure that eliminates sub-scale formulators lacking ANVISA documentation infrastructure or EU REACH testing capabilities.
For Market Incumbents: Acquire cold-press extraction facilities with captive Southeast Asian botanical contracts to secure tocopherol-preservation capacity. Consolidate specialty store distribution relationships before direct-to-consumer subscription operators capture pharmacy-adjacent positioning. Defend against mineral-active encapsulation technology disruption through R&D partnerships with Seoul-based cosmetic innovation clusters. For New Entrants and Emerging Players: Encapsulated UV-filter lipid matrix technology offers entry wedge against legacy white-cast mineral formulations. Target Australian athletic after-sun subscription white-space where TGA-validated SPF testing creates barrier to synthetic chemical competitors. Pursue fitness center institutional procurement channels with bundled SPF and recovery oil protocols. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with verified ANVISA supply chain documentation in Brazil. Long-term viability hinges on backward integration into Southeast Asian cooperative sourcing structures. Watch EU Green Deal biodegradability enforcement acceleration as inflection signal for petroleum-emollient replacement capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Facility Acquisition | Captive tocopherol preservation capacity secures premium SPF oil positioning under EU REACH scrutiny. |
| ANVISA Documentation Infrastructure | Verified botanical provenance systems unlock Brazil pharmacy channel access against import competitors. |
| Encapsulated Mineral-Active R&D | Seoul-based formulation partnerships address K-beauty white-cast aesthetic demands for facial oil formats. |
| Athletic Subscription Platform Launch | Algorithmic replenishment timing converts sporadic retail purchasing into predictable recurring revenue streams. |
| Biodegradable Emollient Reformulation | EU Green Deal compliance eliminates petroleum-derived base oils from rinse-off portfolio exposure. |
Research Methodology
Trade databases, EU REACH substance registration filings, and ANVISA cosmetic notification records formed the secondary backbone for supply chain mapping and regulatory constraint identification. Primary interviews with cold-press facility operators, dermatology clinic procurement managers, specialty store category buyers, and direct-to-consumer subscription platform executives validated extraction technology claims and channel margin structures. Bottom-up capacity modeling across Indonesian and Philippine coconut processing hubs triangulated against top-down consumption estimates from Brazil and Australian retail audit data.
Historical trendline analysis of cold-pressed oil pricing volatility against solvent-extracted commodity benchmarks informed projection mechanics across the analysis window. Segmentation dimensions modeled include product type (SPF Oils, After-Sun Oils, Moisturizing Oils, Tanning Oils), application protocol (Skin Protection, After-Sun Care, Tanning, Hydration), distribution channel (Specialty Stores, Online Retail, Pharmacies, Supermarkets), and end-user archetype (Individuals, Dermatology Clinics, Salons, Fitness Centers). CAGRs derived from regression-adjusted growth rates incorporating EU Green Deal implementation pacing and ANVISA enforcement intensity.
Several conditions sit outside the modeled scope, including synthetic chemical sunscreen substitution elasticity, climate-induced coconut harvest failure scenarios, and FDA monograph reform timing. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and subscription adoption saturation curves. A model refresh is warranted upon material change in EU biodegradability testing standard harmonization or ANVISA origin documentation mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Specialty Beverage Stabilizers Market
Specialty Ingredients
North America Grape Seed Extract Market
Specialty Ingredients
Normal and Specialty Fats Market
Specialty Ingredients
Europe Specialty Food Ingredients Market
Specialty Ingredients
Floral Water Market
Specialty Ingredients
Mangosteen Market
Specialty Ingredients
Vanilla Extract Alternatives Market
Specialty Ingredients
Green Sic Market
Specialty Ingredients
Specialty Carbohydrates Market
Specialty Ingredients
Tea-Based Skin Care Products Market
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
Specialty Meat Ingredients Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
Global Sea Buckthorn Oil Market