
 Global Infusion Pharmacy Management Market | 2026-2036
Global Infusion Pharmacy Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Infusion Pharmacy Management Market Foresight
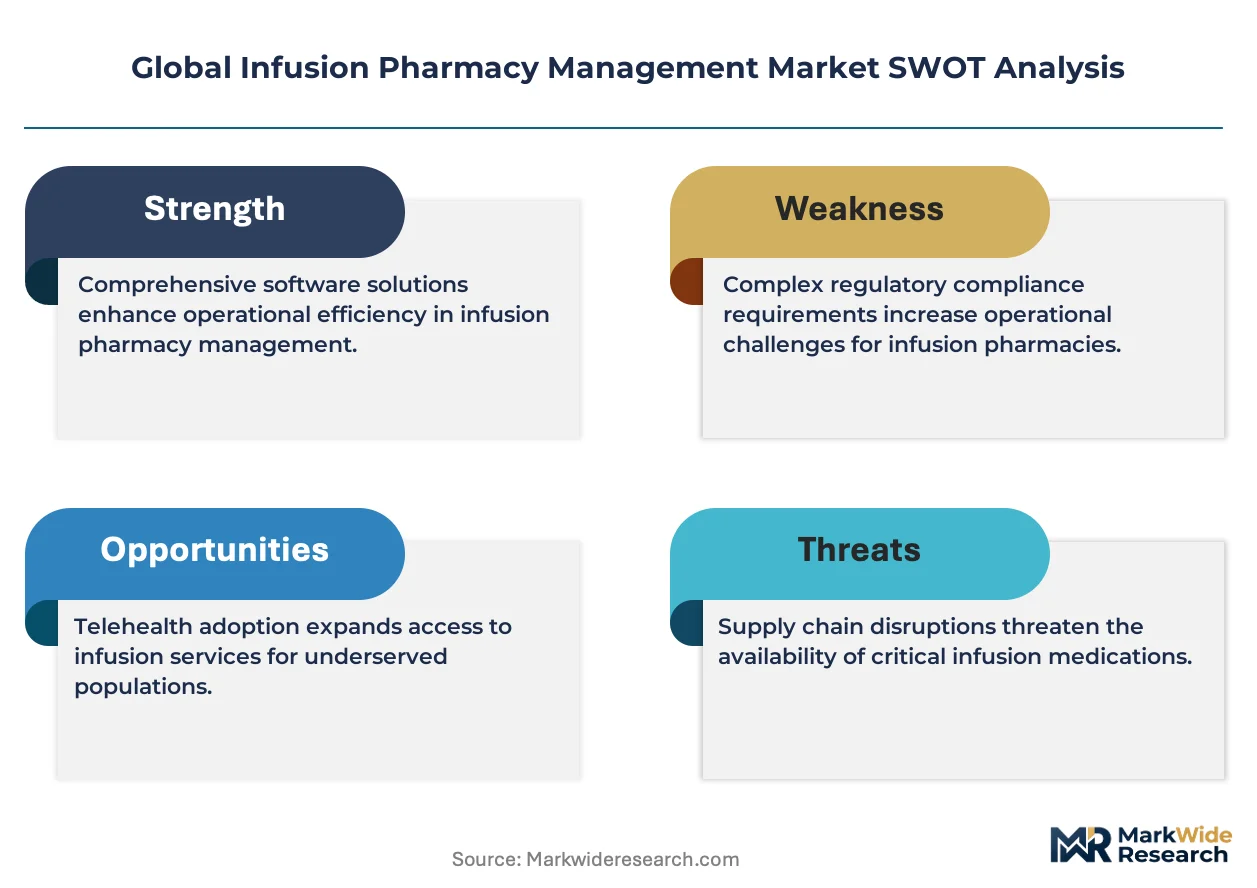
North American specialty pharmacy networks are restructuring their infusion service footprints to capture higher-margin home infusion volumes. McKesson Corporation leverages its wholesale infrastructure to anchor distribution density in key metropolitan corridors. CVS Health sustains competitive pressure through vertical control over payer, PBM, and pharmacy assets. Option Care Health Inc. specializes in home and alternate-site infusion, occupying a narrow but defensible clinical niche.
Infusion pharmacy management encompasses software, hardware, and integrated platforms that automate sterile compounding workflows, dose verification, inventory serialization, and remote patient monitoring for parenteral therapies. These systems enforce beyond-use dating, environmental monitoring, and chain-of-custody documentation to prevent medication errors and microbial contamination. Cloud-based deployment is expanding fastest among home care providers seeking scalable interoperability with electronic health records and payer systems. Software solutions for compliance management and dose calculation command premium pricing due to embedded clinical decision support and regulatory audit trails. Hardware devices for sterile compounding remain a mature margin pool with replacement-driven demand cycles.
FDA oversight of 503B compounding facilities and HIPAA security rule enforcement shape capital allocation toward audit-ready platforms with embedded quality management modules. EMA's Good Manufacturing Practice annexes for sterile medicinal products and Japan's PMDA pharmacovigilance requirements create parallel compliance burdens for multinational platform vendors. Stakeholders must monitor evolving reimbursement parity between hospital-based and home infusion settings as site-of-care policy shifts determine addressable market expansion.
Market Dynamics
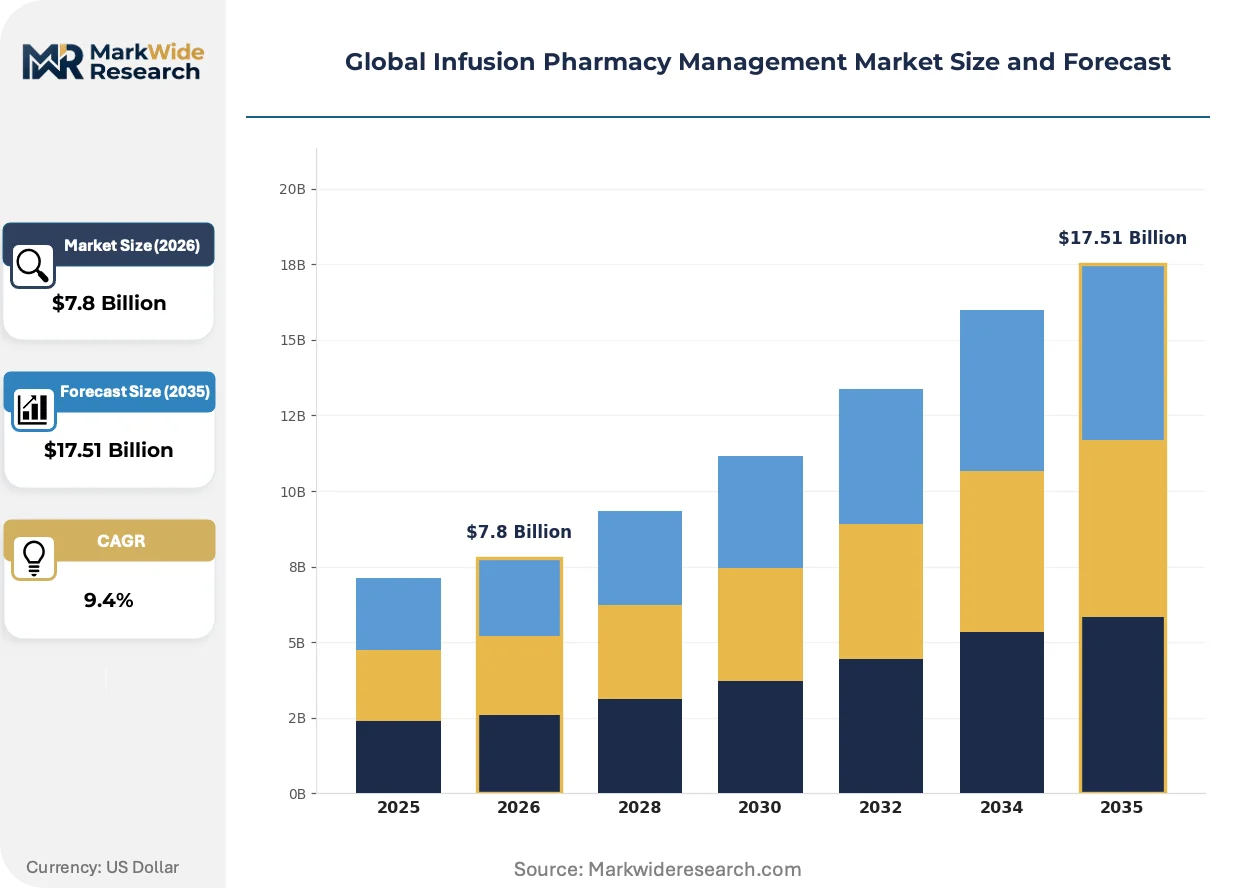
Site-of-care reimbursement parity policies are compressing hospital-based infusion margins while redirecting capital toward home delivery infrastructure and cloud-native pharmacy platforms.
Growth Catalysts
- HIPAA Security Rule Enforcement:Strengthened audit protocols in the United States are compelling pharmacy networks to replace legacy documentation systems with automated compliance modules that embed encryption and access logging.
- Japan's Aging Demographics:PMDA pharmacovigilance requirements for sterile compounding are accelerating platform adoption among home care providers serving elderly populations with complex parenteral therapies.
- Cloud-Native Interoperability:Electronic health record integration capabilities are pulling mid-sized infusion providers toward SaaS deployment models that reduce IT overhead.
Market Restraints
- FDA 503B Facility Oversight:Compounding quality standards are raising capital requirements for sterile production infrastructure, squeezing smaller regional operators.
- Specialized Pharmacy Technician Scarcity:Certification bottlenecks for sterile compounding personnel are constraining expansion velocity in high-demand metropolitan corridors.
- Hardware Replacement Cycles:Mature margin pools in compounding devices limit vendor pricing power and compress R&D recovery timelines.
Strategic Opportunities
- Germany's Ambulatory Care Shift:EMA Good Manufacturing Practice annexes for sterile products are creating compliant-platform demand among hospital-outpatient networks transitioning infusion services.
- Remote Patient Monitoring Convergence:Integration of biometric sensors with dose tracking software is opening subscription revenue streams for platform vendors serving chronic disease management.
- Reimbursement Parity Legislation:Site-of-care policy reforms in multiple jurisdictions are expanding addressable volume for home infusion operators.
Industry Challenges
- Legacy System Integration:Home care providers face technical debt when connecting cloud platforms to on-premise electronic health record architectures.
- Environmental Monitoring Calibration:Beyond-use dating automation requires continuous sensor validation that strains quality assurance staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Infusion Pharmacy Management Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Devices, Integration Platforms, Monitoring Systems Application: Medication Preparation, Dose Calculation, Inventory Tracking, Patient Monitoring, Compliance Management End User: Hospitals, Ambulatory Care Centers, Specialty Clinics, Home Care Providers Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based |
| Companies Covered | McKesson Corporation, CVS Health, Cardinal Health, Option Care Health Inc., CarepathRx, Brightree, ContinuumRx, Accredo Health Group, OptumRx, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Infusion Pharmacy Management Market Shifts & Advancements
Artificial intelligence and machine learning capabilities are embedding into pharmacy management platforms, transforming dose verification from rule-based checks to predictive clinical decision support.
AI-enabled dose calculation engines are expanding into infusion pharmacy workflows through embedded clinical decision support modules. Home care providers in the United States are adopting these tools fastest, driven by malpractice liability concerns and HIPAA audit readiness requirements. The technology is expanding into premium pricing tiers for software vendors who can demonstrate reduced medication error rates.
EMA's strengthened Good Manufacturing Practice annexes for sterile medicinal products are forcing platform vendors to re-architect quality management modules. Compounding facilities across Germany and neighboring jurisdictions must now demonstrate real-time environmental monitoring with automated deviation alerts. Specialty pharmacy networks are responding by consolidating vendor relationships around audit-ready platforms with pre-validated compliance templates.
Buyers are consolidating procurement around integrated platform suites rather than point solutions for compounding, inventory, and patient monitoring. Hospital-affiliated infusion centers in Japan are leading this shift, replacing fragmented vendor stacks with unified systems. The preference compresses sales cycles for full-suite vendors while marginalizing standalone software specialists.
Global Infusion Pharmacy Management Market Segmentation
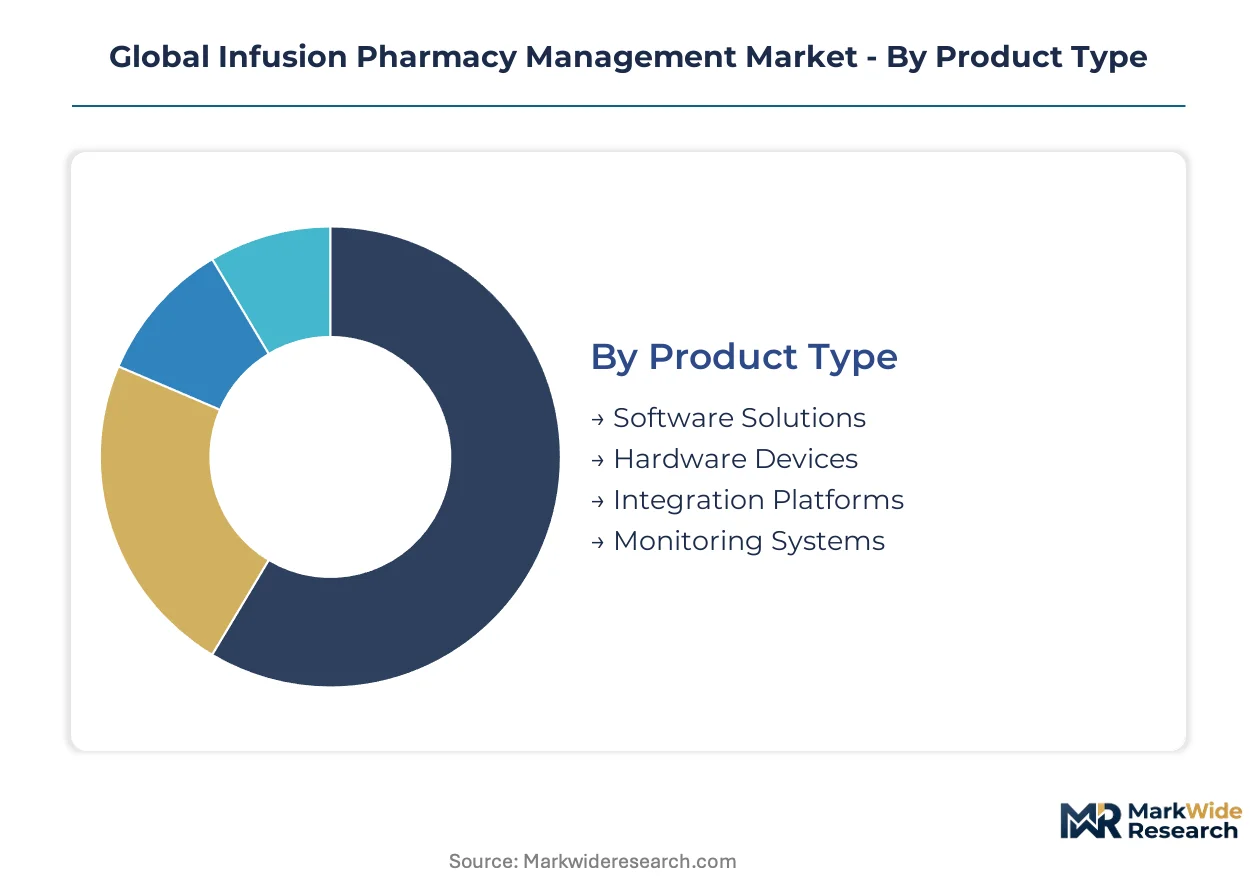
Segmentation reveals how capital flows diverge across technology layers and care settings in infusion pharmacy management. Upgrade cycles and interoperability requirements reshape procurement patterns differently for software, hardware, and service-oriented deployments.
Product Type:
Replacement dynamics vary sharply across product layers, with software platforms refreshing on 3-5 year cycles while hardware endures 7-10 year amortization schedules.
- Software Solutions:Modular architectures for sterile compounding workflow automation, dose verification algorithms, and regulatory audit trail generation. Demand clusters among United States home care networks modernizing for HIPAA Security Rule enforcement, with premium pricing attached to clinical decision support modules.
- Hardware Devices:Physical systems encompassing automated compounding pumps, environmental monitoring sensors, and barcode-enabled inventory stations. Germany's hospital-outpatient networks drive replacement demand as EMA Good Manufacturing Practice annexes mandate real-time contamination detection capabilities.
- Integration Platforms:Unified middleware connecting pharmacy management with electronic health records and payer systems.
- Monitoring Systems:Biometric-enabled remote patient tracking tools for home infusion settings.
Volume placements concentrate in Software Solutions; the faster expansion belongs to Integration Platforms.
Application:
Functional modules map to distinct staffing specializations and liability exposure profiles across pharmacy operations.
- Medication Preparation:Sterile compounding workflow engines enforcing beyond-use dating and environmental parameter logging. Japan's home care providers deploy these systems to satisfy PMDA pharmacovigilance documentation requirements for complex parenteral therapies.
- Compliance Management:Automated quality management modules with pre-validated FDA 503B and HIPAA audit templates. United States specialty pharmacy networks prioritize this function to reduce malpractice exposure and inspection preparation costs.
- Dose Calculation:Rule-based and AI-enabled engines for patient-specific dosing protocols.
- Inventory Tracking:Serialization and chain-of-custody systems for controlled substances and high-value biologics.
- Patient Monitoring:Remote surveillance tools integrating biometric feeds with dose administration records.
Procurement prioritizes Compliance Management for risk mitigation; Patient Monitoring climbs fastest on chronic disease management expansion.
End User:
Site-of-care economics and reimbursement parity policies redistribute platform demand across institutional and home-based settings.
- Home Care Providers:Independent and network-affiliated agencies delivering infusion services in residential settings. United States operators expand platform adoption fastest as site-of-care reimbursement parity narrows the gap with hospital-based payment rates.
- Hospitals:Acute care institutions maintaining inpatient infusion capabilities and transitioning selected services to outpatient models. Germany's university medical centers anchor demand for audit-ready platforms supporting EMA-compliant sterile production.
- Ambulatory Care Centers:Hospital-affiliated and independent outpatient infusion facilities.
- Specialty Clinics:Disease-focused practices managing complex parenteral therapies in concentrated patient populations.
Platform revenue concentrates in Home Care Providers; Ambulatory Care Centers gain share fastest on site-of-care migration.
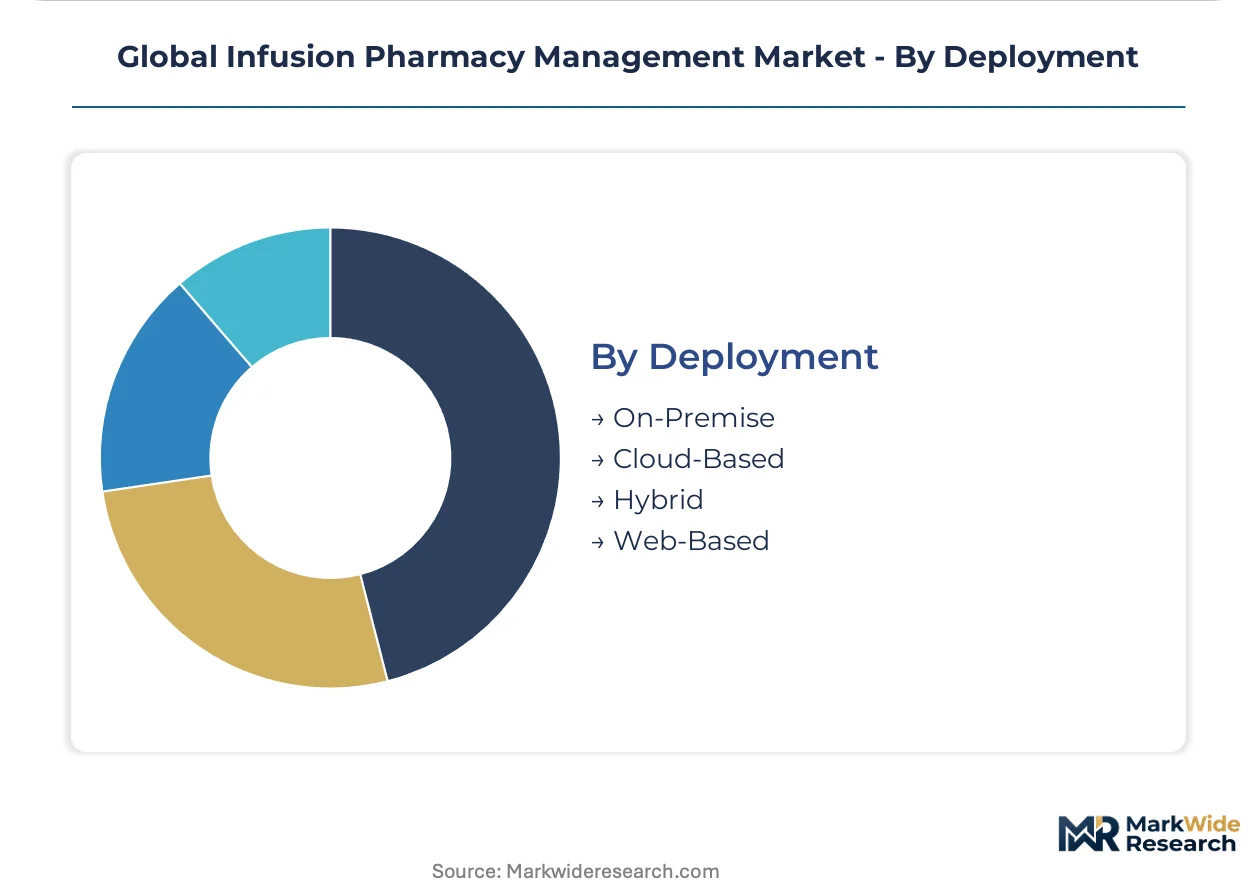
Deployment:
IT infrastructure maturity and interoperability requirements determine cloud migration velocity across customer segments.
- Cloud-Based:SaaS delivery models with scalable electronic health record integration and automatic regulatory update deployment. Mid-sized United States infusion providers adopt this mode to eliminate on-premise server maintenance and accelerate HIPAA compliance certification.
- Hybrid:Architectures combining local compounding workstation control with cloud-hosted analytics and reporting. Japan's hospital-affiliated networks favor this approach to balance PMDA data sovereignty requirements with centralized oversight needs.
- On-Premise:Fully localized installations retaining all data and processing within facility firewalls.
- Web-Based:Browser-accessible platforms without dedicated client software installation.
Customer additions concentrate in Cloud-Based deployment; Hybrid configurations expand most quickly among regulated multi-site operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmaceutical distribution infrastructure in the United States anchors regional investment flows, with reimbursement parity policies and HIPAA enforcement driving platform modernization across multiple jurisdictions.
United States
Site-of-care reimbursement parity and chronic disease prevalence accelerate home infusion platform adoption. FDA 503B oversight and HIPAA Security Rule enforcement compel pharmacy networks toward audit-ready cloud systems. The Dallas-Fort Worth corridor concentrates specialty pharmacy operations as regional hubs expand sterile compounding capacity.
Germany
Hospital-outpatient network restructuring and aging demographics shift infusion services toward ambulatory settings. EMA Good Manufacturing Practice annexes mandate real-time environmental monitoring capabilities. The Rhine-Ruhr metropolitan region anchors platform deployment as university medical centers consolidate vendor relationships.
Japan
PMDA pharmacovigilance requirements and elderly population growth drive demand for compliant home infusion documentation. METI digital health initiatives support cloud-hybrid architectures balancing data sovereignty with interoperability. The Kanto region around Tokyo concentrates hospital-affiliated infusion center modernization.
United Kingdom
NHS long-term plan commitments to shift-site care expand home infusion service commissioning. MHRA guidance on sterile compounding quality standards shapes platform procurement specifications. The Greater London area dominates specialty pharmacy network consolidation and platform investment.
Canada
Provincial health system integration efforts and rural access challenges elevate telehealth-connected infusion management. Health Canada oversight of sterile compounding facilities aligns with international GMP standards. The Toronto-Waterloo corridor anchors health technology procurement and platform vendor activity.
Global Infusion Pharmacy Management Market Competitive Landscape
Global majors compete with regional champions across distribution infrastructure and care delivery integration, producing a tiered structure where wholesale-backed platforms, vertically integrated health systems, and specialized home infusion operators occupy distinct competitive positions. Consolidation pressures favor entities controlling payer relationships, PBM assets, or captive distribution networks. Three archetypes dominate: wholesale-anchored platforms leveraging density economics, vertically integrated health systems combining insurance and pharmacy assets, and pure-play home infusion specialists defending clinical niches. Dominant competitive moves include geographic service footprint expansion and cloud-native platform acquisition to accelerate EHR interoperability.
Among wholesale-anchored platforms, McKesson Corporation and Cardinal Health exemplify scale-driven positioning through distribution infrastructure control. Within the specialized home infusion tier, Option Care Health Inc. occupies a narrow but defensible position focused on alternate-site clinical services. CVS Health represents vertically integrated health system architecture, combining payer, PBM, and pharmacy assets under unified management. These entities anchor competitive dynamics as mid-sized regional operators face capital constraints from escalating compliance requirements.
| Leading Market Players |
|---|
| McKesson Corporation |
| CVS Health |
| Cardinal Health |
| Option Care Health Inc. |
| CarepathRx |
| Brightree |
| ContinuumRx |
| Accredo Health Group |
| OptumRx, Inc. |
| Others |
Supply & Pricing Matrix
FDA 503B environmental monitoring mandates gate qualified supply access and premium-tier pricing for audit-ready infusion pharmacy platforms serving United States home care networks. EMA Good Manufacturing Practice annexes for sterile medicinal products create parallel certification barriers in Germany, compressing vendor margins for non-compliant systems while elevating pricing power for pre-validated quality management modules.
Pricing Analysis
Service-bundling separates annual software subscriptions with embedded compliance updates from unbundled hardware maintenance contracts and per-incident technical support. Three-tier pricing structure across premium, standard, and economy levels stratifies by clinical decision support depth and HIPAA audit trail sophistication. Cost compression in economy tiers intensifies because mid-sized regional operators face capital constraints from sterile compounding infrastructure requirements. Hospital-affiliated networks in Japan exhibit lowest price sensitivity due to PMDA pharmacovigilance liability exposure, while independent home care agencies in the United States prioritize total cost of ownership in procurement decisions.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor hub-and-spoke patterns for infusion pharmacy hardware and cloud platform delivery. Component sourcing draws from Taiwanese semiconductor foundries for environmental monitoring sensors, German precision engineering for automated compounding pumps, and United States software development for clinical decision support engines. Single-source vulnerability concentrates in specialized barcode-enabled inventory stations subject to FDA 503B validation requirements. Distribution runs through wholesale-anchored logistics networks controlled by McKesson Corporation and Cardinal Health, with last-mile delivery contracting to regional pharmacy service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native interoperability architectures are displacing legacy on-premise electronic health record integrations across infusion pharmacy management, compressing sales cycles for full-suite vendors while marginalizing standalone software specialists.
For Market Incumbents: To counter SaaS-native entrants with superior electronic health record integration, McKesson Corporation and CVS Health should deepen backward integration into sterile compounding device manufacturing and acquire cloud-native platform capabilities in the United States. Certification investment in pre-validated FDA 503B and HIPAA compliance modules preserves pricing power against audit-ready competitors. For New Entrants and Emerging Players: Launch via hybrid deployment models targeting Japan's hospital-affiliated networks seeking PMDA pharmacovigilance documentation with data sovereignty controls. White-space concentration exists in remote patient monitoring convergence for chronic disease management, with biometric sensor integration representing the most penetrable application layer. Direct-to-home care provider sales channels bypass wholesale-anchored incumbent control. For Investors and Strategic Acquirers: Site-of-care reimbursement parity legislation passage is the leading indicator that home infusion platform demand will accelerate across multiple jurisdictions. Long-term viability favors vendors controlling payer relationships or captive distribution networks over standalone software specialists. Acquisition target archetypes include regional home infusion operators with cloud-native platform adoption and established HIPAA compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Acquisition | Accelerates electronic health record interoperability for mid-sized United States infusion providers. |
| Pre-Validated Compliance Module Development | Reduces FDA 503B inspection preparation costs for specialty pharmacy networks. |
| Remote Patient Monitoring Integration | Opens subscription revenue streams through biometric sensor and dose tracking convergence. |
| Geographic Service Footprint Expansion | Captures site-of-care migration volumes in Germany's Rhine-Ruhr metropolitan corridor. |
| Sterile Compounding Infrastructure Investment | Satisfies EMA Good Manufacturing Practice annex requirements for real-time environmental monitoring. |
Research Methodology
Document review covered FDA 503B inspection records, EMA Good Manufacturing Practice guidance documents, and PMDA pharmacovigilance advisories, complemented by interviews with pharmacy operations directors, biomedical informatics officers, sterile compounding supervisors, and GPO contracts managers. Secondary validation drew from hospital procurement databases, CMS Medicare reimbursement filings, and specialty pharmacy network annual disclosures. Bottom-up demand modeling and top-down market sizing triangulated segment-level outputs.
Quantitative outputs span product type, application function, end user setting, and deployment architecture dimensions across the projection horizon. CAGRs derive from regression analysis against chronic disease prevalence trajectories and site-of-care policy shift timelines. Forecast inputs incorporate HIPAA Security Rule enforcement intensity indices and EMA audit frequency patterns for sterile medicinal products.
Regulatory enforcement delays, reimbursement parity legislative setbacks, and cloud platform cybersecurity incidents are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
Acute Care Market
Healthcare Services
US Care Services Market
Healthcare Services
Medically Supervised Weight Loss Services Market
Healthcare Services
Funeral Products and Services Market
Healthcare Services
Assisted Living Market
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
US Concierge Medicine Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
US Medical Billing Outsourcing Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Aged Care Market