
 Specialty Medical Chairs Market | 2026-2036
Specialty Medical Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Medical Chairs Market Intelligence
Skilled biomedical technician shortages across North American healthcare systems is unwinding installation and maintenance capacity for complex electric chair fleets. Dentsply Sirona leverages its dental equipment service infrastructure to support chair uptime commitments in outpatient settings. Danaher sustains R&D intensity across its life sciences platform, extending ergonomic design protocols into clinical seating subsidiaries. Midmark Corp. dominates the North American clinic renovation channel through direct specification relationships with architectural firms.
Specialty medical chairs are purpose-built patient seating systems engineered for clinical procedures, diagnostic examinations, and therapeutic interventions, typically incorporating adjustable height ranges, Trendelenburg positioning, and infection-control-rated upholstery seams. Their primary commercial purpose centers on optimizing clinician access angles while minimizing patient transfer risk during extended procedures. Recliners capture substantial margin pools in infusion therapy settings where extended dwell times justify premium electric configurations. Programming chairs represent the fastest-growing product type as robotic surgery expansion drives demand for integrated surgeon seating with memory-positioning capabilities. Manual technology segments remain mature in cost-constrained markets, though hydraulic systems face displacement by quieter electric actuators in new hospital construction.
FDA 510(k) clearance pathways shape electric chair market access timelines, while the EU Medical Device Regulation imposes clinical evidence requirements on powered patient positioning devices exported to Europe. OSHA ergonomic guidelines for healthcare workers indirectly drive specification standards for adjustable seating in US facilities. Stakeholders must monitor how cybersecurity mandates for connected medical devices reshape electric chair control system architectures and supplier qualification criteria.
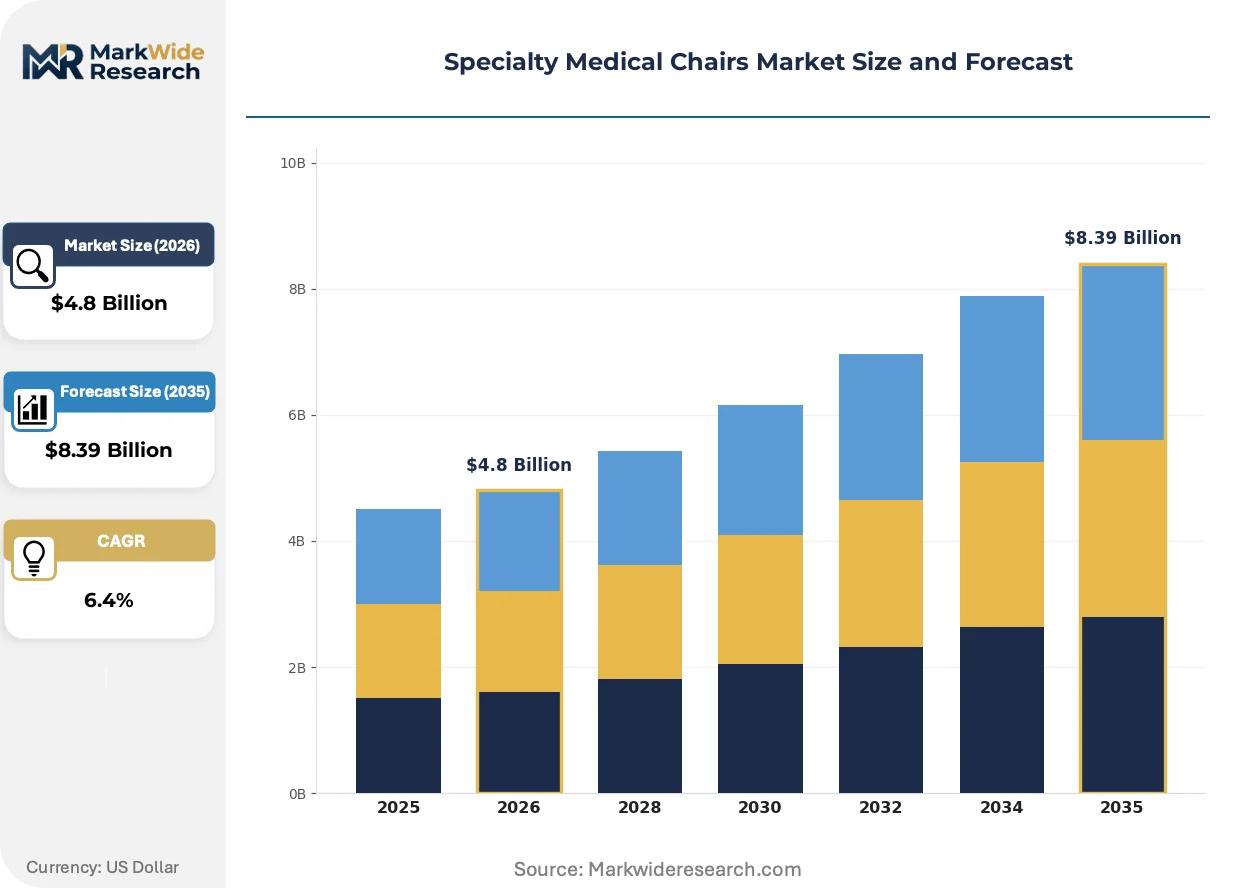
Market Dynamics
Powered positioning systems are displacing manual and hydraulic alternatives as ambulatory surgical centers scale procedural throughput and prioritize infection-control-rated upholstery seams in renovation specifications.
Growth Catalysts
- OSHA ergonomic guidelines:US healthcare facilities face compliance pressure to equip staff with adjustable seating, directly expanding specification standards for electric actuators in hospital construction.
- Robotic surgery expansion:Integrated surgeon seating with memory-positioning capabilities commands premium positioning in operating theater designs, pulling programming chair demand upward.
- Germany hospital modernization:Federal procurement programs prioritize ergonomic patient seating, concentrating European demand in this single national market.
Market Restraints
- Biomedical technician shortage:North American healthcare systems lack installation and maintenance capacity for complex electric chair fleets, extending deployment timelines.
- Steel and actuator cost volatility:Input price swings compress margin pools for manufacturers serving cost-constrained manual technology segments.
- EU MDR clinical evidence requirements:Powered patient positioning devices face extended market access timelines for European export certification.
Strategic Opportunities
- Outpatient infusion therapy:Extended dwell times in oncology and immunology clinics justify premium electric recliner configurations with programmable positioning.
- FDA cybersecurity guidance:Hardened electric chair control architectures create supplier qualification barriers that favor incumbents with compliance infrastructure.
- Architectural specification channel:Direct relationships with design firms enable early-stage influence over clinic renovation seating decisions.
Industry Challenges
- Field service technician scarcity:Complex electric actuator diagnostics require specialized training that outpaces vocational program output.
- Legacy hydraulic fleet compatibility:Electric replacement cycles face friction from sunk capital in existing clinic infrastructure.
- 510(k) clearance documentation:Substantial equivalence pathways demand extensive predicate device analysis, stretching regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Medical Chairs Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recliners, Stools, Transport Chairs, Programming Chairs End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Material: Vinyl, Leather, Fabric, Foam Technology: Manual, Electric, Hydraulic, Adjustable |
| Companies Covered | Dentsply Sirona, Danaher, Planmeca Oy, A-dec, Inc., Midmark Corp., Hill Laboratories Company, Fresenius Medical Care AG & Co. KGaA, DentalEZ, Inc., Topcon Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Medical Chairs Market Strategic Shifts & Innovations
Control system architectures are hardening against cyber intrusion while actuator mechanisms compress physical footprints. Clinical seating is converging with diagnostic imaging workflows.
Brushless DC motor arrays with integrated position feedback are miniaturizing. Ambulatory surgical centers specify these compact actuators for multi-axis positioning in space-constrained procedure rooms. Component volume reduction enables slimmer chair profiles without sacrificing load capacity or precision.
EU MDR post-market surveillance requirements now mandate systematic clinical follow-up for powered patient positioning devices. Manufacturers must maintain vigilance databases tracking device performance across European installations. Class IIa and IIb chair systems face heightened notified body scrutiny, compressing certificate renewal cycles.
After-sales service contracts are unbundling from equipment purchase agreements. Hospital procurement teams now negotiate uptime commitments and preventive maintenance separately from capital expenditure. This shift is most visible in US health system consolidation, where centralized supply chain offices demand standardized service level agreements across multi-facility electric chair fleets.
Specialty Medical Chairs Market Segmentation
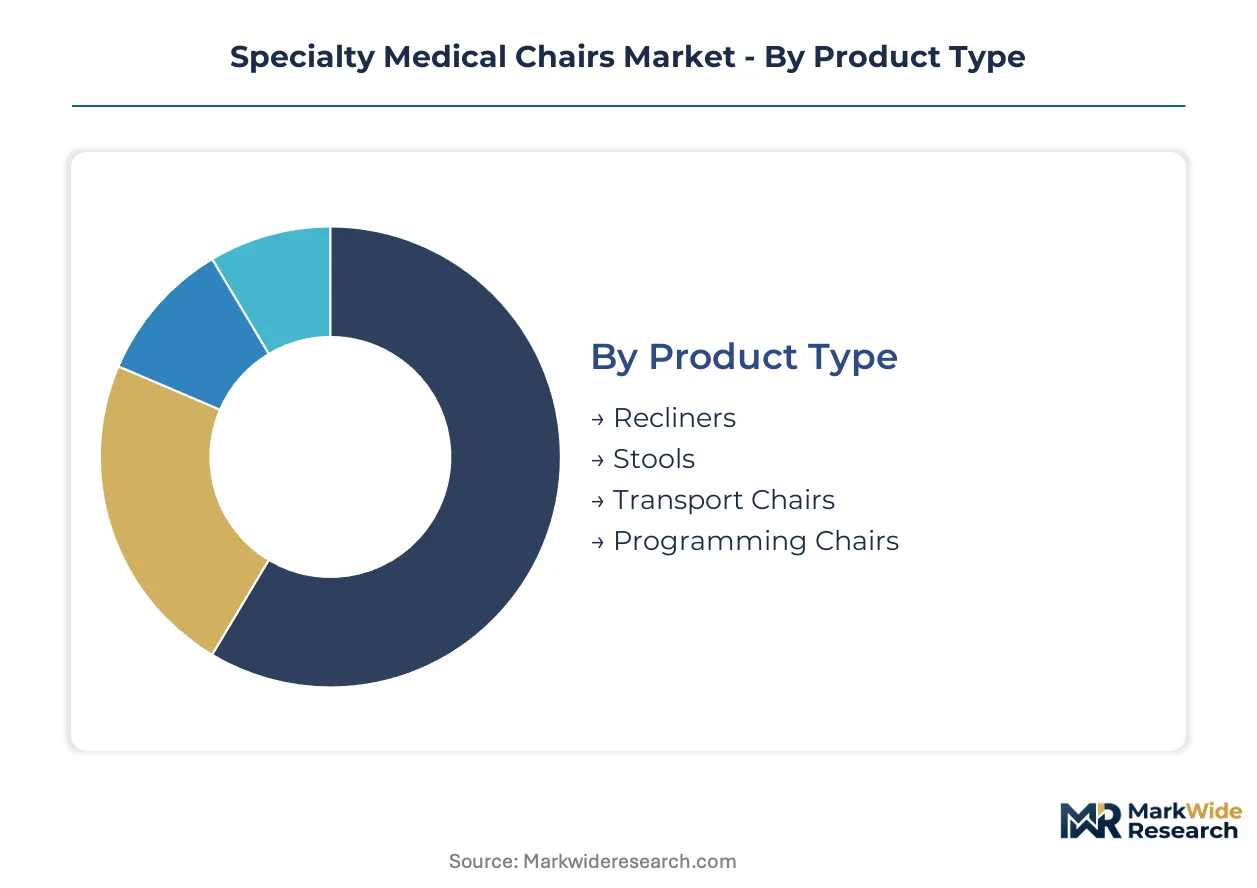
Segmentation in specialty medical chairs reveals how clinical workflow requirements reshape procurement patterns across care settings. Product configurations diverge sharply between high-throughput surgical environments and extended-dwell infusion therapy, while technology choices reflect capital availability and maintenance infrastructure.
Product Type:
Electric actuators and integrated positioning systems are displacing manual alternatives across multiple product categories, though substitution pressure varies by procedure complexity and dwell time economics.
- Recliners:Extended-dwell infusion therapy settings in oncology and immunology clinics specify these chairs with programmable positioning and infection-control-rated upholstery seams. Demand concentrates in US outpatient facilities where reimbursement structures justify premium electric configurations for patient comfort during multi-hour treatments.
- Programming Chairs:Integrated surgeon seating with memory-positioning capabilities serves robotic surgery expansion in operating theaters. German hospital modernization programs prioritize these systems for ergonomic clinician access during complex procedures.
- Stools:Compact seating for examination and minor procedure rooms.
- Transport Chairs:Mobile patient positioning systems for inter-facility movement.
Recliners retain volume leadership across installed base; programming chairs hold the steepest expansion curve.
End User:
Procurement authority and capital allocation cycles diverge meaningfully across institutional buyer types, with ambulatory settings outpacing acute care in electric chair refresh rates.
- Hospitals:Federal modernization programs in Germany and health system consolidation in the US drive specification of powered positioning systems with hardened cybersecurity architectures. Construction timelines extend due to biomedical technician shortages affecting installation capacity.
- Clinics:Ambulatory surgical centers scale procedural throughput with space-constrained multi-axis positioning chairs. Direct specification relationships with architectural firms shape early-stage renovation decisions.
- Home Care:Cost-constrained settings favor manual technology segments with simpler maintenance requirements.
- Rehabilitation Centers:Extended therapy sessions demand durable upholstery and adjustable height ranges for patient transfer safety.
Hospitals dominate capital expenditure volume; clinics are climbing the fastest on electric chair penetration.
Material:
Infection control protocols and cleaning cycle durability determine material selection, with regulatory pressure elevating performance standards beyond aesthetic considerations.
- Vinyl:Seam-sealed constructions rated for hospital-grade disinfectant protocols dominate acute care specifications. FDA cybersecurity guidance for connected devices indirectly influences material integration with sensor-enabled chair systems.
- Foam:Pressure-redistribution formulations serve extended-procedure seating in infusion and dialysis settings. German ergonomic procurement standards prioritize foam density specifications for patient comfort during prolonged immobility.
- Leather:Premium aesthetic configurations for executive health suites.
- Fabric:Breathable alternatives for lower-acuity examination environments.
Vinyl commands the broadest specification footprint; foam is gaining share fastest on pressure-injury prevention mandates.
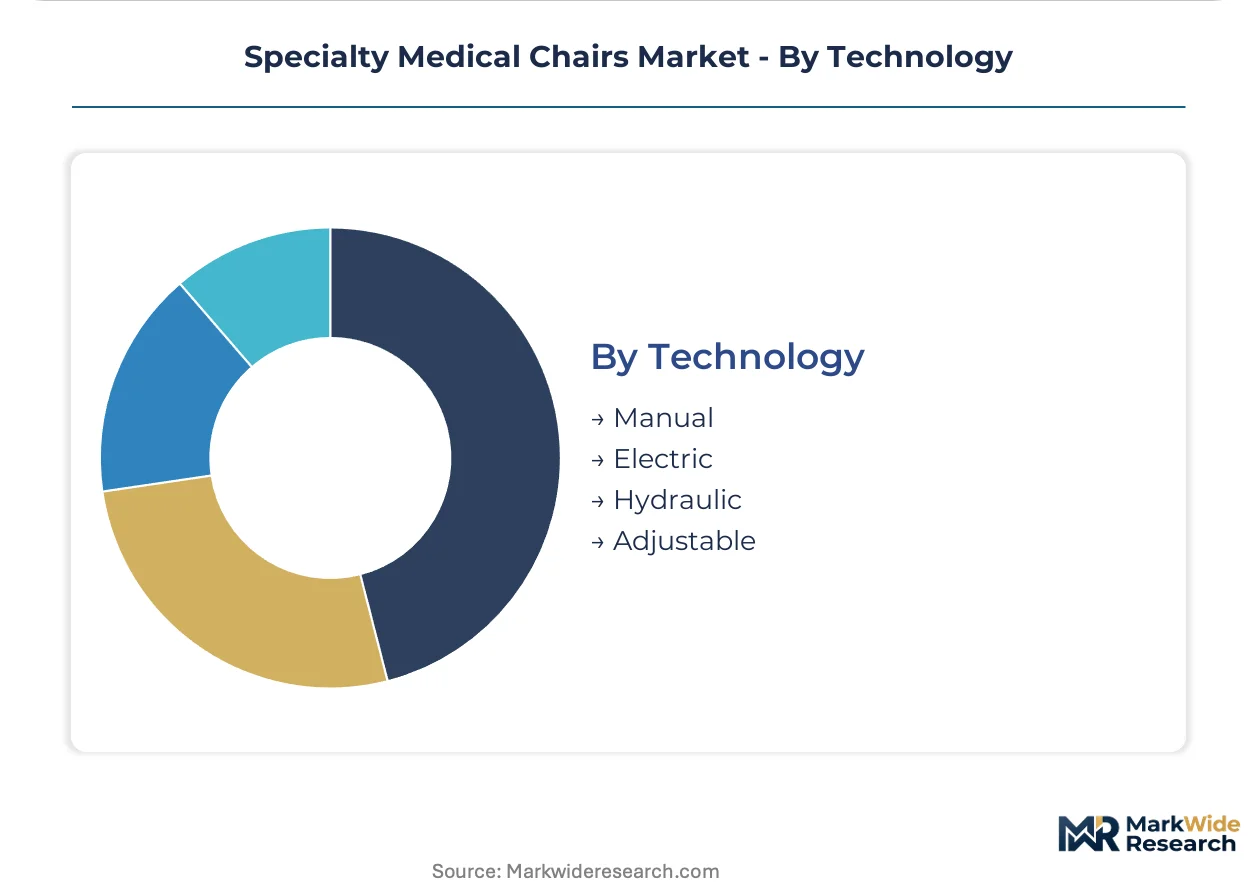
Technology:
Actuator mechanism selection reflects tradeoffs between precision positioning, acoustic profile, and total cost of ownership across facility types.
- Electric:Brushless DC motor arrays with integrated position feedback miniaturize physical footprints while maintaining load capacity. EU MDR clinical evidence requirements extend market access timelines for powered patient positioning devices exported to Europe.
- Manual:Mature technology segments persist in cost-constrained markets and legacy fleet replacement cycles. Hydraulic system compatibility friction slows displacement in existing clinic infrastructure.
- Hydraulic:Quieter operation than electric alternatives in select European installations.
- Adjustable:Hybrid configurations bridging fixed and powered positioning.
Electric systems lead new construction specifications; manual retains residual volume in replacement markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German procurement premiums for ergonomic patient seating exceed pricing floors in cost-constrained Southern European markets by substantial margins. This asymmetry concentrates manufacturer investment in federal modernization corridors while compressing margin pools elsewhere.
United States
Ambulatory surgical centers in Texas and Florida drive specification of powered positioning systems with hardened cybersecurity architectures. OSHA ergonomic guidelines for healthcare workers mandate adjustable seating in new hospital construction. The Dallas-Fort Worth medical district anchors installation capacity for complex electric chair fleets serving consolidated health systems.
Germany
Federal hospital modernization programs prioritize ergonomic patient seating with infection-control-rated upholstery seams in Bavaria and North Rhine-Westphalia. EU MDR clinical evidence requirements extend market access timelines for powered patient positioning devices. The Stuttgart industrial cluster hosts precision actuator manufacturing for programming chairs serving robotic surgery suites.
China
Public hospital renovation waves in Shanghai and Guangzhou accelerate displacement of manual technology segments by electric actuators. NMPA medical device registration pathways shape domestic market access timelines for powered seating systems. The Yangtze River Delta manufacturing base supplies brushless DC motor arrays for compact multi-axis positioning chairs.
Japan
Aging clinic infrastructure in Tokyo and Osaka drives replacement demand for quieter electric alternatives to legacy hydraulic systems. METI industrial standards influence precision positioning specifications for robotic surgery seating. The Nagoya medical device corridor concentrates post-market surveillance capabilities for EU MDR-compliant export manufacturing.
India
Private hospital chains in Maharashtra and Karnataka specify mid-tier electric configurations balancing cost constraints with infection control protocols. CDSCO medical device rules impose registration requirements on powered patient positioning equipment. The Hyderabad medical technology cluster assembles manual and hybrid seating for cost-constrained domestic and export markets.
Specialty Medical Chairs Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure with limited overlap. Premium-tier vendors concentrate on integrated positioning systems with memory-capability and cybersecurity-hardened architectures, while value-tier fabricators optimize manual and hybrid configurations for price-sensitive procurement channels. Two strategic archetypes dominate: full-service dental equipment conglomerates leveraging service infrastructure for uptime commitments, and clinical seating specialists capturing architectural specification influence. Competitive moves center on M&A for service network density and direct specification relationships with design firms.
Among North American equipment conglomerates, Dentsply Sirona and Danaher occupy positions that exemplify service-integrated competitive strategy, while Midmark Corp. anchors the specialist archetype focused on clinic renovation channels. These three entities represent distinct approaches to market access: dental equipment service leverage, life sciences R&D extension, and architectural specification capture respectively.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Danaher |
| Planmeca Oy |
| A-dec, Inc. |
| Midmark Corp. |
| Hill Laboratories Company |
| Fresenius Medical Care AG & Co. KGaA |
| DentalEZ, Inc. |
| Topcon Corp. |
| Others |
Cost & Logistics Intelligence
Brushless DC motor arrays replacing hydraulic actuators in new hospital construction are redrawing procurement geography toward East Asian electronics manufacturing corridors while compressing margin pools for European hydraulic component suppliers locked into legacy pricing contracts. This substitution dynamic concentrates actuator sourcing in the Yangtze River Delta and Nagoya industrial clusters, forcing incumbent chair manufacturers to renegotiate long-term supply agreements or absorb input cost volatility.
Pricing Analysis
German procurement premiums for ergonomic patient seating with infection-control-rated upholstery seams substantially exceed pricing floors in Southern European markets, creating a bifurcated European pricing landscape. Three-tier pricing structure across premium, standard, and economy levels separates integrated programming chairs with memory-positioning capabilities from basic electric recliners and residual manual configurations. Cost compression in the manual technology segment is intensifying because steel and actuator price volatility erodes fabricator margins serving price-sensitive home care buyers. Clinics and ambulatory surgical centers exhibit lowest price sensitivity due to reimbursement structures justifying premium electric configurations, while home care settings remain most price-constrained.
Supply Chain Analysis
Strategic stockpiling of brushless DC motor arrays and precision actuators dominates inventory strategy among tier-one chair manufacturers, contrasting with just-in-time upholstery material procurement from regional textile suppliers. Component manufacturing concentrates in China, Japan, and Germany, with the Yangtze River Delta feeding compact multi-axis positioning systems, Nagoya supplying precision feedback mechanisms, and Stuttgart anchoring high-load actuator assembly for robotic surgery seating. Raw material dependencies center on rare-earth magnets for motor efficiency, medical-grade vinyl for infection control compliance, and high-density foam formulations for pressure redistribution. Single-source vulnerability in rare-earth magnet processing creates structural supply chain risk. Distribution runs through hospital group purchasing organizations in consolidated US health systems and direct architectural specification channels in European clinic renovation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty medical chairs occupy an early-cycle expansion phase as ambulatory surgical center procedural throughput growth and robotic surgery suite construction create sustained demand pull for integrated positioning systems with hardened cybersecurity architectures.
For Market Incumbents: Fortify service network density through acquisition of regional biomedical technician training programs, addressing the North American installation capacity bottleneck that extends deployment timelines for complex electric chair fleets. Deepen backward integration into brushless DC motor assembly to capture margin pools currently flowing to East Asian electronics suppliers and insulate against rare-earth magnet price volatility. Prioritize FDA cybersecurity guidance compliance infrastructure as a supplier qualification barrier against emerging competitors lacking regulatory affairs bandwidth.
For New Entrants and Emerging Players: Differentiate on compact actuator miniaturization for space-constrained ambulatory surgical center procedure rooms, where incumbent footprint constraints create specification white space. Target the US outpatient infusion therapy channel, where extended dwell times in oncology and immunology clinics justify premium electric recliner configurations and architectural specification relationships remain less entrenched than in hospital construction. Pursue direct partnerships with clinic renovation design firms as the primary go-to-market angle, securing early-stage influence over seating decisions before incumbent specification capture.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed clinical seating specialists holding architectural specification relationships but lacking integrated service infrastructure for uptime commitments. The five-to-ten-year viability window favors platforms combining manufacturing scale with preventive maintenance contract capabilities, as after-sales service unbundling from equipment purchase agreements accelerates across US health system consolidation. Acquisition targets should display dense regional service technician networks and EU MDR compliance infrastructure for European export manufacturing. Watch FDA enforcement patterns on medical device cybersecurity as the signal for supplier qualification barrier intensity and incumbent moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct specification relationships with consolidated US health systems lock in multi-facility fleet commitments. |
| FDA Cybersecurity Compliance Investment | Hardened electric chair control architectures create supplier qualification barriers favoring incumbents with regulatory infrastructure. |
| Biomedical Technician Training Acquisition | Installation and maintenance capacity constraints in North America extend deployment timelines for complex electric chair fleets. |
| CE Marking Pathway Acceleration | EU MDR clinical evidence requirements compress certificate renewal cycles for powered patient positioning devices. |
| Software Companion Development | Memory-positioning capabilities for programming chairs integrate with robotic surgery workflow systems. |
Research Approach
A spread of perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ambulatory surgical center administrators converged on the working assumptions shaping this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, EU MDR notified body documentation, hospital procurement records, and ambulatory surgery center construction permits. Bottom-up triangulation across product type, end user, material, and technology segmentation dimensions anchored volume estimates, while top-down cross-checks against health system capital expenditure disclosures validated value projections.
Segmentation dimensions modeled span product configuration, institutional buyer type, upholstery material grade, and actuator technology across the projection horizon. CAGRs derived from procedure volume growth trajectories in ambulatory settings, hospital modernization program allocations, and replacement cycle dynamics for legacy hydraulic fleets. Industry-specific forecast inputs include OSHA ergonomic guideline compliance timelines, robotic surgery suite construction pipelines, and EU MDR certificate renewal cycle compression effects on powered patient positioning device market access.
Material uncertainties — biomedical technician training program output shortfalls, rare-earth magnet supply disruptions, and FDA cybersecurity enforcement intensity escalation — sit outside the modeled envelope. Forecasts reflect assumptions on substitution rates from hydraulic to electric actuators and ambulatory surgical center penetration curves. Revision becomes warranted when health system consolidation pace or EU MDR notified body capacity constraints cross thresholds that alter equipment procurement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Skin Cooling Systems Market
Healthcare Equipment
Global Hospital Asset Management Market
Healthcare Equipment
Medical Cold Storage Market
Healthcare Equipment
Ophthalmic Examination Chairs Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
Microbiological Safety Cabinets Market
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
Clinical Mobility Market
Healthcare Equipment
Medical Chairs Market