
 Medical Chairs Market | 2026-2036
Medical Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Chairs Market Foresight
Hospital supply chains is narrowing as group purchasing organizations consolidate vendor panels for durable medical equipment. Midmark Corp. anchors North American distribution through direct sales teams serving integrated delivery networks. Fresenius Medical Care AG & Co. KGaA dominates dialysis chair procurement through captive clinic networks. Dentsply Sirona controls dental chair specification at the dealer level, leveraging bundled digital imaging contracts.
Medical chairs are powered and non-powered seating devices designed for patient examination, treatment, transport, or extended therapeutic use, typically incorporating adjustable height, recline articulation, and load-rated frames supporting patients from 300 to 600 lbs. Electric variants integrate actuator-driven positioning with programmable presets for bariatric, surgical, and imaging applications. Procedure chairs and dental chairs lead value generation due to higher electromechanical content and specialized infection-control surfaces. Manual and hydraulic technologies retain share in price-sensitive home care and emerging clinic segments where power infrastructure is limited.
The FDA regulates powered medical chairs as Class II devices under 510(k) premarket notification, while the EU MDR requires notified body conformity assessment for motorized patient positioning equipment with new clinical evaluation obligations. ISO 13485 quality management and IEC 60601-1 electrical safety standards govern manufacturing and design verification for export markets. Stakeholders must monitor evolving cybersecurity guidance for connected chairs and prepare for state-level bariatric accessibility mandates affecting weight capacity specifications.
Market Dynamics
Group purchasing organization consolidation is compressing vendor margins and forcing manufacturers to absorb certification costs while maintaining bariatric weight ratings above 450 lbs.
Growth Catalysts
- EU MDR reclassification:Stricter conformity assessment for motorized patient positioning equipment is accelerating replacement of legacy manual chairs in German and French outpatient networks.
- Ambulatory surgical center expansion:Outpatient clinics in the United States are standardizing powered examination chairs with programmable presets for same-day discharge protocols.
- Actuator miniaturization:Compact electromechanical drives enable multi-articulation designs without hydraulic fluid maintenance, opening adoption in space-constrained Japanese dialysis facilities.
Market Restraints
- Stainless steel price volatility:Load-rated frame fabrication depends on alloy grades subject to commodity swings, squeezing margin on economy-tier manual chairs.
- Notified body bottlenecks:EU MDR clinical evaluation backlogs extend time-to-market for new powered chair submissions beyond eighteen months.
- Home care substitution:Recliner-style lift chairs from consumer furniture suppliers capture price-sensitive geriatric demand outside clinical reimbursement pathways.
Strategic Opportunities
- Indian diagnostic clinic buildout:Tier-2 and Tier-3 cities lack powered examination infrastructure, creating first-mover positioning for mid-range electric models with battery backup.
- Cybersecurity guidance convergence:FDA draft guidance on connected device vulnerability management creates service revenue streams for firmware update subscriptions.
- Brazilian ANVISA fast-track:Streamlined registration for Class II patient positioning devices reduces entry barriers for manufacturers with existing ISO 13485 certification.
Industry Challenges
- IEC 60601-1 Edition 3.2 compliance:Third-edition electrical safety testing requires specialized EMC laboratories, constraining in-house verification capabilities.
- Legacy hospital IT integration:New chairs with HL7 connectivity must interface with decades-old nurse call systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Chairs Market |
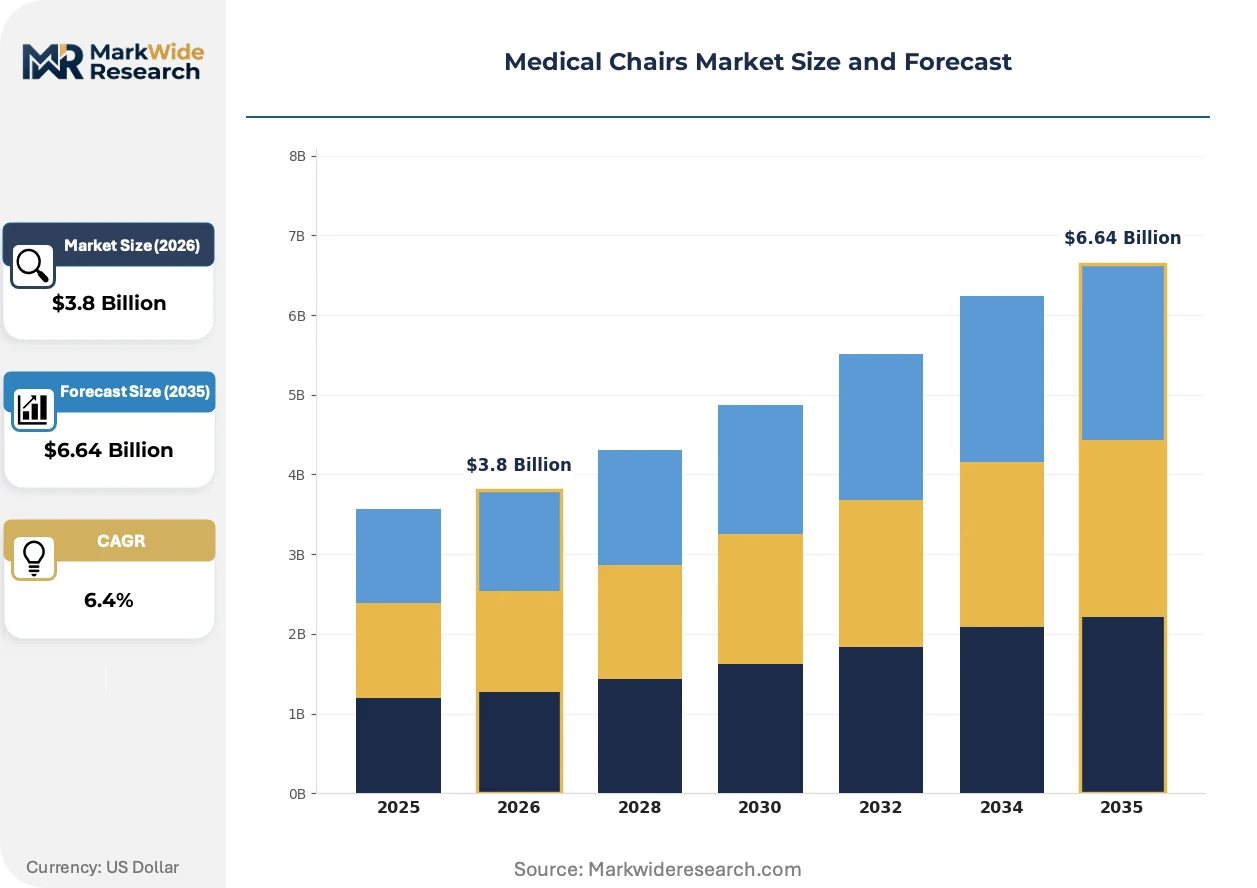
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Examination Chairs, Transfer Chairs, Procedure Chairs, Dental Chairs End User: Hospitals, Outpatient Clinics, Home Care, Rehabilitation Centers Technology: Electric, Manual, Hydraulic, Pneumatic Weight Capacity: 300 lbs, 400 lbs, 600 lbs, Others |
| Companies Covered | Dentsply Sirona, Midmark Corp., Fresenius Medical Care AG & Co. KGaA, Planmeca Oy, A-dec, Inc., Danaher, Baxter, Invacare Corporation, Winco Mfg. LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Chairs Market Shifts & Advancements
Electromechanical actuation and infection-control surface chemistry are converging to redefine durability standards across examination, procedure, and long-term therapeutic seating categories.
Brushless DC actuator systems with integrated position feedback are eliminating hydraulic fluid reservoirs and manual pump mechanisms from mid-range examination chairs. United States outpatient surgery centers are specifying these configurations for same-day turnover efficiency. The technology is rendering obsolete maintenance-intensive hydraulic lift systems that dominated procurement through 2020.
EU MDR Annex XVI expansion reclassifies motorized patient positioning equipment with sustained patient contact as higher-risk devices, mandating clinical evaluation reports from notified bodies. German and Dutch manufacturers are absorbing extended conformity assessment timelines into product development roadmaps. Dental chair suppliers with existing 510(k) clearances face parallel documentation burdens for European market access.
Integrated delivery networks are consolidating durable medical equipment procurement through single-source contracts spanning examination, procedure, and transport categories. Dealer networks that historically sold standalone dental chairs are losing specification influence to direct manufacturer relationships with supply chain officers. This concentration is most advanced in United States health systems with centralized capital equipment committees.
Medical Chairs Market Segmentation
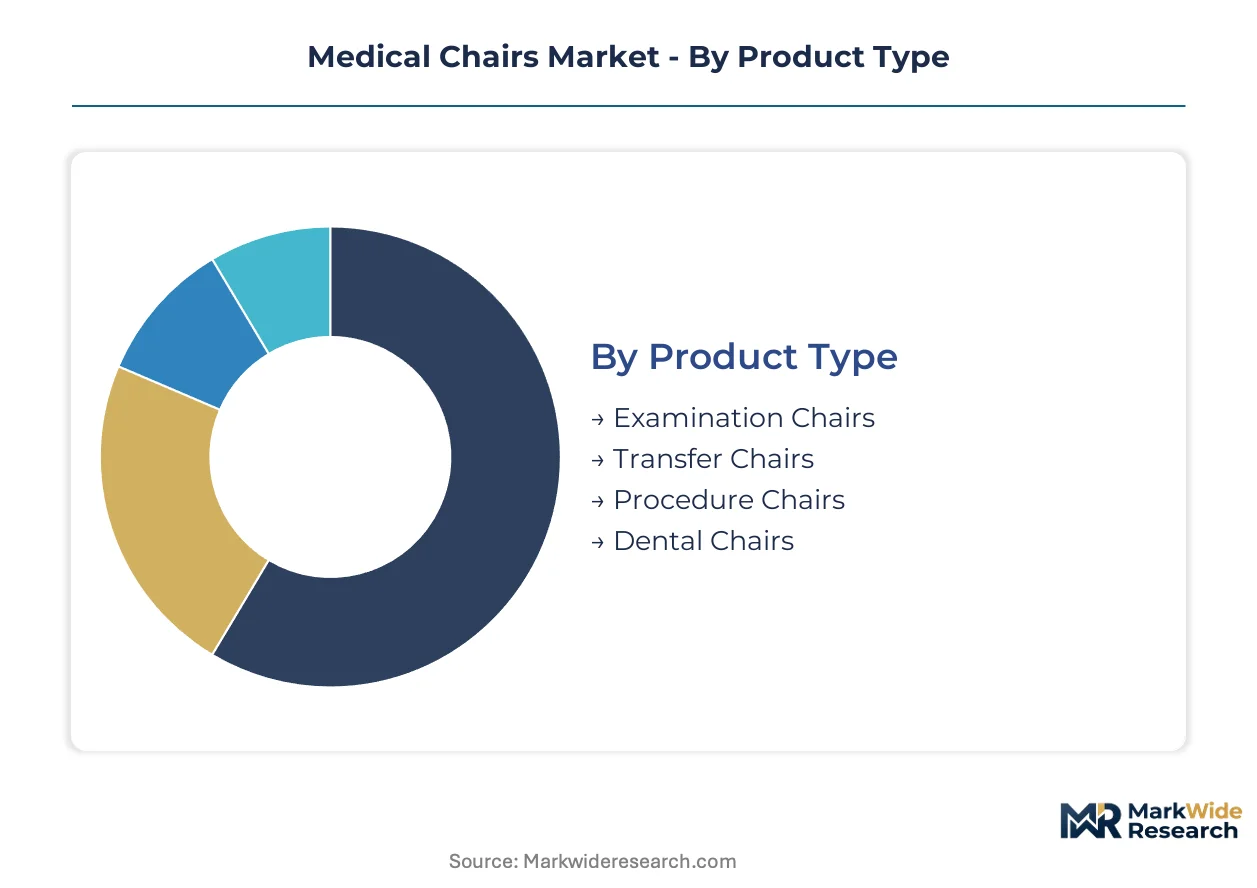
Medical chairs serve distinct clinical workflows ranging from rapid patient turnover in ambulatory settings to extended therapeutic positioning in rehabilitation. Segmentation reveals how electromechanical sophistication, care setting economics, and patient anthropometrics reshape procurement priorities across healthcare infrastructure.
Product Type:
Mature examination platforms coexist with emerging multi-articulation designs as outpatient networks modernize.
- Examination Chairs:Height-adjustable platforms with manual or electric backrest articulation dominate primary care procurement in the United States and Germany. Outpatient clinic expansion drives specification of models with programmable presets for same-day discharge protocols.
- Procedure Chairs:Multi-position electromechanical systems with Trendelenburg and lithotomy positioning support surgical workflows in ambulatory surgical centers. FDA 510(k) clearance requirements for powered patient positioning elevate barrier to entry for new suppliers.
- Transfer Chairs:Mobile wheeled frames with collapsible armrests facilitate lateral patient movement between departments. Manual variants retain share in budget-constrained facilities where electric actuation is non-essential.
- Dental Chairs:Integrated patient positioning with delivery system mounting dominates dental clinic capital budgets. Bundled digital imaging contracts at the dealer level concentrate specification influence with incumbent suppliers.
Examination chairs retain volume leadership; procedure chairs hold the steepest expansion curve.
End User:
Customer concentration varies by reimbursement pathway and capital equipment renewal cycles.
- Hospitals:Integrated delivery networks consolidate procurement through centralized capital committees spanning examination, procedure, and transport categories. Group purchasing organization vendor panel consolidation compresses supplier margins on mid-range electric models.
- Outpatient Clinics:Ambulatory surgical centers in the United States standardize powered chairs with programmable presets. EU MDR reclassification of motorized patient positioning equipment accelerates replacement of legacy manual inventory in German networks.
- Home Care:Recliner-style lift chairs from consumer furniture suppliers capture price-sensitive geriatric demand outside clinical reimbursement pathways. Battery backup specifications gain traction where residential power reliability is inconsistent.
- Rehabilitation Centers:Bariatric-rated frames supporting 450+ lbs address patient populations in long-term therapeutic settings. Extended dwell times demand infection-control surface chemistry and pressure-relief cushioning.
Hospital procurement generates the largest absolute revenue; outpatient clinics are expanding most quickly.
Technology:
Actuator miniaturization is displacing hydraulic fluid systems across mid-range applications.
- Electric:Brushless DC actuators with integrated position feedback eliminate maintenance-intensive hydraulic reservoirs. United States outpatient surgery centers specify these configurations for turnover efficiency.
- Manual:Hand-crank height adjustment and mechanical backrest articulation retain procurement share in emerging clinic segments and price-sensitive home care markets.
- Hydraulic:Foot-pump lift mechanisms dominated procurement through 2020 but face displacement as electromechanical costs decline. Fluid maintenance requirements burden operational budgets in high-turnover settings.
- Pneumatic:Compressed gas positioning systems serve niche applications requiring rapid height adjustment without electrical infrastructure. Limited adoption outside specialized surgical environments.
Electric systems command the premium tier; hydraulic retains residual volume in replacement markets.
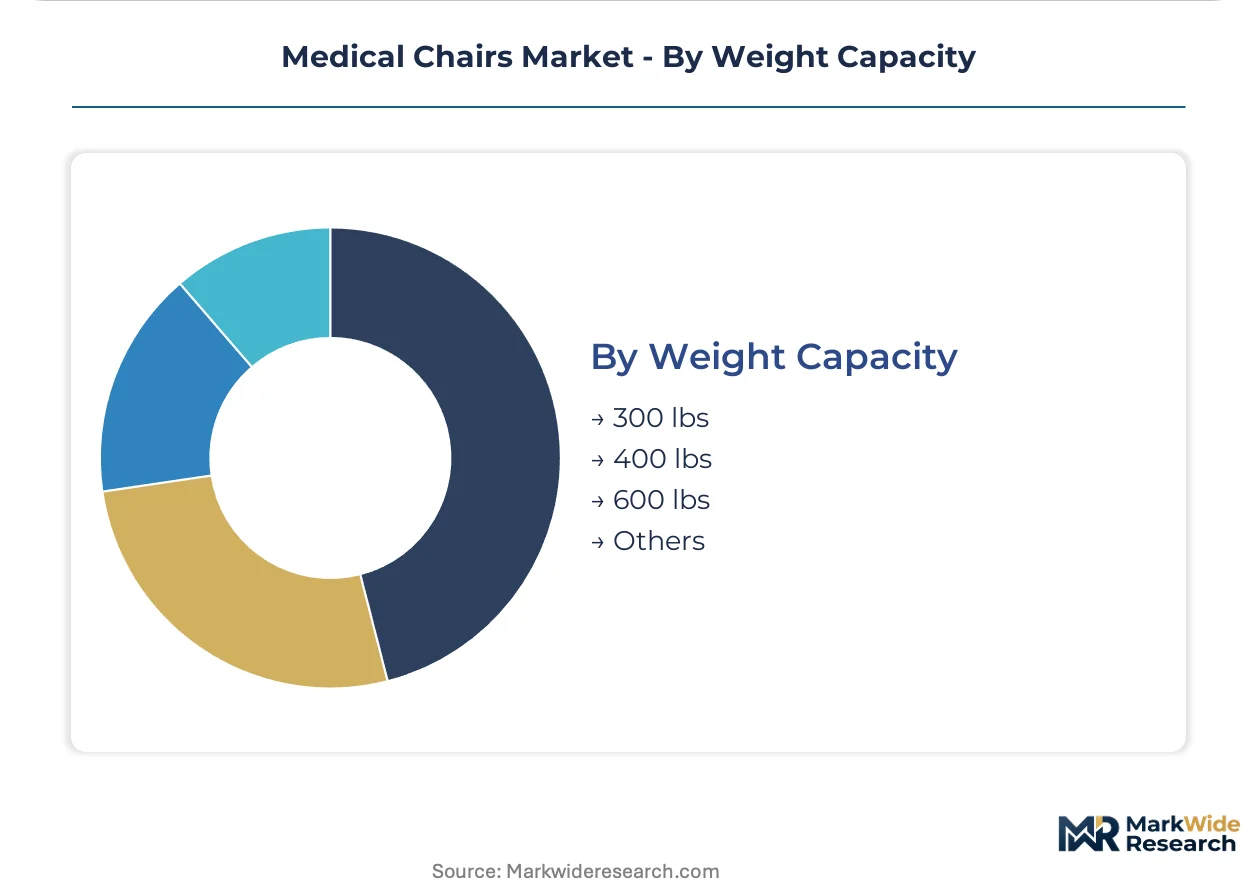
Weight Capacity:
Bariatric accessibility mandates at state level reshape specification minimums.
- 300 lbs:Standard-duty frames serve general patient populations in primary care and routine examination settings. Volume concentration in manual and economy-tier electric configurations.
- 400 lbs:Reinforced frame fabrication with upgraded actuator ratings addresses overweight patient demographics. German and Dutch outpatient networks specify this threshold as procurement minimum.
- 600 lbs:Heavy-duty bariatric designs with distributed load frames and wider seating surfaces serve rehabilitation and long-term care. Stainless steel alloy grades subject to commodity price volatility squeeze margins.
- Others:Custom and pediatric specifications address outlier anthropometric requirements. Limited standardization constrains supplier economies of scale.
400-lb specifications are gaining share fastest; 300-lb frames retain volume leadership in price-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital infrastructure renewal programs and aging demographics are accelerating replacement cycles across developed healthcare systems. Regulatory tightening through FDA 510(k) updates and EU MDR reclassification is reshaping procurement standards. Demand concentrates where ambulatory surgical volumes and outpatient clinic expansion intersect with reimbursement stability.
United States
Ambulatory surgical centers are standardizing powered examination chairs with programmable presets for same-day discharge protocols. The FDA's updated 510(k) pathway for powered medical furniture tightens premarket notification requirements. Integrated delivery networks in the Midwest and Southeast are consolidating durable medical equipment procurement through centralized capital committees.
Germany
Outpatient networks are accelerating replacement of legacy manual chairs due to EU MDR reclassification of motorized patient positioning devices. The country's notified bodies face extended conformity assessment backlogs stretching time-to-market beyond eighteen months. Medical technology clusters in Baden-Württemberg and Bavaria host manufacturers absorbing certification costs into development roadmaps.
Japan
Actuator miniaturization is enabling multi-articulation designs for space-constrained dialysis facilities serving aging patient populations. METI guidelines on medical device quality management align with international standards for export-oriented manufacturers. Tokyo and Osaka metropolitan areas concentrate procurement from domestic suppliers with established distribution to clinic networks.
India
Tier-2 and Tier-3 cities lack powered examination infrastructure, creating first-mover positioning for mid-range electric models with battery backup specifications. CDSCO medical device rules require registration for Class A and B patient positioning equipment. Diagnostic clinic buildout in Maharashtra and Karnataka is driving demand for examination chairs outside traditional hospital procurement channels.
Brazil
ANVISA fast-track registration for Class II patient positioning devices reduces entry barriers for manufacturers with existing ISO 13485 certification. Private hospital groups in São Paulo and Rio de Janeiro are upgrading procedure chair fleets to support ambulatory surgical expansion. Reimbursement pathway uncertainty in the public SUS system limits procurement volume relative to private sector investment.
Medical Chairs Market Competitive Landscape
On the supply side, the industry is consolidating around direct manufacturer relationships with supply chain officers while dealer networks lose specification influence. Group purchasing organization vendor panel compression is squeezing margins and forcing certification cost absorption. Two strategic archetypes dominate: integrated medical equipment conglomerates with captive distribution, and specialized seating fabricators with regional manufacturing footprints. Competitive moves center on strategic partnerships with integrated delivery networks and portfolio diversification across examination, procedure, and transport categories.
Among North American equipment specialists, Midmark Corp. and Invacare Corporation exemplify contrasting scale positions within the durable medical equipment archetype. Fresenius Medical Care AG & Co. KGaA occupies a distinctive position through captive clinic network distribution in dialysis chair procurement. Dentsply Sirona represents the dental-focused archetype where bundled digital imaging contracts concentrate specification influence at the dealer level. These three anchors illustrate how distribution control and vertical integration into clinical workflows separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Midmark Corp. |
| Fresenius Medical Care AG & Co. KGaA |
| Planmeca Oy |
| A-dec, Inc. |
| Danaher |
| Baxter |
| Invacare Corporation |
| Winco Mfg. LLC |
| Others |
Supply & Pricing Matrix
Stainless steel price volatility for load-rated frame alloys determines both the compression of economy-tier margins and the geographic clustering of fabrication capacity around German and Japanese specialty metal suppliers. This commodity exposure forces manufacturers to absorb certification costs while maintaining bariatric ratings, creating tiered spreads that separate FDA-cleared powered systems from manual alternatives.
Pricing Analysis
Certification level creates the primary spread between premium FDA 510(k)-cleared powered chairs and economy-tier manual alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 quality grade, EU MDR conformity burden, and after-sales service bundling. Cost compression in the economy tier is intensifying because group purchasing organizations are consolidating vendor panels and squeezing supplier margins. Home care segments exhibit the highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over unit price.
Supply Chain Analysis
Contract manufacturing for electromechanical actuators concentrates with specialized motion control suppliers in Germany, Japan, and Taiwan. Frame fabrication draws from stainless steel alloy suppliers in Baden-Württemberg and Osaka prefectures, while infection-control surface materials source from chemical coating specialists in the United States and Netherlands. Single-source vulnerability for brushless DC actuator controllers creates procurement risk for mid-range electric chair assemblers. Distribution runs through direct manufacturer relationships with hospital supply chain officers, bypassing traditional dealer networks in consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR reclassification of motorized patient positioning equipment is accelerating a technology disruption that favors electromechanical over hydraulic systems. This regulatory inflection compresses time-to-market for new entrants while forcing incumbents to absorb extended conformity timelines.
For Market Incumbents: Insulate specification influence by deepening direct relationships with integrated delivery network supply chain officers before dealer networks lose remaining procurement access. Invest in captive ISO 13485-certified fabrication capacity to control certification cost absorption and defend margin position against group purchasing organization compression. Prioritize firmware update subscription services as recurring revenue buffers against hardware margin erosion.
For New Entrants and Emerging Players: Build out battery-backed electric examination chair distribution in Tier-2 and Tier-3 Indian cities where powered infrastructure is underpenetrated and CDSCO registration creates first-mover positioning. Target Brazilian private hospital groups leveraging ANVISA fast-track pathways for Class II devices. Lead with mid-range pricing and local service partnerships rather than premium feature sets.
For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors manufacturers with existing notified body relationships and MDR technical documentation libraries. Acquisition targets should demonstrate cleared 510(k) portfolios and established GPO contracts. Watch EU notified body backlog resolution as the signal for competitive positioning inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates market access for motorized positioning devices in German outpatient networks. |
| Hospital System Direct Partnership | Bypasses dealer intermediaries and secures multi-year capital equipment contracts with IDNs. |
| Actuator Controller Firmware Platform | Creates recurring revenue streams through cybersecurity update subscriptions per FDA guidance. |
| Battery Backup Specification Development | Opens diagnostic clinic penetration in Indian Tier-2 cities with unreliable power infrastructure. |
| Bariatric Frame Alloy Sourcing Agreement | Locks stainless steel supply commitments to hedge commodity volatility squeezing margins. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and outpatient clinic operations directors and refined through secondary validation. Primary fieldwork combined structured interviews with supply chain officers at integrated delivery networks and dialysis clinic procurement leads. Secondary sources encompassed FDA 510(k) clearance databases, EU MDR notified body submission records, hospital capital equipment procurement databases, and CMS Medicare durable medical equipment claims data. Bottom-up unit demand modeling was triangulated against top-down healthcare infrastructure spending projections.
Demand-supply balance across the projection horizon anchored the analytical framework, with segmentation across product type, end user, technology, weight capacity, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to replacement cycle timing and ambulatory surgical volume expansion. Industry-specific forecast inputs included EU MDR implementation timelines, FDA cybersecurity guidance progression, and bariatric accessibility mandate adoption at state level.
Stress conditions across stainless steel alloy price bands, notified body assessment backlogs, and group purchasing organization consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement stability and ambulatory surgical center buildout rates. Quarterly review of EU MDR clinical evaluation queue depths and GPO vendor panel compression announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
Healthcare Personal Protection Equipment Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
Global Hospital Asset Management Market
Healthcare Equipment
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Middle East and Africa Ultrasound Probe Disinfection Market
Healthcare Equipment
Skin Cooling Systems Market
Healthcare Equipment
Medical Cold Storage Market
Healthcare Equipment
Ophthalmic Examination Chairs Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
Medical Waste Supervision Solution Market