
 Skin Cooling Systems Market | 2026-2036
Skin Cooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Cooling Systems Market Analytics
Multi-source procurement for cryogenic compressors is repositioning how OEMs secure thermal core components. Zimmer MedizinSystems leverages captive European manufacturing to sustain margin control across its device portfolio. Cryonic Medical anchors its competitive stance through specialized R&D in compact cold-air delivery systems. Vacuactivus competes aggressively on price in the portable segment while navigating distributor fragmentation across Eastern Europe.
Skin cooling systems are electromechanical or cryogenic devices engineered to reduce epidermal temperature to between 4°C and 20°C prior to laser, surgical, or aesthetic interventions, thereby preventing thermal injury to surrounding tissue and improving patient comfort. The systems employ closed-loop refrigeration circuits, pressurized gas expansion, or thermoelectric Peltier modules to achieve controlled cooling rates measured in degrees per second. Active systems dominate installed base value due to their precision and reusability, while portable units represent the fastest-expanding demand category as ambulatory clinics prioritize space-efficient equipment. Electric cooling technology leads in hospital procurement specifications, whereas cryogenics commands premium positioning in high-throughput dermatology centers where rapid temperature drop-off remains clinically essential.
FDA 510(k) clearance requirements and the EU Medical Device Regulation (MDR) impose substantiation burdens on cryogenic device manufacturers seeking market access in the United States and Europe. ISO 13485 quality management certification functions as a baseline qualification for contract manufacturers serving branded OEMs in this sector. The convergence of MDR technical documentation demands with state-level laser device regulations in Texas and California creates a complex compliance landscape that procurement teams must map before vendor selection. Stakeholders should monitor how cooling efficacy claims become standardized under evolving clinical evidence requirements.
Market Dynamics
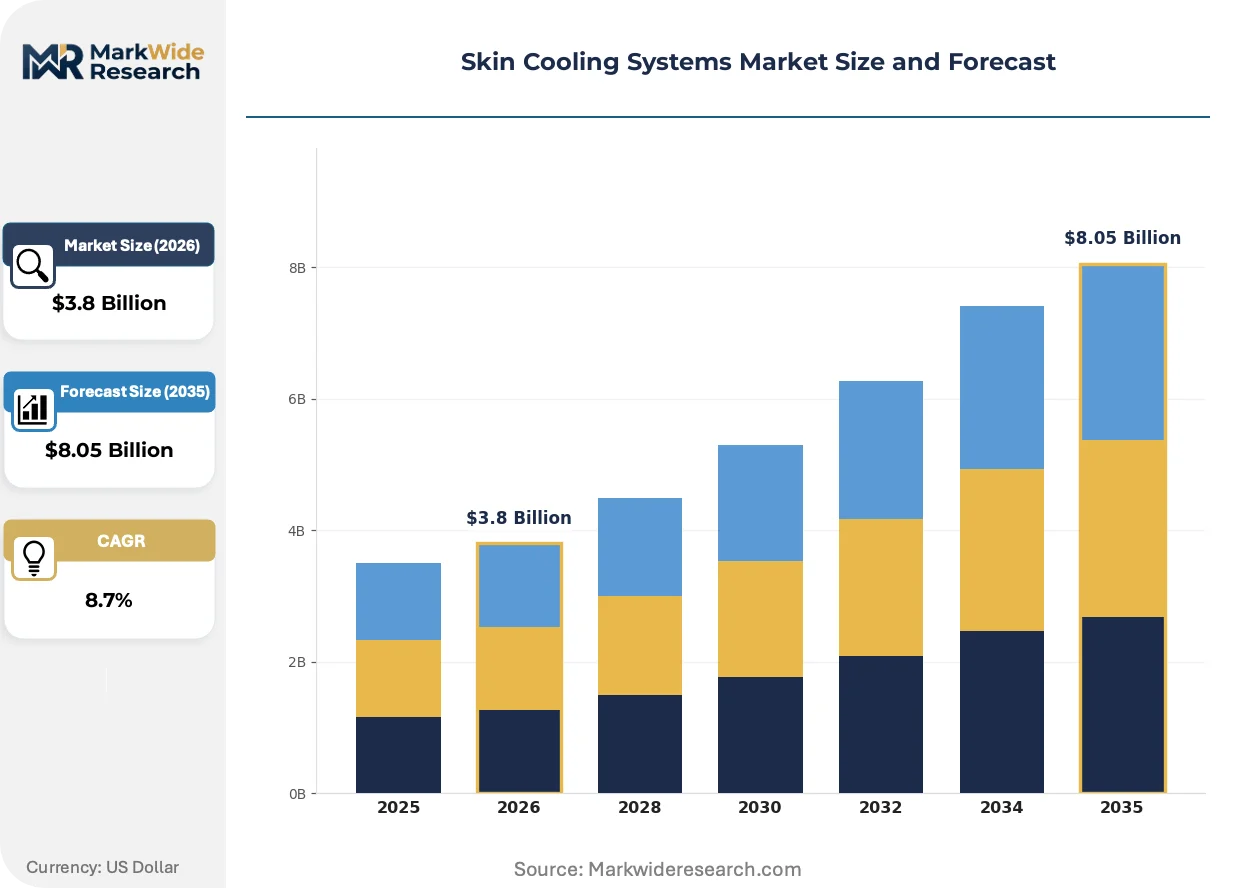
The skin cooling systems market is reconfiguring around the tension between cryogenic precision and thermoelectric modularity, as OEMs face procurement pressure to diversify compressor sourcing while aesthetic chains demand faster patient throughput protocols.
Growth Catalysts
- Pre-treatment cooling protocols:Aesthetic clinic chains in Seoul and Dubai are mandating standardized epidermal cooling before laser interventions, expanding installed base requirements across high-volume dermatology centers.
- FDA 510(k) clearance pathway:The streamlined regulatory route for cryogenic devices accelerates product entry timelines, reducing time-to-revenue for manufacturers targeting US dermatology equipment procurement.
- Thermoelectric Peltier modules:Advances in solid-state cooling efficiency are enabling compact portable units that satisfy ambulatory clinic space constraints without cryogenic infrastructure.
Market Restraints
- Helium supply concentration:Cryogenic device manufacturers depend on concentrated helium extraction from Qatar and the US strategic reserve, exposing margin stability to geopolitical supply disruptions.
- EU MDR technical documentation:The expanded clinical evidence requirements for cryogenic medical devices under the 2017/745 regulation impose substantiation costs that disadvantage smaller OEMs.
- Thermoelectric performance ceiling:Peltier systems face fundamental COP limitations below 10°C, restricting their penetration in high-throughput settings requiring rapid temperature drop-off.
Strategic Opportunities
- Home-use aesthetic devices:Post-pandemic consumer comfort with at-home laser hair removal is creating demand for compact, consumer-grade cooling attachments previously confined to clinical settings.
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing of precision cooling components offer tariff-advantaged supply chain repositioning for global OEMs.
- AI-integrated temperature control:Machine learning algorithms for predictive epidermal thermal mapping are converging with cooling hardware to enable personalized intervention protocols.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in pressurized gas expansion systems and closed-loop refrigeration circuits concentrates in Germany's industrial clusters, constraining OEM expansion.
- Legacy laser device integration:Cooling system retrofits for installed base CO2 and Nd:YAG lasers require proprietary interface protocols that fragment procurement standardization.
- ISO 13485 certification timelines:Contract manufacturers face extended audit backlogs for quality management certification, delaying OEM vendor qualification for MDR-compliant supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Cooling Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Systems, Passive Systems, Portable Units, Fixed Units Application: Dermatology Procedures, Aesthetic Treatments, Pain Management, Surgical Procedures End User: Hospitals, Clinics, Home Care, Research Laboratories Technology: Cryogenics, Electric Cooling, Water Circulation, Gel Pads |
| Companies Covered | Zimmer MedizinSystems, Cryonic Medical, Vacuactivus, Zamar care, Aussie Medi Tech, METRUM CRYOFLEX, Sanhe Beauty S & T, The Global Beauty Group, Vertex Lasers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Cooling Systems Market Evolving Landscape
Active cooling architectures are fragmenting into modality-specific configurations as dermatology chains prioritize patient throughput metrics over capital equipment standardization, while regulatory convergence between FDA and EU MDR frameworks is compressing differentiation timelines.
Thermoelectric Peltier arrays with enhanced semiconductor junction materials are overtaking traditional compressor-based systems in the portable segment. Ambulatory clinic networks in Germany and South Korea are adopting these solid-state units for space-constrained treatment rooms. The technology is overtaking cryogenic alternatives in sub-15°C applications by eliminating gas handling infrastructure and reducing maintenance intervals.
The EU Medical Device Regulation's expanded clinical evidence requirements for cryogenic devices are forcing manufacturers to generate prospective cooling efficacy data. This policy shift elevates documentation costs for market access but creates competitive moats for firms with established post-market surveillance infrastructure. High-throughput dermatology centers in Spain and Italy are responding by consolidating procurement around MDR-certified OEMs with verified technical files.
After-sales service unbundling is disrupting traditional equipment leasing models in the aesthetic device channel. Clinic operators in Dubai and São Paulo are separating cooling hardware acquisition from maintenance contracts, favoring modular component suppliers over integrated system vendors. This behavioral shift is most visible in Brazil's independent dermatology practices, where procurement teams now negotiate cooling module replacement cycles independently from laser platform service agreements.
Skin Cooling Systems Market Segmentation
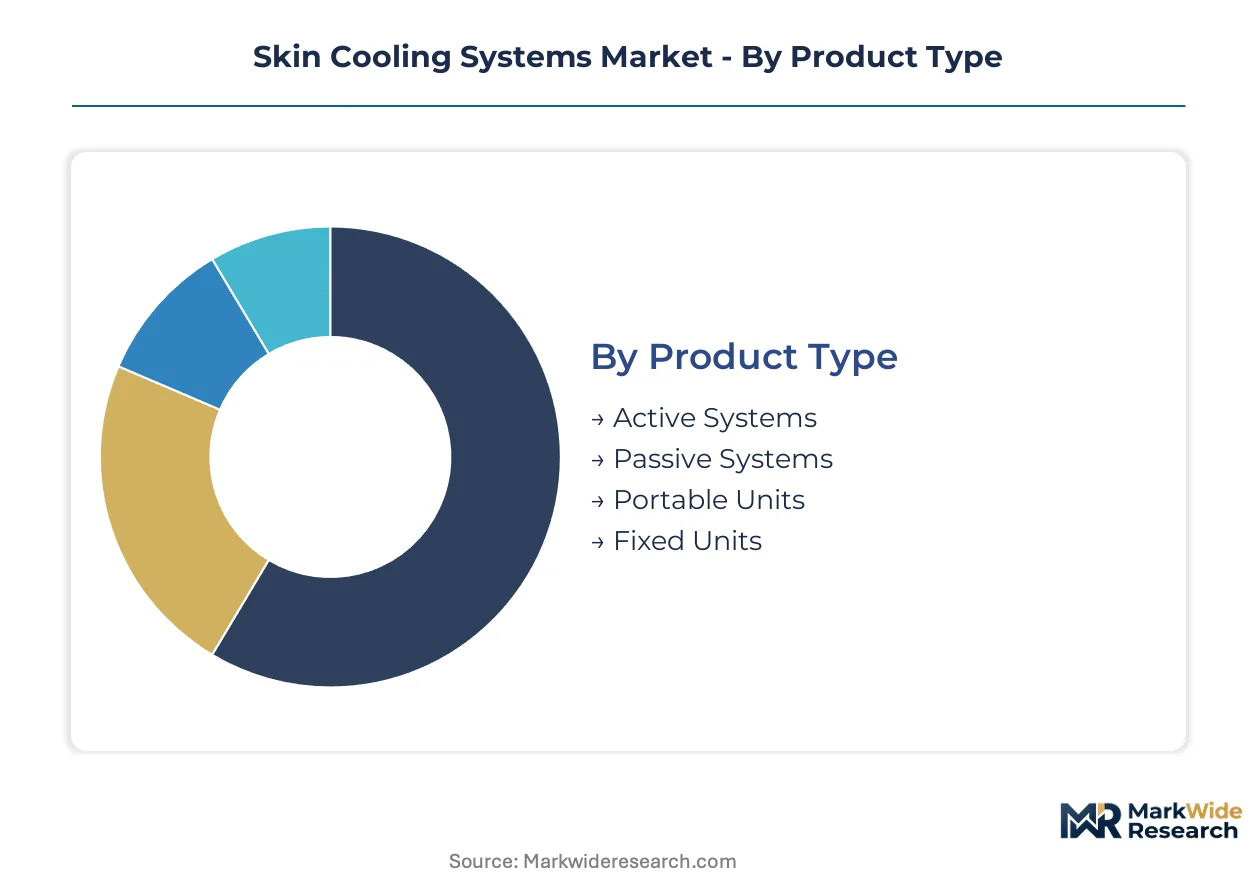
Skin cooling systems fragment across four interlocking dimensions that determine procurement specifications, regulatory pathways, and replacement cycles. Product architecture dictates infrastructure requirements, while technology choice governs maintenance intervals and helium supply exposure.
Product Type:
Upgrade cycles diverge sharply between reusable capital equipment and disposable accessories, with ambulatory clinics driving portable adoption to avoid fixed infrastructure investments.
- Active Systems:Closed-loop refrigeration circuits with compressor-driven cooling achieve precise temperature control between 4°C and 20°C. Dermatology centers in Seoul and Dubai mandate these for high-volume laser protocols where thermal precision prevents epidermal injury. Replacement cycles extend 7-10 years, though compressor refurbishment occurs at mid-life.
- Portable Units:Compact thermoelectric or cryogenic devices prioritize space efficiency for ambulatory clinics. Germany's independent dermatology practices in Berlin and Munich are standardizing these for satellite locations, trading absolute cooling capacity for installation flexibility. These systems represent the steepest expansion trajectory as clinic chains prioritize patient throughput over capital intensity.
- Passive Systems:Gel-based or phase-change materials requiring pre-conditioning, common in home care and research settings with intermittent cooling needs.
- Fixed Units:Permanent installation systems integrated into laser suites, dominant in hospital procurement where infrastructure amortization spans decades.
Volume placements concentrate in Active Systems; the faster expansion belongs to Portable Units.
Application:
Procedure reimbursement rates and liability exposure determine cooling system specification tiers across clinical settings.
- Dermatology Procedures:Laser hair removal, vascular lesion treatment, and tattoo removal require epidermal cooling to prevent thermal damage. Spain's high-throughput dermatology chains specify MDR-certified active systems with verified technical files. Demand concentrates where malpractice exposure elevates standard-of-care requirements.
- Aesthetic Treatments:Non-invasive facial rejuvenation and body contouring protocols in Dubai and São Paulo drive demand for integrated cooling modules. Brazilian clinic operators unbundle cooling hardware from laser service agreements, favoring modular component suppliers. This application segment gains share fastest as consumer aesthetic spending normalizes post-pandemic.
- Pain Management:Cryotherapy for musculoskeletal conditions, primarily in sports medicine and rehabilitation centers.
- Surgical Procedures:Intraoperative cooling for tissue preservation, concentrated in hospital operating suites with specialized anesthesia support.
Procurement volumes skew toward Dermatology Procedures; Aesthetic Treatments demonstrate the most rapid demand acceleration.
End User:
Capital availability and regulatory scrutiny stratify cooling system specifications across care settings.
- Hospitals:Integrated surgical suites and dermatology departments specify electric cooling systems with ISO 13485-certified supply chains. Texas and California state-level laser device regulations converge with FDA 510(k) requirements, complicating vendor qualification. These institutions prioritize 15-year total cost of ownership over acquisition price.
- Clinics:Independent and chain-affiliated dermatology practices in Germany's Berlin-Munich corridor drive portable unit adoption. After-sales service unbundling is most visible here, with procurement teams negotiating cooling module replacement cycles independently from laser platform agreements. This end user category expands most quickly as aesthetic medicine decentralizes.
- Home Care:Consumer-grade cooling attachments for at-home laser devices, emerging post-pandemic.
- Research Laboratories:Precision cooling for tissue studies and cryopreservation protocols.
Installed base value concentrates in Hospitals; Clinics exhibit the sharpest volume growth.
Technology:
Supply chain configuration and engineering talent availability determine technology selection across geographies.
- Cryogenics:Pressurized gas expansion systems achieve rapid temperature drop-off essential for high-throughput dermatology centers. Qatar and US strategic reserve helium concentration exposes margin stability to geopolitical disruption. Germany's industrial clusters concentrate specialized expertise in closed-loop refrigeration circuits.
- Electric Cooling:Thermoelectric Peltier modules with enhanced semiconductor junction materials overtake compressor systems in portable applications. South Korean ambulatory clinic networks adopt these for space-constrained treatment rooms, eliminating gas handling infrastructure. This technology climbs the fastest as solid-state efficiency improves.
- Water Circulation:Closed-loop chilled water systems for fixed installations with existing plumbing infrastructure.
- Gel Pads:Passive phase-change materials for intermittent cooling with minimal capital investment.
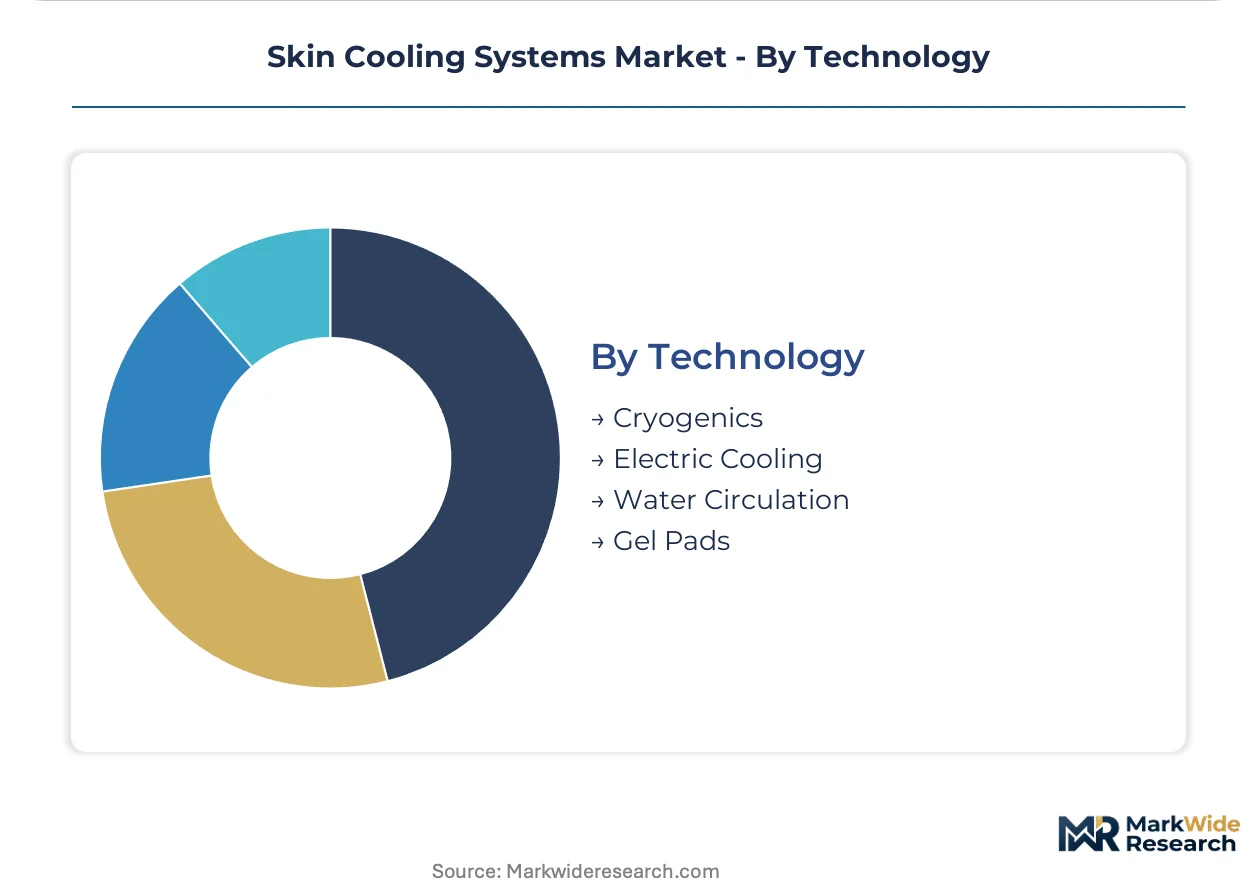
Revenue concentration favors Cryogenics; Electric Cooling demonstrates the most rapid share gain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's concentrated helium extraction anchors cryogenic supply chains for pressurized gas expansion systems. German engineering clusters around Berlin and Munich concentrate specialized expertise in closed-loop refrigeration circuits. Dubai's aesthetic clinic chains mandate standardized pre-treatment cooling protocols before laser interventions.
United States
FDA's 510(k) clearance pathway accelerates cryogenic device entry timelines for manufacturers targeting dermatology equipment procurement. Texas and California state-level laser device regulations converge with federal requirements, complicating vendor qualification for cooling system retrofits. Hospital procurement in the Midwest prioritizes 15-year total cost of ownership for integrated electric cooling systems.
Germany
Berlin and Munich industrial clusters concentrate scarce cryogenic engineering talent in pressurized gas expansion systems and closed-loop refrigeration circuits. The EU Medical Device Regulation's expanded clinical evidence requirements elevate documentation costs for market access. Independent dermatology practices in the Berlin-Munich corridor drive portable unit adoption for satellite locations.
South Korea
Seoul's aesthetic clinic chains mandate standardized epidermal cooling protocols, expanding installed base requirements across high-volume dermatology centers. MFDS medical device regulations align with international standards for quality management certification. Ambulatory clinic networks adopt thermoelectric Peltier arrays for space-constrained treatment rooms.
United Arab Emirates
Dubai's high-throughput aesthetic centers specify cryogenic systems for rapid temperature drop-off in non-invasive facial rejuvenation protocols. MOHAP medical device registration requirements govern import and distribution of cooling hardware. Clinic operators unbundle cooling hardware acquisition from maintenance contracts, favoring modular component suppliers.
India
The PLI scheme for medical devices offers tariff-advantaged supply chain repositioning for precision cooling component manufacturing. CDSCO medical device rules impose quality management standards on domestic and imported equipment. Maharashtra and Karnataka industrial corridors attract contract manufacturers seeking ISO 13485 certification for MDR-compliant supply chains.
Skin Cooling Systems Market Competitive Landscape
Global majors compete with regional champions across technology licensing and captive manufacturing configurations. The vendor base stratifies between integrated system vendors and modular component specialists, with after-sales service unbundling disrupting traditional equipment leasing models. Three archetypes dominate: European OEMs with captive manufacturing, price-aggressive portable specialists, and contract manufacturers serving branded device portfolios. Competitive moves concentrate on geographic expansion through distributor qualification and backward integration into compressor sourcing.
Among Germany-based medical technology specialists, Zimmer MedizinSystems GmbH occupies a position exemplifying captive European manufacturing for margin control. Cryonic Medical S.A.S. and Vacuactivus Sp. z o.o. represent contrasting approaches to compact cold-air delivery specialization and aggressive portable-segment pricing. These three anchors illustrate how regional engineering concentration, price positioning, and distributor fragmentation shape competitive differentiation across the European market.
| Leading Market Players |
|---|
| Zimmer MedizinSystems |
| Cryonic Medical |
| Vacuactivus |
| Zamar care |
| Aussie Medi Tech |
| METRUM CRYOFLEX |
| Sanhe Beauty S & T |
| The Global Beauty Group |
| Vertex Lasers |
| Others |
Value Network & Pricing Analysis
Family-owned German engineering specialists with multi-decade compressor manufacturing heritage anchor pricing discipline through captive production of thermal core components, insulating margin structures from helium spot volatility while clinic procurement teams in Dubai and São Paulo unbundle service contracts to extract hardware-only pricing.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier active systems from unbundled portable units where Brazilian clinic operators negotiate replacement cycles independently. Pricing stratifies across MDR-certified premium configurations, ISO 13485-compliant standard tiers, and economy portable units lacking technical file documentation. Cost compression in the portable segment intensifies as South Korean ambulatory networks prioritize acquisition price over service inclusion. Price sensitivity concentrates among independent dermatology practices in Germany's satellite locations, while Dubai's high-throughput aesthetic centers prioritize cooling precision over capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle compressor procurement for Zimmer MedizinSystems and Cryonic Medical, bypassing distributor markups on thermal core components. Manufacturing concentrates in Germany's Berlin-Munich industrial corridor, South Korea's Seoul-Incheon medtech cluster, and China's precision component zones. Raw material dependencies center on helium extraction from Qatar and the US strategic reserve, semiconductor junction materials for Peltier arrays, and specialized refrigerants governed by EU F-Gas Regulation restrictions. Single-source vulnerability in helium supply exposes margin stability to geopolitical disruption. Distribution runs through qualified medical device distributors with MDR technical documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
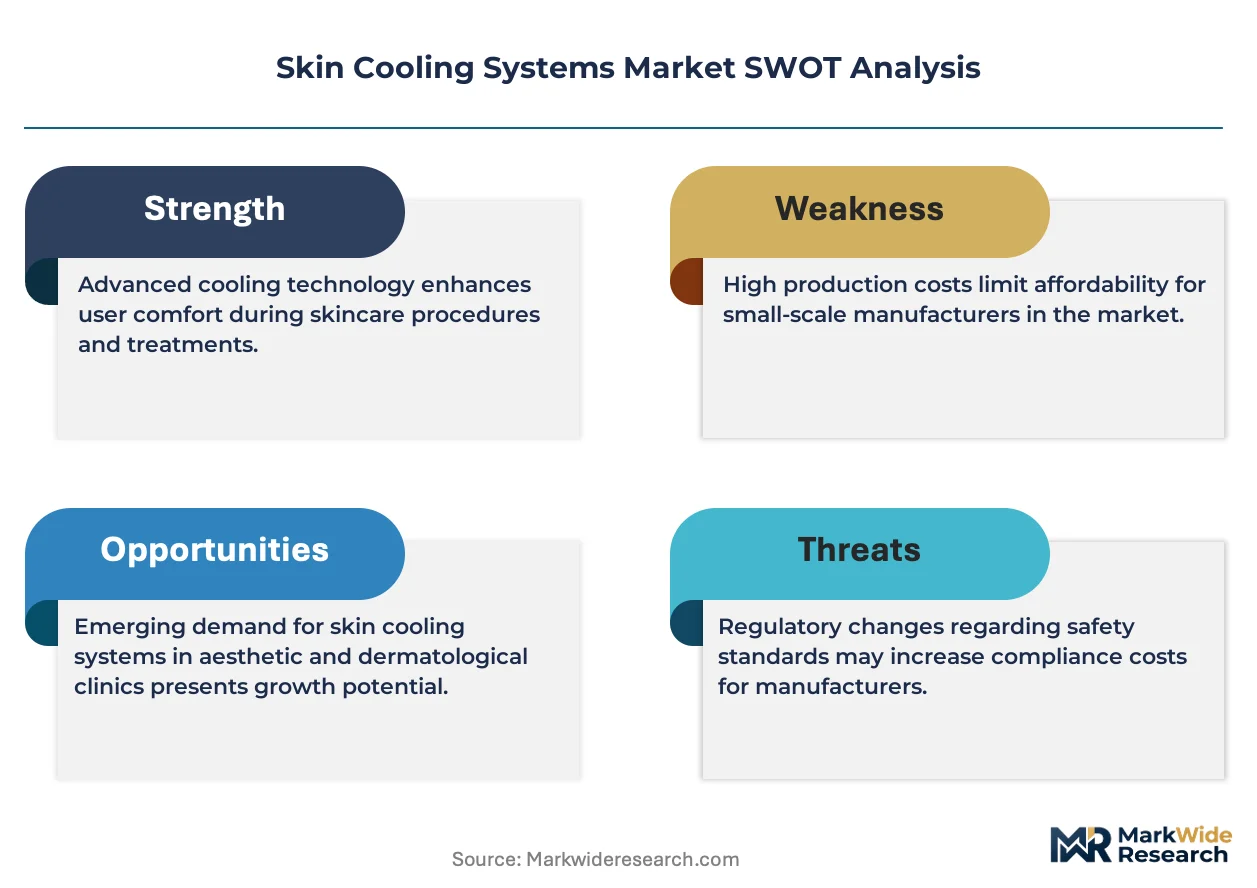
The EU Medical Device Regulation's expanded clinical evidence requirements function as a compliance moat, elevating substantiation costs that disadvantage smaller OEMs while rewarding established players with post-market surveillance infrastructure.
For Market Incumbents: Deepen backward integration into compressor sourcing to secure thermal core supply against Qatar helium concentration risk, while expanding ISO 13485-certified contract manufacturing capacity in India's PLI-advantaged corridors to offset MDR documentation cost inflation from European regulatory expansion. For New Entrants and Emerging Players: Launch via direct-to-clinic digital distribution targeting Brazil's independent dermatology practices where after-sales unbundling has fragmented procurement standardization, prioritizing compact thermoelectric portable units for space-constrained ambulatory settings lacking cryogenic infrastructure. For Investors and Strategic Acquirers: MFDS alignment with international quality management standards is the leading indicator that South Korean regulatory convergence will accelerate consolidation among mid-cap OEMs lacking certification infrastructure, positioning MDR-compliant specialists with verified technical files as preferred acquisition targets across the medium-term horizon.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Investment | Establishes competitive moat against uncertified rivals in Spain and Italy procurement. |
| Helium Supply Diversification | Mitigates Qatar concentration risk pressuring cryogenic device margin stability. |
| AI-Integrated Temperature Control Development | Converges machine learning with cooling hardware for personalized Seoul clinic protocols. |
| India PLI Manufacturing Repositioning | Captures tariff advantages for precision component supply to European OEMs. |
| Portable Unit Service Unbundling | Matches São Paulo clinic operator preference for independent replacement cycle negotiation. |
Research Methodology
Independent corroboration across dermatology equipment procurement managers, biomedical engineers at hospital purchasing committees, GPO contracts specialists, and cryogenic engineering directors underwrites the qualitative findings. Primary field engagement with clinic operators in Seoul, Dubai, Berlin, and São Paulo combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, MFDS registration records, and helium supply chain trade data. Bottom-up installed base modeling and top-down equipment spending triangulation anchored volume estimates.
Comparable-period anchoring to historical replacement cycles and compressor refurbishment intervals structured the projection horizon across active system, portable unit, and passive system product architectures. Segmentation modeling incorporated technology type, end-user capital availability, application reimbursement rates, and regional regulatory cluster dimensions. CAGRs derived from equipment procurement pipeline analysis and aesthetic clinic expansion trajectories, with helium spot price volatility and MDR audit backlog timelines as specific forecast inputs.
Regulatory enforcement variance, helium supply disruption events, and thermoelectric efficiency breakthroughs are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding clinic chain standardization timelines and OEM certification completion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Healthcare Personal Protection Equipment Market
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
Medical Waste Supervision Solution Market
Healthcare Equipment
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market
Healthcare Equipment
Clinical Mobility Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Specialty Medical Chairs Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Microbiological Safety Cabinets Market
Healthcare Equipment
Emergency Hospital Beds Market