
 US Medical Cold Storage Market | 2026-2036
US Medical Cold Storage Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Cold Storage Market Insights
Biologics manufacturing is pivoting toward ultra-low temperature infrastructure as cell and gene therapies expand. Thermo Fisher Scientific leverages its vertical integration from reagents to cryogenic freezers to dominate laboratory procurement channels. Lineage Logistics Holdings anchors temperature-controlled warehousing capacity through strategic cold chain nodes across pharmaceutical distribution corridors. Peli BioThermal specializes in portable thermal packaging systems that compete on ISTA-certified performance for last-mile vaccine delivery.
US medical cold storage encompasses engineered refrigeration and freezing systems designed to maintain precise thermal conditions for temperature-sensitive healthcare products, typically operating between standard refrigeration at 2°C to 8°C and cryogenic ranges below -150°C using liquid nitrogen or mechanical cascade systems. These systems employ redundant cooling loops, continuous monitoring sensors, and validated alarm protocols to prevent thermal excursions that compromise drug potency or biological sample viability. Freezers and cryogenic storage units command the largest installed base, though temperature monitoring systems are capturing expanding margin pools as regulatory validation requirements intensify. Vapor compression technology leads in hospital and blood bank installations, while liquid nitrogen systems dominate biorepository and cell therapy manufacturing applications where mechanical failure risks prove unacceptable.
FDA enforcement of Current Good Manufacturing Practice and Drug Supply Chain Security Act provisions shapes equipment validation protocols and documentation requirements for pharmaceutical cold storage operators. OSHA workplace safety standards and EPA refrigerant phase-down regulations under the AIM Act are simultaneously forcing equipment retrofits and alternative coolant adoption across installed base fleets. Stakeholders must monitor emerging USP <1079> revisions and state-level pharmaceutical waste rules to anticipate compliance-driven replacement cycles and service contract restructuring.
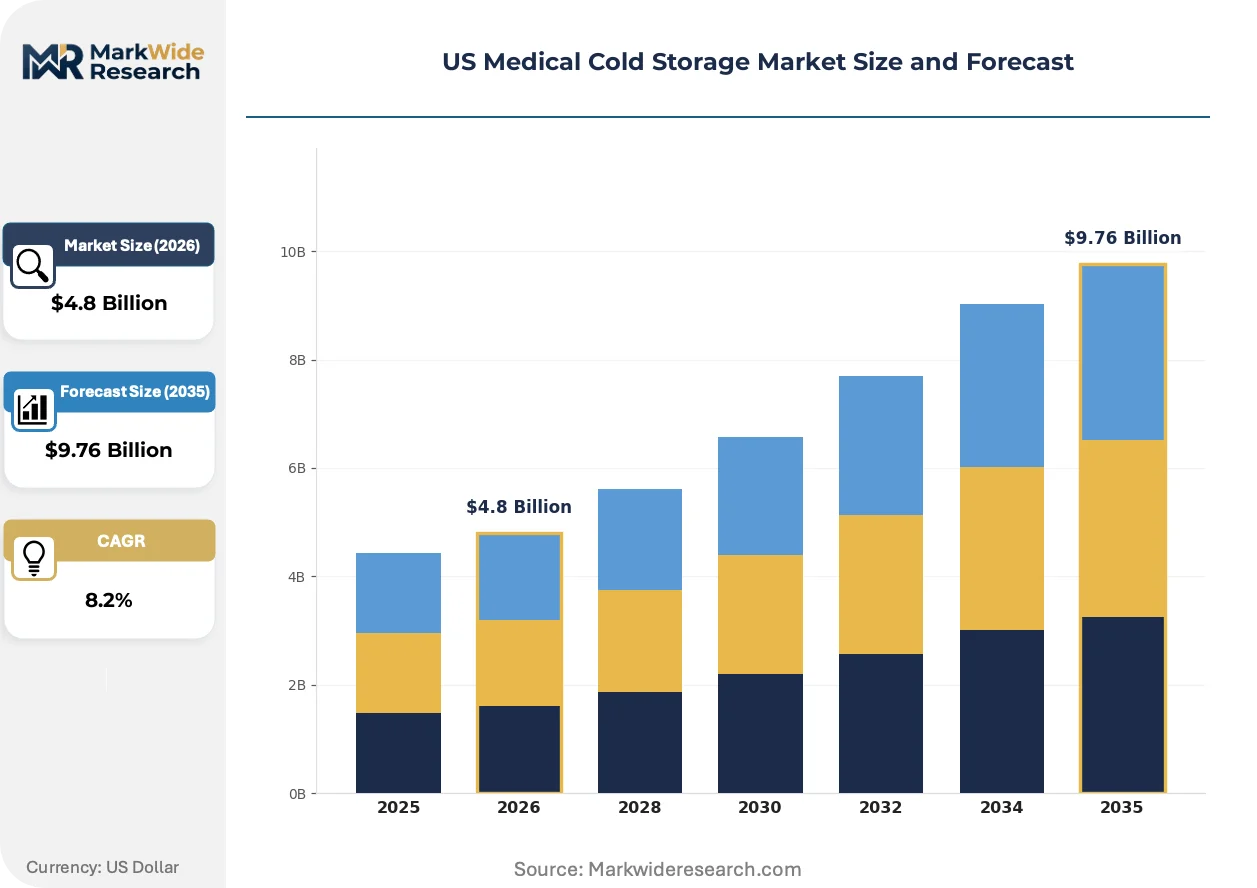
Market Dynamics
FDA enforcement of Current Good Manufacturing Practice provisions is compressing equipment replacement cycles as pharmaceutical operators race to validate ultra-low temperature infrastructure ahead of cell therapy manufacturing scale-up.
Growth Catalysts
- Cell and Gene Therapy Manufacturing:Biologics producers are expanding cryogenic storage footprints to accommodate autologous therapy workflows requiring vapor-phase liquid nitrogen systems at -150°C.
- Drug Supply Chain Security Act:Track-and-trace mandates are forcing wholesale distributors to upgrade temperature monitoring systems with continuous data logging capabilities.
- Boston-New Jersey Pharmaceutical Clustering:Dense concentration of biotech headquarters and CDMO facilities is driving freezer farm construction across the Northeast corridor.
Market Restraints
- Refrigerant Phase-Down Constraints:EPA regulations under the AIM Act are restricting hydrofluorocarbon availability and forcing premature equipment obsolescence across installed mechanical compression fleets.
- Liquid Nitrogen Supply Concentration:Regional production capacity limitations and cryogenic logistics bottlenecks create vulnerability for biorepository operators dependent on vapor-phase storage.
- Cascade System Complexity:Mechanical ultra-low freezers requiring staged compression circuits exhibit higher failure rates than single-stage units, elevating total cost of ownership.
Strategic Opportunities
- Midwest Biomanufacturing Expansion:Indiana and North Carolina are attracting cell therapy production facilities with state tax incentives, creating greenfield cold storage demand outside traditional coastal clusters.
- IoT-Enabled Predictive Maintenance:Wireless sensor networks and edge computing platforms are converging to enable remote equipment diagnostics and reduce unplanned downtime.
- Modular Cold Room Deployment:Prefabricated, containerized storage units are opening faster installation pathways for clinical trial material depots and hospital pharmacy expansions.
Industry Challenges
- Cryogenic Equipment Technician Scarcity:Specialized training requirements for liquid nitrogen system maintenance and safety protocols outpace vocational program output.
- Validation Documentation Burden:FDA 21 CFR Part 11 compliance for electronic records and signatures extends equipment qualification timelines by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Cold Storage Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Freezers, Cryogenic Storage, Temperature Monitoring Systems End User: Hospitals, Laboratories, Pharmacies, Blood Banks Application: Vaccines, Biologics, Blood Products, Pharmaceuticals Technology: Vapor Compression, Thermoelectric, Liquid Nitrogen, Hybrid Systems |
| Companies Covered | Thermo Fisher Scientific, ThermoSafe Technologies, Lineage Logistics Holdings, CSafe, Cryoport Systems, Americold Realty Trust, Peli BioThermal, DGP Intelsius, United States Cold Storage, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Cold Storage Market Trends and Innovations
Equipment architecture is pivoting from mechanical redundancy to sensor-driven reliability as operators prioritize predictive uptime over capital-intensive backup systems.
Mechanical cascade refrigeration for ultra-low temperature storage is consolidating around single-compressor designs with variable-speed drives and hydrocarbon refrigerant blends. Hospital blood banks and academic biorepositories are adopting these platforms to reduce energy consumption and simplify maintenance protocols. The technology is consolidating vendor portfolios as integrated system suppliers acquire component specialists to capture aftermarket service revenue.
OSHA workplace safety standards for cryogenic handling are tightening personal protective equipment mandates and ventilation requirements for liquid nitrogen storage facilities. Biopharmaceutical manufacturers are responding by redesigning warehouse layouts to segregate vapor-phase units from occupied spaces. Cell therapy CDMOs in Massachusetts and New Jersey face the steepest compliance costs as state inspectors align with federal enforcement patterns.
Hospital pharmacies are unbundling equipment purchase from validation services, treating temperature mapping and qualification as separate procurement categories with distinct vendor selection criteria. This behavior is fragmenting supplier relationships as specialized validation consultancies capture margin pools previously retained by equipment OEMs. The shift is most pronounced in California and Texas health systems with centralized supply chain governance.
US Medical Cold Storage Market Segmentation
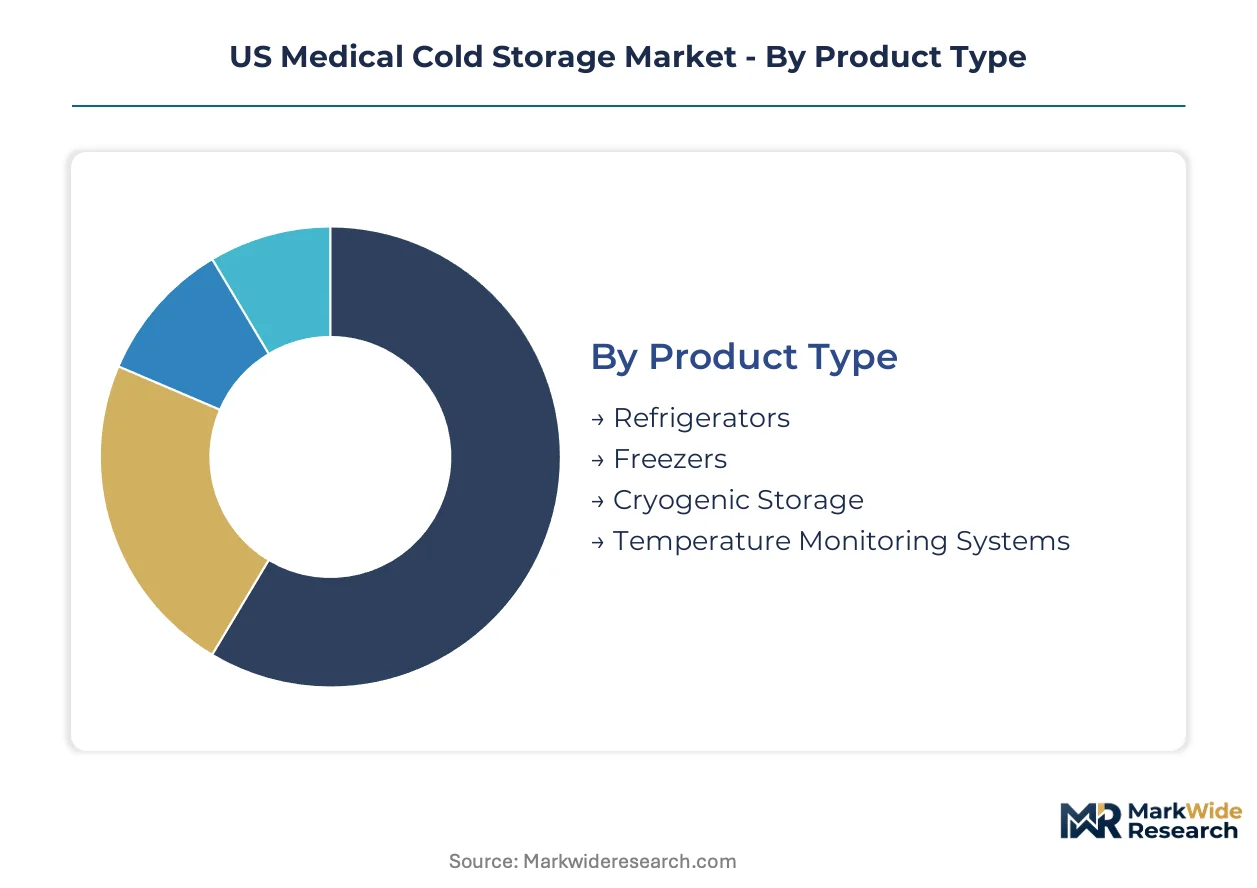
Segmentation in US medical cold storage reveals divergent capital requirements and regulatory exposure across equipment categories. Procurement patterns vary sharply between hospital blood banks prioritizing uptime redundancy and biopharmaceutical manufacturers validating ultra-low temperature infrastructure for cell therapy workflows.
Product Type:
Capital intensity peaks in cryogenic infrastructure, where vapor-phase liquid nitrogen systems demand specialized facility retrofits and redundant supply contracts.
- Refrigerators:Standard 2°C to 8°C units employ single-stage vapor compression with forced air circulation. Hospital pharmacies in California and Texas health systems drive replacement demand as centralized procurement unbundles equipment from validation services.
- Freezers:Ultra-low mechanical units operating at -80°C utilize cascade refrigeration with staged compression circuits. Biorepositories and academic research centers anchor installed base, though higher failure rates elevate total cost of ownership versus cryogenic alternatives.
- Cryogenic Storage:Vapor-phase liquid nitrogen systems maintain -150°C for cell therapy manufacturing. Autologous therapy workflows in Massachusetts and New Jersey CDMOs are expanding footprints despite OSHA ventilation mandates and supply concentration risks.
- Temperature Monitoring Systems:Continuous data logging platforms with wireless sensor networks. FDA 21 CFR Part 11 compliance requirements are extending qualification timelines and fragmenting supplier relationships as specialized consultancies capture validation revenue.
Most installed capacity flows through freezers. Expansion is steepest in cryogenic storage.
End User:
Customer type determines procurement sophistication, with blood banks and biopharmaceutical manufacturers operating at opposite ends of the validation complexity spectrum.
- Hospitals:Blood bank and pharmacy departments prioritize mechanical redundancy and rapid service response. Vapor compression technology dominates installations, with energy efficiency upgrades accelerating under EPA AIM Act refrigerant phase-down pressure.
- Laboratories:Academic and clinical research biorepositories require validated sample integrity protocols. Thermo Fisher Scientific's vertical integration from reagents to cryogenic freezers dominates laboratory procurement channels nationwide.
- Pharmacies:Hospital and retail chains unbundling equipment purchase from temperature mapping services. This procurement shift fragments supplier relationships as validation consultancies capture margin pools previously retained by equipment OEMs.
- Blood Banks:FDA Current Good Manufacturing Practice enforcement compresses replacement cycles. Redundant cooling loops and continuous monitoring sensors are non-negotiable specifications for plasma and platelet storage.
Procurement volume concentrates in hospitals. Validation complexity peaks in blood banks.
Application:
Application segments map directly to temperature band requirements and regulatory scrutiny intensity, with cell and gene therapies imposing the most stringent storage protocols.
- Vaccines:Standard cold chain at 2°C to 8°C with last-mile thermal packaging demands. Peli BioThermal's ISTA-certified portable systems compete on validated performance for distribution to point-of-care sites.
- Biologics:Cell and gene therapies requiring vapor-phase liquid nitrogen at -150°C. Boston-New Jersey pharmaceutical clustering drives freezer farm construction as autologous manufacturing scales.
- Blood Products:Plasma, platelets, and red cell concentrates spanning multiple temperature bands. Blood banks anchor demand for mechanical ultra-low freezers with cascade refrigeration and alarm protocol redundancy.
- Pharmaceuticals:Small-molecule and protein therapeutics with intermediate cold chain requirements. Drug Supply Chain Security Act track-and-trace mandates force wholesale distributors toward continuous data logging capabilities.
Biologics command the steepest infrastructure investment per cubic foot. Vaccines drive highest unit volume.
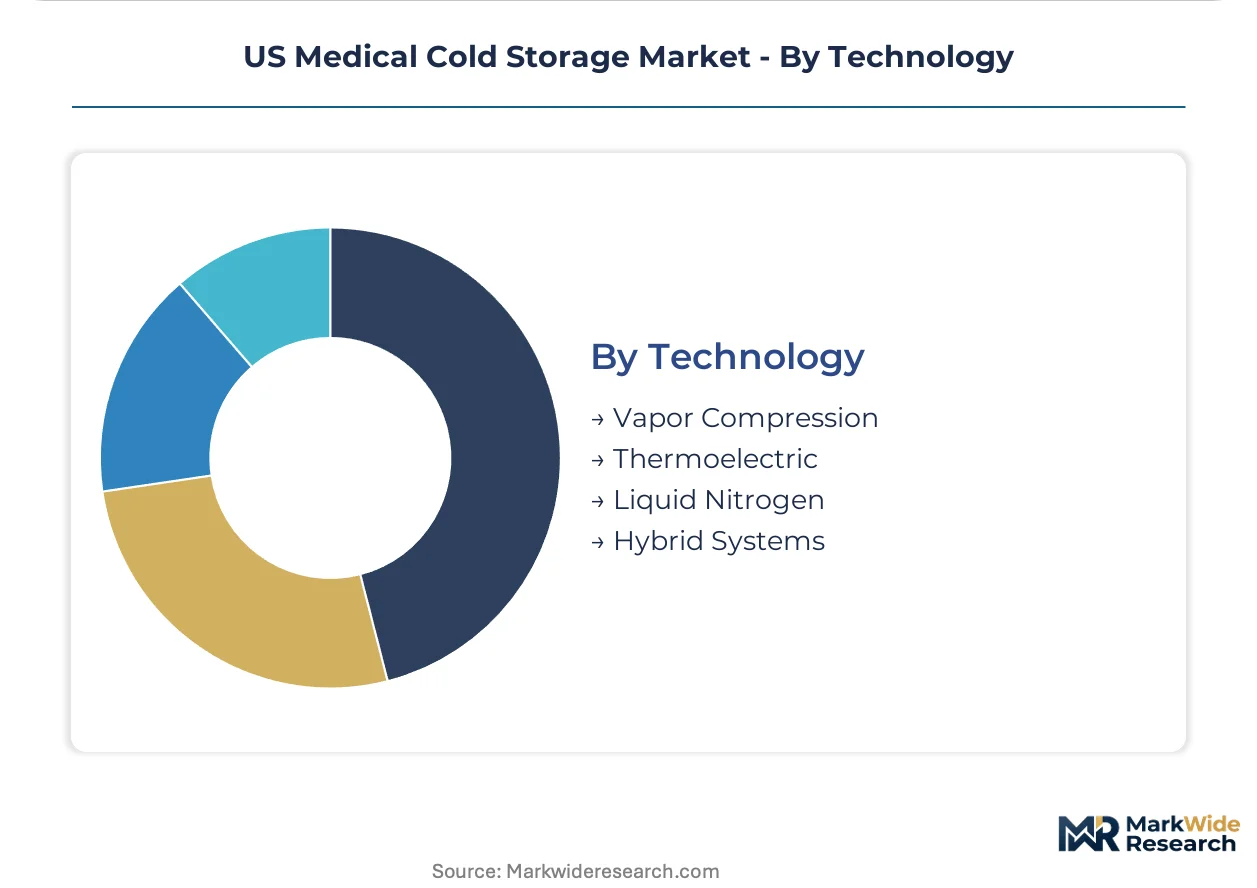
Technology:
Technology selection hinges on failure mode tolerance, with liquid nitrogen systems preferred where mechanical breakdown risks prove unacceptable.
- Vapor Compression:Dominant technology for standard refrigeration and ultra-low mechanical freezers. Hospital and blood bank installations consolidate around single-compressor designs with variable-speed drives and hydrocarbon refrigerant blends.
- Thermoelectric:Solid-state cooling for portable and small-scale applications. Limited penetration in medical cold storage due to energy efficiency constraints at larger capacities.
- Liquid Nitrogen:Cryogenic vapor-phase storage for biorepositories and cell therapy manufacturing. Regional production capacity limitations create supply vulnerability for operators dependent on continuous nitrogen delivery.
- Hybrid Systems:Mechanical compression with liquid nitrogen backup for critical applications. Emerging architecture in cell therapy CDMOs seeking to balance energy efficiency against catastrophic failure risk.
Mechanical vapor compression anchors installed base. Liquid nitrogen systems are gaining share fastest in biopharmaceutical manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity is shifting toward jurisdictions offering streamlined FDA validation pathways and state-level tax incentives for biomanufacturing. Operators are arbitraging compliance costs by locating freezer farms in states with faster environmental permitting and workforce training subsidies.
Massachusetts
Cell therapy CDMOs are expanding cryogenic footprints around Cambridge and Worcester to support autologous manufacturing workflows. The Massachusetts Life Sciences Center tax incentive program offsets capital costs for liquid nitrogen infrastructure. Greater Boston's Kendall Square biotech clustering drives demand for vapor-phase storage systems exceeding -150°C.
New Jersey
Pharmaceutical headquarters concentration in Princeton and New Brunswick anchors wholesale distributor cold chain upgrades. FDA District Office enforcement of Drug Supply Chain Security Act provisions accelerates temperature monitoring system replacements. The Port of Newark pharmaceutical logistics corridor supports freezer farm construction for import-export biologics handling.
North Carolina
Research Triangle Park cell therapy facilities are attracting greenfield investment through state biomanufacturing tax credits. North Carolina Biotechnology Center workforce grants address cryogenic equipment technician scarcity. RTP-based CDMOs are installing hybrid mechanical-nitrogen backup systems to balance energy efficiency against catastrophic failure risk.
California
Hospital pharmacy unbundling of equipment from validation services concentrates in Los Angeles and San Francisco Bay Area health systems. Cal/OSHA alignment with federal cryogenic handling standards tightens ventilation mandates for liquid nitrogen storage. Stanford and UCSF academic biorepositories anchor demand for validated sample integrity protocols.
Texas
Centralized supply chain governance at Houston and Dallas health systems fragments supplier relationships across equipment and validation categories. Texas Workforce Commission vocational programs lag specialized cryogenic maintenance training requirements. The Texas Medical Center blood bank network prioritizes redundant cooling loops under FDA Current Good Manufacturing Practice compression.
US Medical Cold Storage Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Laboratory procurement channels consolidate around vertically integrated reagent-to-equipment suppliers, while pharmaceutical distribution favors specialized cold chain logistics operators. Three archetypes dominate: integrated life sciences conglomerates, temperature-controlled warehousing specialists, and portable thermal packaging engineers. M&A activity targets validation service capabilities, while capacity expansion concentrates in Midwest biomanufacturing corridors.
Among integrated life sciences conglomerates, Thermo Fisher Scientific exemplifies the reagent-through-cryogenic-freezer vertical control archetype. Temperature-controlled warehousing specialists include Lineage Logistics Holdings, which occupies a position in pharmaceutical distribution corridor node development. Portable thermal packaging engineers such as Peli BioThermal represent the ISTA-certified last-mile delivery validation tier. These three anchors illustrate how procurement channel fragmentation creates distinct competitive arenas with divergent margin structures and customer retention mechanisms.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| ThermoSafe Technologies |
| Lineage Logistics Holdings |
| CSafe |
| Cryoport Systems |
| Americold Realty Trust |
| Peli BioThermal |
| DGP Intelsius |
| United States Cold Storage |
| Others |
Pricing and Supply Chain Analysis
FDA 21 CFR Part 11 compliance mandates for electronic records and signatures are compressing equipment qualification timelines and fragmenting supplier relationships as specialized validation consultancies capture margin pools previously retained by equipment OEMs. This procurement unbundling forces manufacturers to absorb higher upfront validation costs while distributors face margin compression from disintermediation.
Pricing Analysis
Distributor margins in pharmaceutical cold storage equipment are thinning as hospital pharmacies and blood banks unbundle hardware procurement from temperature mapping and qualification services. Three-tier pricing structure across premium, standard, and economy levels separates validated cryogenic systems from mechanical ultra-low freezers and basic refrigeration units. Price differentiation hinges on FDA compliance certification tier and after-sales service bundling. Cost compression in the standard tier is intensifying because EPA AIM Act refrigerant phase-down regulations are forcing premature equipment obsolescence. Blood banks exhibit lowest price sensitivity due to non-negotiable uptime requirements, while retail pharmacy chains drive hardest bargaining on per-unit transactional pricing.
Supply Chain Analysis
Liquid nitrogen supply for vapor-phase cryogenic storage rests on regional production capacity concentrated in the Gulf Coast, Midwest, and select Northeast corridor facilities. Mechanical compression systems draw from compressor manufacturing anchored in the United States, Germany, and Japan, with hydrocarbon refrigerant blends increasingly sourced from domestic specialty chemical producers. Supply chain risk centers on single-source vulnerability for cryogenic logistics and regional nitrogen production bottlenecks. Distribution runs through pharmaceutical distribution corridor nodes in New Jersey, Massachusetts, and North Carolina, with cold chain validation services fragmenting across specialized regional consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
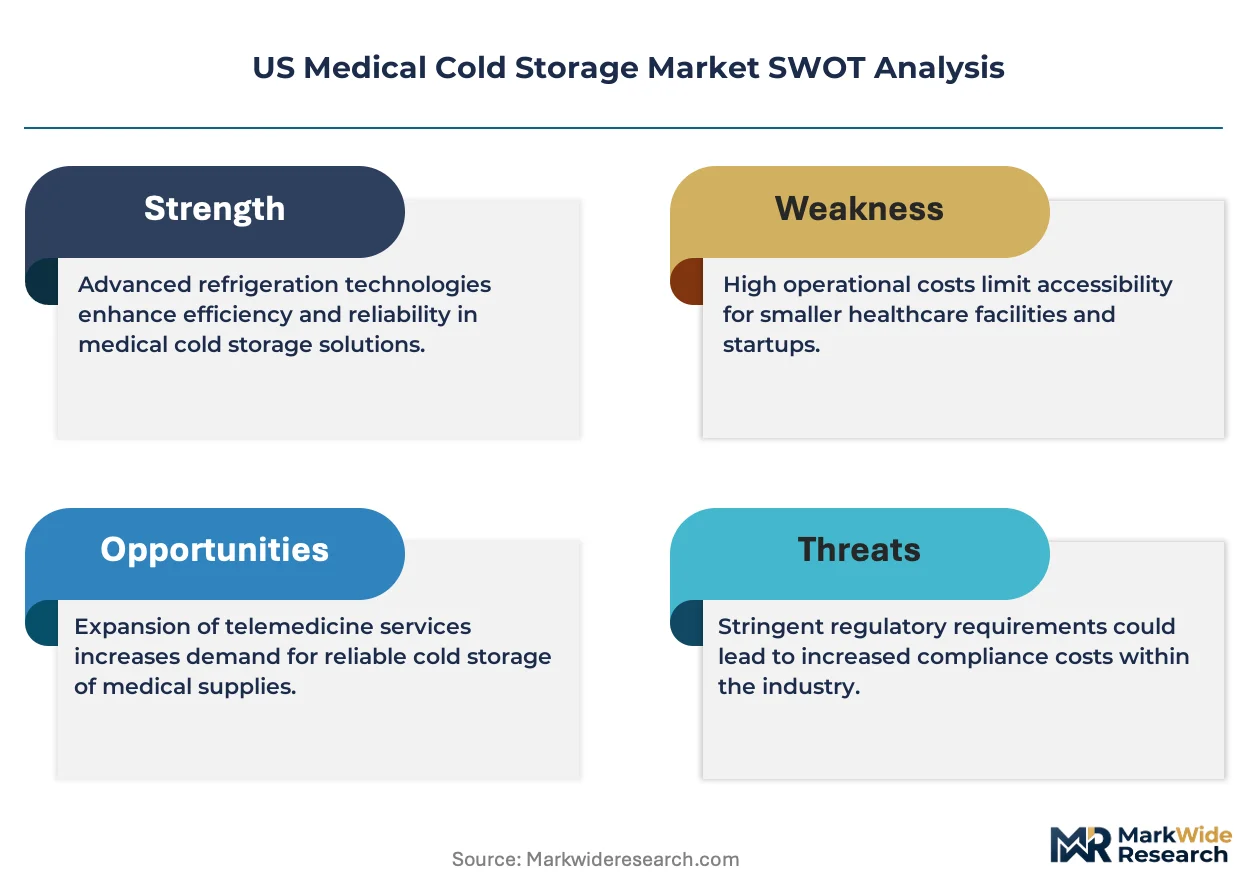
This market operates as a regulatory compounder where FDA enforcement of Current Good Manufacturing Practice provisions accelerates equipment replacement cycles and validation service demand.
For Market Incumbents: Deepen backward integration into cryogenic equipment technician training programs to address vocational program output gaps that constrain service capacity expansion. Fortify channel control through captive validation service offerings that recapture margin pools migrating to specialized consultancies. The threat of modular cold room deployment by containerized storage specialists demands preemptive certification investment in prefabricated unit qualification protocols. For New Entrants and Emerging Players: The price-point gap between premium cryogenic infrastructure and economy mechanical freezer tiers opens white-space targeting in the hybrid system segment, where mechanical compression with liquid nitrogen backup addresses cell therapy CDMO risk tolerance. Midwest biomanufacturing expansion in Indiana and North Carolina offers the most penetrable geography given state tax incentive programs and less entrenched incumbent relationships. A validation-first go-to-market angle—leading with FDA 21 CFR Part 11 qualification services rather than equipment—secures faster hospital pharmacy procurement decisions. For Investors and Strategic Acquirers: Asymmetric upside sits with temperature monitoring system specialists possessing wireless sensor network platforms and edge computing capabilities for predictive maintenance. Long-term viability favors acquisition targets with recurring revenue from validation service contracts rather than transactional equipment sales. The signal to watch is EPA enforcement patterns on AIM Act refrigerant phase-down timelines, which will trigger accelerated replacement cycle demand.| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Predictive Maintenance Platform | Wireless sensor networks at Massachusetts CDMOs reduce unplanned cryogenic downtime through edge computing diagnostics. |
| Modular Cold Room Deployment | Containerized storage units accelerate clinical trial material depot installation in North Carolina's Research Triangle Park. |
| Validation Service Capability Acquisition | Specialized consultancies capture margin pools as California health systems unbundle equipment from temperature mapping. |
| Liquid Nitrogen Supply Contract Structuring | Redundant supply agreements mitigate regional production concentration risks for Boston-New Jersey biorepository operators. |
| Hydrocarbon Refrigerant Transition Program | Alternative coolant adoption addresses EPA AIM Act compliance for Texas Medical Center blood bank mechanical fleets. |
Research Methodology
Coverage spans Massachusetts, New Jersey, North Carolina, California, and Texas, with primary inputs from each state informing demand-side modeling. The analysis combines structured interviews with hospital pharmacy procurement managers, blood bank operations directors, cell therapy CDMO facility heads, cryogenic equipment service technicians, and FDA regulatory affairs specialists with secondary validation from FDA warning letters, EPA AIM Act implementation guidance, USP <1079> draft revisions, and state-level biomanufacturing incentive program disclosures. Bottom-up equipment unit demand estimates triangulate against top-down pharmaceutical cold chain infrastructure spending projections.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end user category, application temperature band, and technology platform, with additional granularity on regional regulatory cluster intensity. CAGRs derive from logistic diffusion curves fitted to cell therapy manufacturing capacity expansion timelines and FDA enforcement pattern historical analysis. Industry-specific forecast inputs incorporate liquid nitrogen supply capacity utilization rates and mechanical cascade system failure rate trends from biorepository operator maintenance records.
Caveats apply where EPA refrigerant phase-down acceleration, OSHA cryogenic handling standard revisions, or FDA validation protocol changes could materially shift the outlook. Forecasts reflect assumptions on state tax incentive program continuity and vocational training program expansion rates. A small set of named triggers—EPA enforcement intensity, nitrogen supply disruption events, and USP <1079> finalization timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
Medical Waste Supervision Solution Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Emergency Hospital Beds Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
Medical Cold Storage Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Middle East and Africa Hospital Furniture Market
Healthcare Equipment
Ophthalmic Examination Chairs Market
Healthcare Equipment
Microbiological Safety Cabinets Market
Healthcare Equipment
Specialty Medical Chairs Market
Healthcare Equipment
Middle East and Africa Ultrasound Probe Disinfection Market
Healthcare Equipment
Global Hospital Asset Management Market