
 India Healthcare Machine Vision System Market | 2026-2036
India Healthcare Machine Vision System Market Size, Share, and Industry Trends Forecast 2026-2036
India Healthcare Machine Vision System Market Insights
Modular hardware-software bundles is broadening buyer choice across budget tiers in the India Healthcare Machine Vision System Market. Cognex Corporation leverages its deep learning software stack to anchor premium diagnostic deployments in metropolitan hospitals. Keyence Corporation sustains channel control through direct technical service networks spanning Bengaluru and Hyderabad. SigTuple specializes in AI-powered microscopy solutions for pathology workflows, occupying a distinct niche in clinical laboratory automation.
Healthcare machine vision systems integrate high-resolution cameras, optical sensors, and algorithmic software to capture, process, and interpret visual data for medical decision-making, typically operating at frame rates exceeding 30 fps and resolution thresholds of 2 megapixels for diagnostic-grade imaging. These systems serve primary industrial purposes in automated disease detection, surgical navigation, and quality assurance for pharmaceutical manufacturing. Deep learning technology commands expanding R&D allocation as convolutional neural networks improve lesion classification accuracy in radiology workflows. Medical device manufacturers represent a concentrated demand node where inline vision inspection ensures compliance with CDSCO packaging integrity requirements. 3D vision applications in surgical assistance are gaining traction among tertiary hospitals performing minimally invasive procedures.
CDSCO mandates quality management system certification for Class C and D medical devices, compelling vision system vendors to validate software algorithms under clinical performance standards. BIS certification for electromagnetic compatibility and electrical safety shapes hardware design specifications for equipment deployed in Indian healthcare facilities. The PLI scheme for medical device manufacturing creates procurement pull for domestic vision system integration. Stakeholders must monitor how CDSCO's evolving software-as-medical-device guidelines classify AI-driven diagnostic algorithms.
Market Dynamics
CDSCO's tightened medical device quality norms are compressing procurement timelines and forcing diagnostic imaging departments to validate vision systems under clinical performance standards before deployment.
Growth Catalysts
- CDSCO Quality Mandates:Tightened norms for Class C and D medical devices compel hospitals to upgrade to automated visual inspection tools that ensure packaging integrity and traceability compliance.
- Deep Learning Integration:Convolutional neural networks are improving lesion classification accuracy in radiology workflows, driving R&D allocation toward AI-powered diagnostic platforms.
- Maharashtra Manufacturing Corridor:Concentrated medical device production around Mumbai and Pune creates localized demand clusters for inline vision inspection systems serving export-oriented manufacturers.
Market Restraints
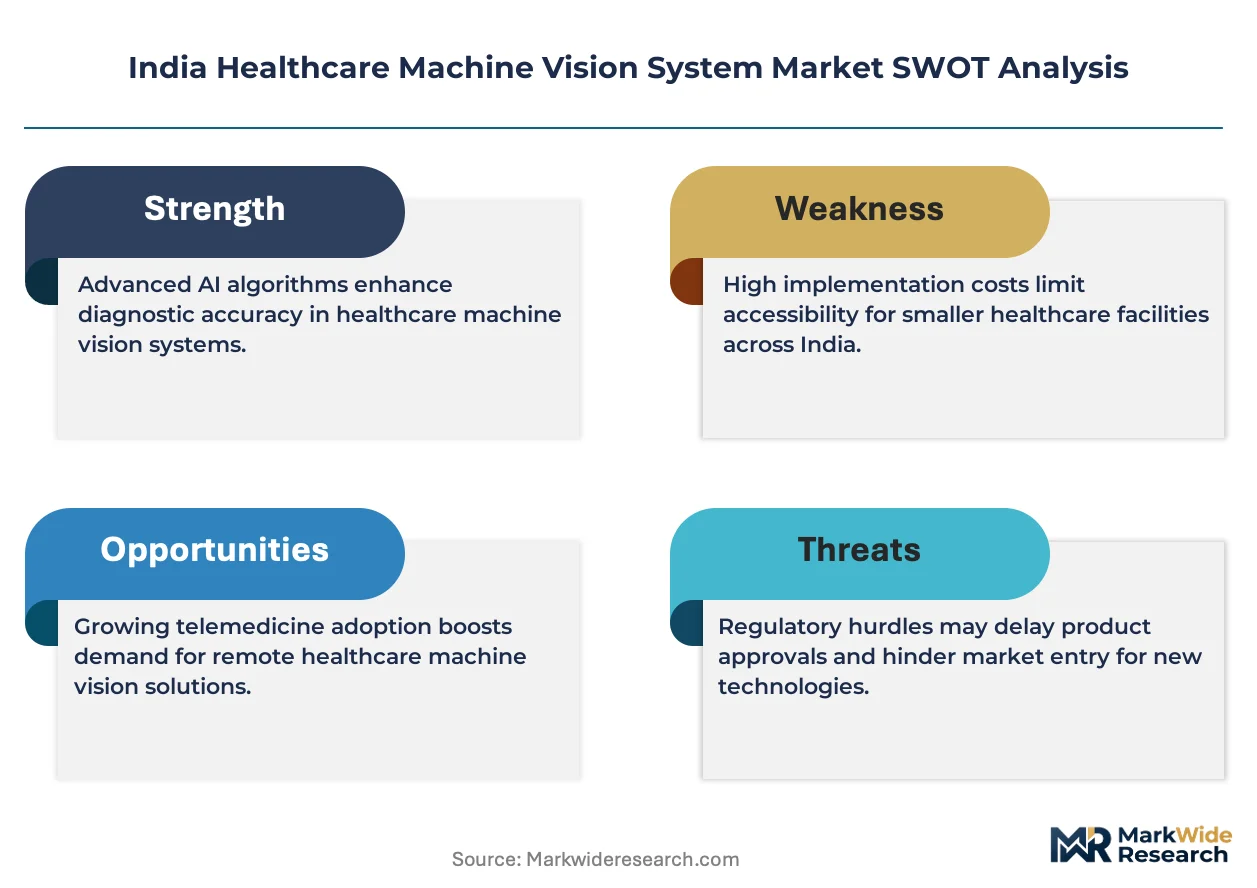
- Import Dependency for Optical Sensors:High-resolution cameras and specialized lenses rely heavily on East Asian supply chains, exposing buyers to currency volatility and shipping disruptions.
- CDSCO Software-as-Medical-Device Classification Uncertainty:Evolving guidelines for AI-driven diagnostic algorithms create validation delays and compliance cost ambiguity for vendors.
- Capital Intensity of 3D Vision Systems:Surgical assistance platforms requiring sub-millimeter depth accuracy demand specialized hardware that stretches hospital capital budgets.
Strategic Opportunities
- PLI Scheme Procurement Pull:Production-linked incentives for domestic medical device manufacturing create captive demand for locally integrated vision systems serving export markets.
- Tier-II City Hospital Expansion:Underpenetrated diagnostic infrastructure in cities like Indore, Lucknow, and Coimbatore offers whitespace for mid-tier hardware-software bundles.
- Pharmaceutical Quality Assurance Convergence:Combination of machine vision with spectroscopic analysis enables inline tablet inspection, opening new application vectors beyond diagnostics.
Industry Challenges
- Algorithm Validation Expertise Gap:Shortage of clinical engineers capable of training convolutional neural networks on Indian pathology datasets slows deployment cycles.
- BIS Electromagnetic Compatibility Certification:Extended testing timelines for electrical safety compliance delay product launches and tie up working capital.
- Interoperability with Legacy PACS:Integration friction between new vision systems and existing picture archiving infrastructure in tertiary hospitals requires costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Healthcare Machine Vision System Market |
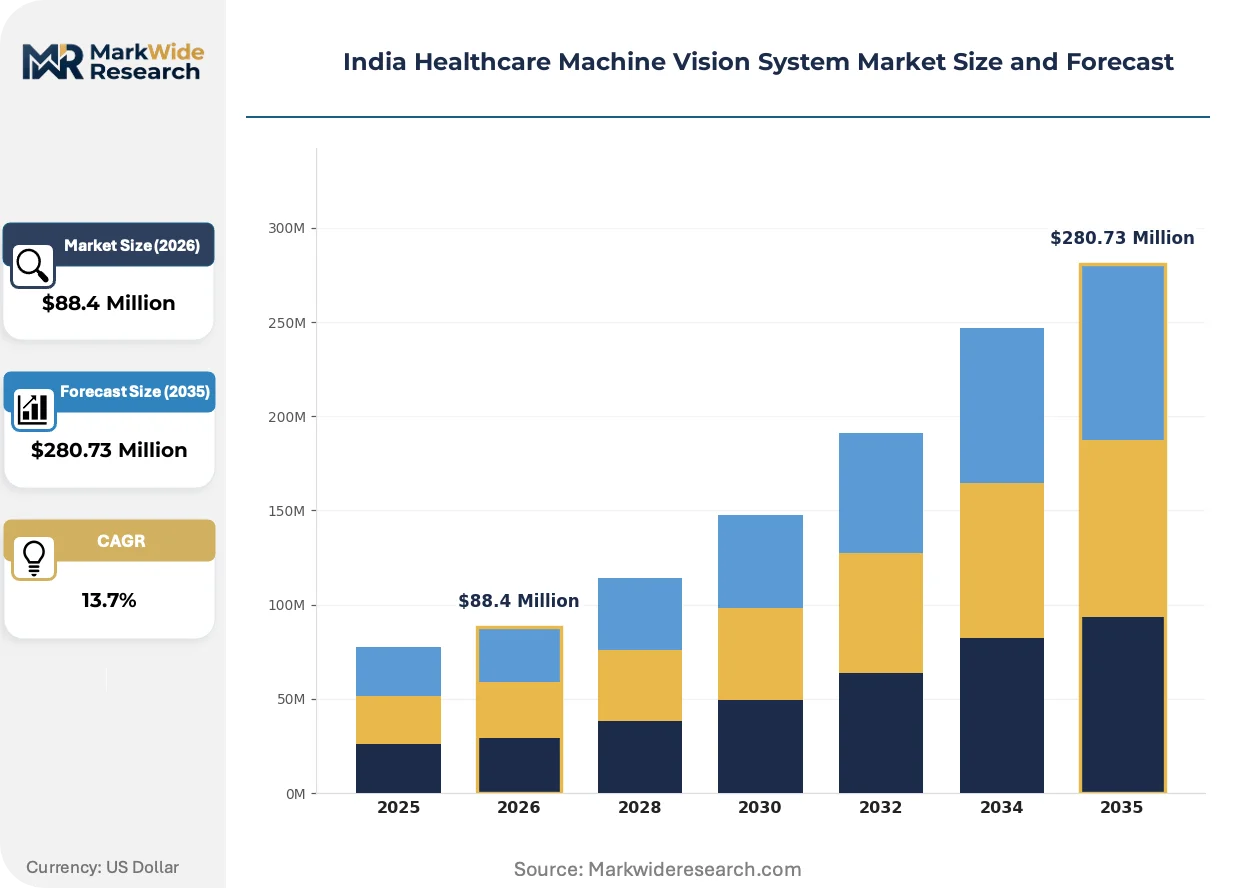
| Market Size in 2026 | $88.4 Million |
| Market Size in 2035 | $280.73 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Optical Sensors, Software Solutions, Cameras Technology: 2D Vision, 3D Vision, Infrared Imaging, Deep Learning Application: Diagnostic Imaging, Surgical Assistance, Patient Monitoring, Quality Control End User: Hospitals, Clinics, Research Laboratories, Medical Device Manufacturers |
| Companies Covered | Cognex Corporation, Keyence Corporation, Basler AG, Teledyne Technologies Incorporated, Omron Corporation, SICK AG, GE HealthCare Technologies Inc., Qure AI, SigTuple, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Healthcare Machine Vision System Market Trends and Innovations
Deep learning architectures are compressing the gap between research-grade accuracy and clinical deployment feasibility across Indian healthcare facilities.
Convolutional neural networks with attention mechanisms are rewriting diagnostic workflows by enabling real-time lesion detection in radiology without specialized hardware accelerators. Metropolitan tertiary hospitals in Delhi and Chennai are piloting these systems for tuberculosis screening and diabetic retinopathy assessment. The technology is compressing the validation timeline from algorithm development to clinical deployment from years to months.
CDSCO's evolving software-as-medical-device guidelines are forcing vendors to restructure product development around clinical performance benchmarks rather than laboratory accuracy metrics. Manufacturers must now submit algorithm training datasets and validation protocols for pre-market review, increasing regulatory compliance costs. Tier-I hospitals with established quality management systems are absorbing these requirements faster than mid-tier facilities, widening the deployment gap between institution types.
Service unbundling is fragmenting traditional capital equipment sales into subscription-based software licensing paired with hardware leasing arrangements. Diagnostic imaging departments in government hospitals are replacing upfront procurement with annual contracts that include algorithm updates and technical support. This shift is most visible in Karnataka and Telangana, where state health missions prioritize operational expenditure budgets over capital allocations.
India Healthcare Machine Vision System Market Segmentation
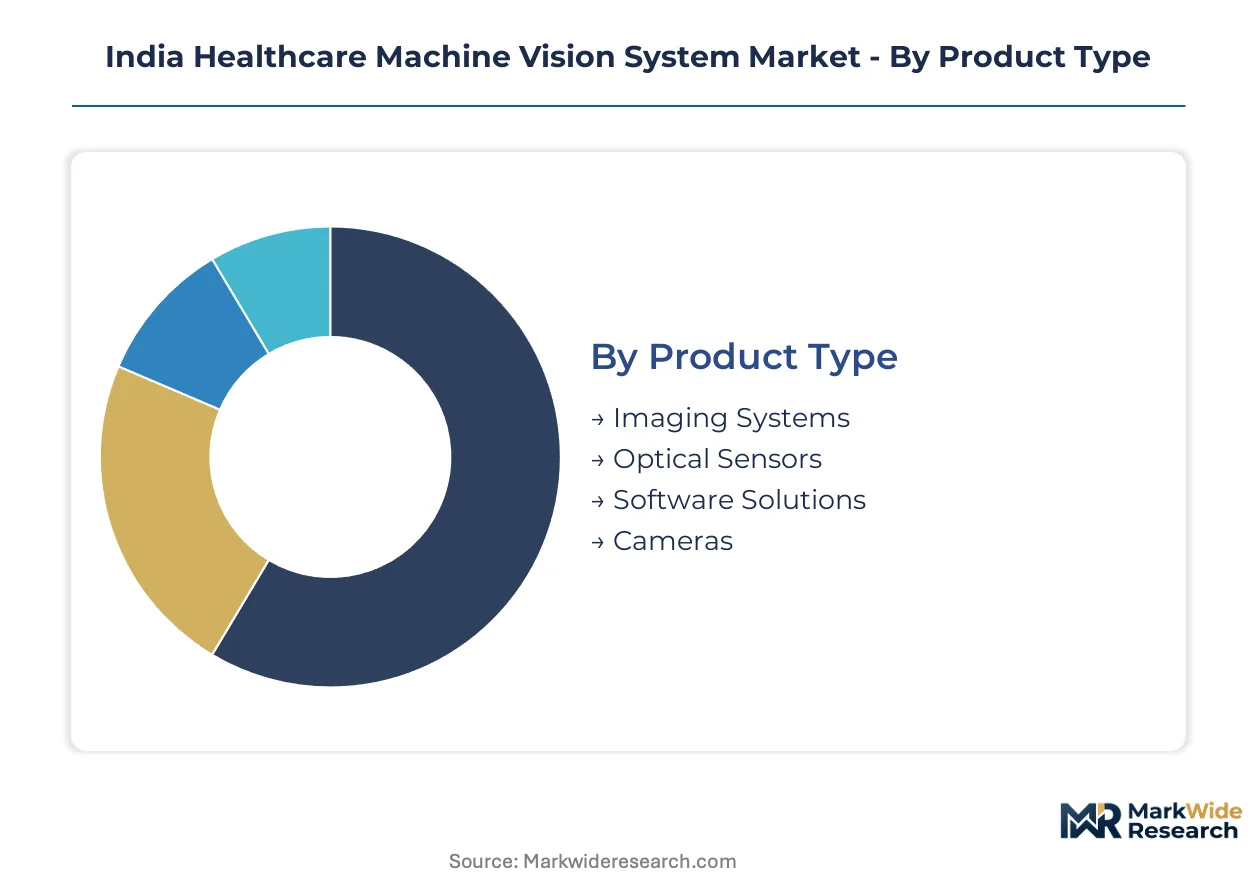
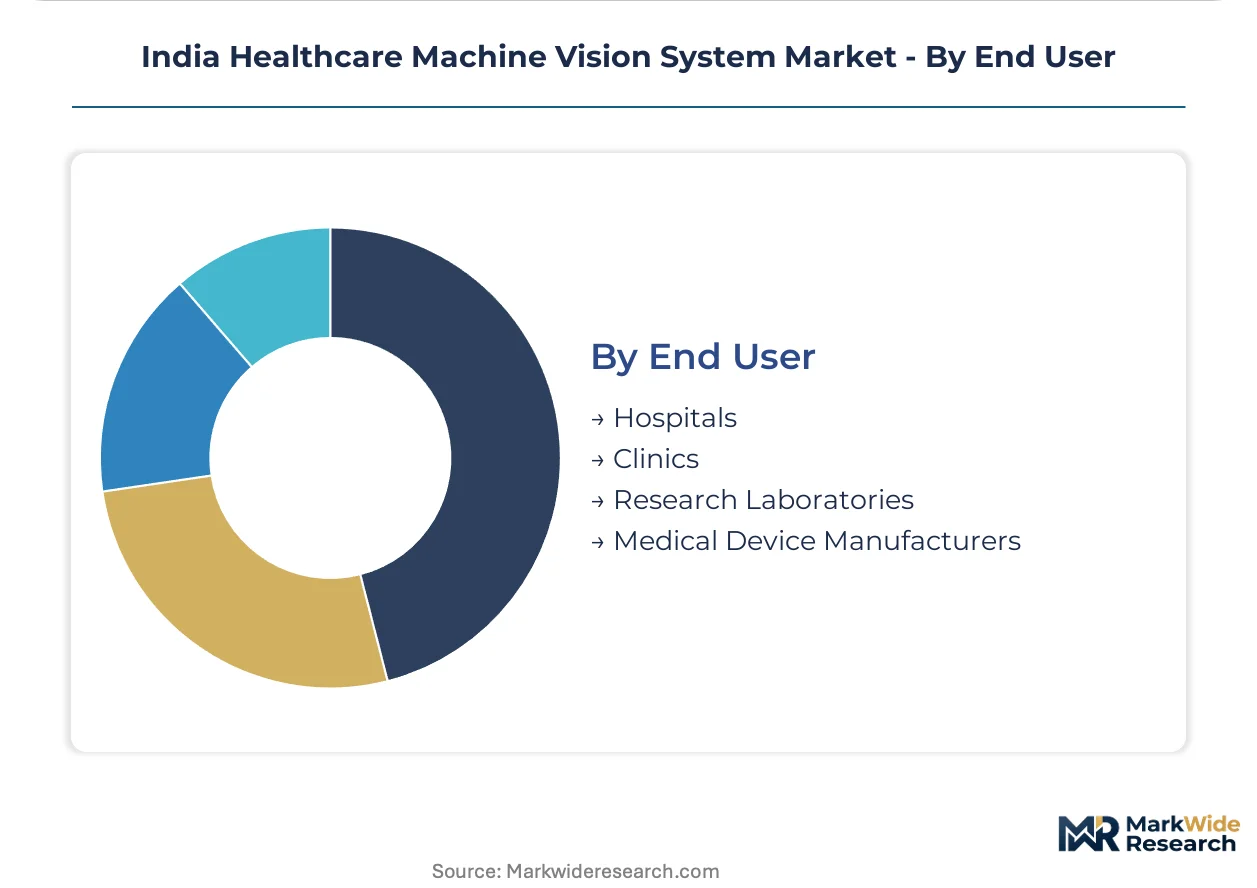
Healthcare machine vision procurement in India follows distinct technical and institutional pathways. Equipment replacement cycles vary dramatically between tertiary hospitals upgrading surgical suites and medical device manufacturers validating inline inspection systems for export compliance.
Product Type:
Upgrade trajectories diverge sharply between hardware-heavy diagnostic installations and software-centric AI deployments, with replacement cycles stretching from 5-7 years for optical hardware to 18-24 months for algorithmic components.
- Imaging Systems:Integrated hardware-software platforms combining high-resolution capture modules with real-time processing units. Maharashtra's medical device manufacturing corridor around Mumbai and Pune drives concentrated demand for systems validating packaging integrity under CDSCO export norms.
- Software Solutions:Algorithmic stacks enabling lesion classification, surgical navigation, and quality assurance workflows without dedicated hardware refresh. Delhi and Chennai tertiary hospitals are prioritizing these for tuberculosis screening and diabetic retinopathy programs where convolutional neural networks compress validation timelines.
- Optical Sensors:Specialized photodetectors and lens assemblies for sub-millimeter precision applications.
- Cameras:Diagnostic-grade capture devices exceeding 2 megapixel resolution thresholds and 30 fps frame rates.
Imaging Systems sits at the top of the volume ranking, with Software Solutions climbing the fastest.
Technology:
Cost tier stratification separates premium 3D surgical platforms from standardized 2D radiology tools, with mid-tier hospitals in Karnataka and Telangana gravitating toward hybrid configurations.
- 2D Vision:Established planar imaging technology for radiology workflows and basic quality inspection. Government hospitals in tier-II cities like Indore and Lucknow favor these systems for tuberculosis screening programs where budget constraints dominate procurement decisions.
- Deep Learning:Convolutional neural networks with attention mechanisms enabling real-time diagnostic inference without specialized hardware accelerators. Metropolitan tertiary centers in Bengaluru and Hyderabad are absorbing these for pathology automation despite CDSCO software-as-medical-device validation requirements.
- 3D Vision:Depth-sensing platforms delivering sub-millimeter accuracy for minimally invasive surgical navigation.
- Infrared Imaging:Thermal capture systems for tissue perfusion assessment and non-contact patient monitoring.
2D Vision commands the largest installed base, though Deep Learning is gaining share fastest among new deployments.
Application:
Application maturity varies from validated diagnostic imaging protocols to emerging surgical assistance deployments where clinical evidence requirements prolong procurement cycles.
- Diagnostic Imaging:Automated disease detection in radiology and pathology workflows with established clinical validation frameworks. CDSCO's tightened quality norms for Class C and D medical devices are accelerating hospital procurement of AI-powered screening tools for diabetic retinopathy and tuberculosis.
- Quality Control:Inline vision inspection for pharmaceutical packaging integrity and medical device traceability. Export-oriented manufacturers in Pune's medical device cluster deploy these systems to satisfy CDSCO documentation requirements for regulated markets.
- Surgical Assistance:Real-time navigation and tissue identification platforms for minimally invasive procedures.
- Patient Monitoring:Non-contact vital sign extraction and fall detection systems for ward automation.
Diagnostic Imaging dominates current revenue, with Quality Control expanding most quickly on manufacturing corridor investments.
End User:
Customer type determines procurement modality, with government hospitals favoring operational expenditure models and medical device manufacturers requiring capital-intensive inline validation systems.
- Hospitals:Tertiary and secondary care institutions deploying vision systems across radiology, pathology, and surgical departments. State health missions in Karnataka and Telangana are shifting diagnostic imaging procurement from capital budgets to annual software licensing contracts with bundled technical support.
- Medical Device Manufacturers:Production facilities integrating vision inspection for packaging integrity, label verification, and traceability compliance. The PLI scheme for domestic medical device manufacturing is creating captive demand for locally integrated systems serving export markets from Maharashtra and Gujarat.
- Clinics:Smaller diagnostic centers deploying portable or mid-tier imaging solutions.
- Research Laboratories:Academic and clinical research institutions piloting experimental algorithms and novel imaging modalities.
Hospitals represent the largest addressable base, while Medical Device Manufacturers show the steepest expansion trajectory on PLI scheme incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's healthcare machine vision industry traces its origins to the 1990s diagnostic imaging import wave, when multinational equipment suppliers established service networks in Mumbai and Delhi to support radiology modernization at tertiary hospitals.
Maharashtra
Mumbai and Pune anchor the nation's densest medical device manufacturing corridor, where export-oriented producers deploy inline vision systems for CDSCO-compliant packaging validation. The state's PLI scheme beneficiaries drive captive demand for automated inspection tools serving regulated markets in Europe and North America. Pune's medical device cluster concentrates quality control installations for pharmaceutical packaging integrity.
Karnataka
Bengaluru's hospital procurement is shifting from capital equipment purchases to annual software licensing contracts with bundled technical support. State health missions prioritize operational expenditure budgets over capital allocations for diagnostic imaging departments. The city's tertiary hospitals pilot deep learning platforms for tuberculosis screening under CDSCO software-as-medical-device guidelines.
Telangana
Hyderabad's diagnostic infrastructure expansion targets underpenetrated tier-II city networks with mid-tier hardware-software bundles. State procurement frameworks favor subscription-based diagnostic platforms that include algorithm updates and technical service. The city's medical technology corridor attracts vision system vendors establishing direct technical service networks.
Tamil Nadu
Chennai's tertiary hospitals absorb AI-powered screening tools for diabetic retinopathy despite extended BIS electromagnetic compatibility certification timelines. CDSCO's tightened quality norms for Class C and D medical devices accelerate hospital validation of automated visual inspection capabilities. The city's manufacturing base integrates vision systems for medical device traceability compliance.
Delhi-NCR
Government hospitals in the capital region replace upfront procurement with operational expenditure models for diagnostic imaging software. CDSCO mandates quality management system certification for vision system deployments in public health programs. The region's research laboratories pilot experimental algorithms for pathology automation under evolving regulatory frameworks.
India Healthcare Machine Vision System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the software-hardware integration spectrum, with algorithmic solution vendors capturing value from diagnostic workflows while component suppliers compete on sensor specifications and frame rates. The vendor base stratifies into three tiers: multinational system integrators with direct service networks, domestic AI specialists with regulatory navigation expertise, and optical component distributors serving manufacturing quality control. Market consolidation pressures favor acquisition of algorithm validation capabilities and backward integration into sensor supply.
Among multinational system integrators, Cognex Corporation and Keyence Corporation exemplify contrasting channel strategies—one anchoring premium diagnostic deployments through deep learning software stacks, the other sustaining market position through technical service density in Bengaluru and Hyderabad. Domestic specialist SigTuple occupies a distinct position in clinical laboratory automation, representing the AI-native archetype that CDSCO's software-as-medical-device guidelines most directly affect.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| Basler AG |
| Teledyne Technologies Incorporated |
| Omron Corporation |
| SICK AG |
| GE HealthCare Technologies Inc. |
| Qure AI |
| SigTuple |
| Others |
Pricing and Supply Chain Analysis
Tertiary hospital procurement committees concentrated in Maharashtra and Karnataka dictate pricing power through operational expenditure models that favor subscription-based software licensing over capital equipment purchases. CDSCO's software-as-medical-device classification requirements inflate compliance costs, compressing margins for vendors while creating pricing premiums for validated algorithmic solutions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated surgical navigation platforms from mid-tier radiology tools and basic quality inspection modules. Certification grade under CDSCO guidelines and algorithm validation depth drive price differentiation, with Class C and D medical device compliance adding substantial cost layers. Pricing pressure stems from government hospitals shifting to annual licensing contracts that bundle technical support. Medical device manufacturers show least price sensitivity due to PLI scheme incentives, while tier-II city hospitals absorb maximum budget constraints.
Supply Chain Analysis
Assembly of high-resolution optical sensors draws from specialized engineering talent pools in Taiwan, Japan, and South Korea, where precision manufacturing expertise concentrates. CMOS image sensors, specialized lens assemblies, and FPGA processing units anchor raw material dependencies. Single-source vulnerability for sub-2 megapixel diagnostic-grade cameras exposes buyers to East Asian logistics disruptions. Distribution runs through direct technical service networks in Bengaluru and Hyderabad, bypassing traditional distributor markups for enterprise hospital accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Healthcare Machine Vision System Market compounds steadily as CDSCO regulatory mandates force continuous compliance investment cycles across hospital and manufacturing end uses.
For Market Incumbents: Acquire algorithm validation capabilities to defend against AI-native entrants exploiting CDSCO software-as-medical-device uncertainty. Backward integration into optical sensor supply reduces currency volatility exposure from East Asian procurement. Channel control through direct technical service networks in Bengaluru and Hyderabad remains the critical lever for margin defense. For New Entrants and Emerging Players: Enter via tier-II city hospital networks in Indore, Lucknow, and Coimbatore where diagnostic infrastructure remains underpenetrated and procurement favors mid-tier hardware-software bundles. Pharmaceutical quality assurance convergence offers whitespace for spectroscopic-vision hybrid platforms. Go-to-market through state health mission operational expenditure frameworks bypasses capital budget competition. For Investors and Strategic Acquirers: Medical device manufacturers are the most active acquirer in this space, seeking captive vision inspection capabilities for export compliance. Long-term viability centers on regulatory navigation expertise rather than pure algorithmic performance. Watch CDSCO's final software-as-medical-device guidelines as the inflection signal for valuation repricing of AI diagnostic assets.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Software Validation Pathway | Pre-market algorithm review secures premium positioning in tertiary hospital procurement. |
| Hospital System Partnership | State health mission contracts in Karnataka and Telangana lock recurring revenue streams. |
| Backward Integration into Sensors | In-house optical component supply mitigates East Asian currency and logistics exposure. |
| PLI Scheme Manufacturing Alignment | Domestic integration qualifies vision systems for medical device production incentives. |
| Deep Learning Platform Expansion | Convolutional neural network deployment for tuberculosis screening captures government program demand. |
Research Methodology
Direct dialogue with hospital procurement committees, biomedical engineers, CDSCO regulatory affairs specialists, and medical device manufacturing quality heads grounded qualitative findings. Secondary validation drew from CDSCO medical device registration databases, BIS certification records, PLI scheme beneficiary disclosures, and state health mission budget allocations. Bottom-up equipment deployment counts triangulated against top-down healthcare infrastructure investment flows.
Segment-level revenue estimates emerged from modeling across product type, technology architecture, clinical application, and end-user procurement modality through the projection horizon. CAGRs derived from equipment replacement cycle analysis, algorithm refresh timelines, and regulatory compliance investment patterns. Deep learning adoption curves and CDSCO software-as-medical-device implementation timelines served as India-specific forecast inputs.
Inputs from hospital procurement databases and manufacturing facility surveys were available through the study window; gaps in tier-II city diagnostic infrastructure deployment introduce uncertainty bands around penetration rate assumptions. Forecasts reflect documented assumptions regarding CDSCO guideline finalization and PLI scheme continuation. Material deviation in CDSCO software classification enforcement or East Asian supply chain disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Medical Chairs Market
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
Ophthalmic Examination Chairs Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Global Hospital Asset Management Market
Healthcare Equipment
Skin Cooling Systems Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Microbiological Safety Cabinets Market
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
Middle East and Africa Ultrasound Probe Disinfection Market
Healthcare Equipment
Medical Waste Supervision Solution Market
Healthcare Equipment
Emergency Hospital Beds Market
Healthcare Equipment
Healthcare Personal Protection Equipment Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
Specialty Medical Chairs Market