
 Medical Cold Storage Market | 2026-2036
Medical Cold Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Cold Storage Market Insights
Remote temperature monitoring subscriptions is realigning how cold storage vendors monetize hardware deployments. Thermo Fisher Scientific leverages its connected platform ecosystem to sustain recurring revenue from biopharma clients. Haier Biomedical anchors its competitive position through manufacturing scale across Asia and Europe. PHC Holdings Corporation specializes in ultra-low temperature systems that dominate the biological sample storage segment.
Medical cold storage encompasses engineered refrigeration and freezing systems designed to maintain precise temperature bands, typically from standard refrigeration at 2°C to 8°C down to cryogenic conditions below -150°C, using insulated enclosures, compressor-driven vapor compression cycles, and multi-layered gasketing to protect temperature-sensitive pharmaceuticals, vaccines, blood products, and biological specimens from degradation. Freezers and cryogenic storage units command the deepest margin pools due to the technical complexity of cascade and liquid nitrogen backup systems required for cell therapy materials. Blood banks and hospital pharmacies represent the most replacement-intensive end-user categories as regulatory audit cycles force equipment refresh timelines.
FDA, EMA, and WHO standards collectively govern qualification protocols, temperature mapping documentation, and alarm responsiveness that determine which equipment platforms gain market access in regulated jurisdictions. The EU MDR and F-Gas Regulation are tightening refrigerant specifications and energy efficiency benchmarks that manufacturers must integrate into next-generation compressor designs. Stakeholders should monitor how evolving cell therapy logistics requirements reshape the balance between on-site cryogenic infrastructure and centralized biorepository outsourcing models.
Market Dynamics
Cell therapy commercialization timelines are compressing qualification protocols for cryogenic infrastructure, forcing equipment vendors to pre-validate systems before site delivery rather than conduct post-installation commissioning.
Growth Catalysts
- EMA's Advanced Therapy Medicinal Products framework:The regulation mandates auditable cold-chain documentation for gene therapies, compelling European biomanufacturers to upgrade freezer fleets with integrated data-logging capabilities.
- Plasma fractionation expansion:Blood processing facilities in India and Brazil are scaling cryopreservation capacity to meet immunoglobulin demand, driving freezer procurement in emerging pharmaceutical manufacturing clusters.
- Liquid nitrogen backup systems:The technology is becoming standard specification for cell therapy storage, as cascade compressor failures risk millions in irreplaceable patient doses.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger materials constitute 15-20% of freezer manufacturing costs, compressing margins when commodity markets spike.
- Compressor supply concentration:German and Japanese OEMs dominate high-efficiency refrigeration compressors, creating single-source vulnerability for mid-tier freezer assemblers.
- F-Gas Regulation phase-down:The EU mandate restricts hydrofluorocarbon refrigerants with high global warming potential, forcing costly R&D pivots toward natural refrigerant architectures.
Strategic Opportunities
- Biorepository outsourcing models:Academic medical centers in the United States are divesting on-site cryogenic infrastructure to specialized third-party storage operators, opening service-contract revenue streams.
- Remote temperature monitoring convergence:IoT sensor platforms and cloud analytics are merging into subscription-based offerings that lock in multi-year client relationships beyond hardware sales.
- India's PLI scheme for medical devices:The production-linked incentive program subsidizes domestic cold storage manufacturing, attracting joint ventures between multinational OEMs and local contract manufacturers.
Industry Challenges
- Temperature mapping technician shortage:Qualified validation engineers capable of executing IQ/OQ/PQ protocols for ultra-low temperature units command premium salaries that strain regional service networks.
- Integration complexity with building management systems:Hospital IT departments struggle to normalize alarm protocols across mixed-vendor freezer fleets, delaying regulatory audit approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Cold Storage Market |
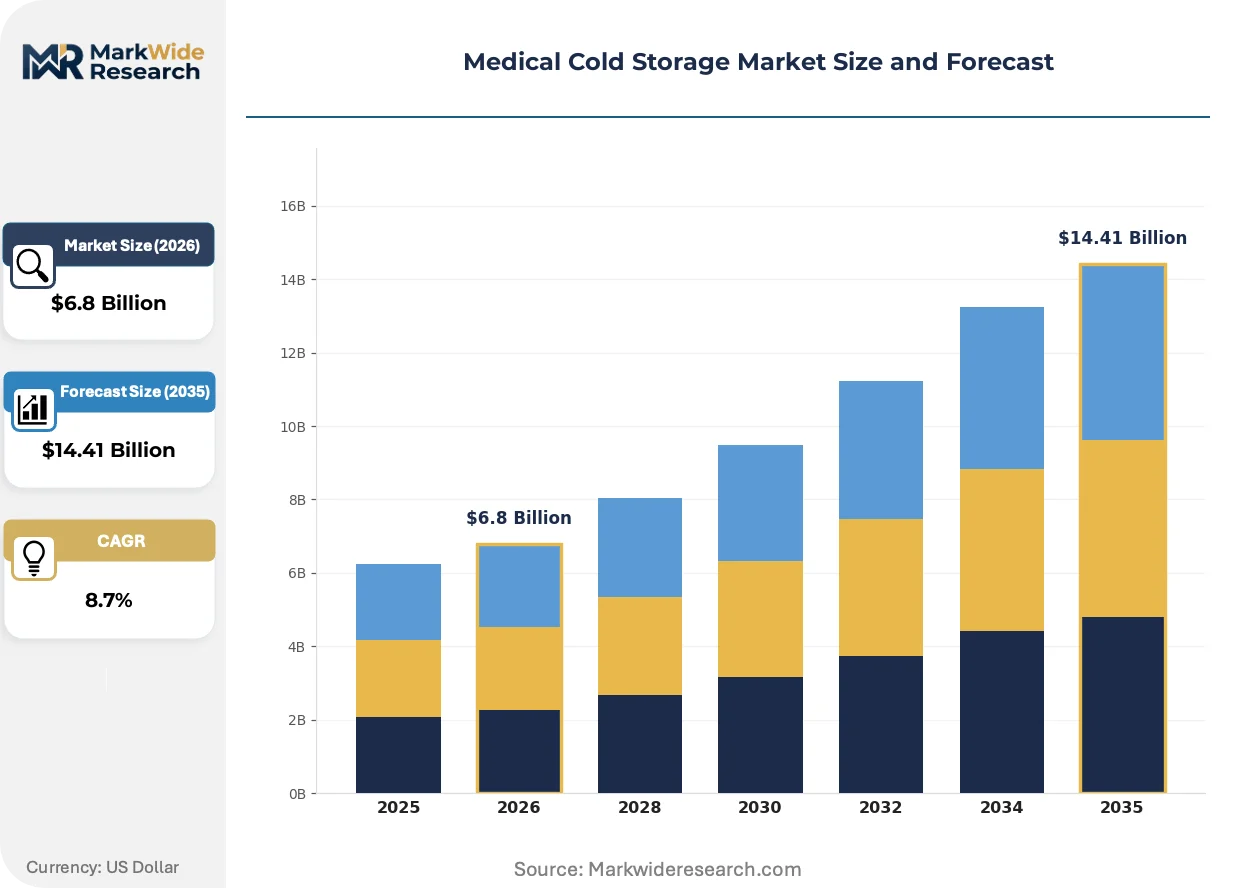
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Freezers, Walk-in Cold Rooms, Cryogenic Storage Units End User: Hospitals, Clinics, Laboratories, Blood Banks Technology: Vapor Compression, Thermoelectric, Absorption, Cascade Systems Application: Pharmaceutical Storage, Vaccine Preservation, Blood Storage, Biological Sample Storage |
| Companies Covered | Thermo Fisher Scientific, Haier Biomedical, PHC Holdings Corporation, Helmer Scientific, BioLife Solutions, Panasonic Healthcare, Binder, Azenta, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Cold Storage Market Trends and Innovations
Stirling engine freezers are disrupting vapor-compression dominance in biological sample preservation, while regulatory pressure on refrigerant chemistry accelerates equipment replacement cycles ahead of normal depreciation schedules.
Stirling engine cryogenic technology eliminates compressor-based failure modes through closed-cycle helium displacement, delivering temperature uniformity within ±1°C across storage chambers. Biobanks and contract research organizations are adopting these units for irreplaceable specimen collections despite 40% capital cost premiums. The technology is expanding into cell therapy manufacturing suites where compressor vibration risks sample integrity.
The EU F-Gas Regulation mandates 79% reduction in hydrofluorocarbon consumption by 2030, prohibiting common refrigerants in new medical freezer deployments. Manufacturers are retooling assembly lines for propane and carbon dioxide-based systems, extending product development timelines by 18-24 months. Blood bank procurement committees in Germany and France now prioritize natural refrigerant models in tender specifications, anticipating compliance deadlines.
Biopharma procurement teams are unbundling hardware purchases from validation and calibration services, treating cold storage as operational expenditure through multi-year service agreements. Equipment vendors respond with remote diagnostics platforms that reduce on-site technician dispatch frequency. This model is penetrating fastest among mid-sized contract development and manufacturing organizations in the United States seeking to preserve capital for drug pipeline investment.
Medical Cold Storage Market Segmentation
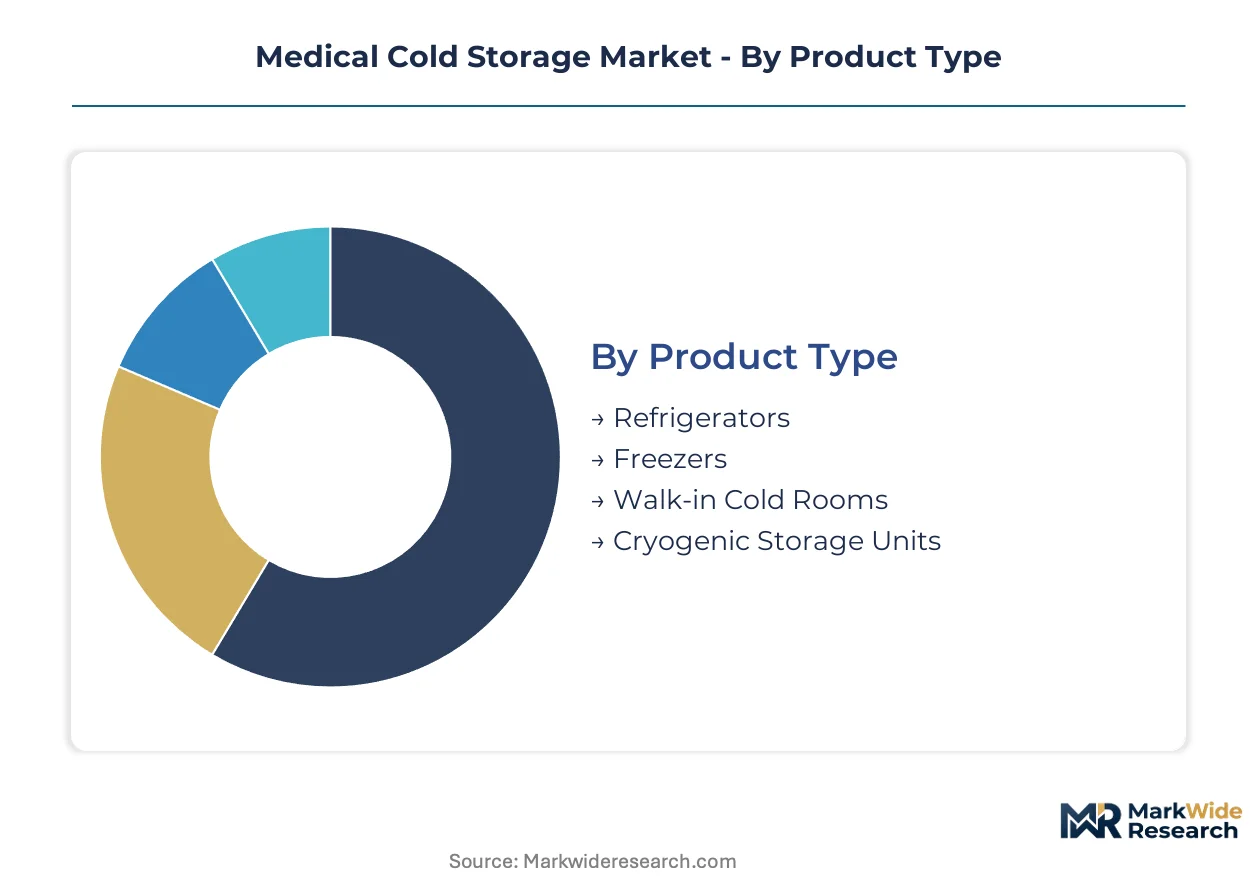
Equipment specifications in medical cold storage diverge sharply across temperature bands, regulatory jurisdictions, and end-user risk tolerances. Segmentation reveals how procurement priorities shift from standard refrigeration in hospital pharmacies to cryogenic infrastructure for cell therapy manufacturing.
Product Type:
Customization intensity escalates from mass-produced pharmacy refrigerators to engineered cryogenic systems with redundant cooling architectures.
- Refrigerators:Compressor-driven units maintaining 2°C to 8°C for vaccine and pharmaceutical storage. Demand concentrates in United States hospital pharmacies refreshing fleets to meet FDA temperature mapping guidance.
- Freezers:Ultra-low temperature systems operating at -40°C to -86°C using cascade or Stirling engine technology. Biopharma manufacturers in Germany and Switzerland deploy these for biological sample preservation, driven by EMA audit documentation requirements.
- Walk-in Cold Rooms:Modular insulated enclosures for bulk pharmaceutical storage. Blood processing facilities in India expand capacity to support plasma fractionation growth.
- Cryogenic Storage Units:Liquid nitrogen or mechanical systems below -150°C for cell therapy materials. Leading the category by volume: Freezers. Growing fastest: Cryogenic Storage Units.
Leading the category by volume: Freezers. Growing fastest: Cryogenic Storage Units.
End User:
Procurement sophistication varies from standardized blood bank tenders to bespoke biopharma qualification protocols.
- Hospitals:Multi-department deployments spanning pharmacy, pathology, and research functions. Replacement cycles accelerate in Germany as university hospitals consolidate vendor relationships.
- Clinics:Smaller-scale refrigeration for vaccine and biologic administration. United States outpatient networks prioritize connected monitoring platforms for regulatory compliance.
- Laboratories:Precision temperature control for research specimens. Contract research organizations in Switzerland drive demand for Stirling engine freezers to eliminate compressor vibration risks.
- Blood Banks:High-availability systems with 24/7 monitoring and redundant cooling. India's expanding immunoglobulin production capacity fuels procurement in this segment.
Replacement intensity peaks in Blood Banks; Laboratories show steepest expansion trajectory.
Technology:
Energy efficiency mandates and refrigerant phase-downs are reordering technology adoption curves.
- Vapor Compression:Dominant architecture using mechanical compressors with synthetic or natural refrigerants. EU F-Gas Regulation compliance costs are compressing margins for manufacturers dependent on hydrofluorocarbon systems.
- Thermoelectric:Solid-state cooling via Peltier effect for small-volume, precise temperature applications. Point-of-care diagnostic deployments in Japan favor these units for portability and vibration-free operation.
- Absorption:Heat-driven systems using ammonia-water or lithium bromide solutions. Remote clinic installations in India leverage solar thermal integration where electrical infrastructure is unreliable.
- Cascade Systems:Staged refrigeration circuits achieving ultra-low temperatures through refrigerant combination. Cell therapy manufacturers in the United States specify these with liquid nitrogen backup for irreplaceable patient doses.
Vapor Compression retains dominant share; Cascade Systems gain fastest on cell therapy demand.
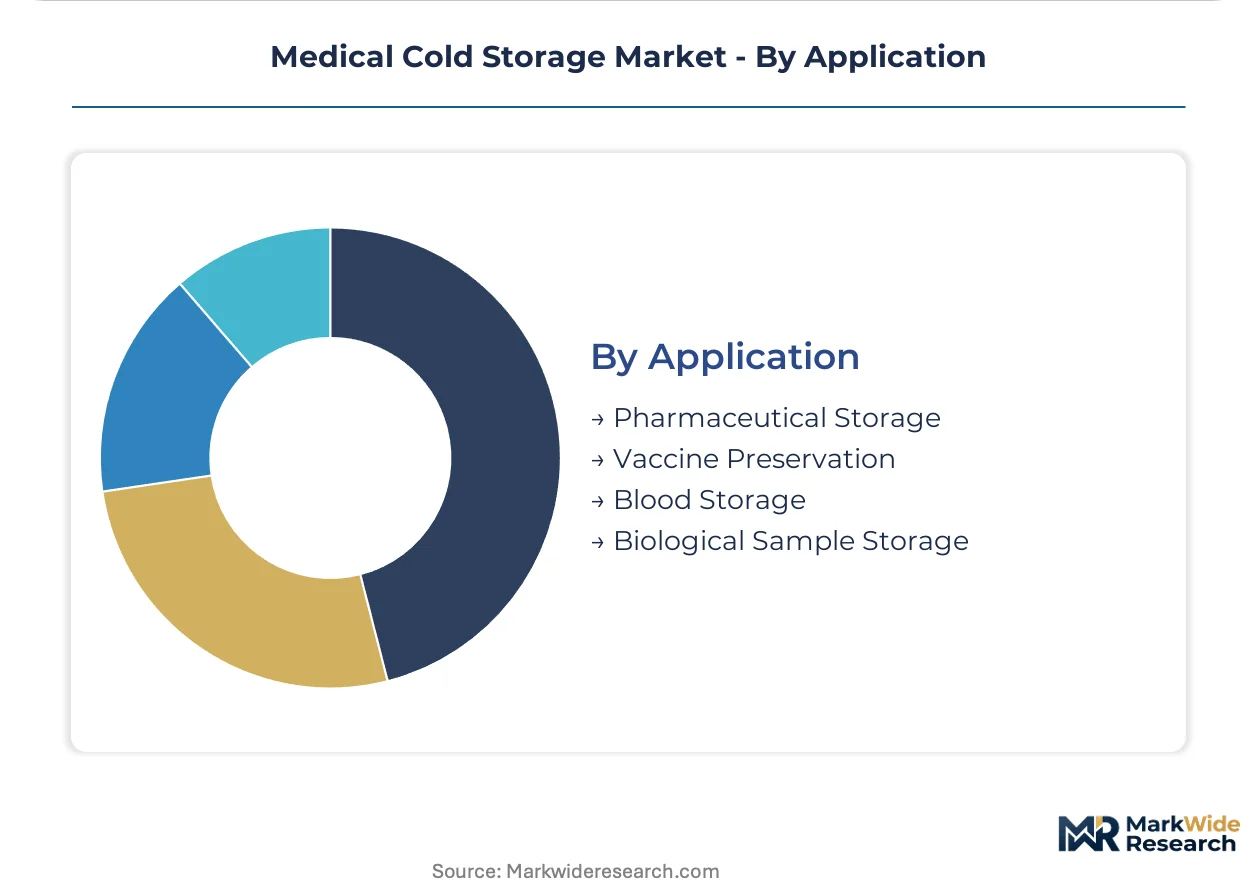
Application:
Regulatory stringency intensifies from pharmaceutical storage through to biological specimens with irreplaceable value.
- Pharmaceutical Storage:Temperature-controlled environments for drug products and active ingredients. United States distribution hubs upgrade monitoring capabilities to satisfy FDA distribution guidance.
- Vaccine Preservation:Cold chain maintenance from manufacture through last-mile administration. National immunization programs in Brazil and India drive procurement of solar-compatible refrigeration.
- Blood Storage:Whole blood and component preservation at 1°C to 6°C with continuous temperature logging. German and French blood services prioritize natural refrigerant models anticipating F-Gas deadlines.
- Biological Sample Storage:Cryogenic preservation of tissues, cells, and genetic material. Academic biobanks in Switzerland and the United States outsource infrastructure to specialized third-party operators.
Pharmaceutical Storage anchors volume; Biological Sample Storage expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and China, while consumption concentrates in the United States and Western Europe where biopharma R&D spending drives equipment procurement cycles.
United States
Hospital pharmacy replacement cycles and cell therapy manufacturing expansion drive equipment procurement. FDA temperature mapping guidance for vaccine storage compels freezer fleet upgrades. Boston and San Francisco biotech clusters prioritize liquid nitrogen backup systems for irreplaceable patient doses.
Germany
University hospital consolidation and blood service modernization sustain replacement demand. EMA Advanced Therapy Medicinal Products documentation requirements mandate integrated data-logging capabilities. The Rhine-Ruhr and Bavarian medical technology corridors concentrate ultra-low temperature freezer production capacity.
China
Domestic biopharma manufacturing scale-up and plasma fractionation facility construction propel cryogenic infrastructure investment. NMPA GMP enforcement tightens temperature validation protocols. Shanghai and Suzhou biotech parks anchor regional demand for Stirling engine freezer technology.
India
Immunoglobulin production expansion and blood bank network modernization drive freezer procurement. PLI scheme subsidies attract multinational joint ventures for domestic manufacturing. Hyderabad and Mumbai pharmaceutical clusters scale cryopreservation capacity for export-oriented plasma processing.
Switzerland
Contract research organization specimen preservation and biobank outsourcing sustain premium equipment demand. Swissmedic audit documentation requirements enforce rigorous qualification protocols. The Basel biopharma corridor and Zurich academic medical centers deploy vibration-free Stirling systems for irreplaceable biological collections.
Medical Cold Storage Market Competitive Landscape
Top-tier vendors anchor the premium cryogenic segment, while mid-tier assemblers compete on price-sensitive hospital pharmacy replacements. The market structure stratifies across three archetypes: diversified laboratory conglomerates with connected platform ecosystems, specialized biomedical refrigeration manufacturers with regional manufacturing scale, and emerging Asian fabricators leveraging cost-advantaged production. Competitive moves concentrate on strategic partnerships for cell therapy qualification protocols and backward integration into compressor supply chains.
Among diversified laboratory technology conglomerates, Thermo Fisher Scientific occupies a position exemplifying connected platform monetization strategies. Haier Biomedical represents the manufacturing-scale archetype with Asia-Europe production footprints. PHC Holdings Corporation anchors the ultra-low temperature specialization tier, with its corporate structure reflecting Japanese precision equipment heritage.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Haier Biomedical |
| PHC Holdings Corporation |
| Helmer Scientific |
| BioLife Solutions |
| Panasonic Healthcare |
| Binder |
| Azenta |
| Cardinal Health |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between GMP-validated cryogenic systems and standard hospital pharmacy units manifests in both procurement premiums and supply chain complexity, with EMA and FDA qualification protocols forcing tier-specific sourcing strategies across compressor technologies and validation service networks.
Pricing Analysis
Margin tightening in mid-tier freezer assemblies reflects copper and aluminum commodity volatility that consumes 15-20% of manufacturing costs. Three-tier pricing structure across premium, standard, and economy levels separates liquid nitrogen backup systems from cascade compressors from basic vapor-compression units. Cost-down pressure on standard refrigeration accelerates because blood bank procurement committees in Germany and France now mandate natural refrigerant models. Hospital pharmacies exhibit highest price sensitivity; cell therapy manufacturers show lowest.
Supply Chain Analysis
Refurbishment flows for ultra-low temperature units create secondary market channels that compete with OEM service contracts in the United States and Western Europe. Manufacturing capacity clusters in Germany, China, and Japan, with compressor supply anchored in German and Japanese OEMs. Heat exchanger materials draw from copper and aluminum supply chains exposed to commodity volatility. Single-source vulnerability in high-efficiency compressor supply creates structural risk. Distribution runs through direct OEM relationships with biopharma manufacturers and GPO contracts with hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited validation engineer supply constrains equipment deployment velocity, sustaining pricing power for vendors with captive service capabilities.
For Market Incumbents: Extend connected platform ecosystems to lock in recurring revenue from remote temperature monitoring subscriptions. Deepen backward integration into compressor supply chains to mitigate single-source vulnerability from German and Japanese OEMs. Counter Stirling engine disruption by acquiring vibration-free cooling specialists.
For New Entrants and Emerging Players: Enter via India's PLI-subsidized manufacturing corridors to bypass tariff exposure and establish cost-advantaged production. Target blood bank modernization in Brazil and India where procurement sophistication lags Western Europe. Lead with solar-compatible absorption refrigeration for vaccine preservation in electrical infrastructure-constrained regions.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified laboratory conglomerates seeking cryogenic specialization. Five-to-ten year viability hinges on cell therapy commercialization velocity and refrigerant regulatory compliance costs. Monitor F-Gas Regulation phase-down timelines and natural refrigerant R&D completion rates as inflection indicators for equipment replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA Advanced Therapy Medicinal Products documentation requirements mandate integrated data-logging capabilities for European market access. |
| Hospital System Partnership | United States academic medical centers divest on-site cryogenic infrastructure to specialized third-party storage operators. |
| Backward Integration | Compressor supply concentration in German and Japanese OEMs creates vulnerability for mid-tier freezer assemblers. |
| Software Companion Development | IoT sensor platforms merge into subscription-based offerings that sustain multi-year client relationships beyond hardware sales. |
| Reimbursement Strategy | Cell therapy logistics requirements reshape balance between on-site cryogenic infrastructure and centralized biorepository outsourcing. |
Research Methodology
Independent corroboration across equipment vendor sales directors, hospital biomedical engineers, and blood bank procurement managers underwrites the qualitative findings. Primary interviews with GPO contracts managers and cell therapy manufacturing executives combined with secondary validation from FDA guidance documents, EMA submission databases, and hospital procurement records. Bottom-up and top-down triangulation cross-checks equipment shipment data against end-user replacement cycle surveys.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window. Segmentation dimensions modeled include temperature band, end-user risk tolerance, and regulatory jurisdiction cluster. CAGRs derive from equipment replacement cycle analysis and biopharma R&D spending trajectories. Cell therapy commercialization timelines and F-Gas Regulation compliance deadlines feed into forecast sensitivity testing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under refrigerant chemistry pivot delays and compressor supply disruption scenarios. Practitioners should monitor copper and aluminum commodity indices and EMA audit documentation requirement updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Middle East and Africa Hospital Furniture Market
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
Skin Cooling Systems Market
Healthcare Equipment
Specialty Medical Chairs Market
Healthcare Equipment
Global Hospital Asset Management Market
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
Medical Waste Supervision Solution Market
Healthcare Equipment
Healthcare Personal Protection Equipment Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Emergency Hospital Beds Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Ophthalmic Examination Chairs Market
Healthcare Equipment
Middle East and Africa Ultrasound Probe Disinfection Market
Healthcare Equipment
Patient Infotainment Terminals Market