
 Patient Recliner Chair Market | 2026-2036
Patient Recliner Chair Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Recliner Chair Market Insights
Hospital procurement consolidation is recalibrating how manufacturers allocate sales resources and service infrastructure. Stryker Corporation leverages its integrated bed-to-chair ecosystem to capture bundled contract opportunities. Hill-Rom sustains clinical credibility through intensive R&D investment in pressure-relief surfaces. Steelcase competes by applying commercial furniture scale to healthcare-adjacent lounge and waiting-room recliner segments.
A patient recliner chair is an adjustable seating device engineered for medical and long-term care environments, typically incorporating steel or aluminum framing, high-density polyurethane foam cushioning, and infection-resistant upholstery rated for hospital-grade disinfection cycles; its primary purpose is to support patient mobility, clinical procedures, and extended recovery periods in supervised settings. Power recliners command premium positioning due to motorized positioning systems that reduce caregiver strain, while manual recliners occupy high-volume contract tiers where capital budgets constrain electrification. Home care represents the fastest-growing end-user channel as post-acute discharge protocols shorten institutional stays and shift recovery monitoring to residential settings.
The FDA regulates powered patient recliners as Class II medical devices under 510(k) premarket notification requirements, compelling manufacturers to validate electrical safety and electromagnetic compatibility before commercial distribution. The Centers for Medicare & Medicaid Services shapes reimbursement eligibility for home-use lift chairs through durable medical equipment coding, directly influencing consumer affordability and manufacturer pricing strategy. Stakeholders must monitor evolving CMS competitive bidding rules and state-level Medicaid expansion decisions that determine addressable volume in the home care segment.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while forcing manufacturers to restructure service networks around long-term bundled contracts rather than transactional equipment sales.
Growth Catalysts
- CMS DME Reimbursement Expansion:The Centers for Medicare & Medicaid Services has broadened durable medical equipment coding for home-use lift chairs, directly expanding consumer affordability and manufacturer addressable volume in residential recovery settings.
- Steel-Framed Power Positioning:Motorized recliner systems incorporating hospital-grade steel framing and electromagnetic compatibility certification are penetrating skilled nursing facilities seeking to reduce caregiver injury rates and workers compensation exposure.
- India Home Care Infrastructure:The country's Ayushman Bharat health mission and expanding private home nursing networks are creating first-time demand for infection-resistant patient seating in metropolitan residential clusters.
Market Restraints
- Aluminum Price Volatility:Input cost swings for lightweight framing materials squeeze margin stability for mid-tier manufacturers lacking forward purchase agreements with primary metal suppliers.
- FDA 510(k) Timeline Friction:The premarket notification pathway for powered recliners creates six-to-eighteen month commercialization delays that deter rapid product iteration and freeze development capital.
- Manual Recliner Substitution:Budget-constrained long-term care facilities in rural United States counties continue specifying hand-operated mechanisms despite caregiver ergonomic penalties.
Strategic Opportunities
- Brazil ANVISA Fast-Track:The national health surveillance agency's streamlined medical device registration for Class II products with prior FDA clearance opens accelerated market entry for certified manufacturers.
- Telehealth-Integrated Seating:Convergence of embedded biometric sensors and remote patient monitoring platforms creates premium positioning for recliners capable of transmitting vital signs during home-based recovery.
- Direct-to-Consumer E-Commerce:Specialized medical equipment marketplaces are disintermediating traditional durable medical equipment distributors, enabling manufacturers to capture margin previously allocated to regional dealer networks.
Industry Challenges
- Electromagnetic Compatibility Engineering Talent:Shortage of specialists capable of designing powered recliner systems that satisfy FDA electrical safety validation without redesign cycles is extending development timelines.
- Legacy EHR Integration Complexity:Biometric-enabled recliners face interoperability friction with fragmented electronic health record systems across United States hospital networks, requiring costly custom API development.
- ISO 13485 Certification Burden:Medical device quality management system audits demand sustained quality engineering headcount that strains mid-cap manufacturer overhead structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Recliner Chair Market |
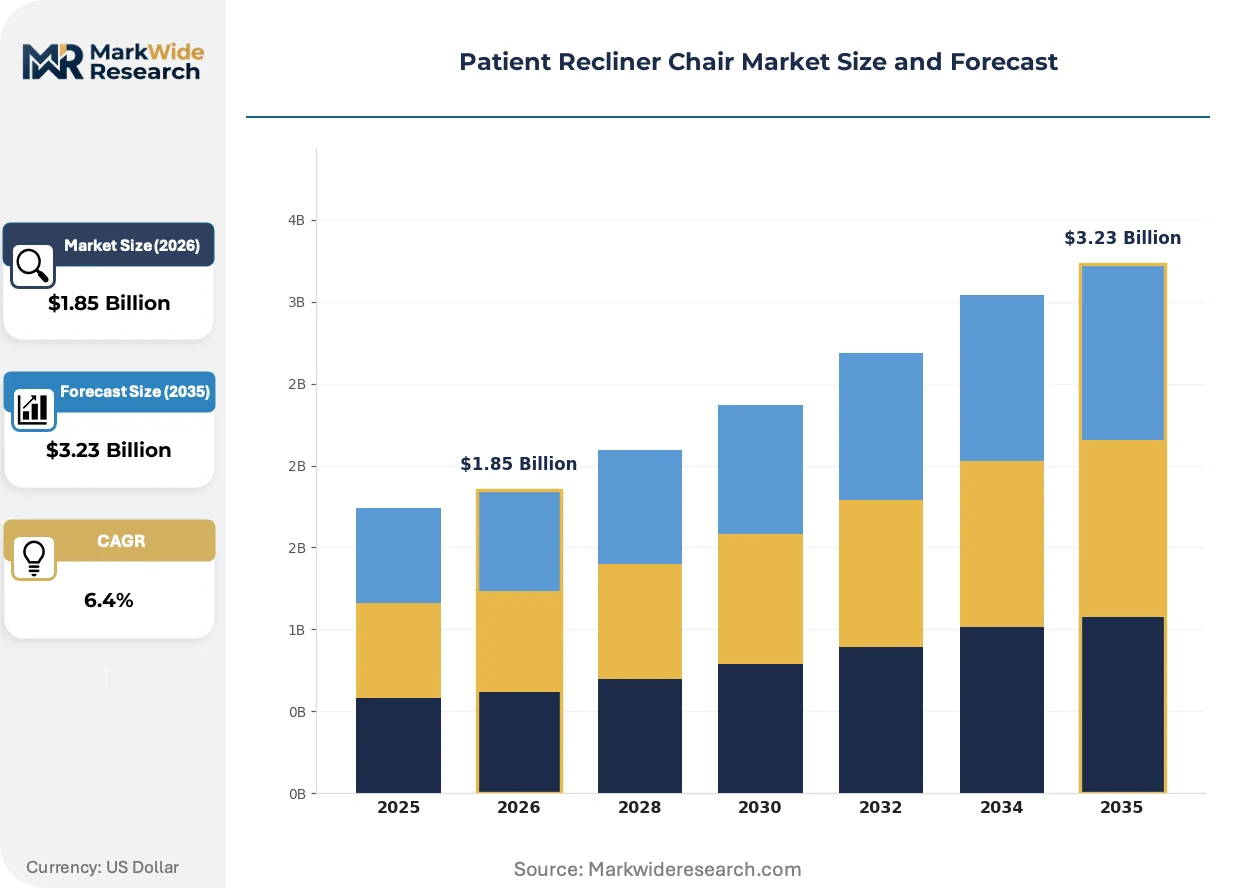
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Recliner, Power Recliner, Lift Chair, Adjustable Recliner End User: Hospitals, Nursing Homes, Home Care, Rehabilitation Centers Material: Fabric, Leather, Vinyl, Foam Feature: Heat Function, Massage Function, Cup Holders, Storage Compartments |
| Companies Covered | Stryker Corporation, Hill-Rom, Steelcase, Medline Industries, Drive DeVilbiss International, Krueger International, Nemschoff, Ocelco, La-Z-Boy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Recliner Chair Market Trends and Innovations
Actively reshaping patient recliner development is the convergence of clinical ergonomics with residential aesthetics, as manufacturers engineer products that satisfy hospital disinfection protocols while blending into home interiors.
Brushless DC motor systems with integrated position memory are electrifying the transition from manual to powered recliner architectures across skilled nursing and acute care settings. Stryker and Hill-Rom are accelerating electrification in their latest contract bids. This technology is compressing the price premium between powered and manual configurations while standardizing caregiver workflow protocols.
The European Union's Medical Device Regulation (MDR) is tightening clinical evidence requirements for powered patient seating previously grandfathered under the Medical Device Directive. Manufacturers must now generate post-market surveillance data and update technical documentation for CE marking renewal. Powered recliners with therapeutic positioning claims face the steepest compliance burden, with several suppliers withdrawing marginal SKUs rather than absorbing MDR certification costs.
Hospital supply chain directors are unbundling after-sales service from equipment purchase contracts, negotiating separate multi-year maintenance agreements with third-party clinical engineering firms. This disintermediation is disrupting traditional manufacturer service revenue streams. The United States exhibits the most aggressive unbundling, with IDN procurement officers demanding itemized service pricing transparency that exposes historical margin cross-subsidies.
Patient Recliner Chair Market Segmentation
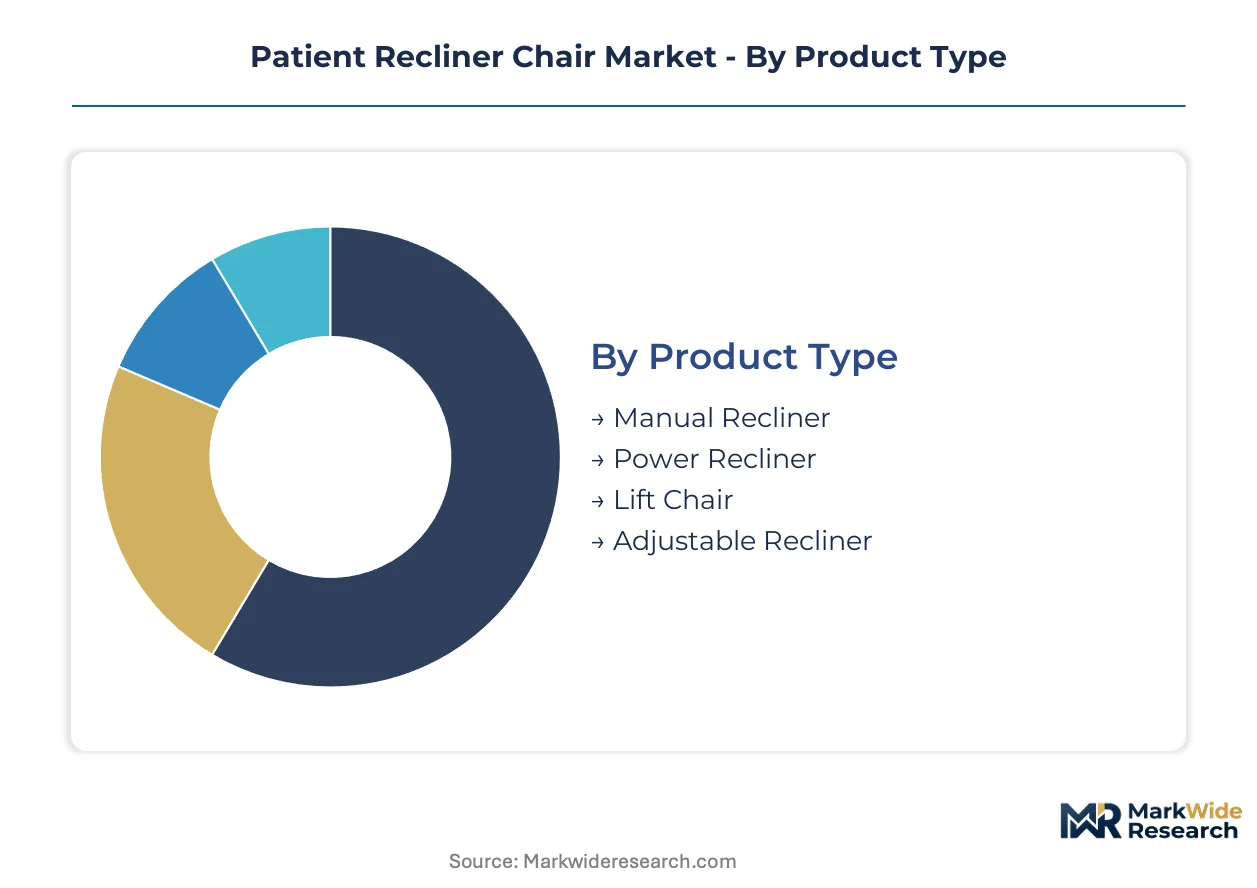
Patient recliner chair segmentation reveals distinct technology-performance tradeoffs across clinical and residential settings. Procurement patterns diverge sharply between capital-constrained institutional buyers and reimbursement-supported home care consumers.
Product Type:
Electrification intensity and caregiver ergonomics define the specification hierarchy across recliner architectures.
- Power Recliner:Motorized positioning systems with brushless DC drives and electromagnetic compatibility certification enable single-caregiver operation in bariatric and post-surgical recovery. Demand concentrates in United States skilled nursing facilities seeking workers compensation reduction through mechanical lift elimination.
- Manual Recliner:Hand-lever or body-weight mechanisms with steel spring suspension occupy high-volume contract tiers where capital budgets constrain electrification. Rural United States long-term care facilities continue specifying these despite caregiver strain penalties.
- Lift Chair:Dual-motor systems combining recline with powered stand-assist satisfy aging-in-place policies expanding CMS durable medical equipment reimbursement.
- Adjustable Recliner:Modular frame systems with interchangeable back angles and seat depths accommodate bariatric patient populations in acute care discharge planning.
Mature deployment sits with Manual Recliner. Newer deployment is concentrated in Lift Chair.
End User:
Care setting reimbursement structures and length-of-stay protocols determine volume allocation across the patient journey.
- Home Care:Post-acute discharge compression and remote patient monitoring expansion are shifting recovery monitoring to residential settings fastest. United States metropolitan clusters with established home nursing networks drive specification of infection-resistant upholstery rated for residential disinfection cycles.
- Hospitals:Integrated delivery network procurement consolidation favors bundled bed-to-chair contracts with multi-year service agreements. Stryker and Hill-Rom compete through embedded clinical engineering support.
- Nursing Homes:Medicaid reimbursement rate pressure in United States state programs constrains capital refresh cycles toward manual configurations.
- Rehabilitation Centers:Outpatient therapy protocols specify durable steel framing for high-frequency position adjustment during physical therapy sessions.
Volume leadership remains with Hospitals. Steepest expansion trajectory belongs to Home Care.
Material:
Surface durability and disinfection protocol compatibility govern material selection across care environments.
- Vinyl:Polyurethane-coated substrates rated for hospital-grade quaternary ammonium and bleach cycles dominate acute care specification. United States infection control committees mandate seamless construction eliminating crevice contamination.
- Fabric:Solution-dyed nylon with moisture barriers penetrates home care channels where residential aesthetics outweigh institutional durability requirements.
- Leather:Top-grain hides with protective coatings occupy premium assisted living lounge segments where furniture lifecycle exceeds clinical replacement cycles.
- Foam:High-density polyurethane cushioning with vapor barrier integration provides pressure redistribution for bariatric and immobile patient populations.
Institutional specification favors Vinyl. Residential transition is accelerating Fabric adoption.
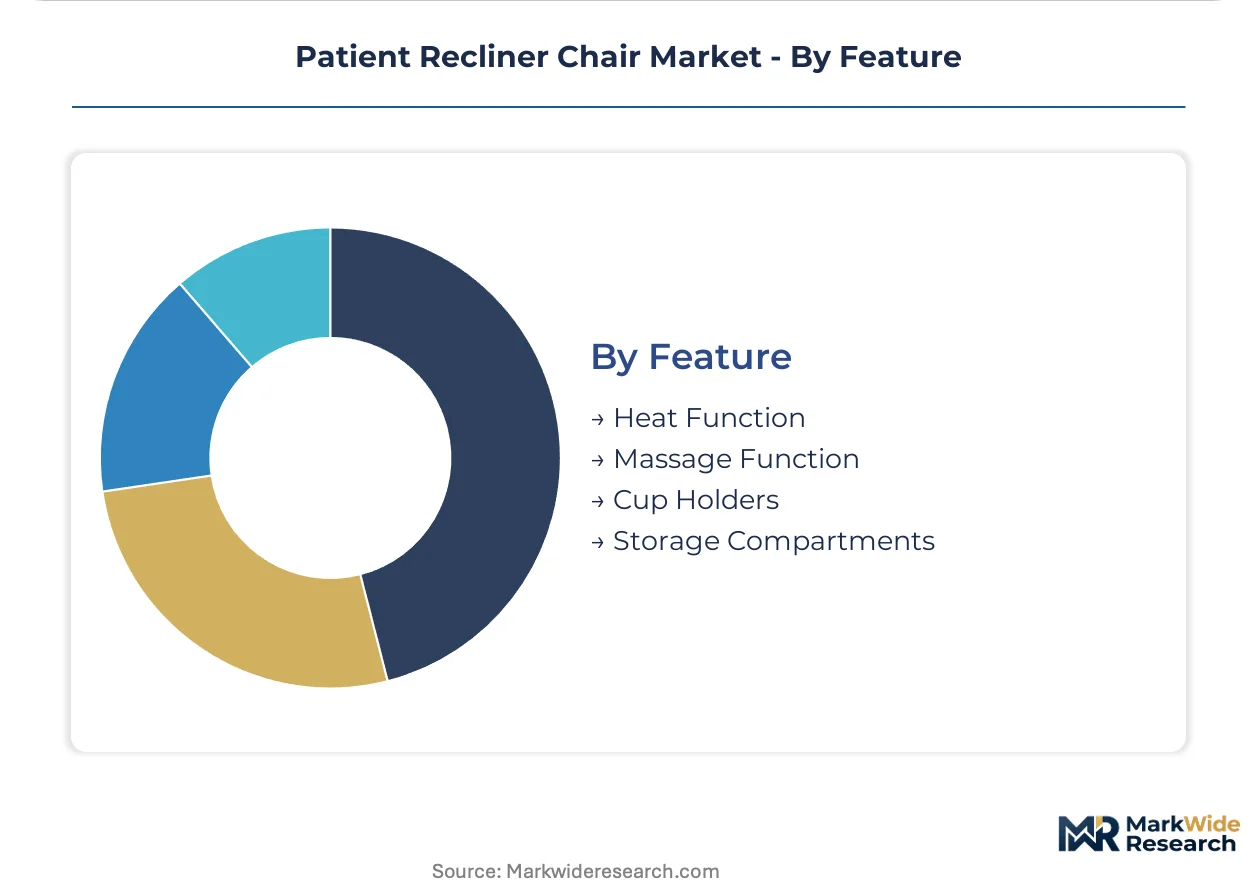
Feature:
Therapeutic and convenience add-ons differentiate price tiers beyond core positioning functionality.
- Heat Function:Carbon fiber heating elements with auto-shutoff timers penetrate home care segments where patient comfort drives direct-to-consumer purchase decisions.
- Massage Function:Vibration motors with zone selection compete in premium retail medical equipment channels outside institutional procurement.
- Cup Holders:Integrated molded compartments satisfy medication administration protocols in dialysis and infusion center settings.
- Storage Compartments:Under-seat enclosures accommodate personal belongings and medical supplies in behavioral health and long-term residential care.
Clinical procurement prioritizes Storage Compartments. Consumer-directed purchase favors Heat Function.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States metropolitan clusters concentrate the highest patient recliner specification activity, driven by integrated delivery network procurement consolidation and CMS durable medical equipment reimbursement expansion for home-based recovery.
United States
Hospital supply chain directors in Chicago and Dallas-Fort Worth are unbundling after-sales service from equipment purchase contracts, negotiating separate multi-year maintenance agreements with third-party clinical engineering firms. The FDA's 510(k) clearance pathway for powered medical furniture shapes product development timelines for manufacturers serving acute care networks. Aging-in-place policies in Florida and Arizona expand home care reimbursement, accelerating residential specification of infection-resistant upholstery.
Germany
Medicaid-equivalent reimbursement pressure in Bavaria and North Rhine-Westphalia constrains capital refresh cycles toward manual configurations in long-term care facilities. The European Union's Medical Device Regulation (MDR) tightens clinical evidence requirements for powered patient seating previously grandfathered under the Medical Device Directive. Stuttgart-based procurement consortia are demanding itemized service pricing transparency that exposes historical margin cross-subsidies.
India
Metropolitan residential clusters in Mumbai and Bengaluru are creating first-time demand for infection-resistant patient seating through expanding private home nursing networks. The Ayushman Bharat health mission extends coverage frameworks that shape equipment procurement standards in emerging home care infrastructure. Delhi-NCR hospital networks are consolidating vendor relationships toward long-term contracts rather than transactional equipment sales.
Brazil
São Paulo's skilled nursing facilities are penetrating motorized recliner systems to reduce caregiver injury rates and workers compensation exposure. ANVISA's streamlined medical device registration for Class II products with prior FDA clearance opens accelerated market entry for certified manufacturers. Rio de Janeiro's private hospital groups are specifying steel-framed power positioning systems in bundled bed-to-chair contracts.
Japan
Tokyo and Osaka prefectures exhibit aggressive procurement consolidation among integrated delivery networks seeking multi-year service agreements. METI standards for electromagnetic compatibility influence powered recliner development timelines for manufacturers targeting acute care specification. Yokohama's aging population density is expanding residential demand for lift chairs combining recline with powered stand-assist functionality.
Patient Recliner Chair Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue telehealth-integrated seating and direct-to-consumer e-commerce channels. The vendor base stratifies across three tiers: integrated medical equipment conglomerates with embedded clinical engineering support, commercial furniture specialists applying scale to healthcare-adjacent segments, and regional fabricators serving price-constrained long-term care networks. Dominant competitive moves include backward integration into steel framing supply and strategic partnerships with third-party clinical engineering firms for aftermarket service capture.
Within the integrated equipment tier, Stryker Corporation and Hill-Rom exemplify archetypes leveraging bundled contract opportunities through bed-to-chair ecosystem positioning. Steelcase occupies a position representing commercial furniture scale applied to healthcare-adjacent lounge and waiting-room recliner segments. These three anchors illustrate how procurement consolidation rewards vendors with sustained quality engineering headcount and multi-year service infrastructure.
| Leading Market Players |
|---|
| Stryker Corporation |
| Hill-Rom |
| Steelcase |
| Medline Industries |
| Drive DeVilbiss International |
| Krueger International |
| Nemschoff |
| Ocelco |
| La-Z-Boy |
| Others |
Pricing and Supply Chain Analysis
Steel and aluminum framing costs cascade through patient recliner manufacturing tiers, with lightweight alloy volatility compressing margins for mid-tier fabricators while integrated conglomerates absorb shocks through captive foundry operations and long-term mineral purchase agreements with primary metal suppliers.
Pricing Analysis
High-volume manual recliners trade on thin margins through GPO-negotiated contracts, while powered positioning systems with FDA 510(k) clearance capture premium positioning through embedded clinical engineering support and multi-year service bundling. Price differentiation hinges on electromagnetic compatibility certification tier and after-sales infrastructure depth. Cost compression in standard-tier vinyl-upholstered units is intensifying as hospital procurement consolidation squeezes transactional equipment margins. Rural long-term care facilities exhibit the highest price sensitivity, deferring electrification despite caregiver ergonomic penalties.
Supply Chain Analysis
Ocean freight rate fluctuations from Chinese and Vietnamese component assembly hubs to United States distribution centers are reshaping landed cost structures for steel-framed power positioning systems. Raw material sourcing draws from domestic polyurethane foam producers, imported brushless DC motor assemblies, and hospital-grade vinyl substrate manufacturers. Single-source vulnerability concentrates in electromagnetic compatibility testing capacity, where certified laboratory queue times extend product launch windows. Distribution runs through integrated delivery network central warehouses and specialized durable medical equipment dealer networks serving home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless DC motor electrification is displacing manual spring mechanisms across skilled nursing and acute care procurement specifications, compressing the technology transition window for legacy-dependent manufacturers.
For Market Incumbents: Cement market position through backward integration into steel framing supply and captive electromagnetic compatibility testing laboratories, insulating against aluminum price volatility and FDA timeline friction that threatens mid-tier competitors lacking capital reserves for quality engineering headcount expansion. For New Entrants and Emerging Players: Launch via direct-to-consumer e-commerce marketplaces targeting home care reimbursement expansion in United States metropolitan clusters with established private nursing networks, exploiting disintermediation of traditional durable medical equipment distributors and CMS coding expansion for lift chair affordability. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap manufacturers with ISO 13485 certification infrastructure and dormant FDA 510(k) clearances in India and Brazil, where Ayushman Bharat coverage expansion and ANVISA fast-track pathways create acquisition optionality ahead of regional home care infrastructure buildout.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Electromagnetic compatibility validation unlocks powered recliner commercialization in acute care networks. |
| Hospital System Partnership | Bundled bed-to-chair contracts with embedded clinical engineering secure multi-year revenue streams. |
| Backward Integration into Steel Framing | Captive foundry operations insulate margin stability against primary metal supplier price volatility. |
| Reimbursement Strategy | CMS durable medical equipment coding expansion directly shapes home care consumer affordability. |
| Software Companion Development | Biometric sensor integration with remote patient monitoring platforms creates telehealth-integrated premium tier. |
Research Methodology
Hospital procurement databases, FDA 510(k) premarket notification filings, and CMS durable medical equipment reimbursement schedules formed the secondary backbone, cross-referenced with primary interviews involving biomedical engineers, GPO contracts managers, home nursing network procurement leads, and clinical engineering directors. Bottom-up and top-down triangulation validated volume estimates across product type and end-user segmentation.
Bottom-up modeling anchored projections in unit-level specification patterns across United States integrated delivery networks, Germany's Medicaid-equivalent reimbursement clusters, and India's metropolitan home nursing expansion, while top-down analysis calibrated aggregate market expansion against healthcare capital expenditure trends. CAGRs derived from regression analysis of historical procurement cycles, patient discharge protocol shifts, and aging-in-place policy adoption curves across the projection horizon.
Regulatory timeline delays, raw material price volatility, and reimbursement coding revisions are the dominant revision risks that could compress or extend the electrification transition trajectory. Stakeholders should weight assumptions against their own operating context and regional procurement consolidation exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Medical Waste Supervision Solution Market
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
Emergency Hospital Beds Market
Healthcare Equipment
Clinical Mobility Market
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
Microbiological Safety Cabinets Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
Healthcare Personal Protection Equipment Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Medical Cold Storage Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
Global Hospital Asset Management Market