
 Specialty Frozen Bakery Market | 2026-2036
Specialty Frozen Bakery Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Frozen Bakery Market Outlook
Single-serve and mini-portion bundling is realigning buyer choice across foodservice channels. Lantmännen Unibake leverages its European production footprint to dominate artisan-style frozen bread lines. Flowers Foods sustains brand strength in North American retail through direct-store-delivery networks. ARYZTA AG anchors its competitive position with specialized frozen pastry capacity serving premium café accounts.
Specialty frozen bakery comprises dough, batter, and fully baked products preserved at sub-zero temperatures for extended distribution, typically formulated with modified starches and emulsifiers to ensure post-thaw texture recovery and oven-spring performance in commercial kitchens. Frozen pastries command the strongest margin pools as café chains prioritize labor-saving laminated products with consistent flake structure. Frozen bread competes on volume scale, while gluten-free ingredient formulations represent the fastest-growing sub-category as allergen-free protocols expand across restaurant and retail bakery channels.
FDA food safety standards and USDA labeling requirements govern product composition and nutritional disclosure across the United States, while EFSA and EU hygiene regulations shape formulation and traceability obligations for European manufacturers. These frameworks elevate compliance costs for smaller producers but create market access barriers that reinforce scale advantages among established frozen bakery suppliers. Stakeholders must monitor evolving clean-label thresholds and carbon-footprint disclosure rules as procurement criteria across foodservice and retail channels.
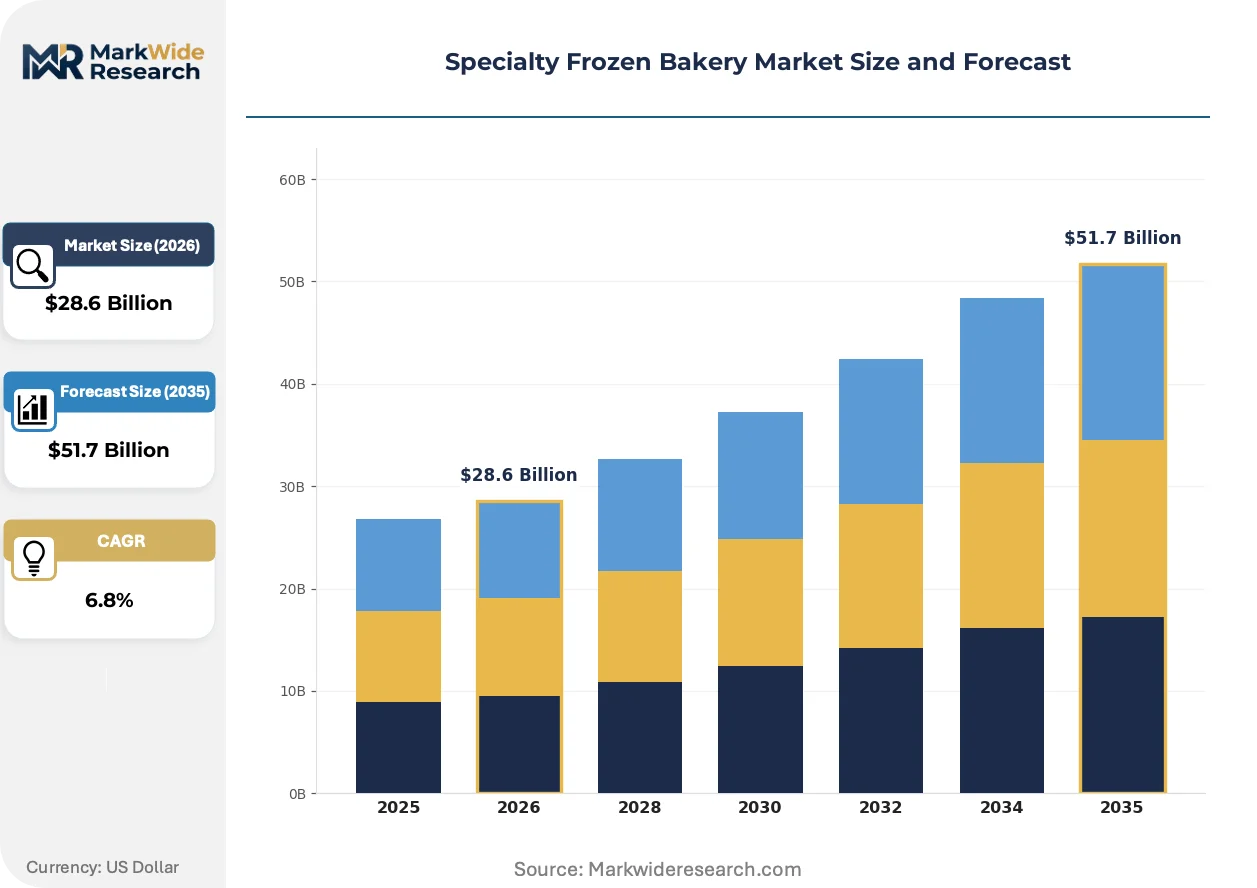
Market Dynamics
Clean-label reformulation mandates and extended shelf-life technology deployment are compressing formulation cycles across frozen bakery supply chains. Producers must now reconcile consumer ingredient transparency demands with freezer-to-oven performance requirements.
Growth Catalysts
- EU Green Deal carbon-footprint disclosure rules:Foodservice procurement teams in Germany and France now prioritize suppliers with verified lifecycle data, accelerating clean-label investment across frozen dough lines.
- Quick-service bakery chains:Labor scarcity in commercial kitchens is driving par-baked adoption for viennoiserie and artisan bread formats, reducing on-site skilled labor requirements.
- Modified starch stabilization technologies:Post-thaw texture recovery improvements enable wider distribution radii for laminated frozen pastries, expanding addressable markets for regional producers.
Market Restraints
- Wheat and butter price volatility:Input cost swings compress margin pools for mid-tier frozen pastry producers unable to pass through commodity fluctuations.
- Cold-chain infrastructure gaps:Last-mile frozen distribution remains underdeveloped in secondary Indian and Southeast Asian cities, limiting geographic expansion for temperature-sensitive laminated products.
- Clean-label technical ceiling:Removal of phosphate-based dough conditioners degrades oven-spring performance in high-hydration frozen bread systems, constraining reformulation options.
Strategic Opportunities
- India foodservice penetration:Café chain expansion in Bangalore and Mumbai creates demand for standardized frozen croissant and Danish formats with localized flavor profiles.
- Gluten-free ingredient systems:Rice and tapioca starch blends with hydrocolloid stabilization are opening allergen-free channels in retail and institutional bakery segments.
- Direct-to-operator e-procurement platforms:Digital ordering systems bypass traditional foodservice distributors, enabling smaller frozen bakery specialists to access independent restaurant accounts.
Industry Challenges
- Laminated dough technician scarcity:Frozen pastry production requires specialized skills in butter-layer distribution and stress-free freezing protocols that outpace vocational training output.
- Dual certification timelines:Simultaneous organic and gluten-free accreditation processes extend product launch cycles by 8-14 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Frozen Bakery Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Bread, Frozen Pastries, Frozen Cakes, Frozen Cookies End User: Restaurants, Cafés, Catering Services, Retail Bakeries Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers Ingredient Type: Gluten-Free, Whole Grain, Organic, Standard |
| Companies Covered | Lantmännen Unibake, Flowers Foods, ARYZTA AG, General Mills, Rich Products, Europastry, Vandemoortele, Mantinga UAB, Grupo Bimbo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Frozen Bakery Market Strategic Shifts
Refrigeration efficiency breakthroughs and digital traceability systems are reconfiguring frozen bakery production economics. These advances compress energy costs while expanding compliance capabilities across extended supply chains.
High-pressure processing for microbial reduction is absorbing validation work from thermal pasteurization methods in frozen raw dough applications. Premium café chains in Italy and Spain are piloting HPH-treated laminated bases to extend refrigerated holding times without chemical preservatives. This technology is absorbing shelf-life extension functions previously requiring frozen storage, enabling hybrid distribution models that blur fresh-frozen category boundaries.
REACH chemical registration requirements in the European Union are tightening emulsifier and enzyme disclosure obligations for frozen bakery additives. Manufacturers must now submit full toxicological dossiers for dough conditioners previously grandfathered under older regulatory frameworks. Frozen bread producers serving German and French retail channels are reformulating around approved enzyme lists, accelerating substitution of synthetic emulsifiers with lecithin and plant-based alternatives.
Café and restaurant procurement teams are consolidating supplier relationships around full-category frozen bakery portfolios rather than single-product sourcing. This behavior compresses vendor counts while raising minimum volume thresholds for participation. The shift is most visible in UK and US urban markets where multi-unit operators negotiate system-wide contracts covering bread, pastry, and specialty formats through integrated supply agreements.
Specialty Frozen Bakery Market Segmentation
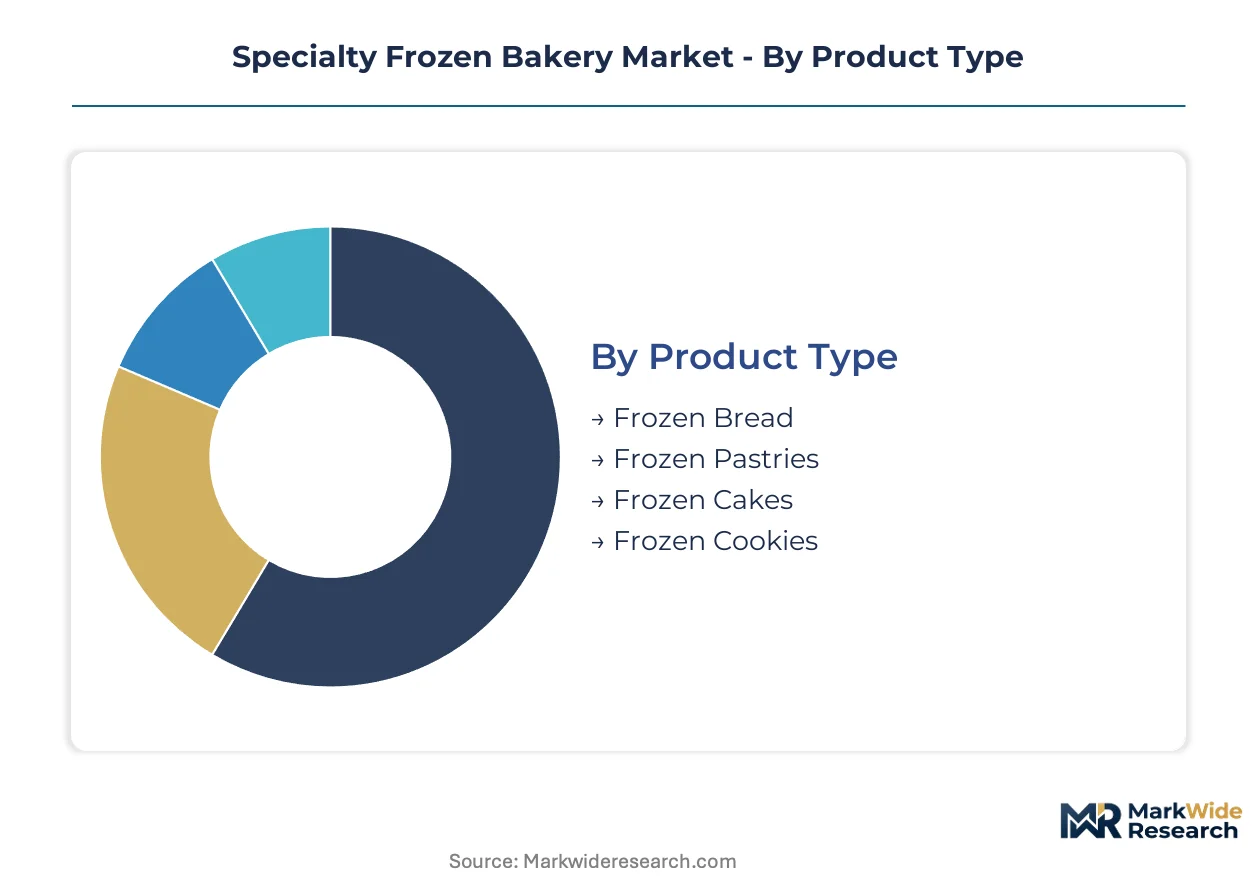
Specialty frozen bakery procurement patterns diverge sharply across product formats and operator types. Understanding these segment boundaries clarifies where formulation investments and distribution infrastructure deliver differential returns.
Product Type:
Freezer-to-oven performance specifications define competitive positioning across frozen bakery formats.
- Frozen Pastries:Laminated dough systems with controlled butter-layer distribution enable consistent flake recovery after thawing. Café chains in France and Italy concentrate procurement here, prioritizing labor savings on viennoiserie production.
- Frozen Bread:Par-baked and fully baked loaves rely on modified starch stabilization for oven-spring recovery. Quick-service bakery operators across Germany and the United States anchor volume demand for artisan and sandwich formats.
- Frozen Cakes:Aerated batter systems with emulsifier blends maintain crumb structure through freeze-thaw cycles. Catering services and institutional accounts drive procurement for standardized dessert portions.
- Frozen Cookies:Drop and rotary-molded formats with extended frozen shelf life serve retail bakery channels seeking thaw-and-serve convenience.
Mature deployment sits with frozen bread. Newer deployment is concentrated in frozen pastries.
End User:
Operator kitchen capabilities and labor economics reshape segment priorities across foodservice channels.
- Cafés:Premium laminated products with consistent visual standards dominate procurement, driven by barista-focused labor models that eliminate on-site pastry production. Urban clusters in Milan and Paris exhibit highest penetration.
- Restaurants:Bread programs emphasize par-baked formats reducing proofing equipment requirements. Independent full-service operators in Spain and the United Kingdom represent expanding adoption.
- Retail Bakeries:Thaw-and-sell frozen formats enable extended product ranges without commissary investment. Suburban and secondary city locations drive volume.
- Catering Services:Standardized portion control and holding stability prioritize frozen cake and cookie formats for event-scale dessert service.
Volume concentration rests with restaurants. Margin expansion is climbing the fastest in cafés.
Distribution Channel:
Cold-chain reliability and order frequency patterns segment channel economics.
- Wholesalers:Foodservice distributors with frozen capacity deliver consolidated bakery portfolios to multi-unit operators. Temperature-controlled fleet investments create scale barriers for regional coverage.
- Supermarkets:Retail frozen bakery sections command dedicated freezer case space, with private-label penetration strongest in German and UK grocery channels.
- Online Retail:Direct-to-consumer frozen shipping requires insulated packaging and expedited delivery, constraining viable product density to premium formats.
- Convenience Stores:Limited freezer capacity restricts assortment to high-velocity bread and pastry singles, with grab-and-go positioning.
Established infrastructure sits with wholesalers. Digital channel development is gaining share fastest in online retail.
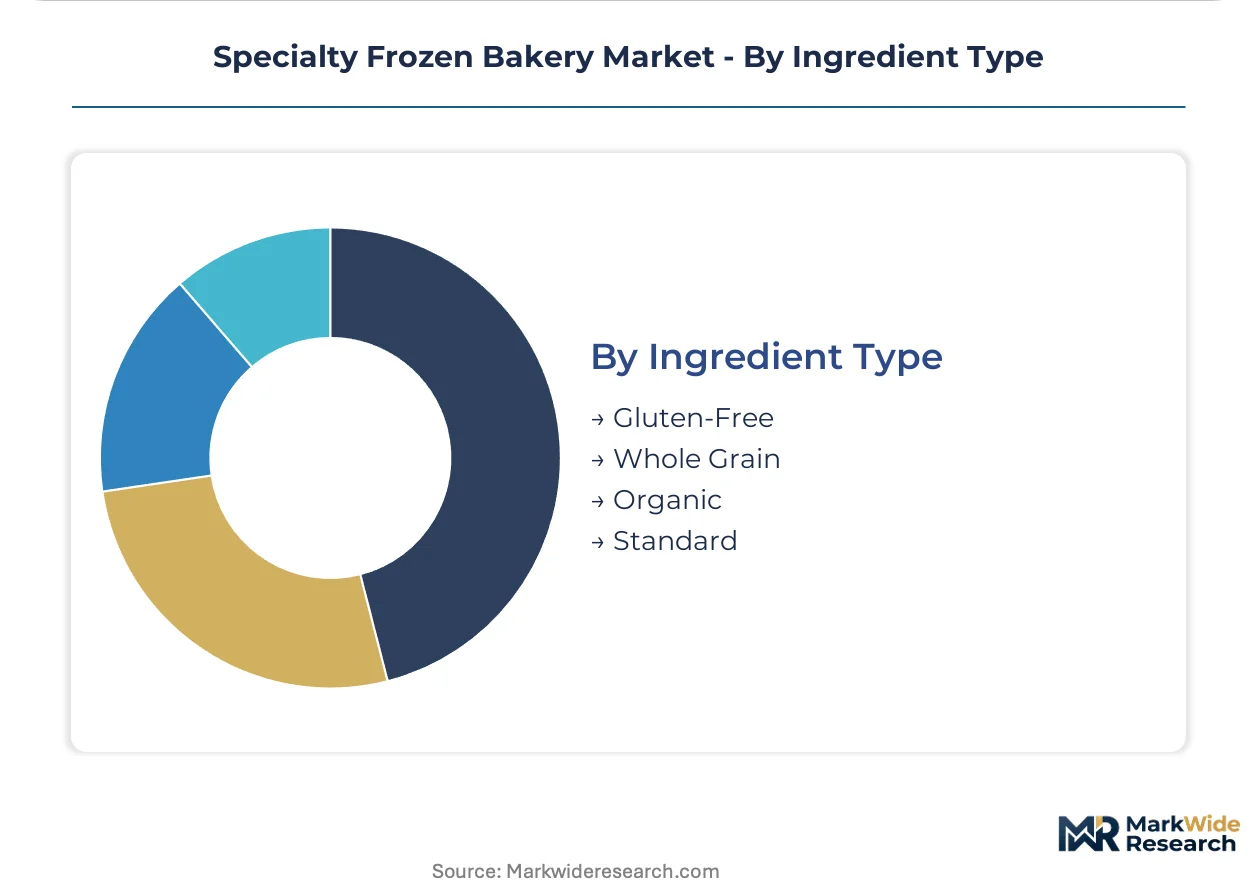
Ingredient Type:
Clean-label thresholds and certification requirements segment formulation complexity.
- Gluten-Free:Rice and tapioca starch blends with hydrocolloid stabilization open allergen-free channels. EFSA and FDA labeling protocols govern disclosure requirements across European and United States retail.
- Organic:Certified ingredient sourcing with restricted additive lists extends product launch timelines. German and French procurement teams prioritize verified supply chains under EU Green Deal carbon-footprint rules.
- Whole Grain:Bran inclusion and fiber content claims target health-positioned retail bakery segments with modified processing for frozen stability.
- Standard:Conventional formulations with full emulsifier and conditioner toolkits maintain cost competitiveness for price-sensitive foodservice accounts.
Certification density sits with organic. Volume expansion is steepest in gluten-free.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frozen bakery production clusters around Rotterdam's port-centric free trade zones and Chicago's cold-chain logistics corridors, where temperature-controlled warehousing incentives attract multinational commissary investments. Tax-advantaged distribution hubs in these zones compress landed costs for laminated dough exports to adjacent metropolitan markets.
United States
Quick-service bakery chains in Texas and Florida drive par-baked bread procurement, reducing on-site labor requirements. FDA food safety standards govern modified starch disclosure and freezer-to-oven performance labeling. Chicago anchors the Great Lakes frozen dough corridor, where Flowers Foods maintains direct-store-delivery networks serving independent retail bakeries.
Germany
EU Green Deal carbon-footprint disclosure rules push foodservice buyers toward suppliers with verified lifecycle data. EFSA hygiene regulations enforce strict traceability for emulsifier and enzyme additives. Bavaria's industrial bakery belt around Munich concentrates artisan frozen bread production for export to Austrian and Swiss café chains.
France
Premium café operators in Paris and Lyon prioritize labor-saving viennoiserie formats with consistent visual standards. REACH chemical registration tightens emulsifier disclosure obligations for dough conditioners. The Île-de-France region hosts Europastry's specialized capacity for laminated frozen pastries serving multi-unit restaurant accounts.
India
Café chain expansion in Bangalore and Mumbai creates demand for standardized frozen croissant formats with localized flavor profiles. FSSAI labeling protocols govern allergen disclosure for imported frozen bakery ingredients. Maharashtra's cold-chain infrastructure investments near Mumbai Port enable wider distribution radii for temperature-sensitive laminated products.
Italy
High-pressure processing pilots in Milan and Rome extend refrigerated holding times for laminated bases without chemical preservatives. EMA-aligned food contact material rules shape packaging specifications for frozen dough distribution. Northern Italy's Emilia-Romagna corridor concentrates par-baked bread production for Mediterranean foodservice export.
Specialty Frozen Bakery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across frozen bakery supply tiers. The vendor base organizes around three strategic archetypes: European artisan-format specialists, North American scale-driven distributors, and emerging regional capacity builders. Consolidation pressure intensifies as café procurement teams consolidate supplier relationships around full-category portfolios. Dominant competitive moves include geographic expansion through cold-chain infrastructure partnerships and backward integration into ingredient sourcing.
Among European-based specialists, Lantmännen Unibake and ARYZTA AG exemplify the artisan-capability archetype with concentrated laminated dough expertise. Flowers Foods occupies a position representing North American scale advantages through direct-store-delivery network density. These three entities anchor the competitive map without exhausting its structural variety.
| Leading Market Players |
|---|
| Lantmännen Unibake |
| Flowers Foods |
| ARYZTA AG |
| General Mills |
| Rich Products |
| Europastry |
| Vandemoortele |
| Mantinga UAB |
| Grupo Bimbo |
| Others |
Value Chain & Pricing Dynamics
Laminated dough technician scarcity in Northern Europe and the Île-de-France region feeds directly into pricing-tier spreads, with labor-cost differentials between artisan-capable and commodity-grade producers widening as vocational training output lags frozen pastry demand.
Pricing Analysis
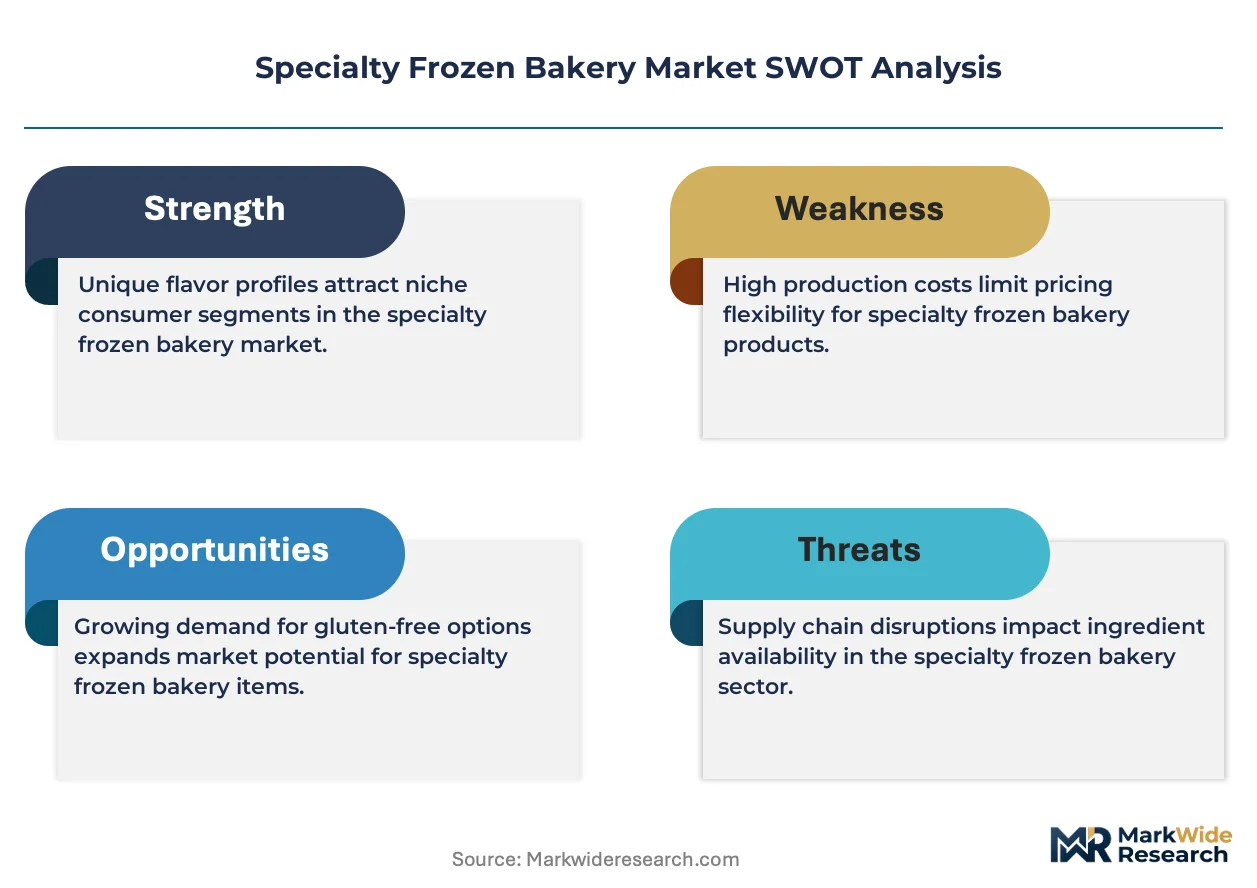
Short lead-time premiums for just-in-time frozen viennoiserie deliveries command substantial markups over contract-based spot inventory held in regional cold-storage facilities. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification density and volume scale, with organic and gluten-free tiers carrying brand premiums while conventional formulations face price erosion from wheat and butter commodity volatility. Quick-service bakery chains exhibit lowest price sensitivity due to labor-cost savings from par-baked adoption, whereas independent retail bakeries operate at thin margins with acute cost consciousness.
Supply Chain Analysis
Dual-sourcing requirements from multi-unit café operators in France and Germany mandate multi-supplier qualification for laminated dough lines, compressing single-source dependencies. Supply concentrates in the Netherlands, Germany, and Belgium, drawing from wheat cultivation in the Paris Basin and butter processing in Normandy and Bavaria. Single-source vulnerability runs through specialized cold-chain logistics corridors, with Rotterdam and Chicago anchoring distribution through temperature-controlled warehousing networks serving adjacent metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with laminated dough technician scarcity propping pricing power for qualified producers across European café procurement channels.
For Market Incumbents: Lock in backward integration into butter-layer sourcing and specialized freezing capacity to defend margin position against emerging regional specialists in India and Southeast Asia. Prioritize certification investment in dual organic-gluten-free accreditation to capture procurement consolidation toward full-category suppliers. For New Entrants and Emerging Players: Foodservice e-procurement platforms represent the most penetrable channel wedge, enabling direct access to independent restaurant accounts bypassing traditional distributor markups. Target Bangalore and Mumbai café chain expansion with localized frozen croissant formats, leveraging Maharashtra cold-chain infrastructure investments near Mumbai Port. For Investors and Strategic Acquirers: Re-rating potential sits with artisan-capability specialists given EU Green Deal carbon-footprint disclosure rules accelerating clean-label investment timelines. Long-term viability over a multi-year window favors producers with verified lifecycle data and specialized laminated dough capacity. Watch for inflection when dual certification timelines compress below eight months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ingredient Sourcing | Captive butter and modified starch supply secures margin control against commodity volatility. |
| Cold-Chain Infrastructure Partnership | Temperature-controlled fleet investments in India expand distribution radii for laminated products. |
| Clean-Label Reformulation Program | EFSA and REACH compliance opens German and French retail channels previously restricted. |
| Direct-to-Operator E-Procurement Launch | Digital ordering platforms bypass foodservice distributor consolidation toward multi-unit accounts. |
| Dual Certification Acceleration | Parallel organic and gluten-free accreditation captures procurement consolidation trends in UK urban markets. |
Study Parameters
Multi-period observation of frozen dough import volumes, café chain expansion rates, and cold-chain infrastructure investments anchored the trend analysis, supplemented by interviews with plant managers at laminated dough facilities, procurement leads at quick-service bakery chains, technical R&D directors at emulsifier suppliers, and category buyers at foodservice distributors. Secondary validation drew from customs and trade data, EFSA additive approval registers, EU Green Deal implementation trackers, and SEC filings of publicly traded bakery conglomerates. Bottom-up volume modeling triangulated against top-down expenditure analysis across the projection horizon.
Input-output matrices mapped frozen bakery consumption by product format, end-user operator type, distribution channel, and ingredient certification tier throughout the forecast period. CAGRs derived from segmented growth rate aggregation with cross-validation against macroeconomic indicators. Industry-specific forecast inputs incorporated modified starch stabilization technology adoption curves and high-pressure processing validation timelines for shelf-life extension applications.
Caveats apply where REACH chemical registration delays or FSSAI labeling protocol changes could materially shift the outlook for emulsifier-dependent product lines. Forecasts reflect assumptions about cold-chain infrastructure buildout rates and vocational training output for laminated dough technicians. A model refresh is warranted upon material change in EU carbon-footprint disclosure enforcement timelines or wheat and butter commodity price regime shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Cake Base Discs Market
Bakery Products
Premixed Bread Flour Market
Bakery Products
Gulf Cooperation Council Frozen Bakery Products Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
United States Bread Market
Bakery Products
Bakery Cases Market
Bakery Products
Low Calorie Muffins Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Aerating Cake Emulsifier Market
Bakery Products
Low Fat Bread Market
Bakery Products
Ice Cream Cake Market
Bakery Products
US Retail Packaged Bread Market
Bakery Products
Bakers Yeast Market
Bakery Products
Waffle Market
Bakery Products
Baking Mix, Base and Concentrate Market