
 Low Fat Bread Market | 2026-2036
Low Fat Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Bread Market Analytics
Asset-light co-manufacturing and third-party bakery leasing is fragmenting competitive barriers in low fat bread production. Grupo Bimbo leverages vertical integration across milling and distribution to sustain cost advantages in North American retail. Flowers Foods anchors its position through direct-store-delivery networks that control freshness-sensitive shelf space.
Low fat bread denotes baked goods formulated with reduced lipid content, typically achieving under 3 grams of fat per serving through modified fat-replacement systems, hydrocolloid stabilizers, or optimized fermentation processes that enhance moisture retention without added oils. The primary commercial purpose centers on delivering calorically controlled staple carbohydrates to consumers managing weight, cardiovascular risk, or metabolic conditions. Whole grain and high fiber ingredient types command premium positioning as fortification protocols align with FDA-approved health claims, while gluten-free formulations occupy a specialized niche constrained by texture-compromise challenges. Sourdough variants lead in clean-label preference among health food store channels where fermentation-derived acidity replaces fat-dependent flavor profiles.
FDA nutrition labeling mandates and USDA dietary guidelines directly shape fat-content thresholds that determine qualified health claims eligibility. EFSA health claim assessments in Europe enforce stricter evidentiary standards for low-fat positioning statements, compressing formulation flexibility for exporters. Stakeholders must monitor evolving WHO trans fat elimination targets and emerging front-of-package warning systems that could recategorize acceptable fat thresholds without reformulation lead time.
Market Dynamics
Reformulation chemistry around fat-replacement systems and hydrocolloid stabilizers is compressing the performance gap between reduced-fat and conventional bread, forcing capital reallocation toward R&D-intensive product pipelines.
Growth Catalysts
- FDA-qualified health claims:Products meeting under-3-grams-fat thresholds gain shelf placement advantages in US supermarket channels where dietary guidance drives purchasing decisions.
- Whole grain fortification protocols:EFSA-approved fiber-content positioning statements enable premium pricing in European retail formats where clean-label preferences concentrate.
- Direct-store-delivery networks:Freshness-controlled distribution infrastructure in North American metropolitan markets sustains velocity for moisture-sensitive reduced-fat formulations.
Market Restraints
- Hydrocolloid input volatility:Guar gum and xanthan supply concentrates in India and Pakistan, exposing formulations to monsoon-driven harvest fluctuations and export duty swings.
- Texture-compromise ceiling:Gluten-free low-fat variants hit organoleptic limits that prevent mainstream adoption despite celiac disease prevalence expansion.
- WHO trans fat elimination targets:Accelerated phase-out timelines in Southeast Asian manufacturing hubs compress reformulation lead times without compensatory price mechanisms.
Strategic Opportunities
- German sourdough fermentation:Clean-label acidity development replaces fat-dependent flavor systems in health food store channels where ingredient minimalism commands loyalty.
- Japanese convenience retail:Underpenetrated shelf space in Lawson and 7-Eleven networks awaits portion-controlled single-serve low-fat bread introductions.
- EU Green Deal procurement incentives:Public sector foodservice contracts now weight carbon-footprint scoring, advantaging regional-milled whole grain suppliers with shortened supply chains.
Industry Challenges
- Enzymologist talent scarcity:Fermentation process optimization for fat reduction requires specialized biochemists whose training pipelines lag formulation demand by three to five years.
- Dual certification timelines:Simultaneous USDA organic and FDA qualified health claim approvals stretch product development cycles beyond seasonal launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Bread Market |
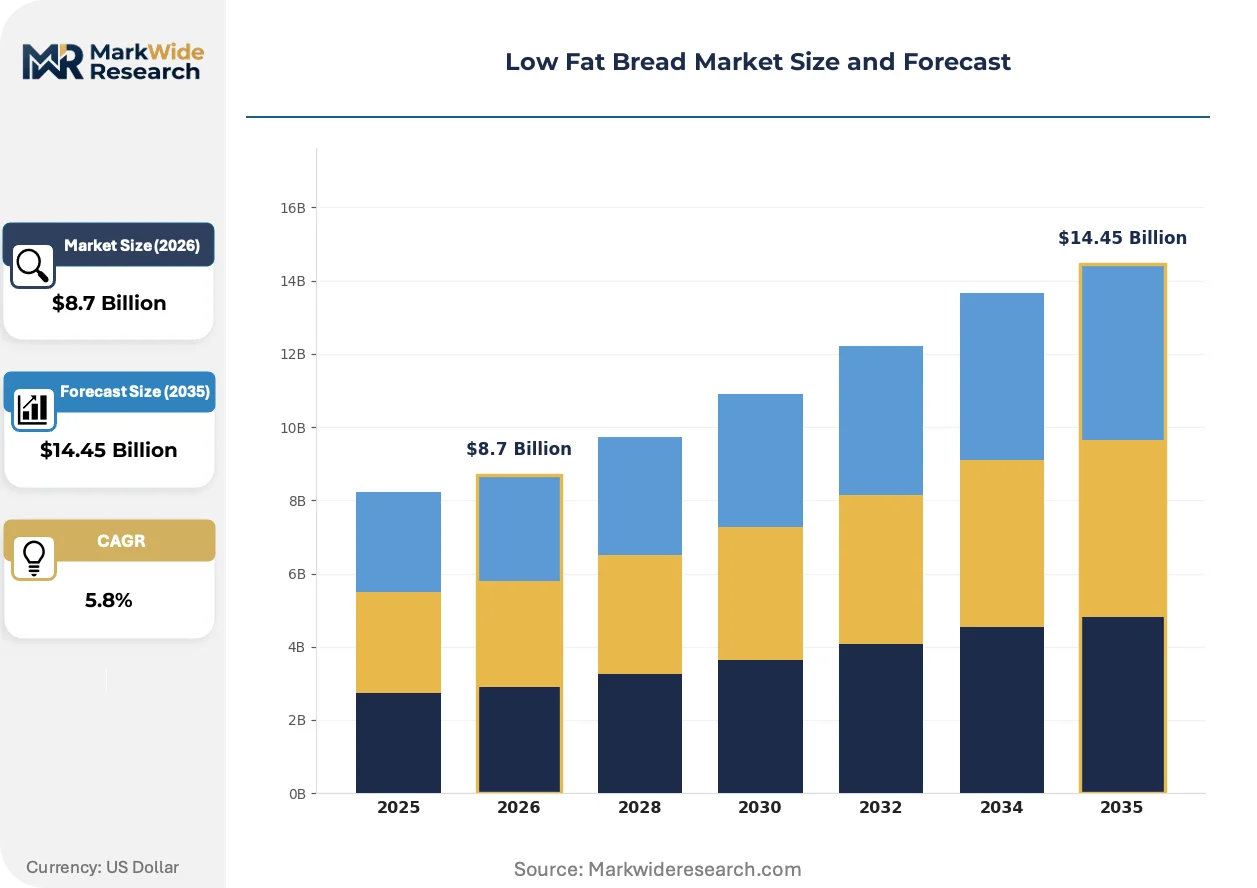
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain, Gluten-Free, Sourdough, Rye End User: Health-Conscious Consumers, Fitness Enthusiasts, Diabetics, Families Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Bakeries Ingredient Type: Natural Sweeteners, Fortified Grains, High Fiber, Others |
| Companies Covered | Grupo Bimbo, Flowers Foods, General Mills, Associated British Foods, Bimbo Bakeries USA, Schmidt, Sola Bread, Julian Bakery, Dave's Killer Bread, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Bread Market Evolving Landscape
Active reformulation is collapsing the traditional trade-off between nutritional credentials and sensory performance, with laboratory-scale breakthroughs now scaling through co-manufacturing partnerships that bypass legacy asset constraints.
Precision fermentation-derived lipid alternatives are digitizing the ingredient specification process for industrial bakeries. Aryballe's digital olfaction sensors and similar platforms allow real-time flavor-profile matching against conventional fat benchmarks. North American contract manufacturers deploy these tools to compress sensory validation from months to weeks. The technology is digitizing quality assurance workflows and enabling faster private-label replication of successful reduced-fat formulations.
EFSA's 2024 tightened evidentiary standards for low-fat health claims are forcing exporters into costly clinical substantiation investments. Products targeting European supermarket channels must now demonstrate physiological benefit beyond mere compositional thresholds. German and Dutch reformulation teams are responding by front-loading clinical trial budgets and shelving borderline-compliant line extensions.
Health food store buyers are consolidating supplier relationships around fermentation-derived acidity credentials that displace fat-dependent flavor architectures. Sourdough positioning now functions as a de facto quality signal in channels where ingredient minimalism trumps fortification claims. This preference compression is most visible in coastal US metropolitan markets and Tokyo's organic retail clusters, where sourdough low-fat bread commands 15-20 percent shelf price premiums over conventional reduced-fat alternatives.
Low Fat Bread Market Segmentation
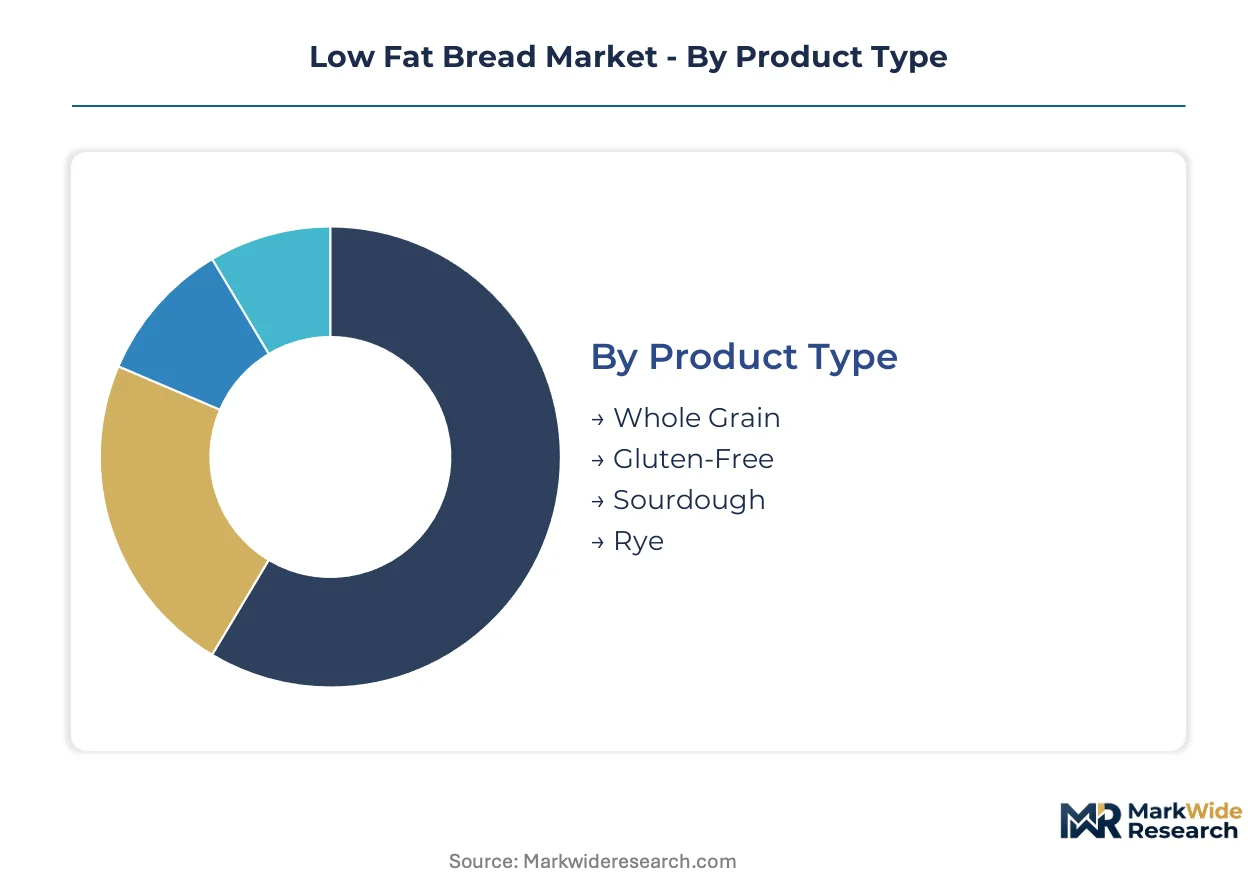
Low fat bread segmentation reflects divergent technical pathways and channel economics. Product type determines formulation complexity and margin structure, while distribution channel shapes shelf-life requirements and branding investment.
Product Type:
Cost tier differentiation separates premium-positioned functional variants from commodity reduced-fat offerings.
- Whole Grain:Formulations incorporate bran and germ fractions that retain lipid-reduction functionality while delivering fiber density above 3 grams per serving. FDA-qualified health claims for cardiovascular benefit drive placement in US supermarket center-store aisles where whole grain positioning commands price premiums over conventional reduced-fat white bread.
- Sourdough:Extended fermentation protocols generate lactic acid that masks fat-absence through flavor complexity rather than additive systems. German and Dutch health food store channels prioritize sourdough credentials as clean-label signals, with coastal US metropolitan markets replicating this preference pattern.
- Gluten-Free:Rice and tapioca starch bases require hydrocolloid stabilization to compensate for both gluten absence and fat reduction.
- Rye:Pentosan-rich fiber structures retain moisture without lipid addition, suing Eastern European flavor preferences.
Whole grain holds installed capacity. Sourdough is rotating up the share rankings.
End User:
Application context determines portion sizing, packaging format, and messaging emphasis across the customer base.
- Health-Conscious Consumers:Primary demand segment seeking caloric control without staple abandonment. US supermarket channels target this cohort through front-of-package labeling that highlights sub-3-gram fat thresholds alongside whole grain content callouts.
- Fitness Enthusiasts:Require macronutrient transparency and protein-fortified variants that complement training regimens. Japanese convenience retail networks serve this segment through single-serve packaging with detailed compositional breakdowns.
- Diabetics:Glycemic index management drives selection toward high-fiber, low-fat combinations.
- Families:Volume purchasing patterns favor multi-loaf packs with extended freshness dating.
Health-conscious consumers anchor volume throughput. Fitness enthusiasts are climbing the fastest as sports nutrition cross-merchandising expands.
Distribution Channel:
Volume concentration varies sharply by freshness sensitivity and capital requirements for shelf access.
- Supermarkets:Dominant throughput channel where direct-store-delivery networks control bakery section rotation. Flowers Foods and similar operators leverage freshness-controlled logistics to maintain velocity for moisture-sensitive reduced-fat formulations in North American metropolitan markets.
- Health Food Stores:Curated assortment environments where sourdough credentials and organic certification filter entry. Tokyo's organic retail clusters and coastal US metro markets concentrate premium pricing power for clean-label variants.
- Online Retail:Frozen shipping requirements constrain participation to shelf-stable or flash-frozen formats.
- Bakeries:Artisan positioning with limited geographic radius and high labor intensity.
Supermarkets maintain infrastructure lock-in. Health food stores are gaining share fastest as channel blurring accelerates.
Ingredient Type:
Margin structure follows input certification grade and supply chain traceability investments.
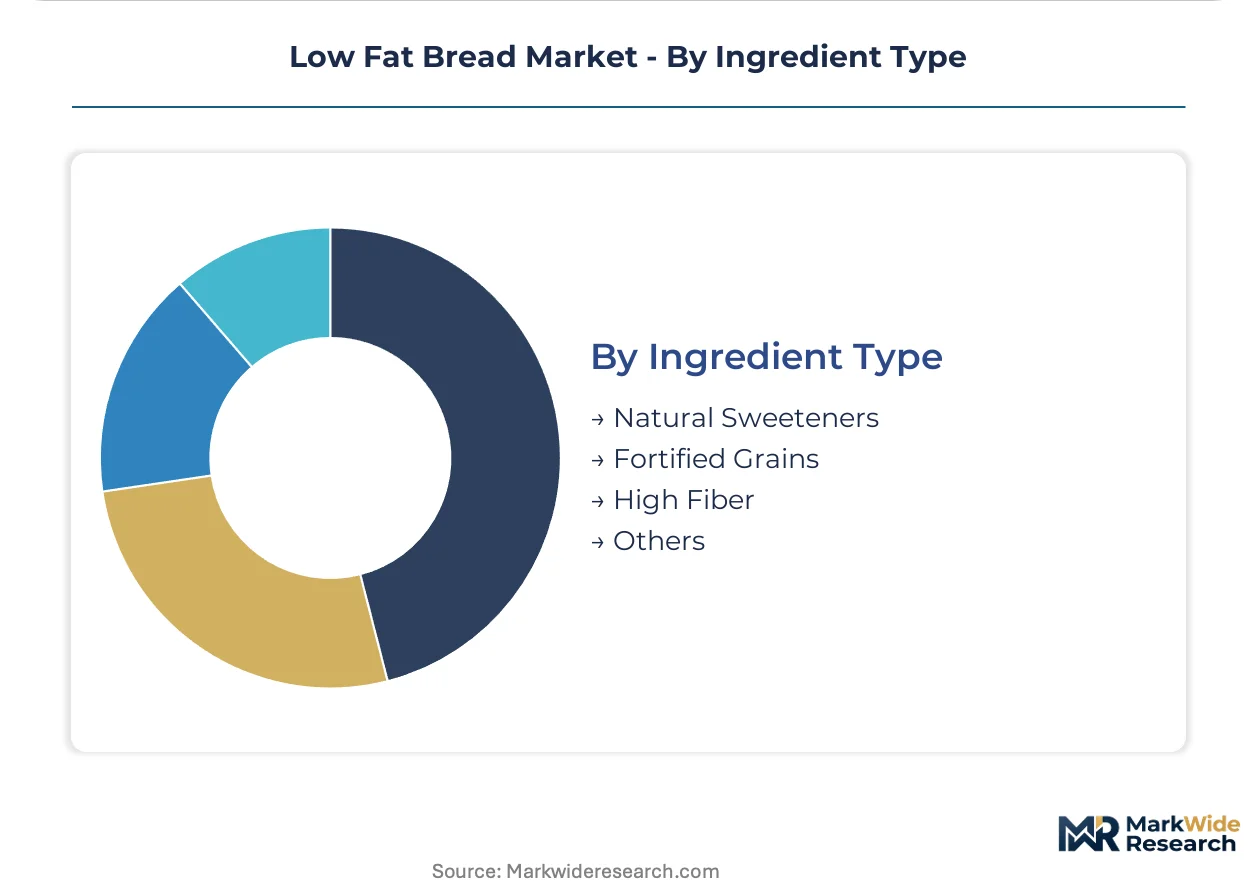
- Natural Sweeteners:Stevia and monk fruit extracts replace sucrose in reduced-calorie positioning without glycemic impact. EFSA health claim assessments enforce stricter evidentiary standards for European market access, compressing formulation flexibility for exporters targeting premium positioning.
- Fortified Grains:Micronutrient addition at milling stage enables qualified health claims for folate, iron, or B-vitamin content. USDA dietary guideline alignment drives institutional procurement in US school nutrition and military feeding programs.
- High Fiber:Resistant starch and inulin incorporation targets digestive health positioning.
- Others:Enzyme systems and emulsifier categories completing fat-replacement functionality.
Fortified grains hold institutional contract volume. Natural sweeteners are expanding most quickly as sugar taxation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA-qualified health claims and EFSA fiber-content positioning statements are redirecting formulation investment toward markets with enforceable label-advantage thresholds. Japan's convenience retail networks and Germany's health food store channels concentrate premium pricing power for clean-label variants.
United States
Supermarket direct-store-delivery networks anchor volume throughput for moisture-sensitive reduced-fat formulations. FDA under-3-grams-fat thresholds determine qualified health claim eligibility that drives center-store shelf placement. Chicago and Dallas metropolitan markets sustain the highest velocity for whole grain fortified lines.
Germany
Extended sourdough fermentation protocols command 15-20 percent shelf price premiums in health food store channels. EFSA tightened evidentiary standards for low-fat positioning statements are front-loading clinical trial budgets among reformulation teams. Berlin and Hamburg organic retail clusters filter supplier entry around fermentation-derived acidity credentials.
Japan
Convenience retail networks at Lawson and 7-Eleven await portion-controlled single-serve low-fat bread introductions. METI-aligned dietary guidance emphasizes glycemic index management for diabetic and fitness-focused segments. Tokyo's organic retail clusters replicate German sourdough preference patterns with clean-label minimalism.
United Kingdom
Whole grain fortification protocols align with NHS dietary guidance that favors reduced-fat staples in public procurement. EU Green Deal carbon-footprint scoring advantages regional-milled suppliers with shortened supply chains. London and Southeast England supermarket channels drive adoption through front-of-package labeling emphasis.
Canada
Health Canada nutrition labeling mandates parallel FDA thresholds for fat-content health claim eligibility. USDA-aligned school nutrition programs in Ontario and Quebec institutionalize fortified grain procurement. Toronto and Vancouver metropolitan markets concentrate health-conscious consumer demand for calorically controlled carbohydrates.
Low Fat Bread Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented bakery networks. Market structure tilts toward tiered consolidation where scale-driven distributors leverage freshness-controlled logistics against R&D-intensive formulators. Two archetypes dominate: vertically integrated milling-to-retail operators and asset-light co-manufacturing specialists. Competitive moves concentrate on direct-store-delivery network expansion and precision fermentation technology licensing.
Among North American channel controllers, Grupo Bimbo and Flowers Foods exemplify divergent scale strategies. Grupo Bimbo represents backward integration into captive milling and distribution infrastructure. Flowers Foods anchors freshness-sensitive shelf access through metropolitan direct-store-delivery density. Associated British Foods occupies a position bridging European health claim compliance with trans-Atlantic export formulation standards.
| Leading Market Players |
|---|
| Grupo Bimbo |
| Flowers Foods |
| General Mills |
| Associated British Foods |
| Bimbo Bakeries USA |
| Schmidt |
| Sola Bread |
| Julian Bakery |
| Dave's Killer Bread |
| Others |
Value Network & Pricing Analysis
Mississippi River barge freight corridors shape cost dynamics for heartland grain flows, concentrating milling power among captive-supply operators while downstream price differentiation splits between FDA-certified health claim tiers and commodity reduced-fat offerings.
Pricing Analysis
Certification level creates the primary spread, with FDA-qualified health claim eligibility commanding shelf price premiums over conventional reduced-fat white bread. Three-tier pricing structure separates premium whole grain fortified lines from standard reduced-fat formulations and economy private-label offerings. Cost compression in the economy tier intensifies as co-manufacturing capacity expands, while health-conscious supermarket shoppers show lowest price sensitivity for sourdough credentials.
Supply Chain Analysis
Export-control regimes on precision fermentation technology limit lipid-alternative ingredient flows to European and North American reformulation teams. Guar gum supply concentrates in India and Pakistan, xanthan production centers on Chinese fermentation facilities, and premium wheat milling clusters in the United States and Germany. Single-source vulnerability in South Asian hydrocolloid harvests threatens formulation stability. Distribution runs through direct-store-delivery networks controlling freshness-sensitive supermarket bakery sections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as clean-label fermentation credentials displace fortification claims, creating niche entry points for specialized sourdough operators alongside scale-driven incumbents.
For Market Incumbents: Build direct-store-delivery density moats by expanding metropolitan freshness-controlled logistics networks against asset-light co-manufacturer encroachment. Secure backward integration into regional milling capacity to buffer hydrocolloid input volatility. Prioritize enzymologist recruitment pipelines to address fermentation talent scarcity constraining R&D velocity. For New Entrants and Emerging Players: Japanese convenience retail networks at Lawson and 7-Eleven represent the most penetrable entry point for portion-controlled single-serve low-fat bread introductions. German health food store channels offer white-space for certified organic sourdough variants. Go-to-market leverage rests on co-manufacturing partnerships that bypass legacy asset requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underperforming bakery divisions lacking fermentation-derived acidity capabilities. Long-term viability favors operators controlling both clean-label positioning and direct-store-delivery infrastructure. Watch EFSA health claim enforcement intensity as inflection signal for European market access costs.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | Aryballe's digital olfaction sensors compress sensory validation timelines for industrial bakeries. |
| Direct-Store-Delivery Expansion | Flowers Foods anchors freshness-controlled shelf access in North American metropolitan markets. |
| Co-Manufacturing Partnership | Asset-light production bypasses legacy milling infrastructure for private-label replication speed. |
| Clinical Trial Front-Loading | German reformulation teams respond to EFSA tightened standards with substantiation investment. |
| Organic Certification Pathway | Dual USDA organic and FDA health claim approvals stretch product development cycles. |
Research Methodology
The analysis maps whole grain fortification protocols, sourdough fermentation systems, gluten-free hydrocolloid stabilization, and rye-based formulations, each validated through bakery R&D directors, supermarket category buyers, health food store procurement managers, and contract manufacturing executives. Primary interviews combined with secondary validation from FDA qualified health claim filings, EFSA substantiation assessments, USDA dietary guideline publications, and customs trade data on hydrocolloid imports. Bottom-up volume triangulation against top-down macroeconomic anchoring ensures cross-verified outputs.
Assumptions held FDA under-3-grams-fat thresholds and EFSA fiber-content positioning standards fixed across the projection horizon, while varying enzymologist talent availability and WHO trans fat elimination timelines. Segmentation modeling spanned product type, end user application, distribution channel, and ingredient certification grade. CAGRs derived from normalized historical velocity patterns projected against channel-specific adoption curves, with inputs including supermarket scanner data and health food store assortment expansion rates.
Macroeconomic conditions sit as an overlay; deviation in wheat commodity prices or South Asian monsoon patterns would shift the trajectory. Forecasts reflect documented assumptions on regulatory stability and consumer clean-label preference persistence. Material shifts in FDA health claim eligibility criteria or EFSA evidentiary standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
North America Pizza Oven Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Cake Base Discs Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
Instant Cake Gel Market
Bakery Products
Bakery Conditioner Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Wedding Cakes Market
Bakery Products
Bakery Improvers Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Bakers Yeast Market
Bakery Products
Gulf Cooperation Council Frozen Bakery Products Market