
 Aerating Cake Emulsifier Market | 2026-2036
Aerating Cake Emulsifier Market Size, Share, and Industry Trends Forecast 2026-2036
Aerating Cake Emulsifier Market Analysis
Retail bakeries is expanding their share of aerating emulsifier procurement as artisan cake segments gain shelf space against mass-market alternatives. Corbion leverages its microbial fermentation expertise to supply bio-based emulsifiers with consistent aeration stability. Palsgaard anchors European supply through integrated manufacturing in Denmark, while Kerry Group competes on application-specific blends for high-ratio cake systems.
Aerating cake emulsifiers are surface-active agents, typically comprising distilled monoglycerides, polyglycerol esters, or lecithin derivatives, that stabilize air incorporation in batter systems to achieve uniform crumb structure and volume expansion in baked products. Soy lecithin dominates commercial formulations due to cost-efficient supply and functional equivalence across pH ranges, though sunflower lecithin is gaining traction among clean-label portfolios seeking non-GMO positioning. Bakery manufacturers represent the most concentrated end-user margin pool, while foodservice channels show faster volume growth driven by frozen cake base expansion.
EFSA evaluations of emulsifier safety profiles, FDA GRAS self-affirmation requirements, and EU REACH chemical registration obligations collectively elevate compliance costs for synthetic additive suppliers. BIS standards in India and China's SAMR food additive approvals add further jurisdictional complexity for multinational formulation houses. Stakeholders must monitor regulatory divergence between plant-derived and synthetic emulsifier approval pathways when allocating R&D investment across regional product registrations.
Market Dynamics
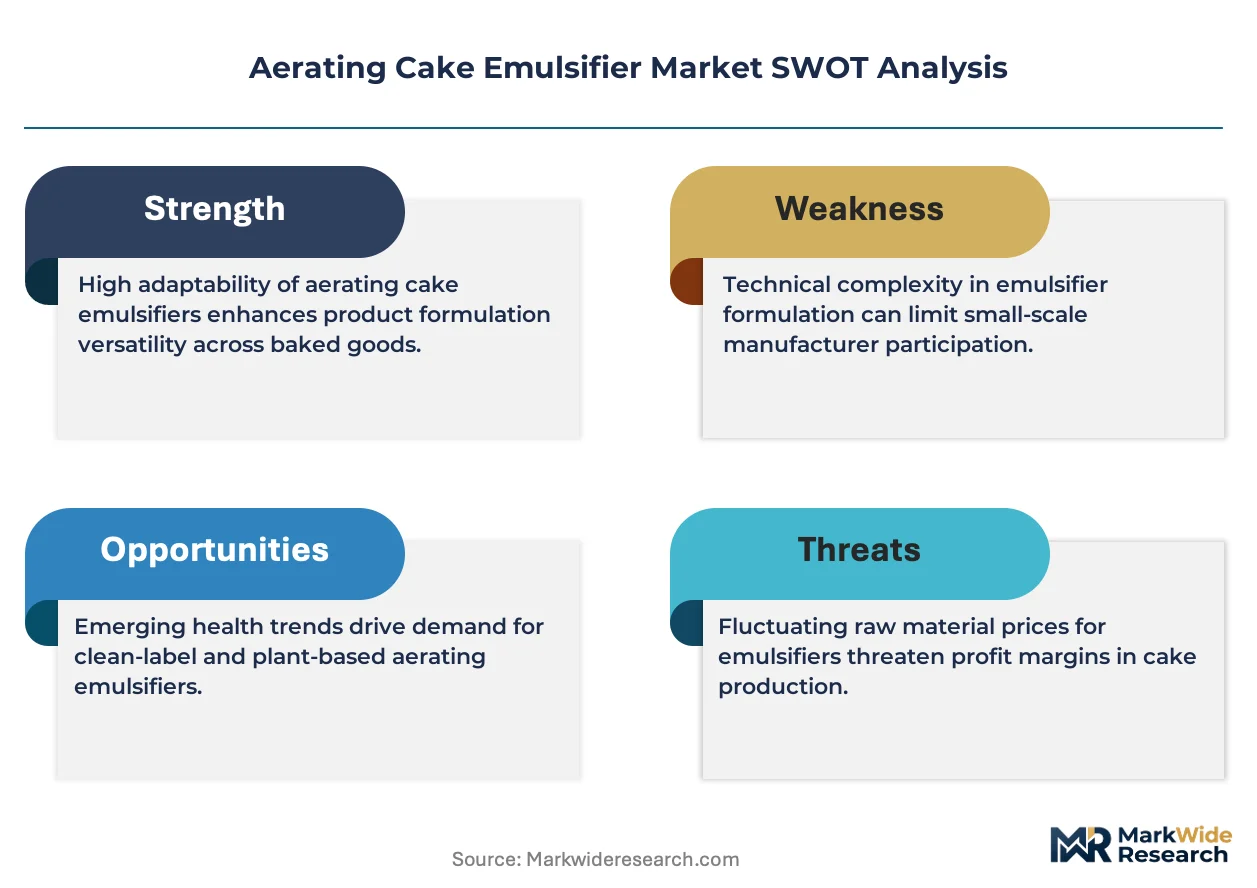
Clean-label mandates from EFSA and FDA are forcing wholesale reformulation of synthetic emulsifier portfolios toward plant-derived alternatives, compressing R&D timelines and elevating raw material qualification costs across the supply base.
Growth Catalysts
- REACH chemical registration obligations:EU regulatory pressure on synthetic additives redirects investment budgets toward bio-based emulsifier development, accelerating substitution timelines in industrial bakery applications.
- Artisan bakery chains:Premium cake segments in Germany and France are scaling procurement of label-friendly aerating systems to capture shelf space from mass-market alternatives.
- Sunflower lecithin:Non-GMO positioning advantages are displacing soy-derived equivalents in clean-label portfolios, opening new formulation specifications for high-ratio sponge cake systems.
Market Restraints
- Raw material concentration:Soy lecithin supply depends on crushing capacity concentrated in Argentina and Brazil, exposing formulators to agricultural commodity volatility and currency fluctuation risk.
- Technical performance ceiling:Plant-derived emulsifiers exhibit narrower temperature stability windows versus synthetic alternatives, limiting application in frozen cake base production requiring extended freeze-thaw tolerance.
- Regulatory fragmentation:Divergent approval pathways between EFSA's novel food assessments and FDA's GRAS self-affirmation create duplicative registration costs for multinational suppliers.
Strategic Opportunities
- India's FSSAI modernization:Streamlined food additive approval timelines are opening access for fermented bio-emulsifiers in the country's expanding organized bakery sector.
- Microbial fermentation platforms:Precision fermentation technology convergence with enzymatic modification is enabling custom-tailored emulsifier molecules with specific HLB values for aeration control.
- Direct-to-manufacturer channels:Digital formulation platforms are bypassing traditional ingredient distributors, allowing emulsifier houses to capture margin and accelerate technical service response times.
Industry Challenges
- Food technologist scarcity:Specialized expertise in emulsion rheology and batter aeration mechanics is concentrated among aging practitioners, constraining formulation innovation capacity at mid-tier suppliers.
- Clean-label certification timelines:Third-party non-GMO and organic validations require 12-18 month audit cycles, delaying product launches and locking working capital in inventory qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerating Cake Emulsifier Market |
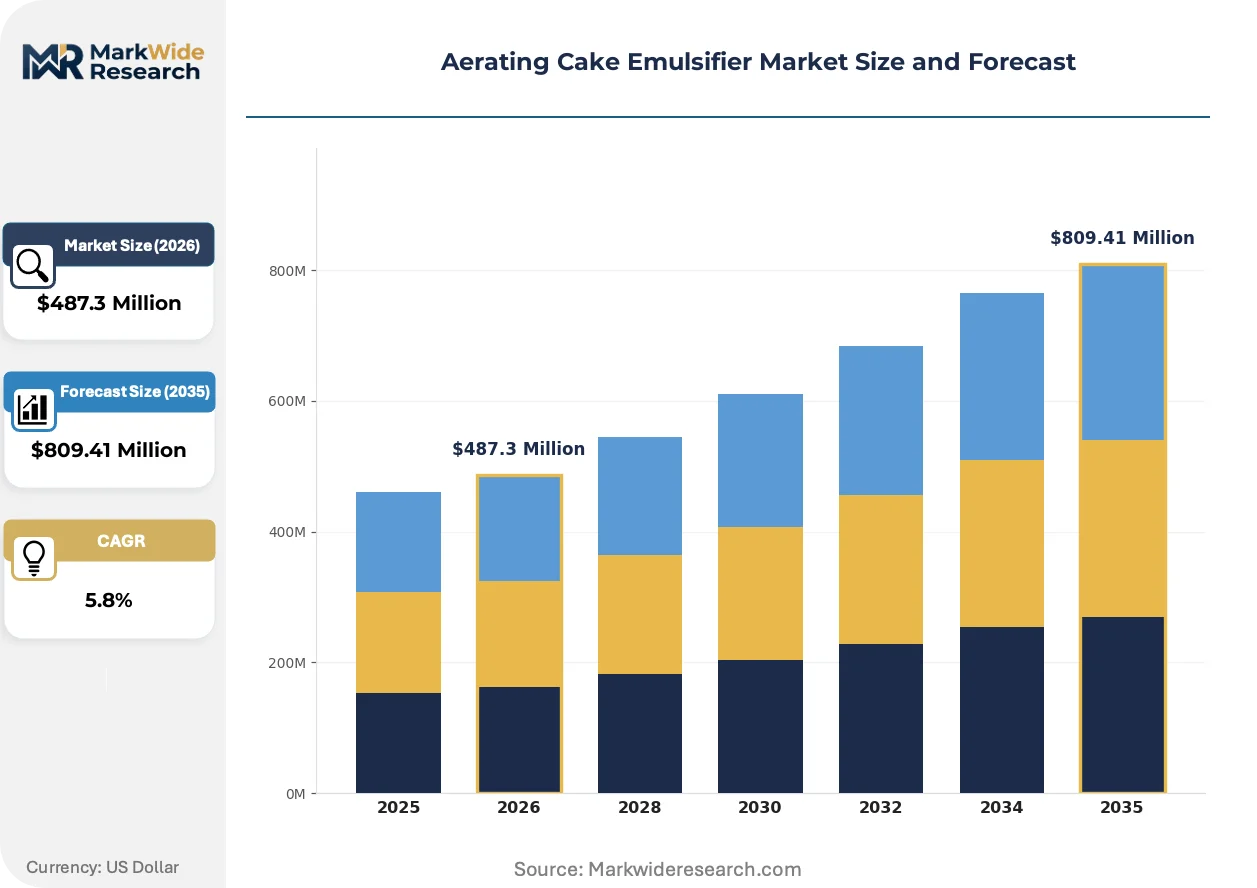
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Lecithin, Egg Lecithin, Sunflower Lecithin, Yeast Extract Application: Baked Goods, Confectionery, Dairy Products, Sauces End User: Bakery Manufacturers, Foodservice, Retail Bakeries, Home Bakers Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Specialty Stores |
| Companies Covered | Corbion, Kerry Group, DowDuPont, Palsgaard, Cargill Incorporated, Archer Daniels Midland Company, BASF SE, Ingredion Incorporated, Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerating Cake Emulsifier Market Emerging Trajectories
Enzymatic modification of phospholipids and precision fermentation of glycolipids are rewriting functional performance benchmarks, while regulatory divergence between jurisdictions is fragmenting formulation standardization efforts.
Microbially-derived sophorolipids and rhamnolipids are expanding into high-performance cake emulsification, delivering foaming stability comparable to synthetic alternatives at reduced usage rates. Industrial bakeries in Germany and artisan producers in Denmark are piloting these bio-surfactants for clean-label sponge cake lines. The technology is expanding into previously cost-prohibitive application segments by achieving price parity through fermentation yield improvements.
EFSA's systematic re-evaluation of food additive safety profiles is tightening acceptable daily intake thresholds for synthetic emulsifiers, triggering reformulation mandates across EU member states. Industrial bakeries face compressed compliance deadlines as existing approvals sunset, forcing parallel development tracks for replacement ingredients. Premium cake manufacturers are responding fastest, leveraging technical partnerships with bio-based suppliers to secure early-mover positioning in clean-label retail channels.
Bakery procurement teams are consolidating supplier relationships around integrated emulsifier-blend providers capable of delivering application-specific technical support. Foodservice channels serving frozen cake bases are displacing fragmented multi-supplier purchasing with single-source partnerships bundling emulsifiers, stabilizers, and texture systems. This concentration is most visible in France and Italy, where artisan bakery cooperatives are negotiating collective procurement agreements to secure volume pricing and dedicated R&D collaboration.
Aerating Cake Emulsifier Market Segmentation
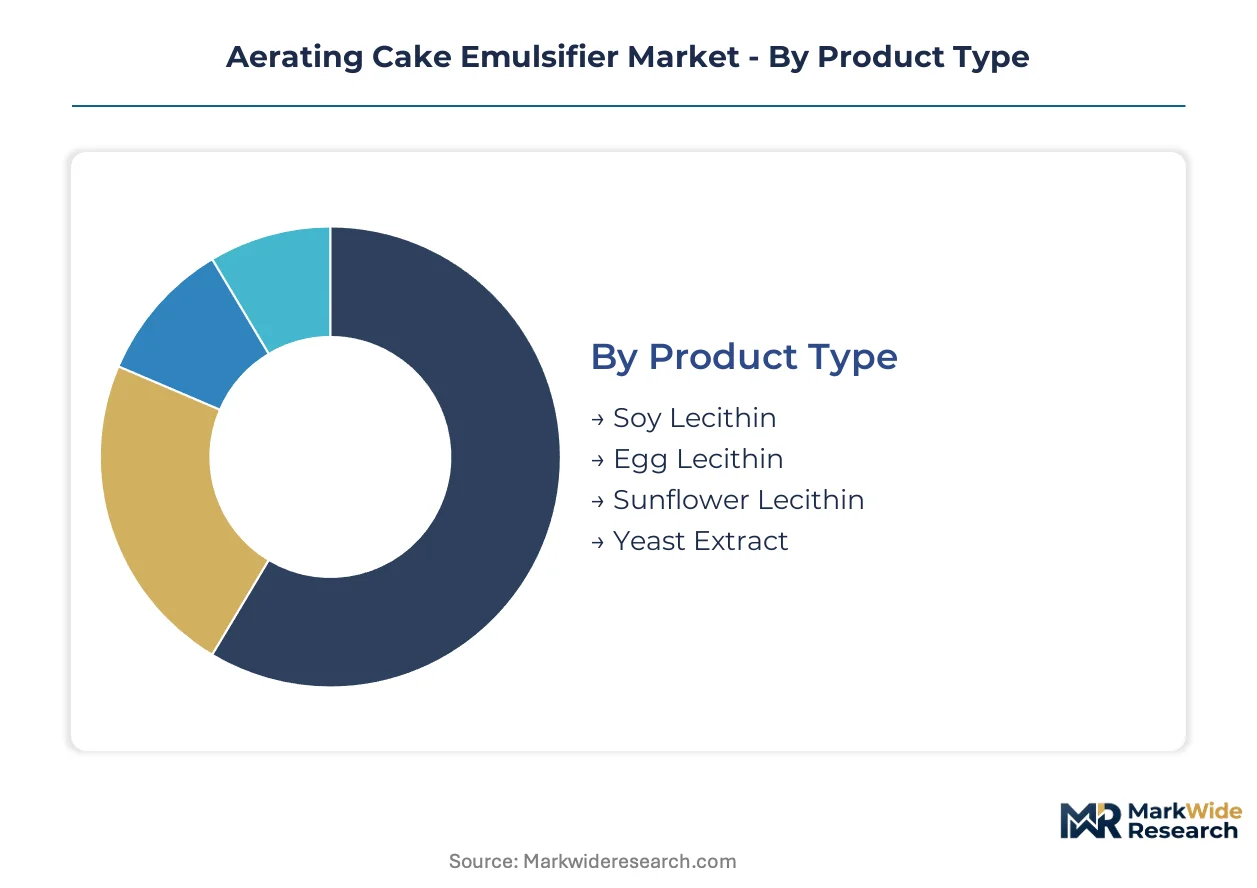
Segmentation in aerating cake emulsifiers reveals how formulation requirements diverge across industrial scale, clean-label positioning, and thermal stability demands. Procurement patterns vary sharply between frozen cake base producers seeking freeze-thaw tolerance and artisan retail bakeries prioritizing non-GMO certification.
Product Type:
Customization versus standardization tension runs deepest here, with commodity lecithins competing against precision-fermented alternatives for specification control.
- Soy Lecithin:Distilled phospholipid fractions extracted from soybean oil processing deliver consistent HLB values across pH ranges. Industrial bakeries in Germany anchor procurement volumes for high-ratio sponge cake systems, though Argentina-Brazil crushing concentration exposes formulators to currency volatility.
- Sunflower Lecithin:Non-GMO phospholipid composition matches soy functional performance while satisfying clean-label portfolio requirements. Demand concentrates among French and Danish artisan producers seeking retail shelf differentiation from mass-market alternatives.
- Egg Lecithin:Phosphatidylcholine-rich extracts from egg yolk provide superior emulsification in premium pastry applications.
- Yeast Extract:Fermentation-derived bio-emulsifiers gaining traction in plant-based cake formulations.
Leading the category by volume: Soy Lecithin. Expanding most quickly: Sunflower Lecithin.
Application:
Cost tier separation distinguishes commodity volume plays from premium positioning opportunities across thermal processing requirements.
- Baked Goods:Aerating emulsifiers stabilize air incorporation in high-sugar, high-fat batter systems for uniform crumb structure. Cake manufacturers in Germany and France represent the concentrated margin pool, with frozen cake base expansion driving fastest volume growth in foodservice channels.
- Confectionery:Controlled aeration in nougat and marshmallow applications demands precise HLB specification. European premium chocolate producers are scaling procurement of plant-derived alternatives ahead of EFSA additive re-evaluations.
- Dairy Products:Whipped topping and mousse applications require freeze-thaw stable emulsification systems.
- Sauces:Vinaigrette and mayonnaise emulsification represents niche volume with distinct stability requirements.
Dominating revenue concentration: Baked Goods. Steepest expansion trajectory: Confectionery clean-label reformulation.
End User:
Customer type fragmentation separates integrated manufacturers from fragmented service channels with diverging technical service expectations.
- Bakery Manufacturers:Industrial-scale producers operate automated high-ratio cake lines requiring consistent emulsifier performance across batch sizes. Procurement concentrates among German industrial bakeries supplying private-label retail, with technical partnerships replacing transactional purchasing.
- Foodservice:Frozen cake base producers and QSR chains demand extended freeze-thaw tolerance specifications. Volume growth outpaces manufacturing channels as central kitchen models expand across France and Italy.
- Retail Bakeries:Artisan chains in Denmark and France negotiate collective procurement for clean-label emulsifier blends.
- Home Bakers:Consumer-packaged emulsifier sales remain marginal with limited penetration outside specialty baking segments.
Highest margin capture: Bakery Manufacturers. Gaining share fastest: Foodservice frozen base applications.
Distribution Channel:
Supply concentration dynamics favor integrated blend providers over fragmented multi-supplier relationships.
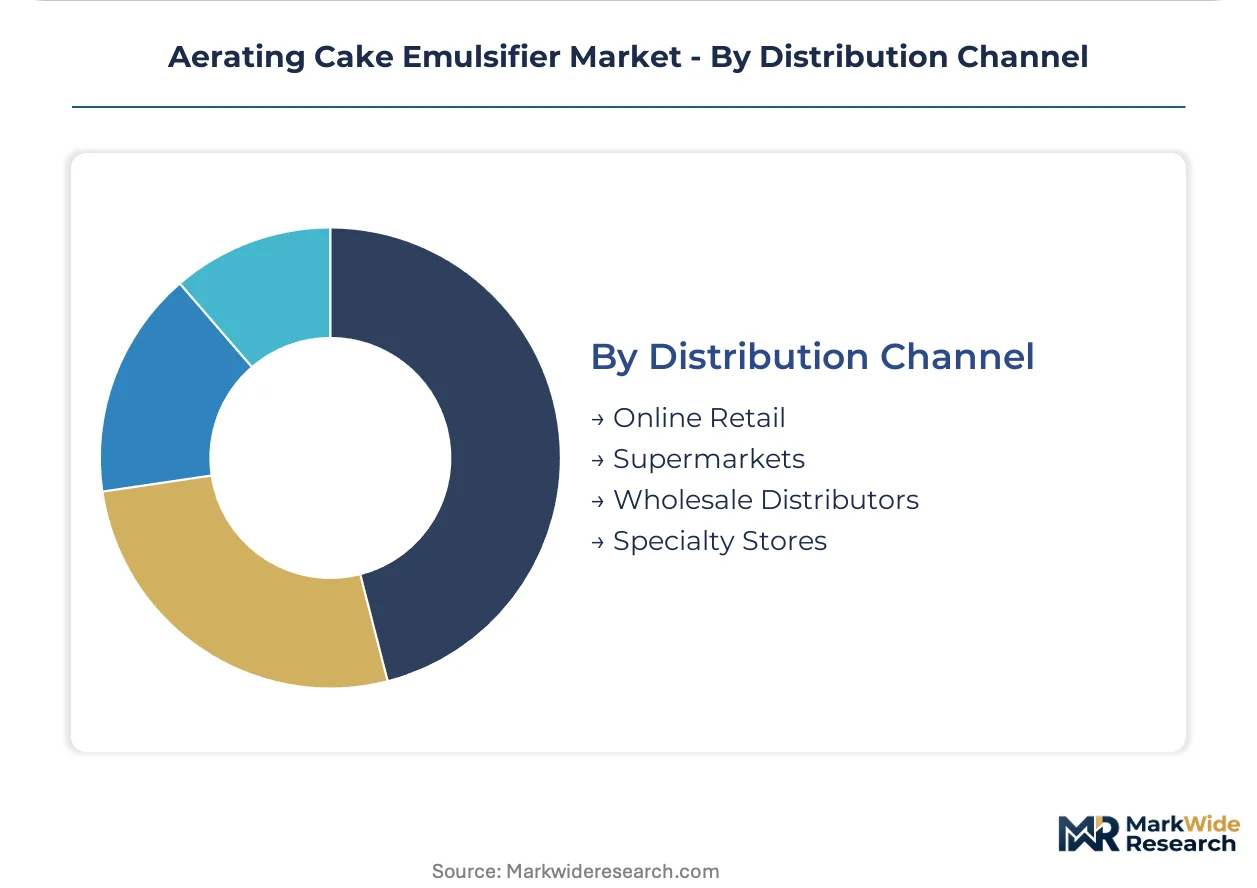
- Wholesale Distributors:Traditional ingredient distribution channels retain volume dominance in industrial bakery supply chains. Palsgaard and Kerry Group leverage direct technical service relationships to bypass distributor margins in key accounts.
- Online Retail:Digital formulation platforms enable emulsifier houses to capture margin and accelerate technical response times. Direct-to-manufacturer channels are displacing fragmented purchasing among mid-tier European bakeries.
- Supermarkets:Limited emulsifier sales confined to consumer-packaged specialty baking ingredients.
- Specialty Stores:Professional baking supply outlets serve artisan retail bakeries with small-batch procurement needs.
Retaining volume leadership: Wholesale Distributors. Climbing the fastest: Online Retail direct channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial bakery clusters in Lower Saxony and Bavaria concentrate emulsifier procurement through tax-advantaged food processing zones near Hamburg and Munich. These designated manufacturing corridors attract formulation houses seeking proximity to automated high-ratio cake production lines serving private-label retail across the continent.
Germany
Industrial bakeries in Lower Saxony anchor European emulsifier consumption through automated sponge cake lines supplying discounters. EFSA's additive re-evaluation timeline compresses reformulation windows for synthetic alternatives. The Munich-Stuttgart corridor hosts technical service partnerships between bio-based suppliers and premium cake manufacturers.
France
Artisan bakery cooperatives in Île-de-France negotiate collective procurement agreements for clean-label emulsifier blends. REACH registration obligations elevate compliance costs for synthetic additive portfolios. The Lyon-Grenoble cluster pilots microbially-derived sophorolipids for retail sponge cake differentiation.
United States
Frozen cake base producers in the Midwest demand extended freeze-thaw tolerance specifications from emulsifier suppliers. FDA GRAS self-affirmation requirements create divergent approval pathways versus European regulators. Chicago-area foodservice distributors consolidate purchasing around integrated blend providers bundling emulsifiers with stabilizer systems.
India
Organized bakery sector expansion in Maharashtra and Gujarat drives demand for fermented bio-emulsifiers in high-ratio cake applications. FSSAI modernization streamlines food additive approval timelines for microbial fermentation platforms. The Mumbai-Pune corridor attracts technical partnerships between domestic ingredient distributors and international formulation houses.
Denmark
Precision fermentation expertise concentrates near Copenhagen, supplying bio-based emulsifiers with consistent aeration stability. EU Green Deal funding accelerates substitution timelines for plant-derived alternatives in industrial applications. The Aarhus food cluster integrates enzymatic phospholipid modification with artisan bakery technical service programs.
Aerating Cake Emulsifier Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated formulation houses capturing margin through application-specific technical service while commodity suppliers compete on lecithin volume. The vendor base organizes around three archetypes: microbial fermentation platforms, integrated emulsifier-blend providers, and agricultural commodity processors with downstream phospholipid fractionation. Consolidation pressures favor backward integration into crushing capacity and captive supply of non-GMO oilseed streams. Geographic expansion through direct-to-manufacturer digital channels and strategic partnerships for regional regulatory navigation represent dominant competitive vectors.
Among microbial fermentation specialists, Corbion leverages Danish biotechnology infrastructure to supply bio-based emulsifiers, while Kerry Group competes on application-specific blends for high-ratio cake systems. Palsgaard anchors European supply through integrated manufacturing capabilities. These three occupy distinct positions within the clean-label reformulation wave: Corbion exemplifies precision fermentation scale-up, Kerry Group represents technical service bundling, and Palsgaard sits within the integrated manufacturing archetype controlling upstream oilseed processing.
| Leading Market Players |
|---|
| Corbion |
| Kerry Group |
| DowDuPont |
| Palsgaard |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| BASF SE |
| Ingredion Incorporated |
| Stepan Company |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between organic-non-GMO and conventional lecithin tiers generates price spreads exceeding raw material cost differentials, with supply chain configurations tracking this bifurcation through dedicated crushing facilities and segregated logistics networks. EFSA additive re-evaluations compress reformulation timelines, forcing buyers into premium-certified supply channels at elevated procurement costs.
Pricing Analysis
Lead-time premiums reward rapid-turn microbial fermentation batches while spot-market soy lecithin trades at discounts reflecting Argentina-Brazil harvest cycles. Three-tier pricing structure across premium, standard, and economy levels separates precision-fermented bio-emulsifiers from distilled soy fractions and commodity unrefined lecithin. Pricing pressure stems from REACH compliance cost absorption and currency volatility in South American oilseed markets. Industrial bakeries in Germany exhibit lowest price sensitivity due to technical service bundling, while mid-tier European foodservice distributors face margin compression from frozen cake base specification tightening.
Supply Chain Analysis
EU Green Deal local-content provisions reshape sourcing toward Danish and German fermentation capacity, displacing traditional Argentine-Brazilian soy lecithin dominance. Raw material flows draw from sunflower seed crushing in Eastern Europe, non-GMO soybean streams from North American contract farming, and precision-fermentation feedstocks near Copenhagen biotechnology clusters. Single-source vulnerability concentrates in phospholipid fractionation capacity controlled by integrated oilseed processors. Distribution runs through direct-to-manufacturer digital platforms bypassing traditional ingredient distributors, with technical service partnerships replacing transactional wholesale relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerating cake emulsifier sector sits in a technology-transition phase where precision-fermented glycolipids displace legacy synthetic alternatives, compressing incumbent reformulation windows and elevating R&D qualification costs across the supply base.
For Market Incumbents: Deploy backward integration into non-GMO oilseed crushing to secure captive supply of sunflower lecithin feedstocks, insulating margin from Argentine currency volatility and EFSA-driven substitution mandates. Deepen technical service partnerships with German industrial bakeries to lock in specification control ahead of bio-emulsifier commoditization. Counter microbial fermentation entrants by accelerating enzymatic phospholipid modification capabilities through Copenhagen-Aarhus cluster collaborations. For New Entrants and Emerging Players: Capture white-space in India's FSSAI-modernized approval pathway for fermented bio-emulsifiers, where organized bakery sector expansion outpaces domestic supply capacity. Target French artisan bakery cooperatives seeking collective procurement of clean-label blends with non-GMO certification. Penetrate through digital formulation platforms offering rapid technical response and direct margin capture versus distributor-dependent incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation platforms given EU Green Deal funding acceleration and EFSA synthetic additive sunset timelines. Long-term viability favors biotechnology infrastructure with enzymatic modification capabilities and existing bakery manufacturer technical partnerships. Monitor FSSAI approval velocity in India as inflection indicator for emerging market penetration feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Captive non-GMO supply secures margin against Argentine-Brazilian currency volatility and EFSA-driven reformulation mandates. |
| Precision Fermentation Scale-Up | Danish biotechnology clusters achieve cost parity with synthetic emulsifiers through yield improvements in sophorolipid production. |
| Digital Platform Direct Sales | Direct-to-manufacturer channels bypass distributor margins and accelerate technical service response for mid-tier bakeries. |
| Regulatory Pre-Approval Investment | Early FSSAI and SAMR registration locks emerging market access before competitor formulation standardization. |
| Technical Service Partnership Consolidation | Single-source bundling of emulsifiers, stabilizers, and texture systems captures foodservice frozen cake base procurement. |
Methodological Framework
Multi-period observation of EFSA additive re-evaluation timelines, FDA GRAS submission patterns, and bakery procurement consolidation trends anchored the trend analysis, supplemented by interviews with fermentation technology directors, industrial bakery procurement leads, foodservice distribution channel managers, and clean-label certification auditors. Secondary validation drew from EU REACH registration databases, FSSAI food additive approval records, customs trade data on phospholipid imports, and SEC filings of integrated ingredient suppliers. Bottom-up volume modeling across product types and applications triangulated against top-down market sizing from regional production cluster analysis.
Input-output matrices mapped lecithin crushing capacity, fermentation yield curves, and bakery line automation rates to emulsifier demand across the projection horizon. Segmentation dimensions modeled include product type certification grade, application thermal stability requirements, end-user scale tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating substitution timelines for synthetic-to-bio-emulsifier transitions. Industry-specific forecast inputs encompassed EFSA sunset schedule assumptions and EU Green Deal funding allocation trajectories for biotechnology infrastructure.
The model holds under sustained regulatory pressure on synthetic additives and stable oilseed commodity price bands; deviation in FSSAI approval velocity or Argentine drought cycles would shift volume trajectories. Forecasts reflect documented assumptions on clean-label certification adoption curves and bakery sector consolidation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Cakes and Pastries Market
Bakery Products
Dough Whitener Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Personalized Bakery Products Market
Bakery Products
Bakery Conditioner Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Dough Conveyor Market
Bakery Products
Pastry Dough Market
Bakery Products
Cookies Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Specialty Bakery Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
No-Fat Cake Market
Bakery Products
Organic Frozen Bakery Market