
 Premixed Bread Flour Market | 2026-2036
Premixed Bread Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Premixed Bread Flour Market Insights
North American milling capacity is expanding as integrated grain processors build dedicated premix lines to capture downstream margin. ADM leverages its origination-to-ingredient pipeline to supply bakeries with traceable wheat profiles and functional additive systems. Puratos sustains competitive position through fermentation technology leadership and regional recipe customization for artisan and industrial clients alike. Lesaffre anchors European supply with yeast-bread premix synergies that reduce client procurement complexity.
Premixed bread flour combines milled wheat or alternative grains with pre-measured functional ingredients including enzymes, emulsifiers, and conditioners, requiring precise hydration parameters and controlled protein content to ensure batch consistency for commercial baking operations. Whole wheat flour and gluten-free flour represent the fastest-expanding product categories as health-positioned bakeries reformulate menus, while white flour maintains volume dominance in mass-market food service channels. Bakeries and restaurants command the largest end-user value pool, though household pouches through online retail channels are gaining traction as home baking persists post-pandemic.
FDA food additive regulations and USDA organic certification standards govern ingredient declarations and clean-label positioning in the United States, while the EU Green Deal and EFSA health claims frameworks shape reformulation priorities across European markets. The CSRD disclosure requirements will increasingly force ingredient suppliers to document Scope 3 emissions from agricultural sourcing through finished premix distribution. Stakeholders must monitor evolving enzyme approval pathways and carbon accounting mandates to preserve market access and premium positioning.
Market Dynamics
Clean-label reformulation pressure from the EU F-Gas Regulation and CSRD disclosure mandates is compressing formulation timelines while fragmenting supplier tiers between compliant specialty blenders and commodity flour processors.
Growth Catalysts
- Artisan Bakery Expansion:Craft bread revival across Germany and France drives demand for consistent, small-batch premixes that eliminate in-house blending expertise requirements.
- CSRD Carbon Accounting:The EU Corporate Sustainability Reporting Directive forces bakeries to document Scope 3 emissions, favoring premix suppliers with traceable agricultural sourcing and verified supply chain data.
- Enzyme Innovation:Novel enzyme systems reduce chemical additive dependence while maintaining dough stability, enabling cleaner-label positioning in premium retail channels.
Market Restraints
- Wheat Price Volatility:Input cost swings from Black Sea supply disruptions and drought cycles in North American grain belts compress blending margins and destabilize contract pricing.
- Supply Concentration Risk:European industrial baking clusters in Germany and the Netherlands create geographic dependency, exposing buyers to localized logistics bottlenecks and port congestion.
- Technical Limitation:Gluten-free flour premixes face hydration sensitivity and texture consistency constraints that limit adoption in high-volume commercial operations.
Strategic Opportunities
- Household Channel Growth:Post-pandemic home baking persistence in the United States and United Kingdom creates demand for premium pouch formats through direct-to-consumer and specialty retail channels.
- EU Green Deal Tailwind:Farm-to-fork sustainability mandates accelerate reformulation toward organic-certified premixes with reduced synthetic inputs and regenerative wheat sourcing.
- Fermentation Technology Convergence:Integration of controlled fermentation systems with premix platforms enables bakeries to offer differentiated flavor profiles without dedicated sourdough infrastructure.
Industry Challenges
- Formulation Expertise Gap:Industrial bakeries struggle to recruit technologists capable of optimizing hydration parameters and protein content across diverse premix specifications.
- Clean-Label Certification Timeline:USDA organic and EU organic logo approvals require 12-18 month documentation cycles that delay product launches and tie up R&D resources.
- Legacy Equipment Integration:Existing mixer and proofing systems in mid-scale bakeries require retrofitting to handle alternative-grain premixes with divergent absorption rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premixed Bread Flour Market |
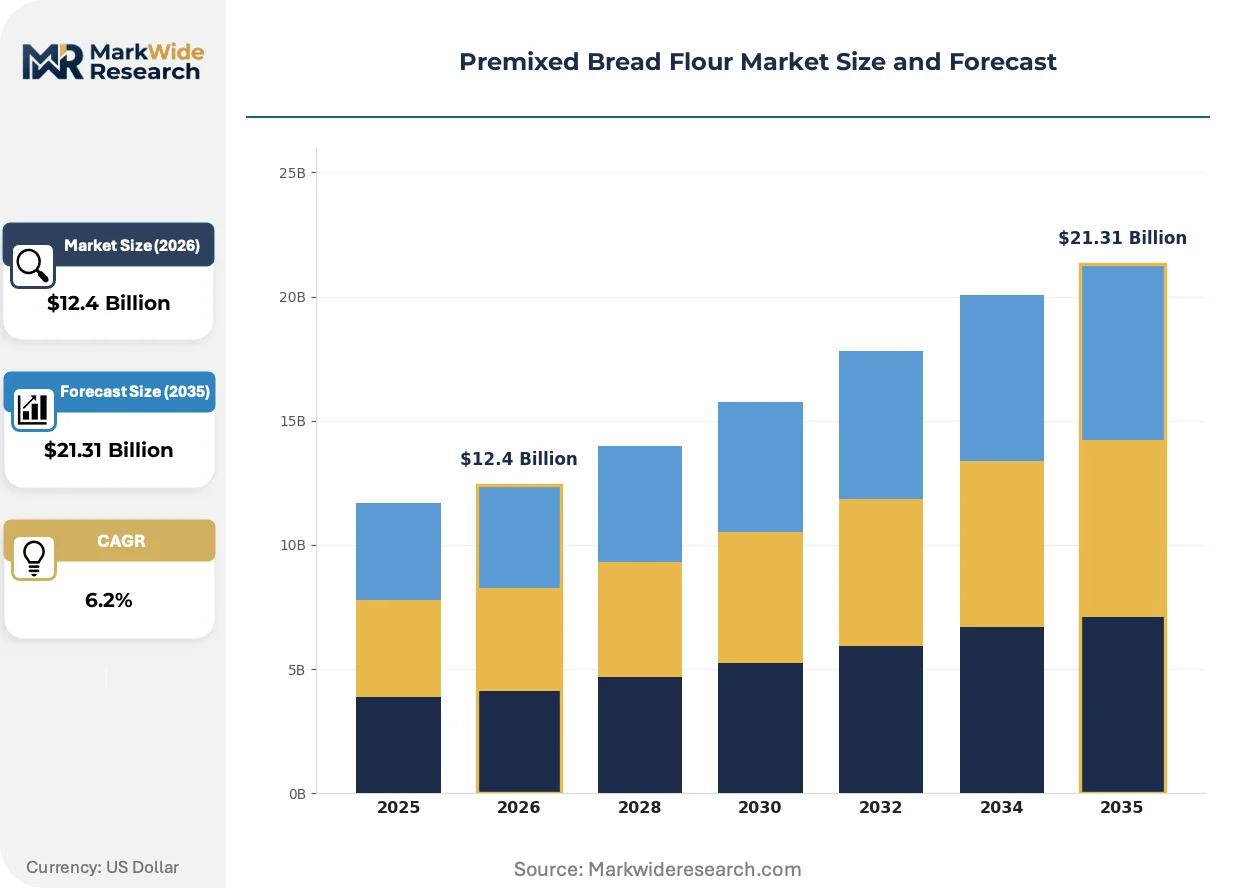
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $21.31 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Flour, Whole Wheat Flour, Gluten-Free Flour, Specialty Flours End User: Bakeries, Restaurants, Households, Food Services Packaging Type: Bulk Packaging, Retail Packaging, Pouches, Bags Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | ADM, Puratos, Lesaffre, Associated British Foods, Bakels Group, Allied Pinnacle, General Mills, Rich Products Corp, Nisshin Seifun Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premixed Bread Flour Market Trends and Innovations
Active enzyme systems and fermentation-controlled platforms are displacing traditional chemical conditioners, while sustainability mandates reconfigure sourcing priorities and procurement relationships across the value chain.
Biotechnological enzyme engineering is electrifying dough development processes by replacing DATEM and SSL emulsifiers with protein-based alternatives. Artisan and industrial bakeries in France and Italy are adopting these systems at accelerated rates to meet clean-label retail requirements. This transition is compressing the addressable market for synthetic additive suppliers while expanding margins for biotechnology-enabled blenders.
The EU F-Gas Regulation and REACH chemical restrictions are forcing reformulation of conditioning agents and shelf-life extenders. Industrial consequences include accelerated R&D spending and supplier qualification audits for European premix manufacturers. German and Dutch industrial baking clusters are most affected, responding by consolidating procurement around certified clean-label suppliers with documented ESG compliance.
Direct-to-restaurant distribution models are bypassing traditional foodservice distributors in metropolitan baking corridors. Specialty premix suppliers now contract directly with bakery chains and restaurant groups, replacing broadline distribution with contracted volume agreements. This pattern is most visible in London, Paris, and New York, where procurement teams prioritize traceability and technical support over distributor breadth.
Premixed Bread Flour Market Segmentation
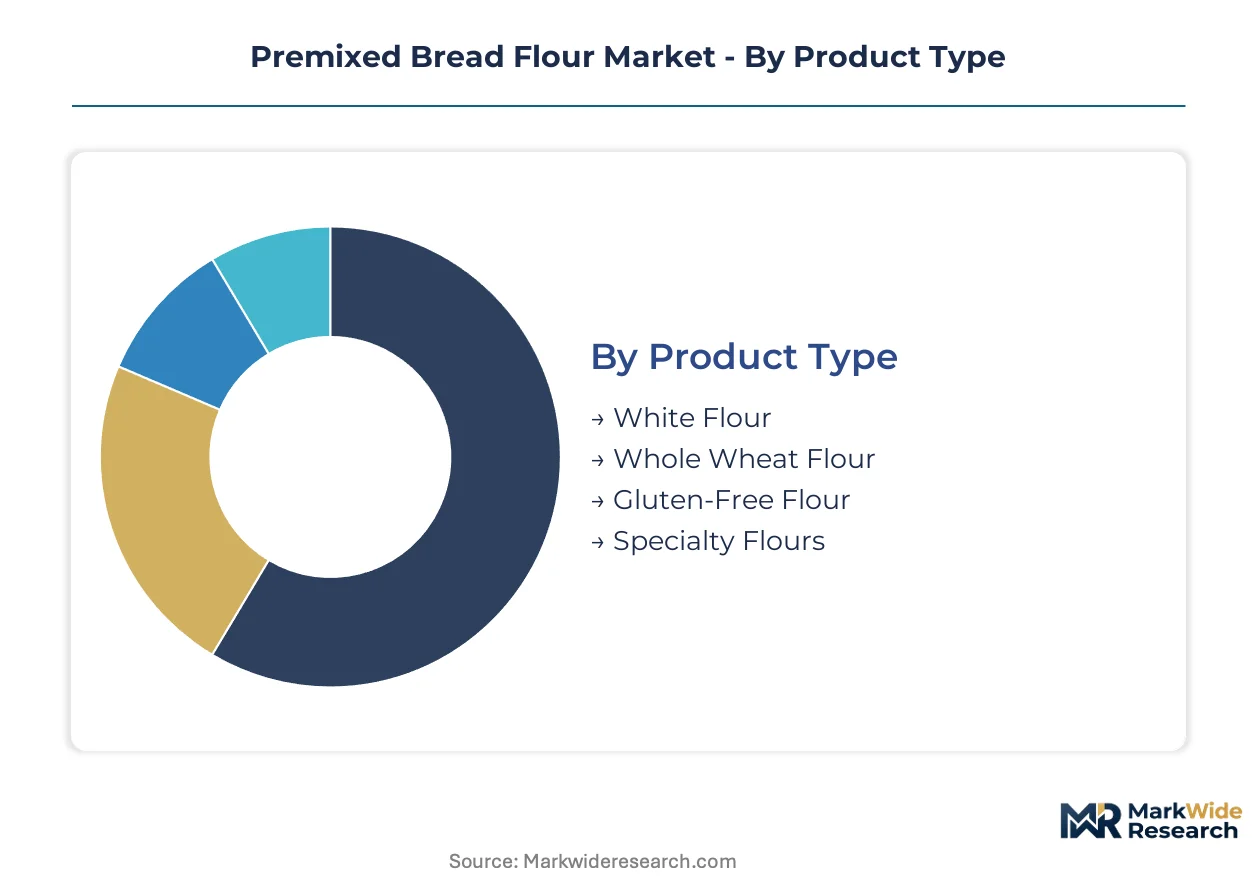
Premixed bread flour segmentation reveals divergent certification burdens across product categories, with organic and gluten-free variants demanding extended documentation cycles while conventional white flour moves through standardized approval pathways. End-use and channel distinctions further complicate compliance, as foodservice buyers prioritize bulk traceability while household pouches face retail labeling mandates.
Product Type:
White flour premixes require minimal additive disclosure under FDA and EFSA baseline standards, while whole wheat and gluten-free variants trigger USDA organic, EU organic logo, and novel enzyme approval pathways that extend qualification timelines.
- White Flour:Milled wheat premixes with standardized protein content and pre-measured conditioners dominate mass-market foodservice procurement. Demand concentrates in German industrial baking clusters where procurement teams prioritize cost stability over clean-label positioning.
- Whole Wheat Flour:Bran-inclusive formulations with adjusted hydration parameters and extended shelf-life enzyme systems. Artisan bakeries in France and Italy drive fastest adoption as operators reformulate menus to meet EU Green Deal farm-to-fork sustainability mandates.
- Gluten-Free Flour:Rice, tapioca, and alternative grain blends with binding hydrocolloids and texture-modifying starches face EFSA novel food consultations and extended safety assessments.
- Specialty Flours:Ancient grain, sprouted wheat, and regenerative-sourced premixes carrying third-party certifications including Demeter and Regenerative Organic Certified.
Leading the category by volume: White Flour. Growing fastest: Whole Wheat Flour.
End User:
Commercial bakeries and restaurant chains negotiate contracted volume agreements with technical support provisions, while household buyers through direct-to-consumer channels absorb premium pricing for convenience formats.
- Bakeries:Industrial and artisan operators purchasing pallet-scale premixes with specified protein content and fermentation control parameters. German craft bread revival drives dual-track demand for standardized and premium formulations.
- Restaurants:Casual dining and bakery-café chains sourcing traceable premixes for in-house bread programs. Direct procurement from specialty blenders in London, Paris, and New York metropolitan corridors accelerates as distributors are bypassed.
- Households:Post-pandemic home baking persistence in the United States and United Kingdom sustains demand for premium pouch formats with recipe instructions and measured yield packaging.
- Food Services:Institutional catering and contract feeding operations prioritizing bulk cost efficiency and consistent batch performance over label positioning.
Volume concentration: Bakeries. Fastest expansion trajectory: Households.
Packaging Type:
Packaging selection correlates with moisture sensitivity and shelf-life requirements, with enzyme-active premixes demanding barrier properties that bulk formats cannot provide.
- Bulk Packaging:Tote and silo-delivered premixes for industrial bakeries with high-throughput mixer systems and controlled storage environments.
- Retail Packaging:Multi-kilogram bags for small commercial operators and high-volume household consumers through supermarket channels.
- Pouches:Single or small-batch formats with oxygen barrier layers preserving enzyme activity for premium household and specialty retail distribution.
- Bags:Standard paper or polywoven formats for foodservice distributors serving mid-scale bakery and restaurant accounts.
Dominant by throughput: Bulk Packaging. Gaining share fastest: Pouches.
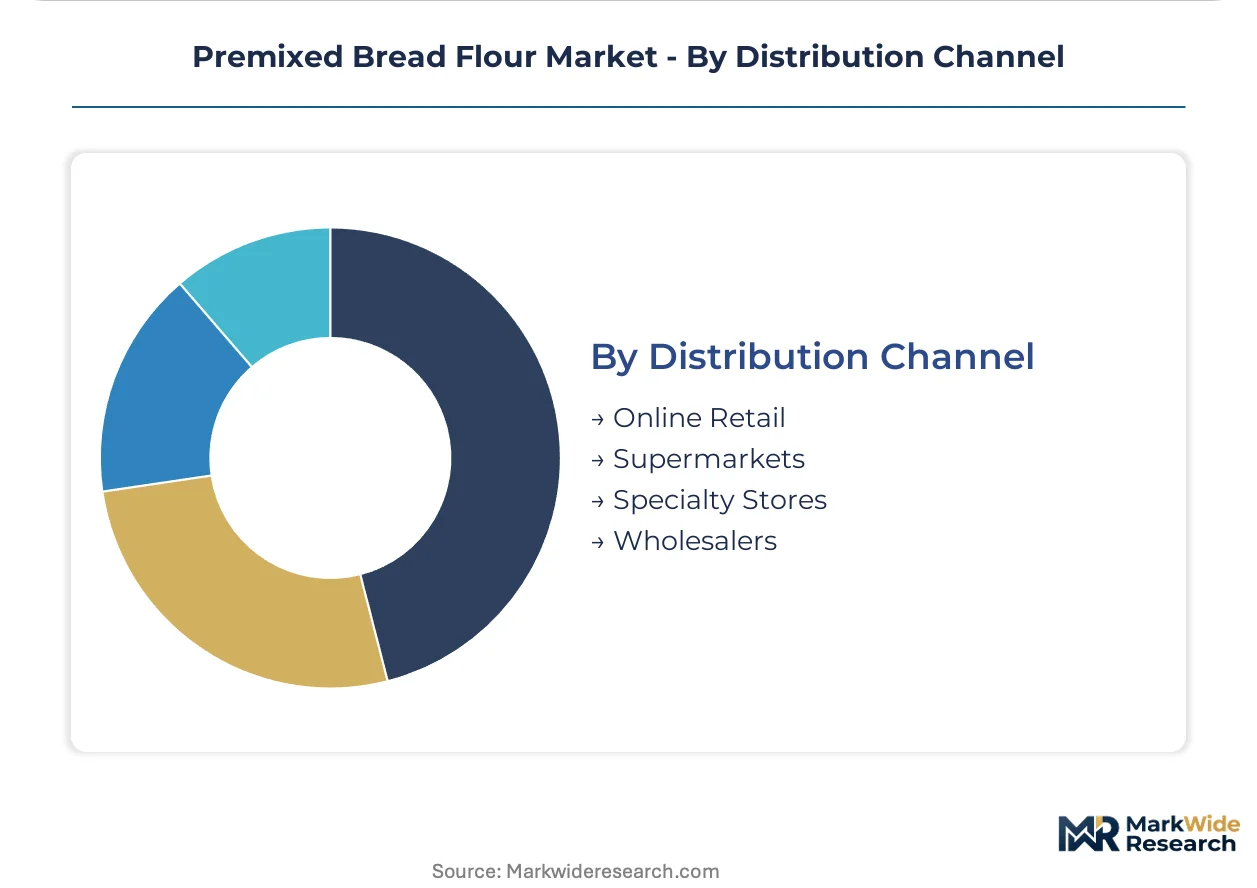
Distribution Channel:
Channel selection determines margin capture and traceability depth, with direct contracting displacing traditional distribution in metropolitan baking corridors.
- Online Retail:Direct-to-consumer platforms and specialty ingredient marketplaces serving household and small commercial buyers with subscription and replenishment models.
- Supermarkets:Mass retail placement for household pouch formats requiring slotting fees and promotional support investments.
- Specialty Stores:Gourmet and professional supply retailers offering technical consultation and recipe customization for artisan bakery clientele.
- Wholesalers:Broadline foodservice distributors consolidating procurement for mid-scale restaurant and institutional accounts with less stringent traceability requirements.
Volume leader: Wholesalers. Steepest expansion: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hard red winter wheat from the Great Plains and Canadian Prairies supplies protein-rich grain to milling operations across North America and Europe. These origination zones anchor premix formulation quality and determine regional supply security for industrial baking clusters.
United States
Kansas and Oklahoma hard wheat belts feed ADM's integrated origination-to-ingredient pipeline, enabling traceable wheat profiles for commercial bakeries. FDA food additive regulations govern enzyme and emulsifier declarations, while USDA organic certification standards shape clean-label positioning. Chicago and Minneapolis milling corridors concentrate capacity expansion as grain processors build dedicated premix lines to capture downstream margin.
Germany
Craft bread revival across Bavaria and North Rhine-Westphalia creates dual-track demand for standardized and premium premix offerings. The EU F-Gas Regulation and CSRD disclosure mandates compress formulation timelines toward cleaner-label emulsifiers. Munich and Hamburg industrial baking clusters consolidate procurement around certified suppliers with documented ESG compliance and verified supply chain data.
France
Artisan bakeries in Île-de-France and Auvergne-Rhône-Alpes adopt novel enzyme systems at accelerated rates to meet clean-label retail requirements. EFSA health claims frameworks shape reformulation priorities for functional ingredient positioning. Lyon and Paris metropolitan corridors witness direct-to-restaurant distribution models bypassing traditional foodservice distributors.
United Kingdom
Post-pandemic home baking persistence sustains demand for premium pouch formats through direct-to-consumer channels. EU Green Deal farm-to-fork sustainability mandates accelerate organic-certified premix adoption despite Brexit regulatory divergence. London baking corridors prioritize traceability and technical support over distributor breadth in procurement decisions.
Japan
Nisshin Seifun Group anchors domestic supply with yeast-bread premix synergies reducing client procurement complexity. METI standards and JIS certification requirements govern quality specifications for commercial bakery applications. Tokyo-Osaka industrial corridors concentrate demand for consistent, small-batch premixes eliminating in-house blending expertise requirements.
Premixed Bread Flour Market Competitive Landscape
Global majors compete with regional champions across origination networks and fermentation technology platforms. The vendor base stratifies between integrated grain processors with captive wheat supply and specialty blenders focused on enzyme innovation and recipe customization. Three archetypes dominate: multinational agribusiness conglomerates with backward integration into grain origination, European fermentation technology specialists with regional recipe customization capabilities, and Asia-Pacific millers with yeast-premix integration. Competitive moves concentrate on capacity expansion in North American wheat belts and strategic partnerships for carbon accounting data sharing.
Within the integrated agribusiness tier, ADM exemplifies origination-to-ingredient pipeline control through traceable wheat profiles and functional additive systems. Puratos and Lesaffre occupy positions as European fermentation technology leaders, with the former sustaining competitive position through regional recipe customization and the latter anchoring supply through yeast-bread premix synergies. Associated British Foods represents the diversified food conglomerate archetype with cross-category ingredient capabilities. These named entities illustrate the competitive tension between scale-driven grain processors and technology-enabled specialty blenders.
| Leading Market Players |
|---|
| ADM |
| Puratos |
| Lesaffre |
| Associated British Foods |
| Bakels Group |
| Allied Pinnacle |
| General Mills |
| Rich Products Corp |
| Nisshin Seifun Group |
| Others |
Pricing and Supply Chain Analysis
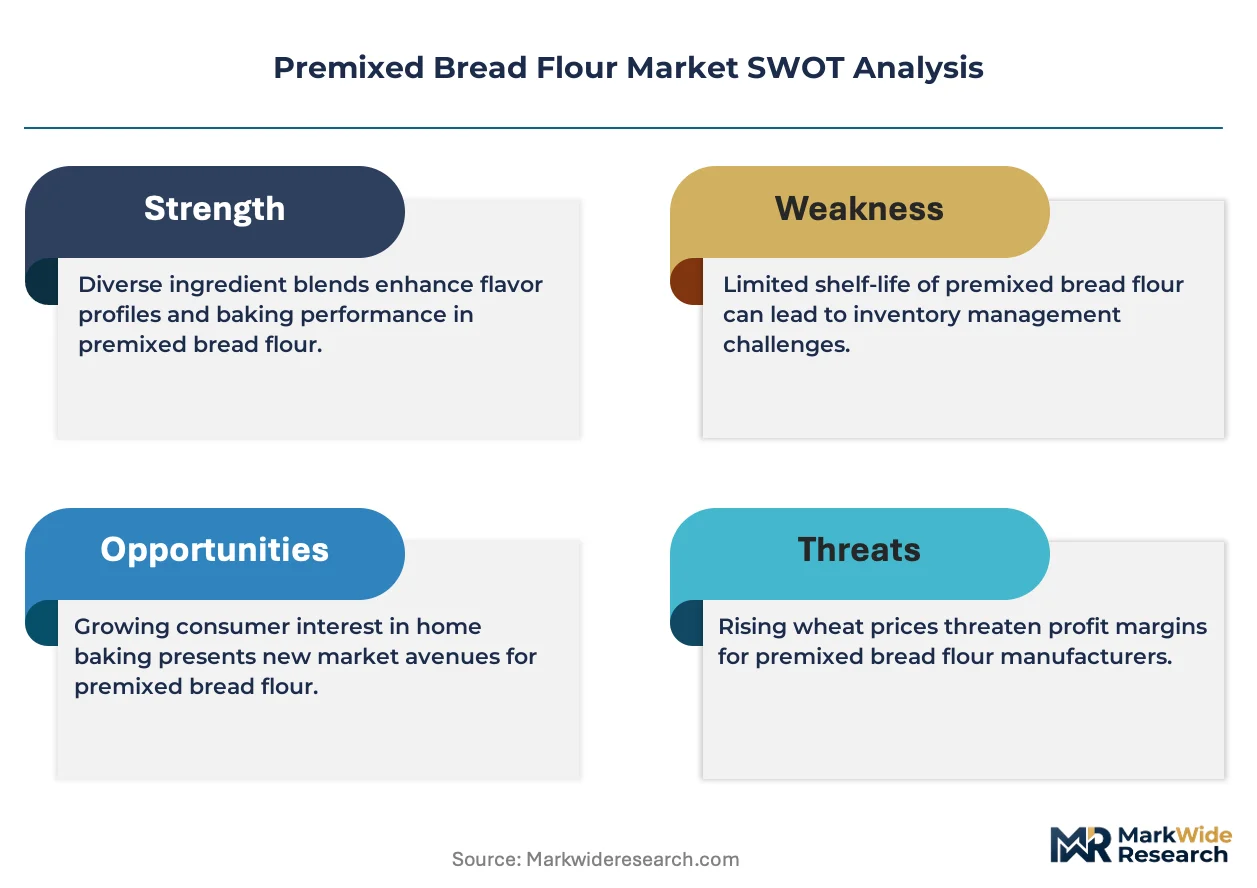
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating cleaner-label emulsifier reformulation that only certified specialty blenders can deliver. German industrial baking clusters now pay sustained premiums for documented ESG compliance while commodity flour processors face margin compression from excluded contract opportunities.
Pricing Analysis
Technical service bundling separates premium premix suppliers from commodity competitors, with recipe customization and fermentation consulting included in contracted volume agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and traceability depth, with organic-certified and enzyme-innovative formulations commanding substantial markups over conventional white flour. Cost compression in the gluten-free tier is intensifying because EFSA novel food consultations extend qualification timelines and tie up R&D resources. Foodservice distributors serving mid-scale restaurant accounts exhibit highest price sensitivity, while artisan bakeries in France and Italy absorb premiums for clean-label positioning.
Supply Chain Analysis
Freight cost volatility from Black Sea supply disruptions and port congestion in Rotterdam and Hamburg feeds into contracted pricing adjustments for European industrial baking clusters. Hard red winter wheat from Kansas and Oklahoma, Canadian Prairie spring wheat, and regenerative-sourced grain from France constitute the primary agricultural inputs. Single-source vulnerability concentrates in German and Dutch industrial baking clusters where localized logistics bottlenecks expose buyers to delivery interruptions. Distribution runs through direct-to-restaurant contracting in metropolitan corridors, bypassing traditional foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Milling capacity expansion lags demand growth from craft bread revival, propping pricing power for qualified suppliers with fermentation technology platforms and documented carbon accounting.
For Market Incumbents: Hedge against enzyme innovation disruption by acquiring biotechnology-enabled blenders with protein-based emulsifier capabilities. Consolidate procurement relationships around German industrial baking clusters through capacity addition in North American wheat belts, securing captive supply of traceable hard red winter wheat profiles. For New Entrants and Emerging Players: Enter via the household pouch segment in the United Kingdom and United States where post-pandemic home baking persistence sustains premium pricing and lower certification barriers. Direct-to-consumer subscription models offer the most penetrable go-to-market angle, bypassing supermarket slotting fees. For Investors and Strategic Acquirers: CSRD disclosure mandate acceleration is the leading indicator that carbon-accounting-enabled premix suppliers will command sustained valuation premiums. Acquisition targets should center on regional fermentation technology specialists with verified supply chain data capabilities. Watch for EU Green Deal farm-to-fork procurement preference shifts as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheat Origination | ADM's pipeline control demonstrates how captive grain supply secures margin capture from farm to finished premix. |
| Enzyme Platform Licensing | Puratos fermentation technology leadership enables cleaner-label positioning that meets EFSA health claims frameworks. |
| Direct-to-Restaurant Distribution | Specialty blenders in London and Paris bypass broadline distributors to capture technical support premiums. |
| Carbon Accounting Certification | CSRD-compliant suppliers with Scope 3 documentation win consolidated procurement from Munich baking clusters. |
| Gluten-Free Formulation Partnership | Collaboration with hydrocolloid innovators addresses texture consistency constraints limiting high-volume adoption. |
Research Methodology
Trade flow databases, EFSA novel food registers, and SEC filings from integrated grain processors formed the secondary backbone of this analysis. Primary interviews with bakery procurement directors, fermentation technology R&D leads, and foodservice distribution channel partners validated demand assumptions. Bottom-up and top-down triangulation reconciled volume estimates across product type, end user, and packaging format segmentation.
Bottom-up modeling anchored projections by building from individual country consumption patterns and facility-level capacity announcements. Segmentation dimensions included flour type, end-use application, distribution channel, and regional regulatory cluster. CAGRs were synthesized from trajectory fitting across the projection horizon, with enzyme approval timelines and wheat price volatility cycles incorporated as industry-specific forecast inputs.
Revisions become necessary when Black Sea supply disruptions intensify, EU F-Gas Regulation enforcement accelerates, or novel enzyme approval pathways extend unexpectedly. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Dough Conveyor Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Bread Premix Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Bread Crumbs Market
Bakery Products
Bakers Yeast Market
Bakery Products
Cookies Market
Bakery Products
Waffle Market
Bakery Products
Pastry Dough Market
Bakery Products
Europe Bakery Products Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Teaseed Cake Market
Bakery Products
Pancakes Market
Bakery Products
Cake Concentrate Market