
 Electronic Chemicals Market | 2026-2036
Electronic Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Chemicals Market Intelligence
The reliance on project finance for constructing ultra-high purity chemical plants is narrowing the field of viable competitors. Large incumbents like BASF SE leverage their vast balance sheets to fund next-generation facilities for semiconductor clients. Meanwhile, specialty gas suppliers such as Linde plc sustain their market position through long-term supply contracts tied to new fab construction. Dow Inc. differentiates through its integrated production and extensive R&D in polymer science for electronics.
Electronic chemicals encompass a range of high-purity substances used in manufacturing electronic components. These materials must meet stringent purity specifications, often measured in parts per billion, to prevent defects in microfabrication processes. Within the product landscape, advanced photoresists and specialty etchants for semiconductor fabrication represent the highest margin segments. In contrast, solvents and cleaners used for printed circuit boards and flat panel displays constitute a more mature, volume-driven category.
Regulatory frameworks significantly influence product formulation and market access. In Europe, the ECHA's REACH regulation governs specific chemical substances, while the EPA in the United States sets emissions standards. These environmental mandates force continuous reformulation, impacting R&D priorities. Key stakeholders must therefore balance investments in next-generation material science with the escalating cost of global regulatory compliance.
Market Dynamics
The central structural force shaping the market is the relentless miniaturization in semiconductor manufacturing. This requires a step-change in chemical purity and performance, concentrating market power with suppliers capable of funding and operating ultra-high purity production facilities.
Growth Catalysts
- Extreme Ultraviolet Lithography:The adoption of EUV lithography in sub-7nm semiconductor nodes necessitates entirely new classes of photoresists and ancillary chemicals, creating a high-value demand segment.
- Semiconductor Fab Onshoring:National initiatives, such as the US CHIPS Act, are stimulating new fab construction, which directly translates to localized, long-term demand for a full suite of electronic chemicals.
- Advanced Packaging Demand:The proliferation of chiplets and 3D-stacked ICs for data centers and AI hardware requires novel dielectric materials, underfills, and high-purity cleaning solutions.
Market Restraints
- Intense Capital Requirements:Building plants capable of producing chemicals with parts-per-trillion purity demands massive capital investment, creating a high barrier to entry for new competitors.
- Stringent Regulatory Hurdles:Compliance with multifaceted regulations like Europe's REACH and US EPA standards for chemical safety and emissions adds significant, ongoing operational costs and R&D complexity.
- Raw Material Concentration:The supply of certain high-purity precursors is concentrated in a few specialized producers, exposing the entire value chain to potential disruptions and price volatility.
Strategic Opportunities
- Green Chemistry Formulations:Developing biodegradable solvents or recyclable etchants provides a strong differentiator, appealing to electronics manufacturers with aggressive corporate sustainability goals.
- Emerging Semiconductor Ecosystems:Establishing production and supply infrastructure in nascent semiconductor manufacturing regions, such as India under its PLI scheme, offers first-mover advantages.
- Materials for Flexible Electronics:Formulating conductive inks, substrates, and encapsulants for the expanding flexible display and wearable device markets opens a distinct application-specific revenue stream.
Industry Challenges
- Specialized Talent Scarcity:A critical shortage of material scientists and process engineers with expertise in sub-nanometer purity control and advanced lithographic chemistry constrains innovation and expansion.
- Intellectual Property Protection:Defending proprietary chemical formulations for high-margin products like advanced photoresists from infringement is a constant and costly legal challenge across jurisdictions.
- Lengthy Customer Qualification:Any new chemical or formulation change requires an extensive and time-consuming qualification process with semiconductor fabs, delaying revenue generation from new products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Chemicals Market |
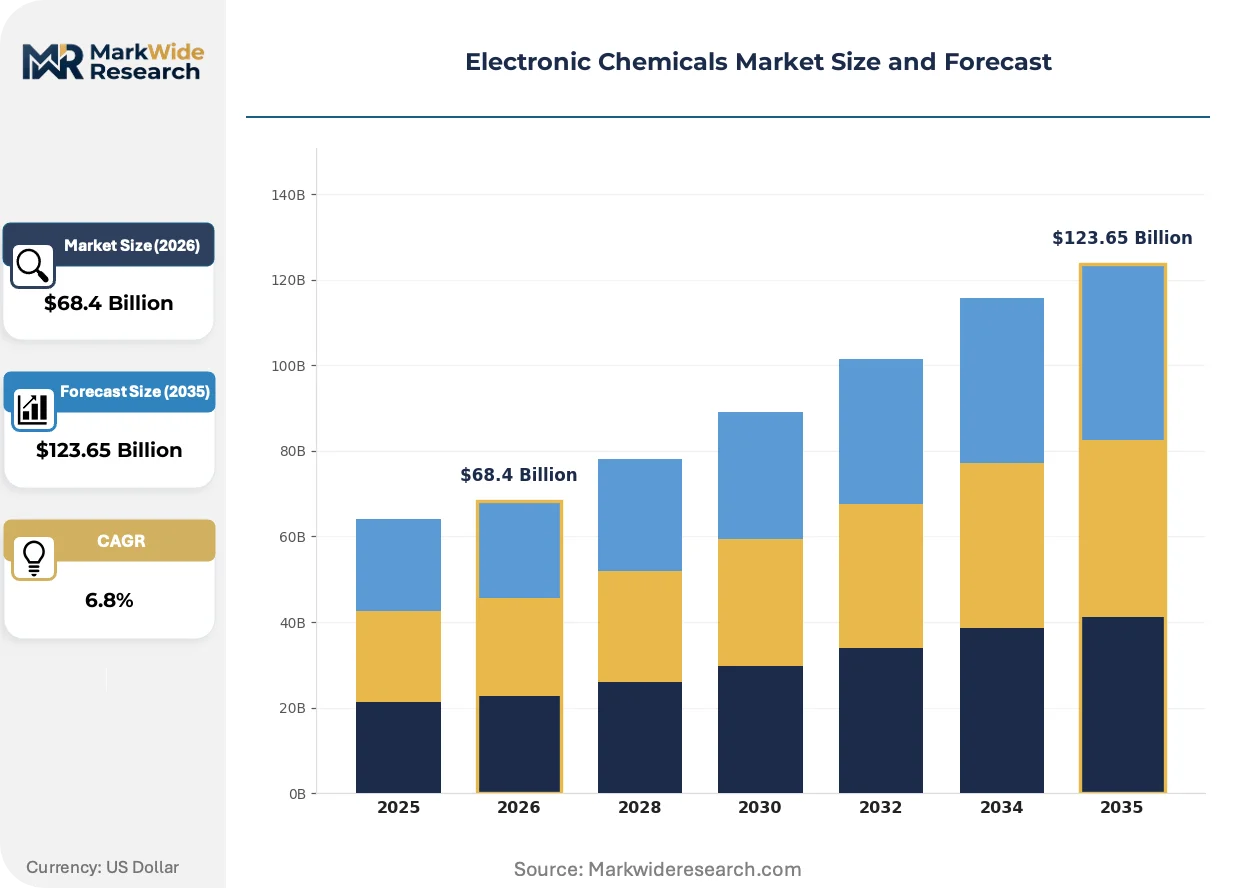
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photoresists, Etchants, Cleaners, Solvents, Developers, Dopants Technology: Chemical Vapor Deposition, Atomic Layer Deposition, Spin Coating, Plasma Etching, Wet Etching, Sputtering Application: Semiconductor Fabrication, Printed Circuit Boards, Flat Panel Displays, Solar Cells, MEMS Fabrication, Nanotechnology End User: Semiconductor Manufacturers, PCB Producers, Display Manufacturers, Photovoltaic Companies, MEMS Developers, Research Institutions |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., BASF SE, Linde plc, Merck KGaA, Air Liquide, Dow Inc., Fujifilm Corporation, Resonac Holding Corporation, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Chemicals Market Strategic Shifts & Innovations
Intensifying pressures for both higher performance and improved sustainability are driving a dual-track innovation path. Material science advancements focus on enabling next-generation chip architecture, while process chemistry is being redesigned to minimize environmental impact and meet stricter global regulations.
Material Informatics Platforms
Material informatics platforms utilize artificial intelligence and quantum chemistry simulations to model new molecules for specific electronic applications. Semiconductor material suppliers are adopting these tools to accelerate the discovery of compounds for advanced nodes. This approach is virtualizing the initial, resource-intensive stages of R&D for novel photoresists and etchants, compressing development cycles.
PFAS Regulation and Reformulation
The European Union's Green Deal is driving stricter regulations on per- and polyfluoroalkyl substances (PFAS), often called "forever chemicals." This action compels chemical producers to invest heavily in finding and qualifying alternative substances for use in etchants, coolants, and coatings. The semiconductor and display sectors are most affected, prioritizing R&D on PFAS-free formulations to ensure continued market access.
On-Site Chemical Management
Semiconductor manufacturers are shifting from transactional purchasing to demanding integrated, on-site chemical management services for new fabrication plants. This model involves long-term contracts where the chemical supplier builds and operates dedicated high-purity generation and recycling plants directly at the fab location. This trend is most visible in new semiconductor clusters in the United States and Taiwan, prioritizing supply resilience.
Electronic Chemicals Market Segmentation
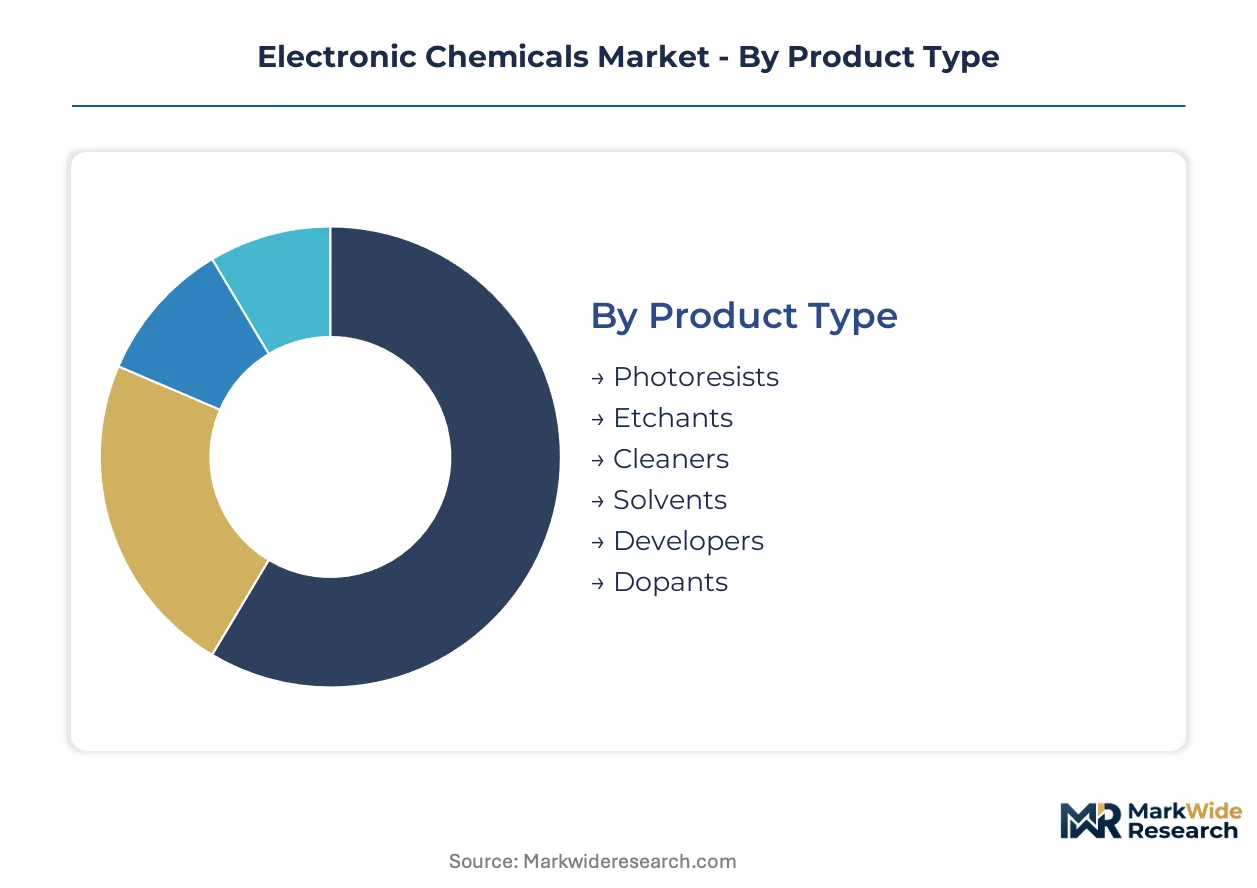
The electronic chemicals market segments reflect diverse purity requirements, processing methodologies, and end-use applications. Understanding these distinctions is critical for suppliers to tailor product portfolios, optimize supply chains, and navigate complex regulatory landscapes for specialized materials.
Product Type:
The after-sales service intensity for electronic chemicals varies significantly by product type, reflecting the criticality and technical support required for specific formulations in microfabrication processes.
- Photoresists:These light-sensitive polymers enable pattern transfer onto semiconductor wafers during lithography, demanding ultra-high purity and precise spectral response for sub-7nm node manufacturing in Taiwan and South Korea.
- Etchants:Specialty etchants selectively remove material from semiconductor substrates, requiring precise chemical composition and delivery systems for advanced manufacturing hubs in the United States and Japan.
- Cleaners:High-purity cleaning solutions remove contaminants from wafers and components, ensuring defect-free surfaces in various stages of electronic manufacturing.
- Solvents:Solvents dissolve and dilute chemical formulations, used for processes like photoresist application and equipment cleaning across the industry.
- Developers:Developers selectively remove exposed or unexposed photoresist layers after lithography, a critical step in pattern transfer.
- Dopants:Dopants introduce impurities into semiconductor materials to alter their electrical conductivity, essential for creating functional devices.
By volume, solvents lead. By growth pace, photoresists are ahead.
Technology:
Application specificity dictates the selection of processing technologies, with each method requiring distinct chemical precursors and precise control for material deposition or removal in semiconductor fabs.
- Chemical Vapor Deposition:CVD processes deposit thin films of material onto substrates through chemical reactions of gaseous precursors, crucial for creating dielectric and conductive layers in advanced integrated circuits.
- Atomic Layer Deposition:ALD offers ultra-thin, conformal film deposition with atomic-scale precision, essential for next-generation memory and logic devices requiring stringent material control.
- Spin Coating:Spin coating applies liquid films, such as photoresists, uniformly onto flat substrates by centrifugal force, a standard process in lithography.
- Plasma Etching:Plasma etching uses reactive gases and plasma to remove material from a wafer surface, offering anisotropic etching for fine patterns.
- Wet Etching:Wet etching employs liquid chemicals to remove material from substrates, often used for bulk material removal or surface preparation.
- Sputtering:Sputtering physically deposits thin films by bombarding a target material with energetic ions, releasing atoms that condense on the substrate.
The integration of Chemical Vapor Deposition with Atomic Layer Deposition is critical for advanced manufacturing.
Application:
The margin profiles of electronic chemicals vary significantly across applications, driven by the technical complexity, purity demands, and value added to the final electronic component.
- Semiconductor Fabrication:This segment consumes the most advanced and highest-purity chemicals, including photoresists, etchants, and specialty gases, for manufacturing integrated circuits.
- Flat Panel Displays:FPD manufacturing requires specialized chemicals for processes like thin-film transistor array formation and color filter deposition, supporting consumer electronics.
- Printed Circuit Boards:PCB production utilizes chemicals for etching copper traces, plating, and cleaning, forming the foundation for electronic assemblies.
- Solar Cells:Photovoltaic manufacturing employs chemicals for silicon wafer processing, doping, and surface passivation.
- MEMS Fabrication:Micro-electromechanical systems require specific chemicals for etching and deposition in creating tiny mechanical devices.
- Nanotechnology:This application involves chemicals for synthesizing and processing nanomaterials for various emerging electronic devices.
Demand for semiconductor fabrication chemicals drives the largest revenue pools, while nanotechnology chemicals exhibit significant expansion.
End User:
Supply concentration among end users impacts procurement strategies for specialized electronic chemicals, particularly for those requiring large volumes or unique specifications.
- Semiconductor Manufacturers:These companies are the primary consumers of ultra-high purity electronic chemicals for producing microchips, driving innovation in material science.
- Display Manufacturers:Producers of LCD, OLED, and other display technologies rely on specialized chemicals for screen fabrication processes.
- PCB Producers:Manufacturers of printed circuit boards use a range of chemicals for etching, plating, and cleaning in their production lines.
- Photovoltaic Companies:Solar cell manufacturers consume chemicals for processing silicon and other materials used in energy conversion.
- MEMS Developers:Companies developing micro-electromechanical systems require specific chemical formulations for their miniature devices.
- Research Institutions:Academic and corporate research bodies utilize electronic chemicals for material science studies and new process development.
Consolidation among semiconductor manufacturers impacts procurement strategies for specialized chemicals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global electronic chemicals market exhibits a complex trade dynamic, with certain regions acting as net exporters of specialized materials while others heavily import high-purity precursors. This balance influences local production investments and supply chain resilience for advanced semiconductor manufacturing. The intense demand for next-generation components drives localized chemical production capabilities.
United States
The United States experiences significant demand for electronic chemicals due to semiconductor fab onshoring and advanced packaging. The US CHIPS Act stimulates new fab construction, bolstering localized chemical requirements. Arizona's expanding semiconductor cluster drives dedicated on-site chemical management services.
South Korea
South Korea drives substantial demand for photoresists and etchants, fueled by its dominant memory and logic chip fabrication. Stringent national quality standards guide chemical development and application. Gyeonggi Province, home to major semiconductor producers, concentrates high-purity chemical supply infrastructure.
Taiwan
Taiwan's advanced foundry operations and rapid EUV lithography adoption create intense demand for next-generation electronic chemicals. Taiwan's industrial development programs prioritize domestic material supply chain resilience. The Hsinchu Science Park remains a global hub, attracting investment in specialized chemical production.
Japan
Japan maintains a strong global presence in specialty electronic chemicals, leveraging its expertise in ultra-high purity material science. The METI actively supports domestic chemical innovation and strategic material production. Kumamoto Prefecture is emerging as a new semiconductor cluster, drawing investments in local chemical supply chains.
China
China's expanding domestic semiconductor manufacturing capacity and robust display panel production drive significant demand for electronic chemicals. The MIIT promotes self-sufficiency in critical materials through various industrial policies. The Yangtze River Delta region, with its numerous fabs, is a key consumption area.
Electronic Chemicals Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the electronic chemicals market. The industry structure leans towards consolidation at the ultra-high purity end, where massive capital investments and extensive R&D are required. Strategic archetypes include globally diversified chemical giants, specialized industrial gas suppliers, and niche material science innovators focusing on specific lithography applications. These players primarily engage in continuous capacity expansion and forge long-term strategic partnerships to secure market share and accelerate product qualification.
Among globally diversified chemical suppliers, BASF SE exemplifies large incumbents leveraging vast balance sheets for next-generation facilities and extensive R&D. Linde plc, a specialty gas supplier, sustains its market position through long-term supply contracts tied to new fab construction and on-site chemical management services. Dow Inc., a US-based chemical company, occupies a distinct position through its integrated production and extensive R&D in polymer science for electronics, catering to advanced packaging needs. These entities represent the deep-pocketed players capable of meeting stringent purity requirements and funding continuous innovation across diverse electronic applications.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| BASF SE |
| Linde plc |
| Merck KGaA |
| Air Liquide |
| Dow Inc. |
| Fujifilm Corporation |
| Resonac Holding Corporation |
| DuPont de Nemours, Inc. |
| Others |
Cost & Logistics Intelligence
Hsinchu Science Park's specialized production capacity for ultra-high purity chemicals directly influences pricing power for advanced electronic chemicals. The concentration of leading foundries in this region creates unique supply-demand dynamics.
Pricing Analysis
Semiconductor manufacturers anchor long-term contract pricing for electronic chemicals. Price differentiation primarily stems from ultra-high purity grades and extensive on-site after-sales service and technical support. Pricing pressure intensifies due to semiconductor fabs' continuous drive for cost efficiencies in high-volume production. Consequently, printed circuit board producers exhibit higher price sensitivity compared to advanced semiconductor manufacturers.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are critical for funding the massive capital outlays required for new production. Geographic supply concentration for critical precursors centers on Japan, South Korea, and the United States. Dependence on a few specialized producers for high-purity raw materials, such as specific polymers and rare earth elements, creates single-source vulnerability. Distribution runs through direct supplier-to-fab agreements, often including integrated on-site chemical management services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electronic chemicals market presents a defensive moat for established players, primarily due to the high switching costs associated with qualifying new materials within semiconductor fabrication. This creates significant barriers to entry for potential competitors.
For Market Incumbents:Build a regulatory compliance moat by proactively investing in green chemistry formulations and PFAS-free alternatives, addressing the EU Green Deal's mandates. Expand ultra-high purity production capacity in strategic regions like the United States and Taiwan to align with fab onshoring initiatives. This defends against emerging entrants offering sustainable alternatives and leverages vertical integration for cost control.
For New Entrants and Emerging Players:Establish a beachhead in advanced packaging materials and flexible electronics, targeting emerging applications such as chiplets and wearable devices. The nanotechnology chemicals segment offers a penetrable entry point due to its rapid innovation cycle. A successful go-to-market angle involves leveraging material informatics platforms to accelerate new compound discovery and secure early-stage intellectual property.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized material science innovators with deep intellectual property in sub-7nm lithography and advanced packaging. Long-term viability centers on enabling next-generation semiconductor architectures. Acquisition targets are niche firms with proven capabilities in novel photoresist or etchant chemistries. The signal to watch is the accelerated qualification of new PFAS-free formulations by leading foundries.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding production in Taiwan supports localized demand from advanced foundry operations. |
| Green Manufacturing Transition | Developing biodegradable solvents aligns with the EU Green Deal and corporate sustainability goals. |
| Long-term Supply Agreement | Securing multi-year contracts with US CHIPS Act-funded fabs ensures stable demand. |
| Acquisition of Specialist Firm | Acquiring a niche innovator strengthens intellectual property in EUV lithography photoresists. |
| Joint Venture | Partnering with a local entity in India establishes first-mover advantage under its PLI scheme. |
Research Approach
A standing panel of R&D directors, procurement leads, and process engineers across semiconductor fabs provided ongoing calibration for market dynamics. This primary research, combined with extensive secondary validation from SEC filings, industry trade association reports, and academic journals, informed the analysis. Bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation.
Scenario-bracketing framed growth trajectories across the analysis window, incorporating optimistic and conservative assumptions. The analytical framework modeled key segmentation dimensions: product type, technology, application, end-user, and purity grade. Compound annual growth rates were derived from historical trends. Key inputs included global semiconductor fab capacity expansions and EUV lithography adoption rates.
Sensitivities concentrate around shifts in global trade policy and new fab construction pace. Forecasts reflect assumptions concerning the current regulatory environment. Geopolitical tensions or raw material supply disruptions could prompt revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Chemicals
Printed Electronic Materials Market
Electronic Chemicals
Electronic Wet Chemicals Market
Electronic Chemicals
Global Electronic Materials and Chemicals Market
Electronic Chemicals
Silver Paste Market
Electronic Chemicals
Global Imaging Chemicals Market
Electronic Chemicals
Global Circuit Materials Market
Electronic Chemicals
Liquid Soldering Flux Market
Electronic Chemicals
Global 5G EMI Materials Market