
 CMIT/MIT Market | 2026-2036
CMIT/MIT Market Size, Share, and Industry Trends Forecast 2026-2036
CMIT/MIT Market Analytics
REACH is recalibrating the cost-of-entry calculus for European CMIT/MIT suppliers by demanding exhaustive substance dossiers and restricting certain isothiazolinone concentrations in consumer products. Lonza Water Treatment leverages its integrated manufacturing footprint to sustain compliance advantage across regulated jurisdictions. Dow anchors its position through backward integration into chlorinated intermediate supply. Clariant differentiates via specialized formulations for high-pH industrial water systems.
CMIT/MIT denotes chloromethylisothiazolinone and methylisothiazolinone, a synergistic biocide pair typically blended at ratios of 3:1 to 4:1 and manufactured through controlled cyclization of N,N'-dimethyldithiodipropionamide with sulfuryl chloride, serving primarily to inhibit microbial growth in aqueous industrial and consumer formulations. The Paints & Coatings application segment dominates volume consumption due to in-can preservation requirements across architectural and industrial formulations, while Personal Care demand is fragmenting as MIT concentration limits tighten across formulations. Preservatives targeting the Cosmetic Industry end user channel command premium positioning where regulatory certification and dermatological safety documentation create margin pools.
The EPA regulates CMIT/MIT under the Federal Insecticide, Fungicide, and Rodenticide Act, requiring registration renewal and efficacy substantiation that shapes product lifecycle planning for US-market suppliers. ECHA's Biocidal Products Committee reviews drive active substance inclusion decisions that determine which formulations retain market access across Europe. China's MEE enforces discharge standards that expand industrial water treatment biocide consumption. Stakeholders must monitor regulatory divergence between jurisdictions to determine where formulation registration investments yield durable commercial positions.
Market Dynamics
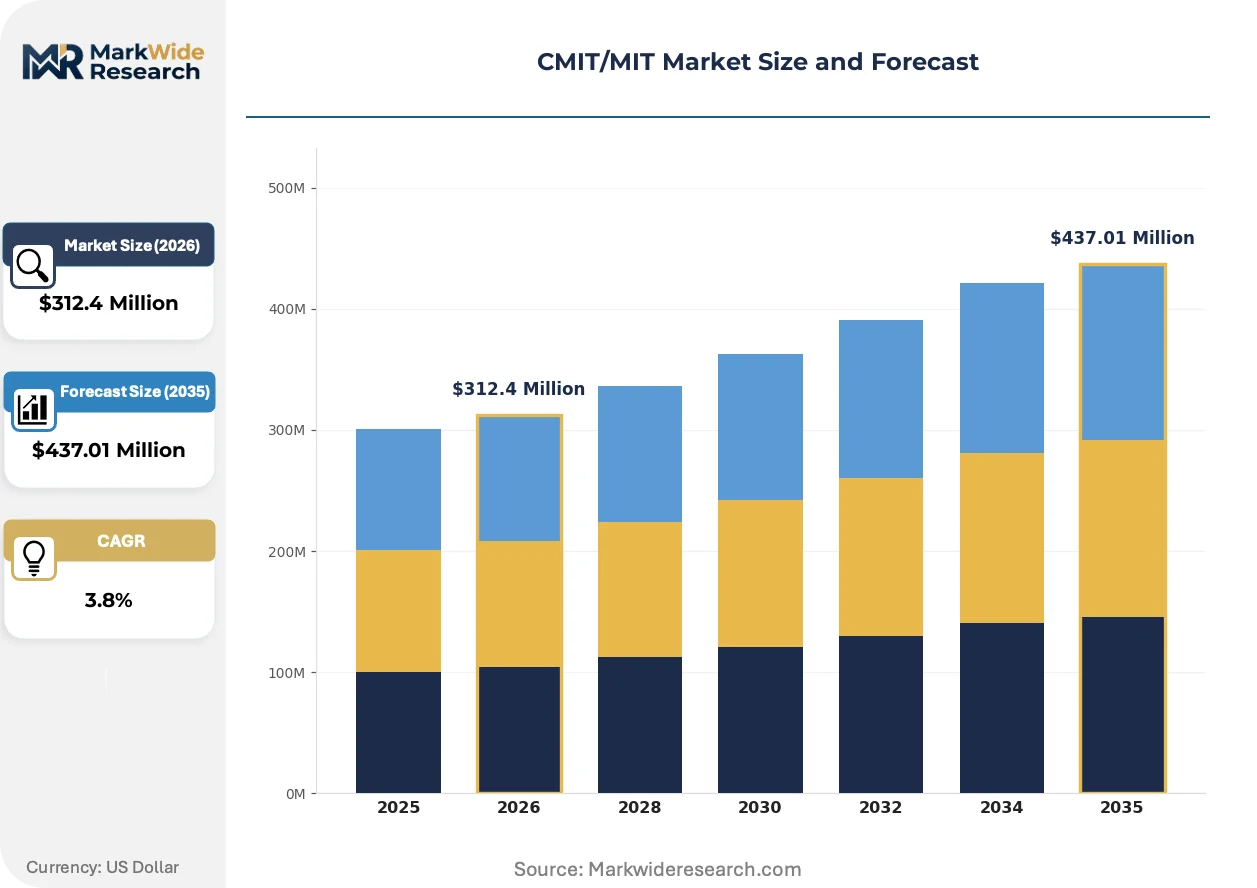
The CMIT/MIT market is experiencing intensifying regulatory bifurcation as REACH restricts isothiazolinone concentrations in consumer products while industrial water treatment demand accelerates in Asia-Pacific manufacturing corridors.
Growth Catalysts
- Industrial Cooling Water Expansion:Power generation and petrochemical facilities in China are scaling closed-loop cooling systems that require continuous microbial control, expanding biocide consumption volumes.
- REACH Compliance Differentiation:European suppliers investing in exhaustive substance dossiers are capturing premium positioning in regulated jurisdictions where competitor products face delisting.
- Construction Chemicals Preservation:Cement admixtures and construction additives in high-humidity climates require robust in-can preservation, extending CMIT/MIT application beyond traditional coatings.
Market Restraints
- Chlorinated Intermediate Volatility:Sulfuryl chloride and propionamide derivative costs fluctuate with chlor-alkali capacity constraints, compressing formulation margins unpredictably.
- Personal Care Substitution:Phenoxyethanol and organic acid blends are displacing MIT in rinse-off cosmetics as dermatological sensitivity concerns mount among formulators.
- Approval Timeline Friction:ECHA's Biocidal Products Committee review cycles extending 18-24 months are freezing new active substance entries and entrenching incumbent positions.
Strategic Opportunities
- Middle East Industrial Water:Desalination-intensive economies in Saudi Arabia and UAE are expanding thermal power capacity with demanding biofouling control requirements.
- High-pH Formulation Gaps:Specialized alkaline-stable CMIT/MIT variants for paper mill and metalworking fluids represent underserved specification zones.
- MEE Discharge Enforcement:China's Ministry of Ecology and Environment is tightening industrial effluent standards, mandating biocide treatment in previously unregulated cooling tower blowdown.
Industry Challenges
- Toxicological Data Generation:Extended one-generation reproductive toxicity studies and skin sensitization protocols are extending registration timelines and consuming R&D budgets.
- Legacy System Integration:Paper mills and textile dye houses with manual dosing infrastructure face retrofit costs when transitioning to automated CMIT/MIT feed systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CMIT/MIT Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CMIT, MIT, Biocides, Preservatives Application: Paints & Coatings, Personal Care, Pharmaceuticals, Wood Preservation End User: Healthcare, Cosmetic Industry, Construction, Food & Beverage Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesale |
| Companies Covered | Xingyuan Chemistry, Tonix Chemical, Nantong Uniphos Chemicals, SKCN Chemicals, Lonza Water Treatment, Dow, Bio-Chem, Clariant, Lanxess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CMIT/MIT Market Evolving Landscape
Formulation science is pivoting toward synergistic stabilization and regulatory pre-certification as competitive differentiators, with technology investments concentrating on performance validation and geographic compliance portability.
Encapsulated slow-release CMIT/MIT delivery systems are unifying sustained antimicrobial efficacy with reduced handling hazards for remote industrial sites. Mining operations and offshore platforms are adopting these formats to minimize personnel exposure during bulk chemical transfers. The technology is unifying logistics efficiency with safety compliance in regions with stringent occupational exposure limits.
REACH's restriction of MIT in leave-on cosmetic products is forcing reformulation investments across European personal care supply chains. Manufacturers are pivoting toward alternative preservative systems or concentration-adjusted rinse-off formats to retain shelf presence. The coatings sector faces parallel scrutiny as ECHA evaluates additional isothiazolinone hazard classifications affecting architectural paint preservation.
Specification-driven procurement is consolidating buyer power among multinational water treatment service providers seeking single-source biocide suppliers with multi-jurisdictional registration portfolios. Regional distributors with fragmented technical support capabilities are losing share to integrated service contracts bundling chemical supply, monitoring equipment, and compliance documentation. This pattern is most pronounced in German and Dutch industrial water treatment markets where bundled service models dominate.
CMIT/MIT Market Segmentation
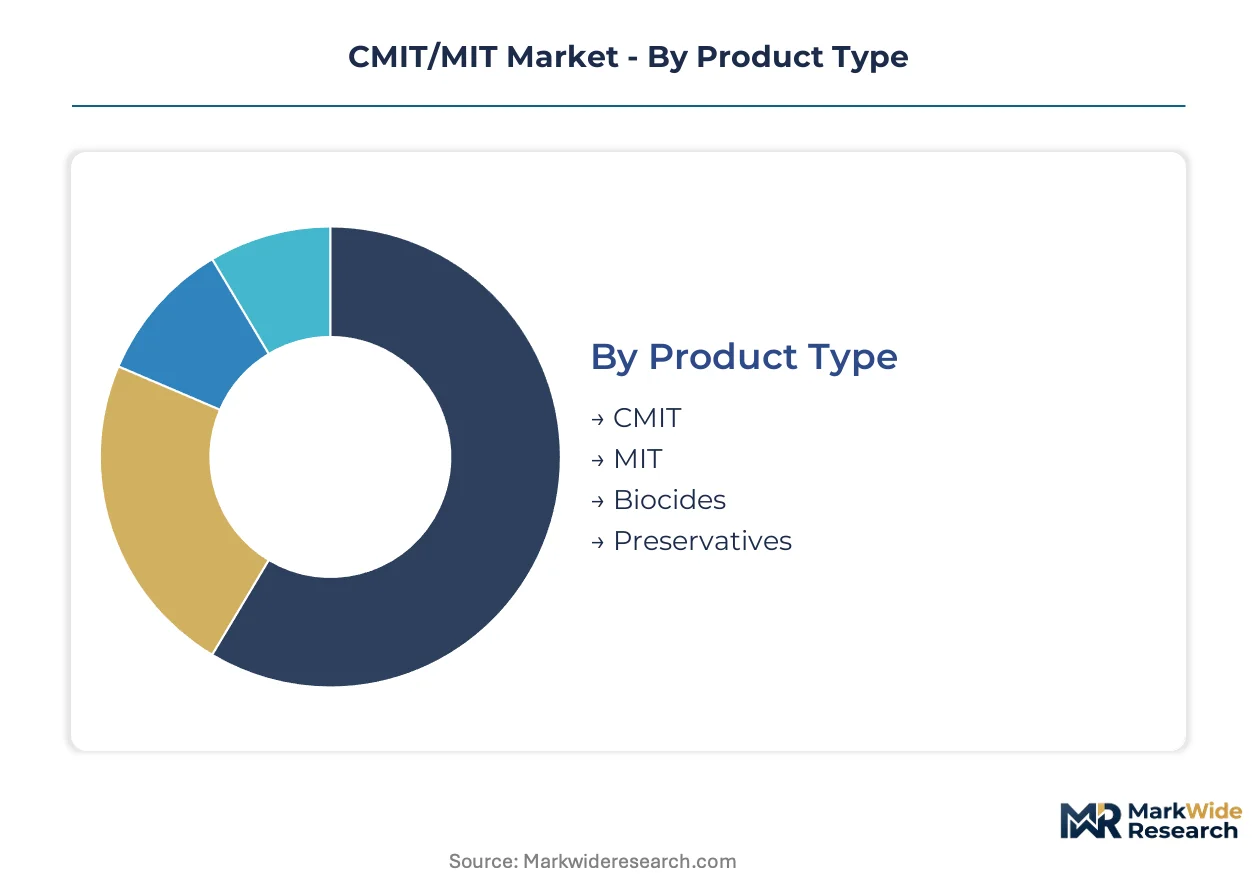
CMIT/MIT market segmentation reflects divergent technical specifications across industrial and consumer applications. Regulatory thresholds vary sharply by end-use channel, forcing suppliers to maintain parallel formulation portfolios. Understanding these segment boundaries enables targeted registration investments and pricing architecture.
Product Type:
Upgrade cycles in water treatment infrastructure are driving specification shifts toward higher-purity grades and stabilized blends that extend dosing intervals in cooling systems.
- CMIT:Chloromethylisothiazolinone delivers rapid microbial kill kinetics at low concentrations, making it indispensable for industrial cooling towers in China's power generation corridor where biofouling control is non-negotiable. Demand concentrates in heavy manufacturing zones with continuous process water requirements; MEE discharge enforcement is expanding treatment volumes in previously unregulated facilities.
- MIT:Methylisothiazolinone serves as the standalone preservative in rinse-off cosmetics and personal care where concentration limits are tightening under REACH. Formulators in European markets are pivoting toward concentration-adjusted formats or alternative systems to retain shelf presence amid dermatological sensitivity concerns.
- Biocides:Broad-spectrum antimicrobial formulations incorporating CMIT/MIT synergies target industrial water systems requiring continuous microbial suppression.
- Preservatives:In-can preservation systems for aqueous formulations span architectural coatings, adhesives, and polymer emulsions.
Volume placements concentrate in CMIT for industrial water treatment; the faster expansion belongs to biocide blends as multi-jurisdictional registration portfolios become procurement prerequisites.
Application:
Cost tier differentiation separates commodity preservation from premium-certified formulations commanding documentation premiums.
- Paints & Coatings:In-can preservation requirements across architectural and industrial formulations make this the dominant volume channel. ECHA's ongoing evaluation of additional isothiazolinone hazard classifications is forcing reformulation investments among European architectural paint suppliers.
- Personal Care:Rinse-off cosmetics represent the remaining viable MIT application as leave-on restrictions tighten. Phenoxyethanol and organic acid blends are displacing MIT in sensitive formulations.
- Pharmaceuticals:Sterile manufacturing water systems and ophthalmic preparations require validated biocide protocols with exhaustive toxicological documentation.
- Wood Preservation:Pressure-treatment applications in high-humidity climates demand robust fungal and bacterial control in aqueous carrier systems.
Application margins stratify across pharmaceutical certification requirements, standard industrial specifications, and commodity coating preservation tiers.
End User:
Customer type determines procurement modality, with multinational service providers consolidating supplier relationships around bundled compliance documentation.
- Healthcare:Hospital water systems and pharmaceutical manufacturing require validated biocide protocols with ISO-compliant efficacy substantiation.
- Cosmetic Industry:Preservative procurement commands premium positioning where dermatological safety documentation and REACH certification create margin pools.
- Construction:Cement admixtures and construction additives in high-humidity climates require robust in-can preservation extending beyond traditional coatings.
- Food & Beverage:Process water treatment applications face stringent residue limits and migration testing requirements.
End-user procurement concentrates among cosmetic and healthcare channels demanding certification depth; construction applications are gaining share fastest as emerging market infrastructure investment accelerates.
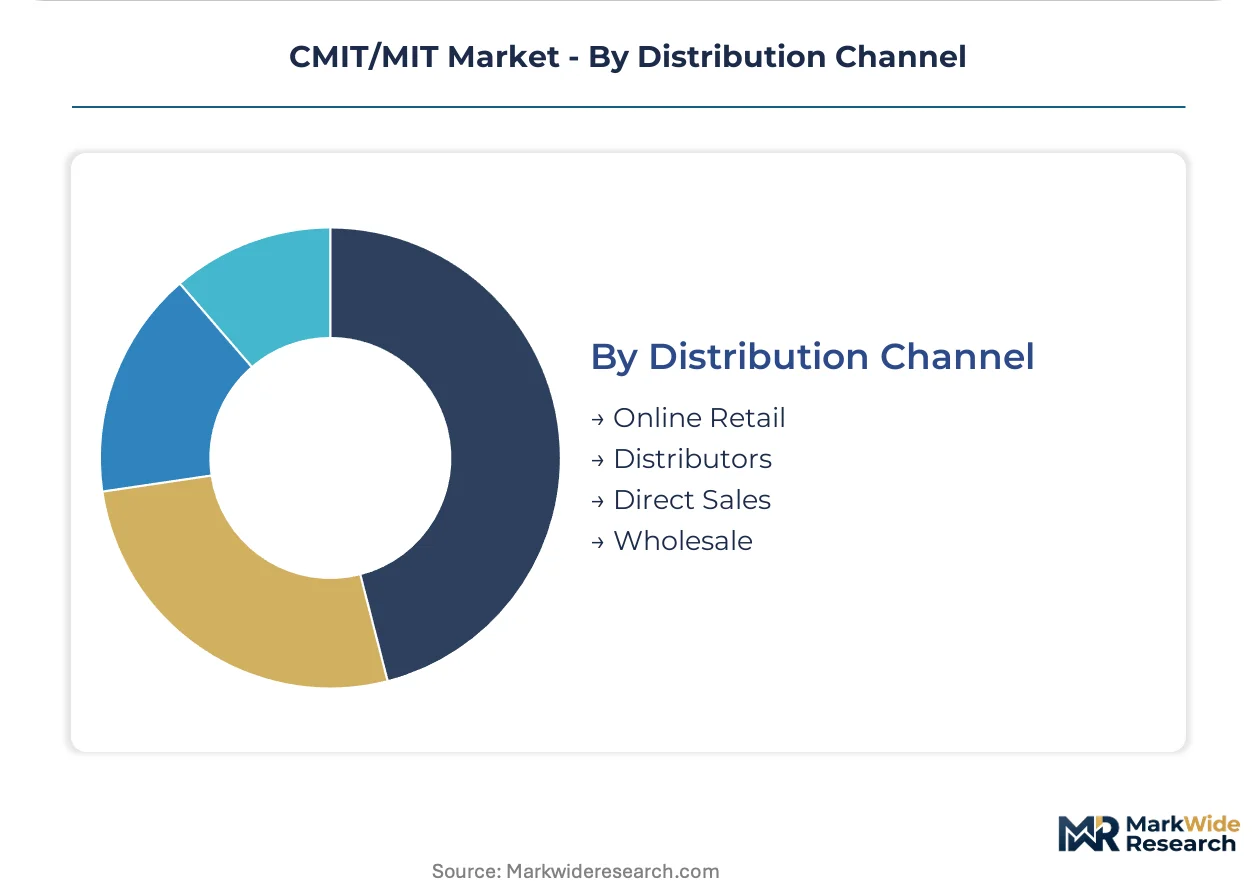
Distribution Channel:
Supply concentration favors integrated service contracts over fragmented distributor networks in regulated jurisdictions.
- Online Retail:Small-volume preservative sales to independent formulators and regional compounders, particularly in personal care ingredient sourcing.
- Distributors:Regional chemical distributors with technical support capabilities serve mid-scale industrial water treatment operators.
- Direct Sales:Multinational water treatment service providers source through single-source contracts bundling chemical supply, monitoring equipment, and compliance documentation.
- Wholesale:Bulk biocide procurement by large-scale manufacturing facilities with established storage and handling infrastructure.
Channel volume concentrates in direct sales to integrated service providers; wholesale expansion is climbing fastest as industrial water treatment scales in Asia-Pacific manufacturing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates CMIT/MIT consumption through its dominant chemical manufacturing base and expanding industrial water treatment infrastructure. Regulatory divergence across jurisdictions is fragmenting formulation standards and redirecting supplier investment toward multi-jurisdictional registration portfolios.
China
Power generation and petrochemical facilities in Jiangsu and Shandong provinces are scaling closed-loop cooling systems that require continuous microbial control. The Ministry of Ecology and Environment enforces discharge standards that expand biocide treatment volumes in previously unregulated cooling tower blowdown. Manufacturing clusters in the Yangtze River Delta are integrating automated CMIT/MIT feed systems to meet tightening effluent requirements.
Germany
Industrial water treatment service providers in the Rhine-Ruhr corridor are consolidating supplier relationships around bundled compliance documentation. ECHA's Biocidal Products Committee review cycles are freezing new active substance entries and entrenching incumbent positions. Chemical formulators in North Rhine-Westphalia are investing in exhaustive substance dossiers to sustain market access under REACH concentration restrictions.
United States
Petrochemical facilities along the Gulf Coast are expanding cooling water treatment capacity to support downstream chemical production. The EPA regulates CMIT/MIT under FIFRA, requiring registration renewal and efficacy substantiation that shapes product lifecycle planning. Industrial water treatment operators in Texas and Louisiana are adopting encapsulated slow-release delivery systems for remote site safety compliance.
Saudi Arabia
Desalination-intensive economies are expanding thermal power capacity with demanding biofouling control requirements in concentrated cooling systems. The national water regulator enforces treatment standards that mandate biocide protocols in industrial effluent discharge. New industrial cities in the Eastern Province are specifying high-pH stable CMIT/MIT variants for alkaline process water conditions.
India
Textile dye houses in Gujarat and Tamil Nadu are retrofitting manual dosing infrastructure to transition toward automated biocide feed systems. The Central Pollution Control Board is tightening effluent discharge parameters for chemical processing industries. Manufacturing corridors in Maharashtra are importing registration-compliant formulations to meet multinational buyer certification requirements.
CMIT/MIT Market Competitive Landscape
Chinese producers anchor the volume tier through integrated manufacturing footprints serving domestic industrial water treatment expansion; European specialists hold premium positioning via REACH-compliant formulation portfolios and exhaustive toxicological documentation. The vendor base stratifies across three tiers: multinational integrated suppliers with multi-jurisdictional registrations, regional manufacturers with concentrated geographic focus, and specialty formulators targeting high-pH or encapsulated delivery niches. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers seek to pre-position for MEE enforcement waves and Middle East industrial water growth.
Within the integrated multinational tier, Lonza Water Treatment and Dow exemplify archetypes of backward-integrated suppliers with captive chlorinated intermediate supply and cross-regional registration depth. Clariant occupies a position among specialty formulators differentiating through alkaline-stable variants and high-pH industrial system expertise. Chinese manufacturers including Xingyuan Chemistry and Tonix Chemical represent the scale-driven domestic supply base serving Asia-Pacific manufacturing corridor expansion.
| Leading Market Players |
|---|
| Xingyuan Chemistry |
| Tonix Chemical |
| Nantong Uniphos Chemicals |
| SKCN Chemicals |
| Lonza Water Treatment |
| Dow |
| Bio-Chem |
| Clariant |
| Lanxess |
| Others |
Value Network & Pricing Analysis
Sulfuryl chloride spot pricing volatility cascades through CMIT/MIT manufacturing tiers, compressing margins at standard-grade producers while REACH-compliant European specialists capture premium spreads through certification-anchored contracts with multinational water treatment service providers.
Pricing Analysis
Volume placements concentrate in standard-grade biocide blends serving Chinese industrial cooling towers, while margin pools accrue to REACH-certified preservative grades for European cosmetic and pharmaceutical channels. Price differentiation separates ISO-compliant pharmaceutical grades from commodity industrial specifications, with geographic delivery costs widening spreads between Asia-Pacific manufacturing hubs and European formulation sites. Cost compression in standard-grade CMIT intensifies as Chinese producers expand captive chlor-alkali capacity. Small-scale personal care formulators exhibit highest price sensitivity, whereas healthcare procurement committees prioritize toxicological documentation over unit economics.
Supply Chain Analysis
China's domestic-content preferences under MEE enforcement protocols are redirecting sourcing toward Jiangsu and Shandong-based manufacturers with integrated chlorinated intermediate production. Supply concentration centers on China, Germany, and the United States for active substance manufacturing, with India emerging as a formulation blending hub. Raw material flows draw from chlor-alkali corridors for sulfuryl chloride, propionamide derivatives from specialty chemical producers, and stabilizer packages from polymer additive specialists. Single-source vulnerability in chlorinated intermediate supply creates exposure to energy-cost shocks. Distribution runs through direct-sales contracts bundling chemical supply with compliance documentation for multinational water treatment operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulated slow-release delivery systems are displacing conventional bulk biocide formats in remote industrial applications, forcing legacy suppliers to reformulate around occupational safety compliance and logistics efficiency.
For Market Incumbents: Lock in registration depth across ECHA, EPA, and MEE jurisdictions to entrench positions before Biocidal Products Committee review cycles freeze new active substance entries. Deepen backward integration into chlor-alkali feedstocks to insulate margins from sulfuryl chloride volatility. Prioritize automated dosing system partnerships with paper mills and textile dye houses facing retrofit mandates under tightening effluent standards. For New Entrants and Emerging Players: E-commerce ingredient platforms offer lower-friction entry for preservative sales to independent personal care formulators seeking REACH-compliant documentation without minimum order constraints. Target high-pH stable CMIT/MIT variants for Saudi Arabian thermal power and desalination infrastructure where alkaline process water conditions dominate. Pursue joint development agreements with construction chemical producers in high-humidity emerging markets requiring cement admixture preservation. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty formulators with encapsulated delivery technology and alkaline-stable product portfolios in European industrial water corridors. Long-term viability hinges on multi-jurisdictional registration portability as regulatory divergence intensifies between REACH, FIFRA, and MEE frameworks. Monitor ECHA hazard classification reviews as an inflection signal for architectural paint reformulation demand and incumbent product delisting risk.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Chinese producers scaling chlor-alkari integration capture MEE enforcement-driven demand in Yangtze River Delta manufacturing clusters. |
| Backward Integration | Captive sulfuryl chloride supply insulates Lonza and Dow from feedstock volatility compressing standard-grade competitor margins. |
| Green Manufacturing Transition | Encapsulated slow-release formats reduce occupational exposure incidents at Saudi Arabian and UAE remote industrial sites. |
| Long-term Supply Agreement | Bundled service contracts with German water treatment operators consolidate procurement around REACH-compliant documentation providers. |
| Joint Venture | Partnerships with Indian textile chemical distributors accelerate automated dosing system adoption in Gujarat dye house retrofits. |
Research Methodology
Document review covered customs trade data, SEC filings from listed chemical producers, ECHA biocidal product registration databases, and MEE discharge enforcement records, complemented by interviews with plant managers at Chinese power generation facilities, procurement leads at European water treatment service providers, technical R&D directors at specialty biocide formulators, and distribution channel partners in Middle East industrial chemical supply. Bottom-up demand modeling from end-use consumption patterns was triangulated against top-down supply-side capacity assessments.
Segment-level value and volume trajectories across the projection horizon reflect discrete modeling of product type splits, application grade tiers, end-user certification requirements, and distribution channel concentration patterns. CAGRs were derived from regression analysis against industrial water treatment capacity expansion, coatings production volumes, and cosmetic formulation output across regulatory jurisdictions. Forecast inputs incorporated chlor-alkali capacity utilization rates and REACH restriction timeline assumptions.
Inputs from ECHA registration databases and MEE enforcement bulletins were available through the study window; gaps in real-time Chinese industrial water treatment dosing system installation data introduce uncertainty bands around near-term volume assumptions. Forecasts reflect documented assumptions regarding regulatory review cycle durations and substitution elasticity in personal care preservative selection. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Hydroxy Ethyl Cellulose (HEC) Market
Specialty Chemicals
Global Chemical Vapor Deposition (CVD) Market
Specialty Chemicals
Avobenzone Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Freeze-Thaw Stabilizers Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
Bio-Ketones Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Acesulfame Potassium Market
Specialty Chemicals
Biocides Market
Specialty Chemicals
Global Photoacid Generators Market