
 Global Metal Chelates Market | 2026-2036
Global Metal Chelates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Chelates Market Foresight
ISO 9001 quality management certification is rotating as the baseline gatekeeper for supplier qualification across pharmaceutical and agricultural offtake contracts. BASF SE leverages its integrated ethylenediamine supply chain to control raw material costs for EDTA production. Yara International ASA anchors its position through backward integration into ammonia and nitric acid, securing captive feedstock for chelate manufacturing. Nouryon differentiates via specialized HEDTA grades tailored to high-pH soil conditions in Mediterranean agriculture.
Metal chelates are coordination complexes where a polydentate ligand binds to a central metal ion through multiple donor atoms, forming ring structures that enhance nutrient bioavailability and prevent precipitation in alkaline environments. These compounds primarily serve to deliver micronutrients such as iron, zinc, and manganese in forms resistant to soil fixation or oxidative degradation. EDTA dominates volume production due to its cost efficiency and broad metal compatibility, while EDDHA commands premium positioning in high-alkalinity applications where stability constants determine agronomic efficacy. Water treatment applications represent the fastest-expanding demand pool as utilities confront stricter effluent metal limits.
REACH registration requirements in Europe and EPA toxicity evaluations in the United States are elevating analytical documentation burdens for chelate manufacturers seeking multi-jurisdictional market access. India's BIS certification mandates and China's GB standards for agricultural inputs create additional compliance layers that favor producers with established regulatory affairs capabilities. Stakeholders must monitor biodegradability classification shifts under OECD testing protocols, as pending reclassifications could reshape acceptable ligand chemistries across fertilizer and pharmaceutical end uses.
Market Dynamics
REACH compliance deadlines in Europe are compressing formulation windows for chelating agent suppliers, forcing simultaneous purity upgrades across pharmaceutical and agricultural product lines while raw material costs for ethylenediamine derivatives fluctuate with ammonia feedstock volatility.
Growth Catalysts
- Soil Health Card Scheme:India's government-backed soil testing mandates are accelerating EDTA and EDDHA adoption among smallholder cooperatives seeking micronutrient correction protocols.
- Effluent Metal Limits:Water treatment utilities across Germany, Japan, and the United States are deploying chelating agents to meet tightening discharge standards for heavy metal capture.
- Biodegradable Ligand R&D:Polyaspartic acid and other non-persistent alternatives are gaining traction in European agriculture ahead of anticipated OECD reclassifications.
Market Restraints
- Ethylenediamine Supply Concentration:Production of this critical EDTA feedstock clusters with integrated petrochemical complexes in China and the US Gulf Coast, exposing buyers to regional supply disruptions.
- REACH Registration Burden:ECHA data requirements for new chelating agents demand extensive toxicological dossiers that smaller manufacturers cannot finance, consolidating supplier tiers.
- Mineral Fertilizer Substitution:Low-cost sulfate and oxide micronutrient formulations retain cost advantage in price-sensitive agricultural markets, limiting chelate penetration in developing regions.
Strategic Opportunities
- Brazilian Cerrado Expansion:Large-scale soybean and corn operations in Mato Grosso and Goiás are expanding precision agriculture programs with customized iron chelate fertigation systems.
- Biopharmaceutical Metal Removal:Monoclonal antibody manufacturers require ultra-high-purity EDTA grades for downstream processing, creating specification premiums above agricultural tiers.
- Direct-to-Cooperative Distribution:Bypassing traditional agrochemical distributors through digital platforms is reducing working capital cycles for Indian and Indonesian smallholder supply chains.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Complexometric titration and ICP-MS expertise for chelate purity verification is concentrated among aging specialist workforces in Europe and Japan.
- ISO 9001 Certification Timelines:Pharmaceutical offtake contracts now require updated quality management documentation that extends supplier qualification periods by 12-18 months.
- Legacy Formulation Integration:Agricultural distributors face technical friction blending next-generation biodegradable chelates with existing inventory management and application equipment calibrated for EDTA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Chelates Market |
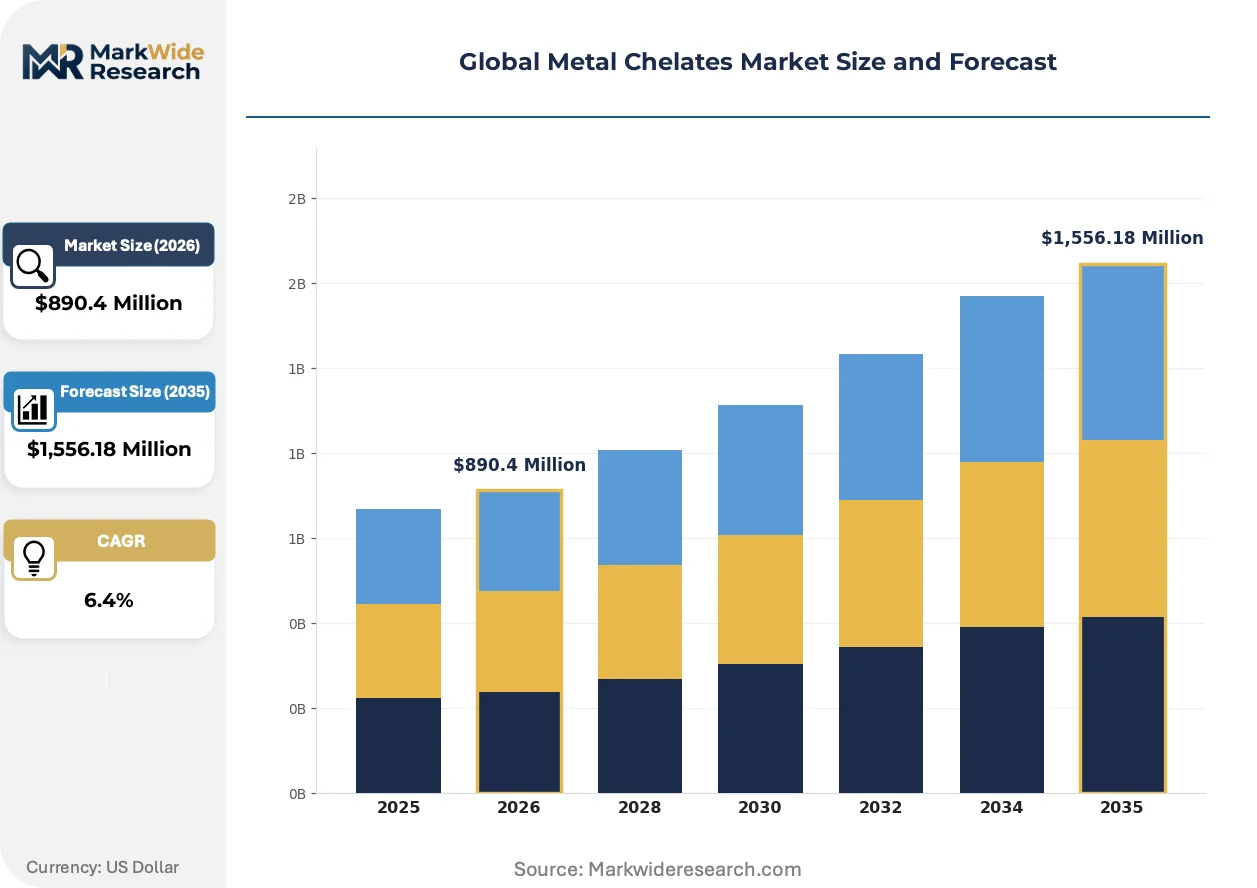
| Market Size in 2026 | $890.4 Million |
| Market Size in 2035 | $1,556.18 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EDTA, DTPA, EDDHA, HEDTA, Others Application: Fertilizers, Animal Feed, Pharmaceuticals, Water Treatment, Cosmetics End User: Agricultural Firms, Livestock Producers, Pharmaceutical Manufacturers, Water Purification Companies Packaging Type: Powder, Granules, Liquid, Pellets |
| Companies Covered | BASF SE, Yara International ASA, Nouryon, Akzo Nobel N.V., Syngenta AG, Nufarm, Haifa Group, Mitsubishi Chemical Corporation, Protex International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Chelates Market Shifts & Advancements
Formulation science is pivoting toward ligand architectures that balance agronomic stability with environmental persistence thresholds, while regulatory pressure on biodegradability accelerates substitution timelines for conventional chemistries.
Glutamic acid diacetic acid (GLDA) is decomposing the traditional EDTA monopoly in European household and industrial cleaning applications where aquatic toxicity concerns dominate procurement criteria. Unilever and Reckitt Benckiser reformulation programs are advancing GLDA incorporation at 15-20% annual substitution rates for dishwasher and laundry segments. This displacement is compressing EDTA volume growth in non-agricultural sectors and redirecting manufacturer R&D budgets toward amino-acid-derived alternatives.
REACH Annex XIV authorization requirements for certain persistent chelating agents are forcing pharmaceutical manufacturers to validate alternative ligands for parenteral nutrition and contrast media applications. ECHA's 2024 updated guidance on endocrine disruptor screening has extended analytical documentation timelines by eight months for suppliers seeking multi-jurisdictional approval. German and French pharmaceutical compounders are responding by consolidating supplier relationships with integrated producers capable of supporting regulatory defense dossiers.
Cooperative procurement consortiums in India and Indonesia are aggregating smallholder demand into volume contracts that bypass traditional distributor markups. These buyer collectives now specify chelate purity grades and delivery schedules previously reserved for large estate operations, compressing margin structures for mid-tier distributors. Maharashtra and Gujarat state agricultural departments are piloting platform-based tender systems that transparently benchmark supplier pricing against international reference points.
Global Metal Chelates Market Segmentation
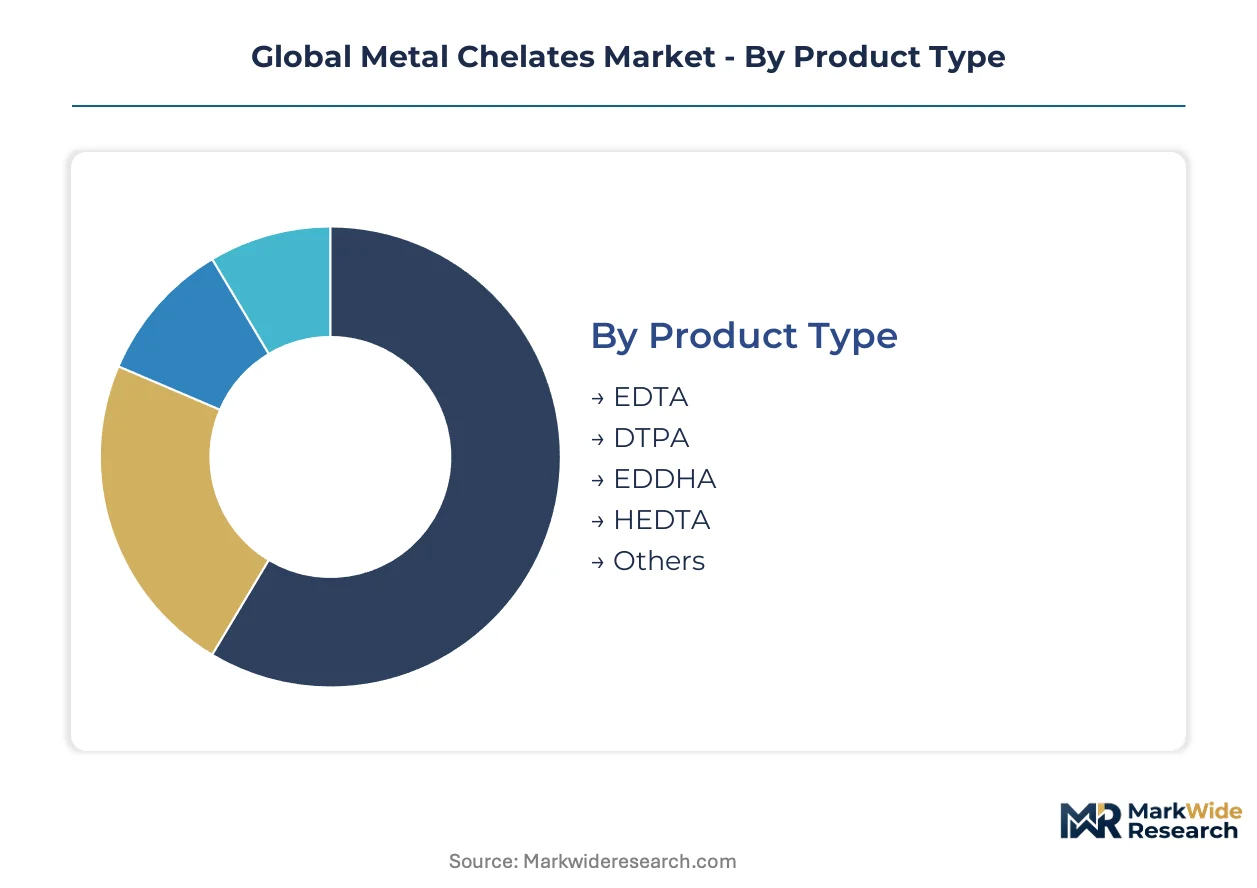
Metal chelate segmentation reveals divergent substitution pressures across ligand chemistries, with biodegradable alternatives compressing growth trajectories in non-agricultural applications while high-alkalinity agronomic needs protect premium formulations. Understanding these segment-specific threat vectors enables suppliers to allocate R&D resources toward defensible positions.
Product Type:
EDTA faces the most acute substitution threat from biodegradable ligands in European cleaning and water treatment sectors, while EDDHA maintains structural protection through unmatched stability in calcareous soils.
- EDTA:Ethylenediaminetetraacetic acid forms hexadentate complexes with divalent and trivalent metal ions, delivering cost-efficient micronutrient delivery across broad pH ranges. Demand concentrates in Indian agricultural cooperatives implementing government-mandated soil correction programs, though REACH-driven reformulation in European household products is redirecting volume toward dedicated fertilizer grades.
- EDDHA:Ethylenediamine-N,N'-bis(2-hydroxyphenylacetic acid) delivers ortho-hydroxyphenyl coordination that maintains iron solubility above pH 9.0, commanding premium positioning in Mediterranean and Brazilian Cerrado agriculture where soil alkalinity would precipitate conventional chelates. Adoption accelerates among Mato Grosso soybean operations deploying precision fertigation.
- DTPA:Diethylenetriaminepentaacetic acid provides intermediate stability suitable for neutral-to-slightly-alkaline conditions, finding application in hydroponic systems and foliar sprays where EDTA proves inadequate.
- HEDTA:Hydroxyethylethylenediaminetriacetic acid offers specialized performance in high-pH environments with reduced environmental persistence compared to EDTA, gaining traction in Nouryon's Mediterranean-focused formulations.
- Others:Emerging amino-acid-derived and polyaspartic acid ligands target OECD biodegradability thresholds, with GLDA leading substitution in Unilever and Reckitt Benckiser cleaning product portfolios.
EDTA anchors the volume base while biodegradable alternatives gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity agricultural inputs from specification-critical pharmaceutical and water treatment grades, with purity documentation burdens escalating across premium tiers.
- Fertilizers:Soil-applied and fertigated micronutrient delivery dominates tonnage, with Brazilian large-scale operations and Indian smallholder cooperatives driving formulation demand. Government soil health mandates in Maharashtra and Gujarat are compressing procurement cycles through platform-based tender systems.
- Water Treatment:Heavy metal capture and effluent compliance applications represent the most rapidly expanding demand pool, with German, Japanese, and United States utilities deploying chelating agents to meet tightening discharge limits. This segment commands analytical documentation premiums above agricultural tiers.
- Pharmaceuticals:Parenteral nutrition, contrast media, and monoclonal antibody downstream processing require ultra-high-purity grades with extensive toxicological dossiers. EMA and FDA validation timelines extend supplier qualification periods.
- Animal Feed:Zinc, copper, and manganese bioavailability enhancement in livestock rations, with regulatory maximum limits constraining formulation flexibility in European and North American markets.
- Cosmetics:Preservative and antioxidant applications facing reformulation pressure from natural-positioned brands, limiting growth trajectory relative to industrial segments.
Fertilizer applications generate the largest revenue base while water treatment climbs the fastest on regulatory compliance spending.
End User:
Customer type fragmentation concentrates procurement power among integrated agricultural enterprises and pharmaceutical compounders, squeezing mid-tier distributors through direct-to-cooperative digital platforms.
- Agricultural Firms:Large-scale Brazilian soybean and corn operations in Goiás and Mato Grosso anchor premium chelate consumption, while Indian smallholder cooperatives aggregate demand through state-backed procurement consortiums.
- Pharmaceutical Manufacturers:German and French compounders consolidate supplier relationships around integrated producers capable of supporting REACH Annex XIV defense dossiers and endocrine disruptor screening documentation.
- Livestock Producers:Concentrated animal feeding operations in the United States and European Union drive feed-grade chelate specification, with maximum permitted levels set by national veterinary regulators.
- Water Purification Companies:Municipal and industrial utilities across Germany, Japan, and the United States deploy chelating agents for heavy metal removal, with effluent limits tightening under EPA and OECD frameworks.
Agricultural firms anchor the volume base while pharmaceutical manufacturers expand specification premiums fastest.
Packaging Type:
Supply chain configuration favors liquid and powder formats for scale efficiency, with pellet and granule differentiation targeting precision application equipment compatibility.
- Liquid:Ready-to-use formulations dominate fertigation and hydroponic systems, with Brazilian Cerrado operations favoring tank-mix compatibility. Concentrates reduce freight costs but require corrosion-resistant handling infrastructure.
- Powder:Bulk shipment efficiency and extended shelf stability make this the default for large-volume agricultural procurement, particularly in Indian cooperative tenders specifying purity grades and delivery schedules.
- Granules:Controlled-release applications in conventional broadcasting equipment, with particle size distribution calibrated to prevent segregation in blended fertilizers.
- Pellets:Specialized formats for precision agriculture equipment, commanding format premiums in automated application systems.
Powder formats anchor the volume base while liquid formulations gain share fastest on precision agriculture expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government soil health mandates and effluent compliance programs are concentrating metal chelate procurement across four major economies. Each market exhibits distinct regulatory pressures and agricultural modernization trajectories.
United States
Water treatment utilities deploy chelating agents for heavy metal capture under tightening EPA discharge standards. The EPA evaluates chelate toxicity profiles for pharmaceutical and agricultural applications. Industrial clusters along the US Gulf Coast anchor ethylenediamine production for EDTA feedstock.
Germany
REACH Annex XIV authorization requirements force pharmaceutical compounders to validate alternative ligands for parenteral nutrition. ECHA guidance on endocrine disruptor screening extends analytical documentation timelines. Chemical manufacturing concentrates in North Rhine-Westphalia and the Upper Rhine region.
India
The Soil Health Card Scheme accelerates EDTA and EDDHA adoption among smallholder cooperatives seeking micronutrient correction. BIS certification mandates create compliance layers favoring established regulatory affairs capabilities. Maharashtra and Gujarat state agricultural departments pilot platform-based tender systems.
Brazil
Large-scale soybean and corn operations in Mato Grosso and Goiás expand precision agriculture programs with customized iron chelate fertigation systems. ANVISA regulates maximum permitted levels for feed-grade applications. The Cerrado region anchors premium chelate consumption for high-alkalinity soil conditions.
China
GB standards for agricultural inputs and dual carbon goals reshape acceptable ligand chemistries across fertilizer applications. The Ministry of Ecology and Environment tightens biodegradability classifications for industrial chelating agents. Yangtze River Delta petrochemical complexes concentrate ethylenediamine derivative production.
Global Metal Chelates Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive feedstock positions and specialized agrochemical formulators with regional distribution density. Three strategic archetypes dominate: petrochemical-integrated producers controlling upstream ethylenediamine supply, fertilizer-specialist distributors leveraging backward integration into ammonia and nitric acid, and application-focused innovators developing biodegradable ligand alternatives. Competitive intensity centers on regulatory dossier capabilities and direct-to-farm digital platform penetration.
Among integrated chemical producers, BASF SE anchors the archetype with ethylenediamine supply chain control, while Yara International ASA exemplifies fertilizer-specialist positioning through captive ammonia and nitric acid feedstock. Nouryon occupies a position within the application-specialist tier, differentiated by tailored HEDTA grades for Mediterranean high-pH agriculture.
| Leading Market Players |
|---|
| BASF SE |
| Yara International ASA |
| Nouryon |
| Akzo Nobel N.V. |
| Syngenta AG |
| Nufarm |
| Haifa Group |
| Mitsubishi Chemical Corporation |
| Protex International |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Brazilian agricultural enterprises and integrated ethylenediamine producers lock in supply access and price visibility across eighteen-month procurement cycles, insulating buyers from ammonia feedstock volatility while anchoring EDTA cost basins.
Pricing Analysis
Certification level creates the primary spread across pharmaceutical, agricultural, and industrial tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9001 documentation burdens, REACH registration status, and batch-specific purity verification. Cost compression in standard-grade agricultural EDTA is intensifying because Indian cooperative procurement platforms transparently benchmark supplier pricing against international reference points. Smallholder cooperatives in Maharashtra exhibit highest price sensitivity, while German pharmaceutical compounders accept specification premiums for ultra-high-purity grades with toxicological dossiers.
Supply Chain Analysis
China and the US Gulf Coast anchor ethylenediamine production for EDTA feedstock, with Yangtze River Delta petrochemical complexes and integrated complexes near Houston supplying global derivative demand. Manufacturing draws from ammonia, nitric acid, and formaldehyde inputs, with purity grades hinging on complexometric titration expertise concentrated among aging specialist workforces in Europe and Japan. Single-source vulnerability runs through Chinese ethylenediamine concentration, exposing buyers to regional supply disruptions. Distribution runs through agrochemical distributors, direct-to-cooperative digital platforms, and pharmaceutical compounder networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping procurement power as Indian and Indonesian cooperative consortiums aggregate smallholder demand into volume contracts, creating interoperability standards that bypass traditional distributor markups and compress margin structures for mid-tier intermediaries.
For Market Incumbents: Shield agricultural market share by deepening backward integration into ammonia and nitric acid feedstock, securing captive supply against ethylenediamine price volatility. Accelerate ISO 9001 certification renewal cycles to extend supplier qualification timelines for pharmaceutical offtake contracts, defending position against emerging biodegradable ligand producers targeting OECD reclassification windows. For New Entrants and Emerging Players: Differentiate on amino-acid-derived ligand architectures targeting European REACH Annex XIV substitution timelines ahead of persistent chelate restrictions. Target water treatment utilities in Germany and Japan with biodegradable polyaspartic acid formulations, leveraging direct-to-utility digital sales channels that circumvent established agrochemical distribution networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated producers with regulatory dossier capabilities and captive feedstock positions. Long-term viability centers on manufacturers capable of supporting multi-jurisdictional approval documentation across REACH, EPA, and BIS frameworks. Watch OECD biodegradability classification shifts as the signal indicating substitution velocity for conventional EDTA formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Feedstock | Yara International's captive nitric acid supply secures cost basins against Gulf Coast ethylenediamine volatility. |
| Biodegradable Ligand R&D Program | GLDA and polyaspartic acid development targets Unilever reformulation timelines ahead of REACH restrictions. |
| Direct-to-Cooperative Digital Platform | Maharashtra state tender systems aggregate smallholder demand into volume contracts bypassing distributor markups. |
| REACH Annex XIV Defense Dossier Investment | German pharmaceutical compounders consolidate supplier relationships around integrated producers with regulatory affairs depth. |
| Precision Agriculture Fertigation Partnership | Mato Grosso soybean operations deploy customized iron chelate systems with Brazilian Cerrado expansion capital. |
Research Methodology
Initial hypotheses were tested against primary input from technical R&D directors at integrated chemical producers, procurement leads at Brazilian agricultural enterprises, regulatory affairs managers navigating REACH compliance, and water treatment utility planning officers, then refined through secondary validation against ECHA guidance documents, EPA toxicity evaluation records, Indian BIS certification standards, and customs trade data for ethylenediamine derivatives. Bottom-up volume modeling triangulated against top-down market sizing across ligand chemistry segments.
Variance decomposition across the analysis window isolates drivers by product type, application end-use, packaging format, and regional regulatory cluster. CAGRs derive from segment-level growth rate reconciliation with macroeconomic indicators and industry-specific inputs including soil health program enrollment data and effluent compliance spending trajectories.
Decision-makers should treat outputs as directional under base assumptions of stable REACH enforcement timelines and continued Indian government soil health funding; material deviation in OECD biodegradability reclassifications or ethylenediamine supply disruptions would warrant model refresh. Recalibration cycles align with material shifts in regulatory classification protocols and cooperative procurement platform penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Zinc Ricinoleate Market
Specialty Chemicals
Global Lactobionic Acid Market
Specialty Chemicals
PEG and PPG Esters Market
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
Diisobutyl Adipate Market
Specialty Chemicals
Global Silanes Market
Specialty Chemicals
UK Insect Repellent Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Middle East and Africa Polyvinylpyrrolidone (PVP) Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Middle East and Africa Amino Acids Market
Specialty Chemicals
Global Water Based Acrylates Copolymer Rheology Modifiers Market
Specialty Chemicals
Multichannel Reagent Reservoir Market