
 Sphingolipids Market | 2026-2036
Sphingolipids Market Size, Share, and Industry Trends Forecast 2026-2036
Sphingolipids Market Analytics
Germany is fragmenting into multiple specialized production zones for high-purity sphingolipids, with Rhineland-Palatinate and North Rhine-Westphalia emerging as competing hubs for pharmaceutical-grade output. Evonik Industries AG leverages its alkoxide chemistry platform to sustain captive ceramide synthesis for drug delivery applications. Croda International PLC anchors lipid innovation through its Super Refined excipient technology, while Merck KGaA competes across glycosphingolipid standards for cell culture media.
Sphingolipids comprise a class of complex lipids built on sphingosine backbones, with ceramides, sphingomyelins, and glycosphingolipids distinguished by head-group composition and fatty acid chain length typically spanning C16 to C24. These molecules function as structural membrane components, signaling mediators in apoptosis and inflammation pathways, and essential raw materials for liposomal drug formulations and cell therapy manufacturing. Ceramides dominate current revenue contribution due to established dermatological and oncology demand, while glycosphingolipids represent the fastest-expanding category as cell therapy developers adopt them for immune modulation protocols. Sphingomyelins retain mature positioning in nutritional supplement applications, though margin pools are shifting toward pharmaceutical-grade specifications.
FDA orphan drug regulations and EMA's advanced therapy medicinal products framework shape clinical-grade sphingolipid purity requirements, with both agencies tightening impurity profiling for lipid-based therapeutics. ISO 13485 and ICH Q7 standards govern contract manufacturing quality systems, creating compliance barriers for new entrants without validated GMP lipid synthesis. Stakeholders must monitor evolving pharmacopeial monographs for sphingolipid reference standards as cell and gene therapy pipelines scale toward commercial manufacturing.
Market Dynamics
Pharmaceutical-grade sphingolipid supply chains are bifurcating into captive synthesis networks and specialized contract manufacturing, driven by tightening FDA and EMA purity mandates for cell therapy applications. This structural shift concentrates procurement power among developers with validated GMP lipid capabilities.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products framework:Accelerated regulatory pathways for sphingolipid-based cell therapies are compressing development timelines and expanding addressable patient populations in rare disease indications.
- Cell therapy manufacturing:Commercial-scale expansion of allogeneic cell therapy facilities is generating sustained demand for glycosphingolipid immune modulators as critical raw materials.
- Rhineland-Palatinate production cluster:Concentrated alkoxide chemistry expertise and shared analytical infrastructure are reducing batch-to-batch variability for ceramide suppliers serving dermatological drug developers.
Market Restraints
- Long-chain fatty acid volatility:C18-C24 saturated fatty acid feedstock prices fluctuate with palm oil and tallow commodity markets, compressing margin predictability for ceramide manufacturers.
- German supply concentration:Over-reliance on Evonik Industries and Merck KGaA for pharmaceutical-grade sphingomyelin creates single-source vulnerability for cell culture media formulators.
- ICH Q7 compliance barriers:Validation requirements for multi-step sphingosine backbone synthesis exclude smaller chemical suppliers from pharmaceutical procurement pools.
Strategic Opportunities
- North Rhine-Westphalia hub expansion:Underutilized specialty chemical infrastructure in the Leverkusen-Dormagen corridor offers brownfield capacity for glycosphingolipid producers seeking EU market access.
- ISO 13485 contract manufacturing:Medical device-grade lipid synthesis capabilities remain scarce, creating white space for suppliers bridging pharmaceutical and diagnostic applications.
- Continuous flow chemistry:Integration of microreactor technology with traditional alkoxide platforms promises yield improvements and reduced solvent waste for ceramide production.
Industry Challenges
- Analytical method development:Pharmacopeial monographs for sphingolipid reference standards remain incomplete, forcing manufacturers to develop and validate in-house impurity profiling protocols.
- Cross-functional talent scarcity:Lipid chemists with simultaneous expertise in GMP compliance and cell therapy raw material specifications command premium compensation and extended recruitment cycles.
- Legacy batch record systems:Paper-based manufacturing documentation at established suppliers creates data integrity risks during FDA pre-approval inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sphingolipids Market |
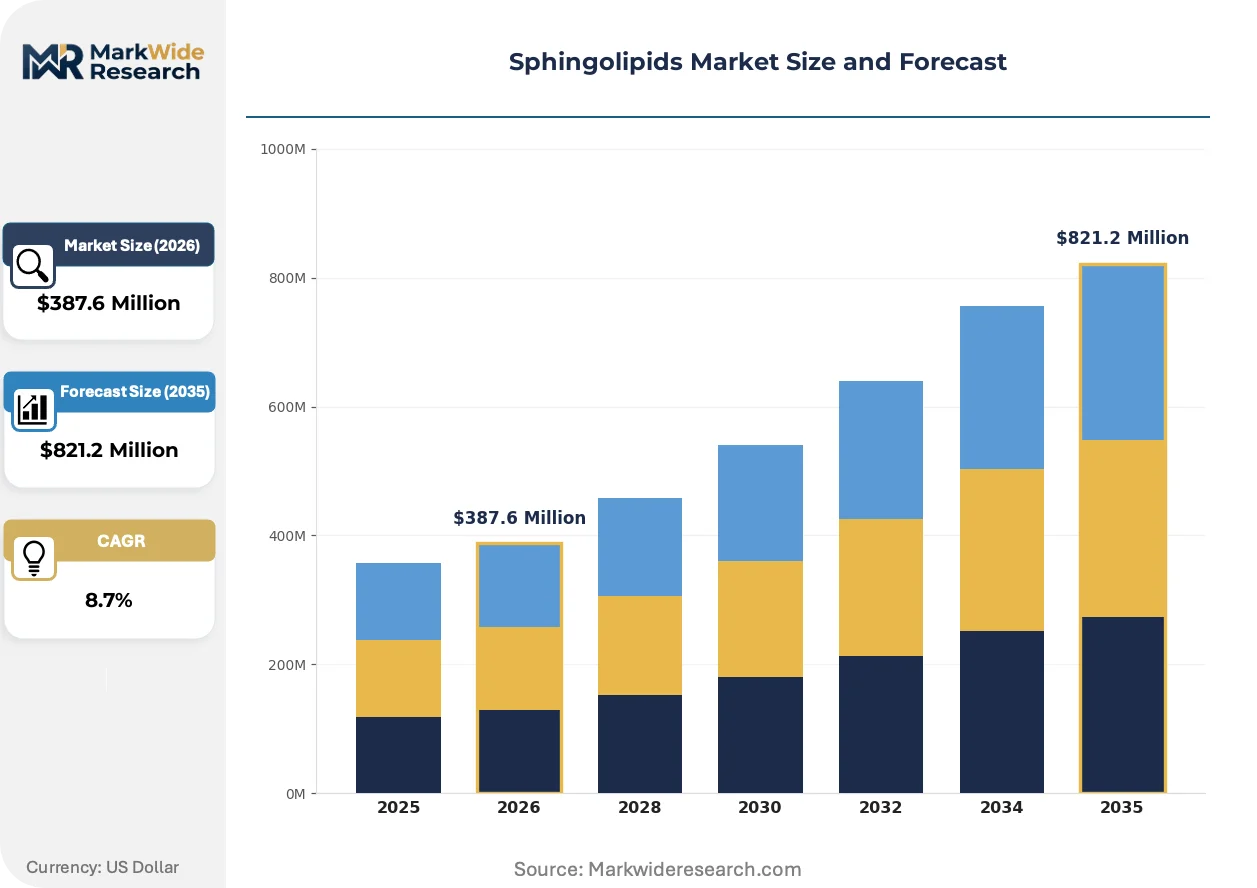
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramides, Sphingomyelins, Glycosphingolipids, Sphingosine Application: Pharmaceuticals, Cosmetics, Nutritional Supplements, Personal Care End User: Pharmaceutical Companies, Research Institutions, Contract Manufacturers, Cosmetic Brands Distribution Channel: Direct Sales, Online Retail, Third-Party Distributors, Wholesalers |
| Companies Covered | Evonik Industries AG, Croda International PLC, Lipoid GmbH, Merck KGaA, Avanti Polar Lipids, Cayman Chemical Company, CLR Berlin, Thermo Fisher Scientific Inc., Takara Bio Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sphingolipids Market Evolving Landscape
Enzymatic synthesis routes are displacing traditional chemical alkoxide methods across pharmaceutical-grade sphingolipid production. This biological manufacturing pivot is compressing process development timelines while expanding stereochemical control over ceramide molecular species.
Microreactor-based continuous flow systems are rendering obsolete conventional batch reactor setups for high-purity ceramide manufacturing. Cell therapy developers in Germany and Switzerland are specifying flow-synthesized lipids for immune modulation protocols, forcing contract manufacturers to retrofit existing alkoxide infrastructure or lose qualified supplier status.
REACH authorization requirements for CMR-classified solvents are restricting traditional sphingosine extraction methods across EU manufacturing sites. ECHA's tightening substance restrictions are accelerating adoption of biosynthetic routes using engineered yeast strains, particularly affecting glycosphingolipid producers serving EMA-regulated clinical trials.
Specification-driven procurement contracts are replacing spot-market purchasing for pharmaceutical-grade sphingomyelins. Cell therapy CDMOs in Germany now require locked-in purity certificates and multi-year supply agreements, squeezing trading margins for distributors while securing captive volumes for integrated alkoxide chemistry platforms.
Sphingolipids Market Segmentation
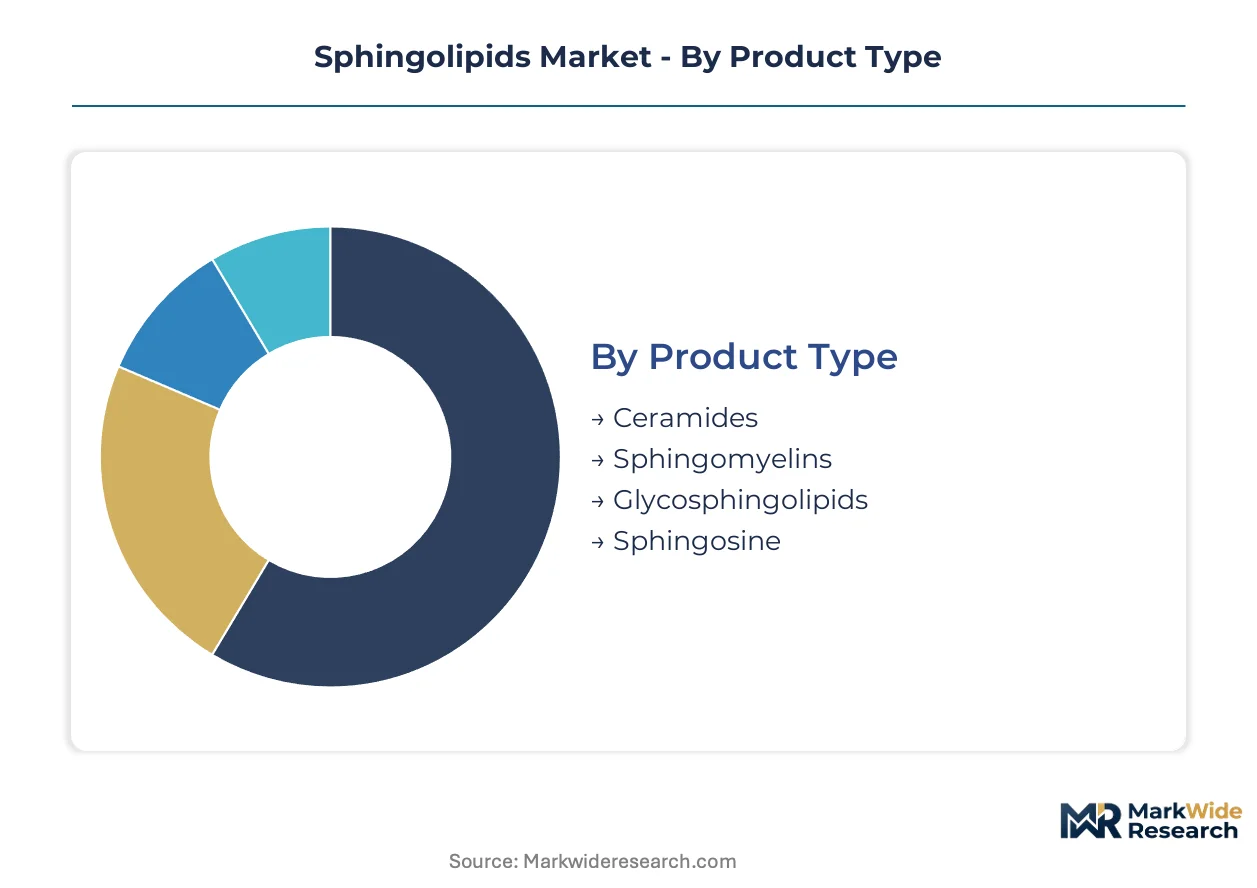
Sphingolipid procurement patterns diverge sharply across product grades and end-use specifications. Pharmaceutical applications demand validated GMP synthesis with complete impurity profiling, while cosmetic and nutritional segments prioritize cost-efficient bulk supply with standardized fatty acid chain distributions.
Product Type:
Cost tier differentiation separates pharmaceutical-grade specifications from industrial bulk supply, with purity premiums expanding across ceramide molecular species.
- Ceramides:These N-acylated sphingosine derivatives with C16-C24 fatty acid chains constitute the primary revenue base. Evonik Industries anchors European supply through alkoxide chemistry platforms serving dermatological drug developers in Germany. FDA and EMA tightening of lipid-based therapeutic impurity limits is compressing batch acceptance rates for non-validated suppliers.
- Glycosphingolipids:Carbohydrate-modified sphingolipids function as immune modulators in cell therapy manufacturing. Demand concentrates among allogeneic cell therapy CDMOs in Germany and Switzerland adopting these molecules for clinical-scale immune modulation protocols. EMA Advanced Therapy Medicinal Products framework acceleration is expanding addressable patient populations.
- Sphingomyelins:Phosphocholine-headgroup lipids retain mature positioning in nutritional supplement applications.
- Sphingosine:The fundamental backbone molecule serves as precursor for downstream ceramide synthesis.
Ceramides command the established base. The steepest expansion runs through glycosphingolipids.
Application:
End-use specifications create divergent purity requirements, with pharmaceutical and cell therapy applications enforcing the strictest analytical thresholds.
- Pharmaceuticals:Liposomal drug formulations and sphingolipidosis therapeutics require ICH Q7-compliant synthesis with validated impurity profiling. FDA orphan drug designations for rare disease indications are reshaping clinical trial material supply chains. German production clusters in Rhineland-Palatinate and North Rhine-Westphalia anchor specialized manufacturing for this segment.
- Cosmetics:Skin barrier repair formulations utilize ceramide complexes at lower purity grades than pharmaceutical specifications. Croda International's Super Refined excipient technology targets this segment with enhanced oxidative stability for premium dermatological products.
- Nutritional Supplements:Sphingomyelin concentrates for infant formula and cognitive health applications operate on volume-driven procurement.
- Personal Care:Hair conditioning and emollient applications represent the most price-sensitive demand tier.
Pharmaceuticals command the established base. The steepest expansion runs through nutritional supplements.
End User:
Customer type determines procurement modality, with integrated pharmaceutical developers favoring captive synthesis and emerging cell therapy developers relying on contract manufacturing.
- Pharmaceutical Companies:Large developers maintain internal lipid synthesis capabilities or locked-in supply agreements with validated GMP manufacturers. Merck KGaA serves this segment with glycosphingolipid reference standards for cell culture media applications.
- Contract Manufacturers:Cell therapy CDMOs represent the fastest-expanding demand channel, requiring multi-year supply agreements with locked purity certificates.
- Research Institutions:Academic and government laboratories procure analytical-grade sphingolipids for mechanistic studies.
- Cosmetic Brands:Formulators source ceramide complexes through distributors with less stringent documentation requirements.
Pharmaceutical companies command the established base. The steepest expansion runs through contract manufacturers.
Distribution Channel:
Supply chain configuration reflects end-use criticality, with pharmaceutical-grade materials bypassing traditional distribution layers.
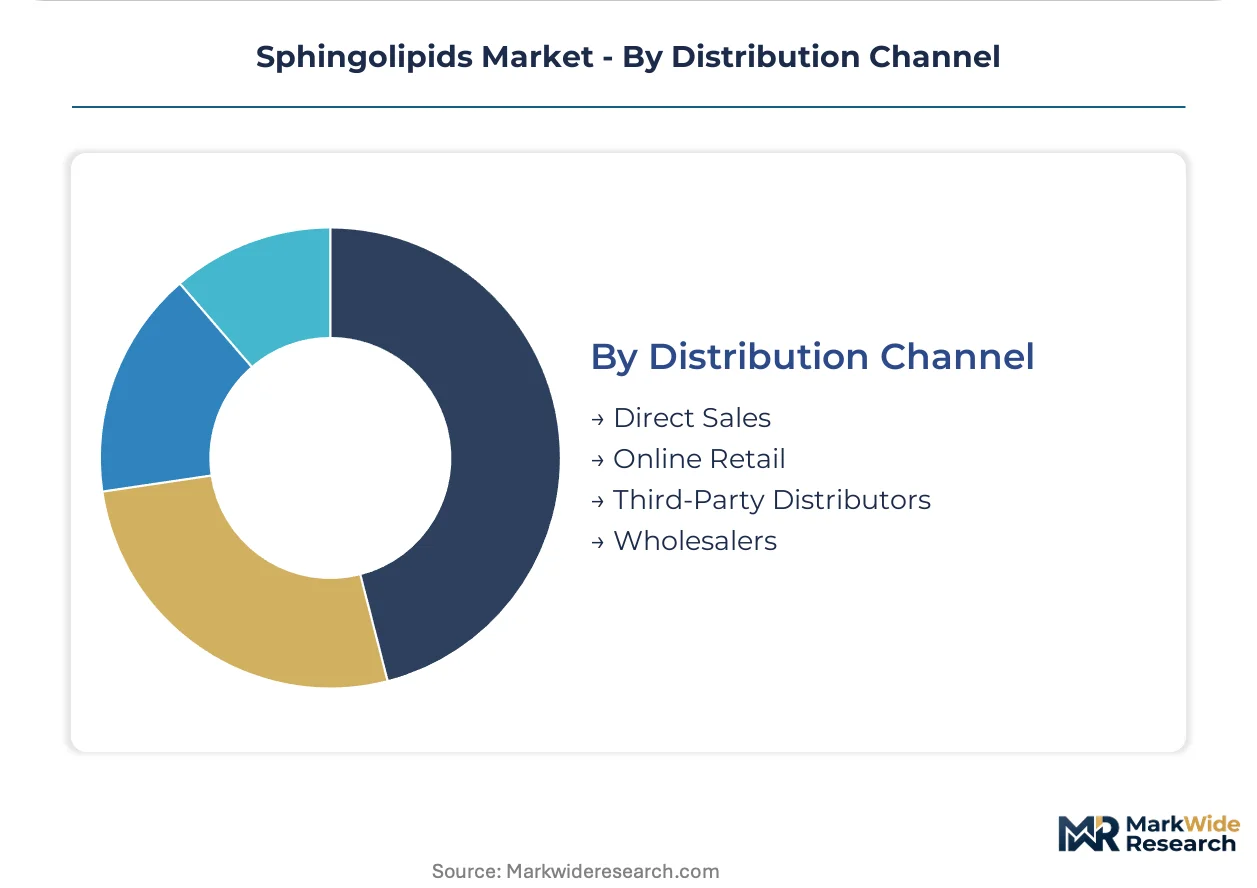
- Direct Sales:Pharmaceutical and cell therapy developers negotiate directly with alkoxide chemistry platforms for validated GMP batches. This channel captures the highest-margin transactions with complete chain-of-custody documentation.
- Third-Party Distributors:Regional specialty chemical distributors serve cosmetic and nutritional supplement formulators with standardized product grades.
- Online Retail:Research-grade sphingolipids for analytical applications flow through e-commerce channels.
- Wholesalers:Bulk cosmetic raw material traders handle lower-specification ceramide complexes.
Direct sales command the established base. The steepest expansion runs through third-party distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug designations and EMA's advanced therapy frameworks are concentrating pharmaceutical-grade sphingolipid production in Germany, with specialized clusters emerging across Rhineland-Palatinate and North Rhine-Westphalia.
United States
Cell therapy developers in Boston and San Francisco are driving procurement of glycosphingolipid immune modulators for clinical-scale manufacturing. FDA tightening of lipid-based therapeutic impurity limits is compressing batch acceptance rates for non-validated suppliers. The Research Triangle Park corridor anchors specialized analytical services for sphingolipid reference standards.
Germany
Evonik Industries and Merck KGaA anchor pharmaceutical-grade production clusters in Rhineland-Palatinate and North Rhine-Westphalia. EMA's advanced therapy medicinal products framework is accelerating regulatory pathways for sphingolipid-based cell therapies. The Leverkusen-Dormagen corridor offers underutilized specialty chemical infrastructure for brownfield glycosphingolipid capacity expansion.
Switzerland
Cell therapy CDMOs in Basel are specifying flow-synthesized lipids for immune modulation protocols. Swissmedic oversight of advanced therapy medicinal products ensures alignment with EMA purity mandates. The Basel-Zürich corridor concentrates lipid innovation for clinical-scale cell therapy manufacturing.
Japan
PMDA regulatory harmonization with ICH Q7 standards is governing contract manufacturing quality systems for sphingolipid synthesis. METI support for regenerative medicine commercialization is expanding addressable demand for glycosphingolipid raw materials. The Kansai region anchors specialized lipid production for cell culture media applications.
United Kingdom
Research institutions in Cambridge and Oxford are procuring analytical-grade sphingolipids for mechanistic studies in neurodegenerative disease. MHRA post-Brexit regulatory autonomy is maintaining alignment with EMA advanced therapy frameworks. The Oxford-Cambridge arc concentrates academic demand for sphingosine backbone precursors.
Sphingolipids Market Competitive Landscape
Capability concentration sits with integrated chemical platforms possessing validated GMP lipid synthesis; scale advantage sits with diversified life science conglomerates serving multiple end-use segments. The vendor base stratifies across three tiers: captive synthesis networks for large pharmaceutical developers, specialized contract manufacturers with ISO 13485 certification, and regional distributors serving cosmetic and nutritional applications. Dominant competitive moves include strategic partnerships between alkoxide chemistry platforms and cell therapy CDMOs, plus brownfield capacity expansion in underutilized European specialty chemical corridors.
Within the integrated chemical platform tier, Evonik Industries AG and Merck KGaA exemplify capability concentration through captive ceramide and glycosphingolipid production serving pharmaceutical-grade specifications. Among specialty chemical specialists, Croda International PLC occupies a position exemplifying lipid innovation through excipient technology development. These three entities represent the structural anchors of pharmaceutical-grade supply, with their geographic positioning in Germany reflecting the regional concentration of alkoxide chemistry expertise and EMA-aligned regulatory infrastructure.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Croda International PLC |
| Lipoid GmbH |
| Merck KGaA |
| Avanti Polar Lipids |
| Cayman Chemical Company |
| CLR Berlin |
| Thermo Fisher Scientific Inc. |
| Takara Bio Inc. |
| Others |
Value Network & Pricing Analysis
German alkoxide chemistry concentration in Rhineland-Palatinate and North Rhine-Westphalia anchors pharmaceutical-grade sphingolipid production, concentrating margin capture with validated GMP manufacturers while squeezing trading margins for non-validated distributors serving cosmetic and nutritional tiers.
Pricing Analysis
Geographic price spreads between German pharmaceutical-grade output and Asian bulk ceramide supply exceed threefold, reflecting ICH Q7 compliance premiums and batch-to-batch variability guarantees. Three-tier pricing structure across GMP-certified, ISO-grade, and cosmetic bulk levels separates cell therapy developers from dermatological formulators from personal care blenders. Cost compression in nutritional supplement sphingomyelins is intensifying because infant formula manufacturers are consolidating procurement volumes. Cosmetic brands exhibit highest price sensitivity; cell therapy CDMOs prioritize purity certificates over unit economics.
Supply Chain Analysis
EU REACH authorization requirements for CMR-classified solvents restrict traditional sphingosine extraction methods, limiting flow of legacy chemical intermediates into pharmaceutical manufacturing channels. Supply concentrates in Germany, Switzerland, and Japan for clinical-grade glycosphingolipids, with C18-C24 saturated fatty acid feedstocks drawing from palm oil and tallow commodity markets. Single-source vulnerability runs through Evonik Industries and Merck KGaA for pharmaceutical-grade sphingomyelin. Distribution runs through direct sales for validated GMP batches, third-party distributors for cosmetic grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA Advanced Therapy Medicinal Products framework acceleration signals early-cycle expansion for sphingolipid immune modulators, with orphan drug designation pipelines multiplying addressable indications faster than manufacturing capacity can scale.
For Market Incumbents: Build regulatory certification moats through ICH Q7 validation investments and locked-in supply agreements with cell therapy CDMOs. Secure backward integration into C18-C24 fatty acid feedstocks to buffer palm oil commodity volatility. Expand alkoxide chemistry capacity in the Leverkusen-Dormagen corridor before brownfield sites attract competitors. For New Entrants and Emerging Players: ISO 13485 contract manufacturing for medical device-grade lipid synthesis represents the most penetrable entry point, given scarce qualified suppliers bridging pharmaceutical and diagnostic applications. North Rhine-Westphalia underutilized specialty chemical infrastructure offers immediate EU market access without greenfield construction timelines. Partner with enzymatic synthesis technology providers to bypass incumbent alkoxide chemistry advantages. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale GMP lipid manufacturers with existing EMA regulatory relationships and expandable batch capacity. Long-term viability hinges on positioning ahead of commercial-scale allogeneic cell therapy manufacturing ramp-up. Watch FDA orphan drug designation velocity as the critical inflection signal for clinical material demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Commercial allogeneic cell therapy facilities require locked-in glycosphingolipid supply agreements with validated GMP producers. |
| Regulatory Approval Pathway | EMA Advanced Therapy Medicinal Products framework acceleration compresses development timelines for sphingolipidosis therapeutics. |
| Backward Integration | Captive C18-C24 fatty acid sourcing buffers ceramide manufacturers from palm oil commodity price swings. |
| Long-term Supply Agreement | Cell therapy CDMOs now require multi-year purity certificates, squeezing spot-market distributors. |
| Joint Venture | Alkoxide chemistry platforms partnering with enzymatic synthesis specialists capture yield improvements and stereochemical control. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with lipid chemists, GMP compliance officers, cell therapy manufacturing heads, and pharmaceutical procurement managers; and secondary validation against FDA orphan drug filings, EMA advanced therapy submissions, ICH Q7 guidance documents, and German chemical industry trade data. Bottom-up triangulation across product-grade volume estimates and top-down cross-check against pharmaceutical excipient market aggregates anchored forecast integrity.
Forecast inputs included modeling across product type, application purity tier, end-user procurement modality, and regional regulatory cluster throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Enzymatic synthesis adoption curves and continuous flow chemistry retrofit timelines served as industry-specific forecast modifiers.
Macroeconomic conditions sit as an overlay; deviation in palm oil commodity prices, REACH authorization timelines, or cell therapy clinical trial success rates would shift the trajectory. Forecasts reflect documented assumptions about EMA regulatory pathway stability and German production cluster capacity expansion. Material shifts in FDA orphan drug designation criteria or ICH Q7 impurity profiling standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Lanolin Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
Asia-Pacific UV Stabilizers Market
Specialty Chemicals
Phytosphingosine Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
Europe Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Zinc Methionine Chelates Market
Specialty Chemicals
Organosilicon Electrolyte Market
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market