
 ASEAN Cosmetic Chemicals Market | 2026-2036
ASEAN Cosmetic Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Cosmetic Chemicals Market Outlook
Buyer concentration among ASEAN mid-tier personal care manufacturers is pivoting toward specialty ingredient partnerships as multinational brands localize production. BASF SE leverages its integrated surfactant complexes to anchor supply relationships with Thai and Indonesian formulators. Evonik Industries AG differentiates through silicone-free emollient technologies targeting clean-label skincare lines. Kao Commercial Co. Ltd. sustains regional dominance via backward integration into fatty alcohol production.
Cosmetic chemicals encompass functionally active and inert substances formulated into beauty and personal care products, including surfactants with specific HLB values for emulsion stability and preservatives with defined MIC ranges against microbial contamination. These inputs enable texture control, shelf-life extension, and sensorial performance across commercial cosmetic manufacturing. Surfactants occupy the largest volume share given their ubiquity across cleansing formulations, while emollients represent the fastest-expanding margin pool as premium skincare penetration deepens in urban Vietnam and the Philippines. Thickeners command stable demand in haircare applications where rheology modification determines product dispensing and spreadability.
ASEAN Cosmetics Directive implementation requires ingredient disclosure and safety assessment alignment across member states, while Thailand's FDA and Indonesia's BPOM enforce national cosmetic registration with varying documentation intensity. The region's national regulators are tightening preservative concentration limits and banning specific paraben variants, forcing reformulation cycles among legacy suppliers. Stakeholders must monitor divergence between harmonized ASEAN standards and country-specific enforcement timelines to optimize regulatory filing sequences.
Market Dynamics
The ASEAN Cosmetics Directive harmonization is compressing formulation timelines while fragmenting compliance pathways across Thailand, Indonesia, and Vietnam, forcing ingredient suppliers to maintain parallel regulatory dossiers for the same molecule.
Growth Catalysts
- ASEAN Cosmetics Directive:Harmonized ingredient disclosure standards reduce cross-border registration redundancy for suppliers serving multiple member states.
- Clean-label skincare penetration:Urban Vietnamese and Filipino consumers prioritize silicone-free and paraben-free formulations, pulling specialty emollient demand upward.
- Java-based manufacturing corridors:Indonesia's concentrated personal care production base generates procurement economies for surfactant and preservative suppliers.
Market Restraints
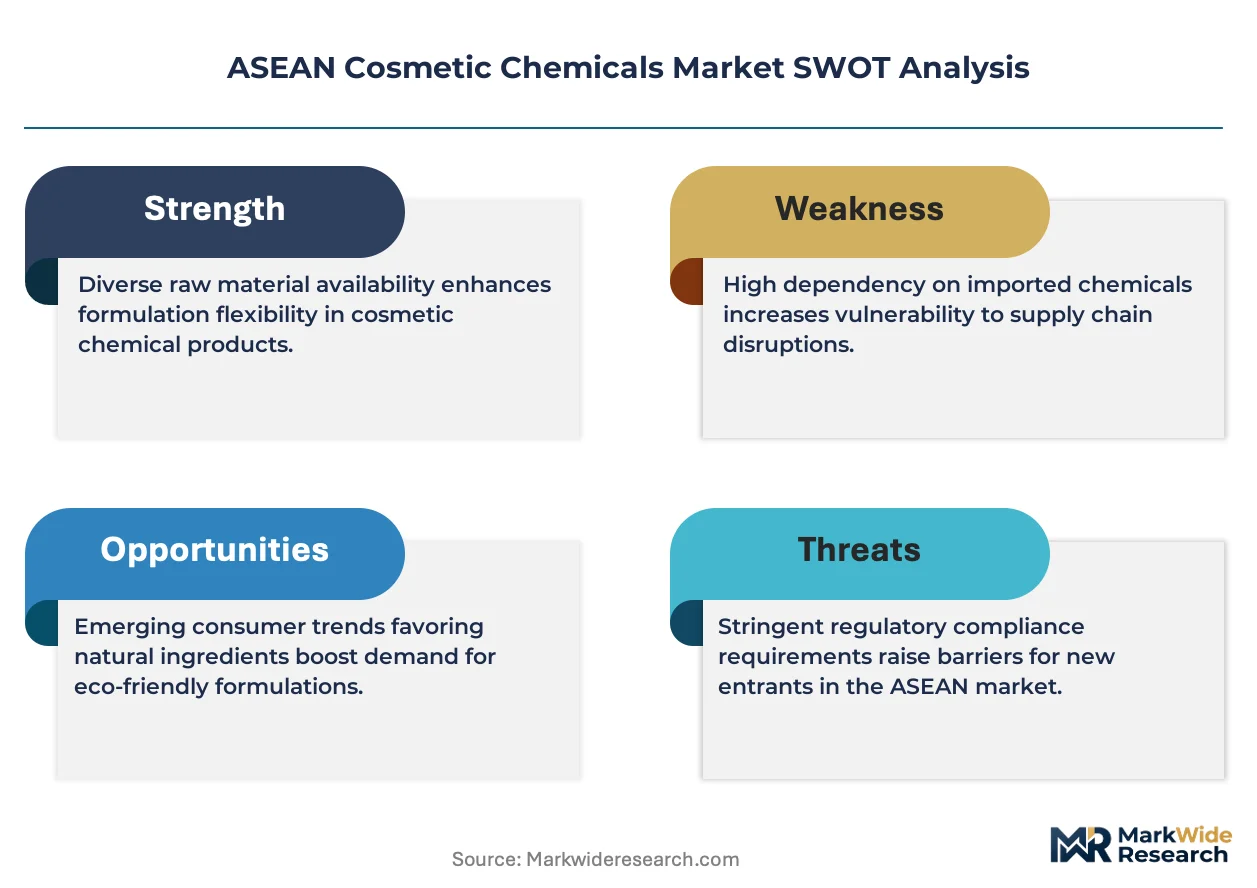
- Palm oil derivative volatility:Fatty alcohol and surfactant feedstock costs fluctuate with Malaysian-Indonesian palm olein export policy shifts.
- Thai FDA documentation intensity:Cosmetic registration requires extended safety assessment timelines that delay new ingredient commercialization.
- Biotechnology-derived actives:Fermentation-based alternatives threaten synthetic peptide and retinol derivative market positions in premium anti-aging segments.
Strategic Opportunities
- Philippines personal care underpenetration:Per-capita cosmetic consumption in secondary Philippine cities trails Bangkok and Jakarta by substantial margins.
- Halal certification convergence:BPOM Indonesia and JAKIM Malaysia alignment creates unified compliance pathways for Muslim-majority market access.
- E-commerce direct-to-formulator channels:Specialty chemical distributors bypass traditional importer networks to serve Vietnamese indie beauty brands.
Industry Challenges
- Cosmetic toxicologist scarcity:Qualified safety assessors for ASEAN Cosmetics Directive dossier preparation command premium compensation in Bangkok and Singapore.
- Legacy ERP integration:Mid-tier Thai formulators struggle to incorporate batch-level ingredient traceability into existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Cosmetic Chemicals Market |
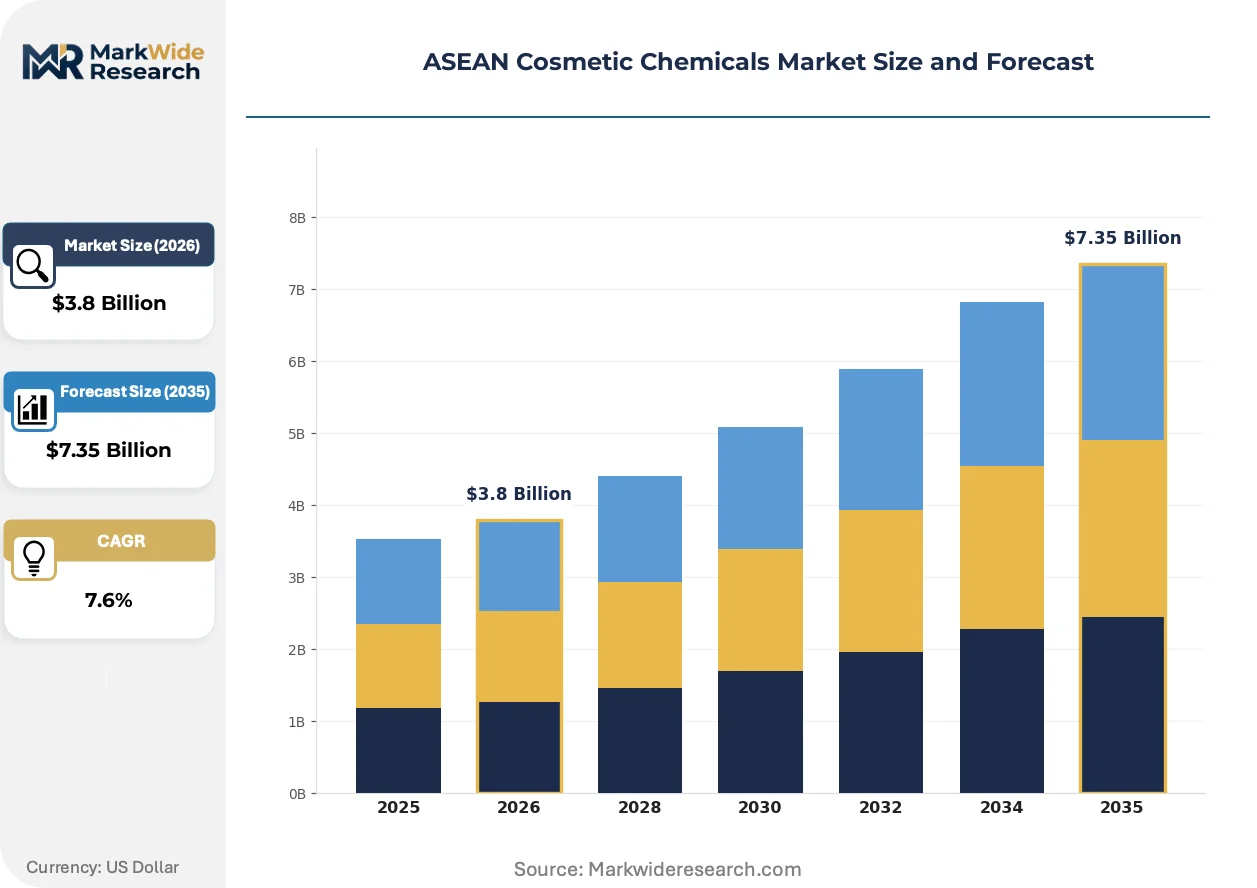
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Preservatives, Emollients, Thickeners Formulation Type: Liquid, Cream, Gel, Powder End Use: Skincare, Haircare, Makeup, Fragrance Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Ashland Global Holdings Inc., Evonik Industries AG, Akzo Nobel NV, Kao Commercial Co. Ltd., Brenntag Ingredients, BASF SE, Eastman Chemical Company, Union Intraco, Dow Inc., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Cosmetic Chemicals Market Strategic Shifts
Bio-fermentation and cold-process emulsification are compressing energy intensity in cosmetic chemical production while enabling novel active delivery formats that bypass traditional encapsulation.
Enzymatic esterification for emollient synthesis is electrifying process economics for medium-chain triglyceride derivatives. Indonesian and Thai formulators adopting cold-process methods reduce thermal degradation of heat-sensitive actives. This technology is electrifying capital allocation toward modular bioreactor installations versus conventional batch reactor expansion.
ASEAN Cosmetics Directive Annex II updates are forcing systematic paraben replacement across preservative portfolios. Thailand's FDA and Indonesia's BPOM enforce divergent transition timelines for banned isopropyl- and isobutylparaben variants. Preservative suppliers serving multi-country brand owners must maintain dual formulation libraries pending full harmonization.
Ingredient procurement from ASEAN-based distributors is replacing European direct-import relationships for mid-tier Vietnamese personal care manufacturers. Regional distributors now stock certified halal and COSMOS-compliant surfactant portfolios that previously required separate supply channels. This behavioral pivot concentrates most visibly in Ho Chi Minh City's emerging cosmetic manufacturing cluster.
ASEAN Cosmetic Chemicals Market Segmentation
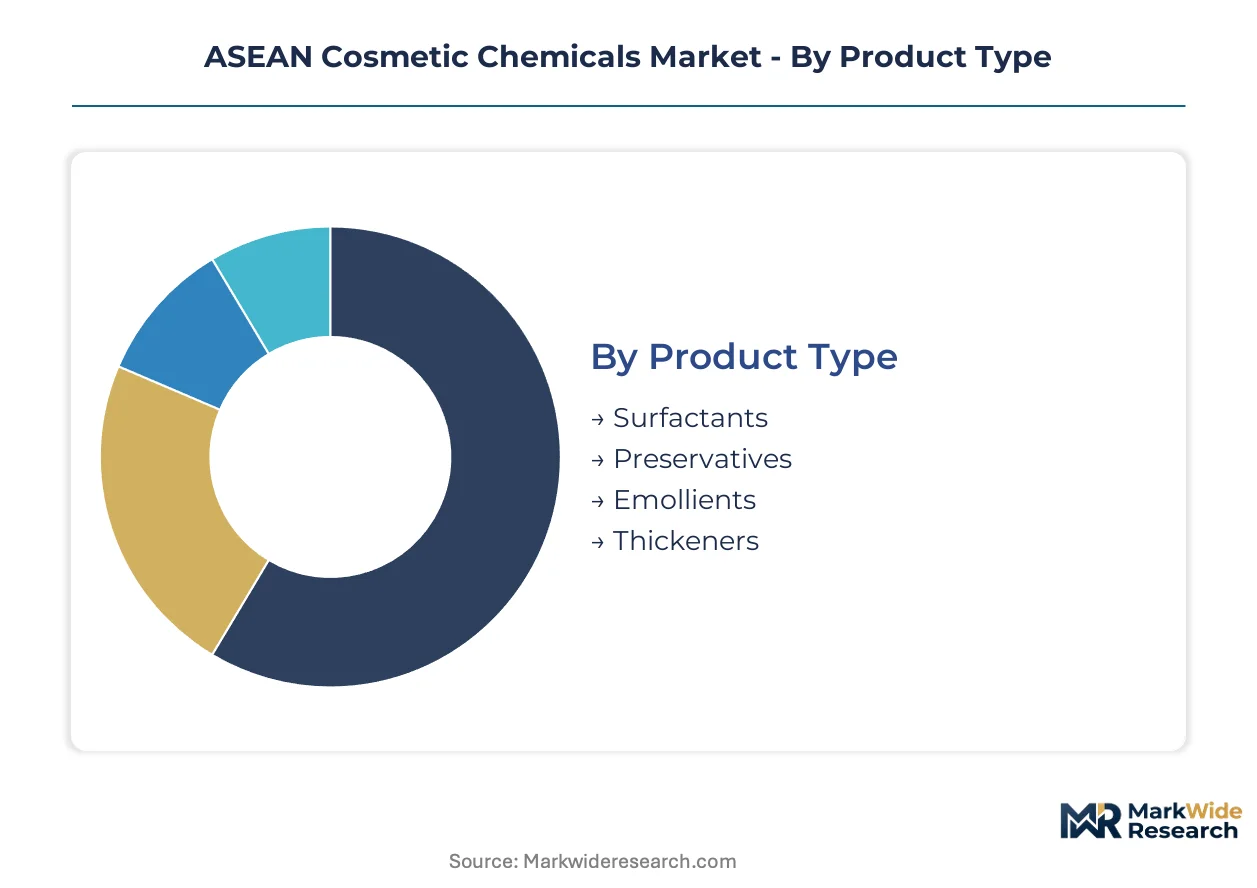
ASEAN cosmetic chemical procurement patterns diverge sharply across product function, formulation physics, and channel access. Buyers in Bangkok and Jakarta prioritize surfactant stability and preservative compliance over cost minimization, while Vietnamese indie brands optimize for cold-process compatibility.
Product Type:
Formulators select product types based on formulation stability requirements and regulatory clearance timelines across Thailand's FDA and Indonesia's BPOM.
- Surfactants:Surface-active agents with defined HLB values enable emulsion stability across cleansing formulations. Thai and Indonesian manufacturers concentrate procurement in anionic and amphoteric variants for sulfate-free shampoo lines. Surfactants lead on scale; emollients lead on momentum.
- Preservatives:Antimicrobial systems with specified MIC ranges against contamination. Divergent ASEAN Cosmetics Directive and national enforcement timelines force dual formulation libraries for paraben alternatives. Preservatives face compressed approval cycles in Vietnam versus Thailand.
- Emollients:Occlusive and humectant compounds for skin barrier function and sensorial texture. Silicone-free esters and plant-derived triglycerides are expanding most quickly in clean-label skincare.
- Thickeners:Rheology modifiers controlling dispensing and spreadability in haircare and cream bases. Xanthan gum and carbomer derivatives dominate Java-based manufacturing corridors.
Surfactants anchor volume procurement; emollients command the steepest expansion trajectory as premium skincare penetration deepens.
Formulation Type:
Processing temperature tolerance and active ingredient compatibility determine formulation platform selection for ASEAN contract manufacturers.
- Liquid:Pump-dispensed solutions and suspensions requiring low-viscosity surfactant systems. Thai formulators dominate liquid output for regional shampoo and body wash exports.
- Cream:Oil-in-water emulsions demanding precise HLB balancing and emollient integration. Cold-process emulsification adoption in Vietnam reduces thermal degradation of heat-sensitive actives.
- Gel:Transparent aqueous matrices stabilized by carbomer or cellulose-derived thickeners. Gel formats are gaining share fastest in men's grooming and acne treatment segments across the Philippines.
- Powder:Dry blends for loose makeup, bath additives, and dry shampoo applications. Powder processing concentrates in Indonesia's Java corridor for talc-alternative mineral formulations.
Cream formulations dominate current value; gel formats exhibit the sharpest demand acceleration.
End Use:
Category-specific performance standards—shelf stability for skincare versus rinse-off efficiency for haircare—shape ingredient specification intensity.
- Skincare:Anti-aging and clean-label formulations requiring preservative-light systems and barrier-repair emollients. Bangkok metropolitan manufacturers anchor regional skincare chemical demand.
- Haircare:Surfactant-dependent cleansing and conditioning with silicone replacement driving ester emollient adoption. Indonesian formulators lead sulfate-free conversion timelines.
- Makeup:Pigment dispersion and long-wear film-forming demand specialized thickeners and volatile silicones. Vietnamese color cosmetics manufacturing is expanding most quickly in Ho Chi Minh City clusters.
- Fragrance:Solubilization and fixative systems for alcohol-based and water-based scent delivery. Fragrance chemical procurement concentrates with Thai and Singaporean compounders serving luxury brands.
Skincare commands ingredient premiumization; makeup exhibits the fastest formulation innovation cycles.
Distribution Channel:
Channel selection determines lot size flexibility, certification documentation access, and technical service intensity for chemical buyers.
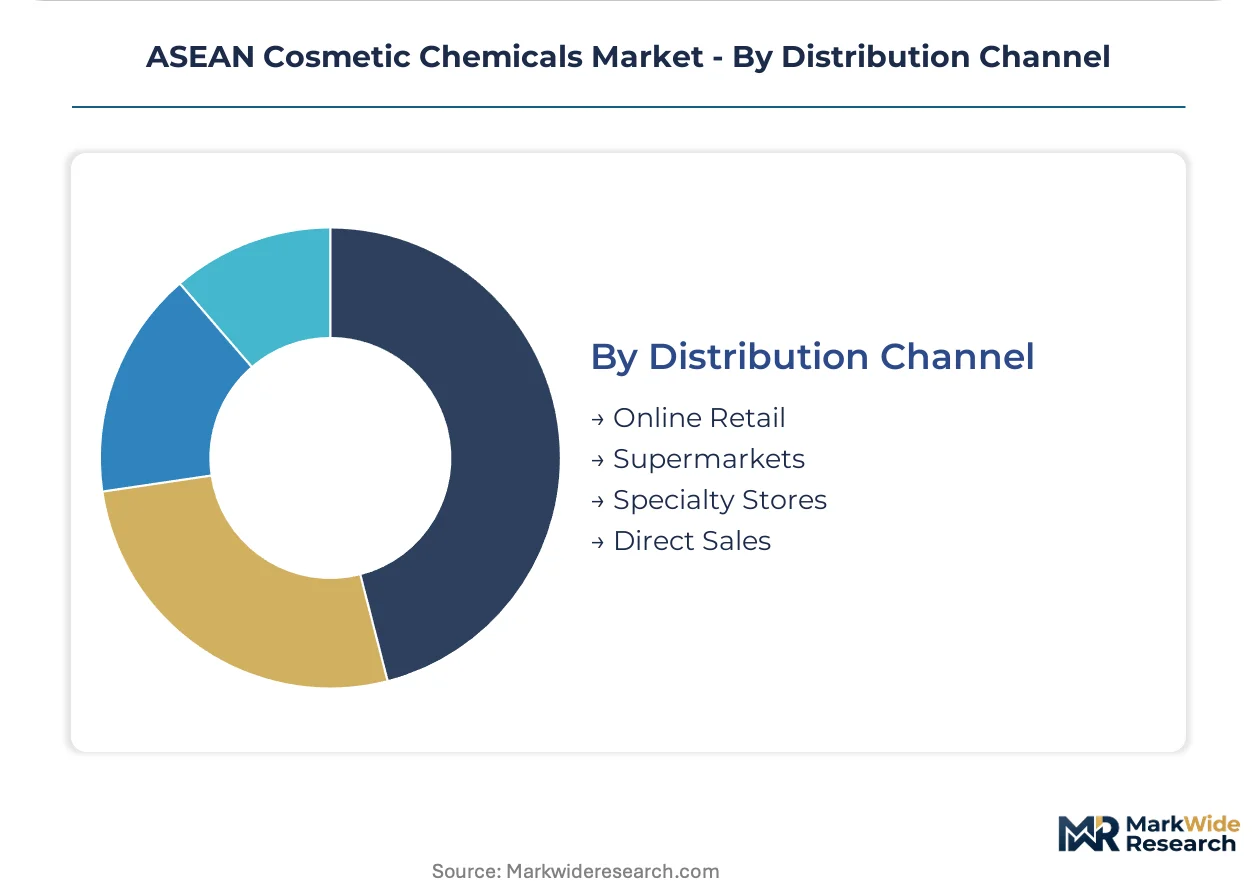
- Online Retail:E-commerce platforms enabling direct-to-formulator transactions with reduced minimum order quantities. Vietnamese indie brands bypass traditional importer networks through specialized chemical distributors.
- Supermarkets:Mass-market personal care brands sourcing through consolidated distributors with regional warehousing. Supermarket-linked procurement concentrates in Jakarta and Bangkok metropolitan zones.
- Specialty Stores:Premium and professional-grade channels demanding COSMOS-compliant and halal-certified ingredient portfolios. Specialty store supply chains are deepening fastest in Malaysia's JAKIM-certified corridors.
- Direct Sales:Manufacturer-direct relationships for large-volume formulators with dedicated technical service. Direct sales anchor surfactant and preservative procurement for Indonesian Java-based manufacturing clusters.
Direct sales dominate volume throughput; online retail channels show the steepest adoption curve among emerging formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cosmetic toxicologists and regulatory compliance specialists concentrate in Bangkok and Singapore, anchoring formulation advisory capacity across the ten-member bloc. This talent distribution shapes where ingredient suppliers locate technical service centers and regulatory filing operations.
Thailand
Premium skincare manufacturers in Bangkok's metropolitan cluster drive demand for silicone-free emollients and preservative-light systems. Thailand's FDA enforces extended safety assessment timelines that delay new ingredient commercialization. Contract manufacturers around Pathum Thani and Samut Prakan anchor regional exports of sulfate-free haircare formulations.
Indonesia
Java-based manufacturing corridors generate procurement economies for surfactant and preservative suppliers serving mass-market personal care brands. BPOM enforces national cosmetic registration with specific documentation requirements for paraben alternatives. Formulators in Bekasi and Tangerang industrial zones lead sulfate-free conversion timelines for domestic and export markets.
Vietnam
Urban consumers in Ho Chi Minh City and Hanoi prioritize clean-label skincare, pulling demand for specialty emollients and cold-process compatible ingredients. Vietnam's regulatory authorities enforce compressed approval cycles for cosmetic ingredients relative to Thai timelines. Emerging manufacturing clusters in Binh Duong province attract ingredient distributors offering direct-to-formulator e-commerce channels.
Philippines
Per-capita cosmetic consumption in secondary cities trails Bangkok and Jakarta by substantial margins, creating whitespace for mid-tier brand expansion. The country's national pharmaceutical and cosmetic regulator maintains registration requirements that align with broader ASEAN harmonization efforts. Manufacturing activity concentrates in Metro Manila and Cebu, with gel formats gaining share fastest in men's grooming segments.
Malaysia
JAKIM halal certification alignment with Indonesia's BPOM creates unified compliance pathways for Muslim-majority market access. The country's national cosmetic regulator enforces ASEAN Cosmetics Directive standards while maintaining specific halal certification protocols for ingredient suppliers. Port Klang and Shah Alam logistics corridors facilitate regional distribution of certified halal surfactant portfolios.
ASEAN Cosmetic Chemicals Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across ingredient categories, creating a tiered competitive structure. The market consolidates around integrated surfactant producers, specialty emollient developers, and regional distribution platforms. Three archetypes dominate: multinational chemical majors with integrated ASEAN supply chains, regional specialists in halal-certified or clean-label ingredients, and commodity surfactant traders serving Java-based manufacturing corridors. Capacity expansion and portfolio diversification toward silicone-free alternatives represent the dominant competitive moves.
Within the integrated chemical major tier, BASF SE and Evonik Industries AG exemplify divergent strategic positioning—BASF anchoring supply relationships through surfactant complex integration while Evonik differentiates via silicone-free emollient technologies. Kao Commercial Co. Ltd. occupies a distinct position through backward integration into fatty alcohol production, representing the captive supply archetype that regional competitors struggle to replicate. These three companies illustrate how scale, specialization, and vertical control define competitive advantage in ASEAN cosmetic chemical procurement.
| Leading Market Players |
|---|
| Ashland Global Holdings Inc. |
| Evonik Industries AG |
| Akzo Nobel NV |
| Kao Commercial Co. Ltd. |
| Brenntag Ingredients |
| BASF SE |
| Eastman Chemical Company |
| Union Intraco |
| Dow Inc. |
| Others |
Value Chain & Pricing Dynamics
Clean-label formulation mandates across Thailand's FDA and Indonesia's BPOM are compressing procurement timelines and forcing ingredient suppliers to absorb compliance costs or pass them through to mid-tier formulators. This specification tightening concentrates pricing power with distributors holding multi-country certification dossiers.
Pricing Analysis
Capacity additions in Vietnam's Binh Duong province are reshaping price floors for cold-process compatible emollients. Three-tier pricing structure across premium COSMOS-certified, standard ASEAN-compliant, and economy surfactant tiers anchors transaction structures. Cost compression in standard-tier surfactants is intensifying because Indonesian palm olein export policies feed fatty alcohol volatility. Mid-tier Thai formulators show highest price sensitivity; premium skincare brands in Bangkok exhibit lowest.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian-Indonesian palm olein corridors for fatty alcohol and surfactant feedstocks. Manufacturing draws from Thailand, Indonesia, and Vietnam for formulation output; raw materials hinge on palm derivatives, petrochemical ethoxylates, and fermentation-based actives. Tariff exposure on cross-border ASEAN chemical shipments creates margin unpredictability. Distribution runs through Jakarta and Bangkok metropolitan warehousing nodes with direct-to-formulator e-commerce emerging in Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN Cosmetic Chemicals procurement functions as a geographic-arbitrage play between Thailand's extended FDA safety assessment timelines and Vietnam's compressed approval cycles, rewarding suppliers with multi-country regulatory filing capabilities.
For Market Incumbents: Deepen backward integration into fatty alcohol production to neutralize palm olein volatility exposure. Anchor technical service capacity in Bangkok's toxicologist cluster while building parallel dossier libraries for divergent ASEAN Cosmetics Directive enforcement timelines across Thailand and Indonesia. For New Entrants and Emerging Players: Launch via direct-to-formulator e-commerce channels targeting Vietnamese indie beauty brands in Ho Chi Minh City. White-space concentrates in halal-certified preservative alternatives for Malaysia's JAKIM corridors and silicone-free emollient supply to Philippine secondary cities. For Investors and Strategic Acquirers: Asymmetric upside sits with regional distributors holding COSMOS and halal-certified portfolios across multiple ASEAN markets. Long-term viability favors acquisition targets with modular bioreactor installations enabling fermentation-based active production. Watch BPOM-Indonesia paraben transition enforcement as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Production | Kao Commercial's captive supply model demonstrates margin defense against palm olein volatility. |
| Halal Certification Convergence Investment | JAKIM-BPOM alignment creates unified compliance pathways for Muslim-majority market access. |
| Cold-Process Emulsification Capacity Buildout | Vietnamese formulators adopting cold-process methods reduce thermal degradation of heat-sensitive actives. |
| Direct-to-Formulator E-Commerce Launch | Specialty chemical distributors bypass traditional importer networks to serve Vietnamese indie beauty brands. |
| Multi-Country Regulatory Dossier Expansion | Suppliers maintaining parallel filing libraries capture share amid divergent Thai FDA and Indonesian BPOM timelines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered plant managers at Indonesian Java-based manufacturing corridors, procurement leads at Thai personal care formulators, distribution channel partners in Vietnam's Ho Chi Minh City cluster, and technical R&D directors at specialty emollient developers. Secondary validation drew from ASEAN Cosmetics Directive implementation documents, Thai FDA registration filings, Indonesian BPOM cosmetic notifications, and customs trade data for surfactant and fatty alcohol imports. Bottom-up volume estimates and top-down market sizing triangulated to anchor projections.
Segment-weighting applied product type, formulation physics, end-use category, and distribution channel dimensions across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating clean-label penetration rates, regulatory filing velocity differentials, and palm olein price covariance. Industry-specific inputs included sulfate-free shampoo conversion timelines and cold-process emulsification adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ASEAN Cosmetics Directive enforcement divergence or Malaysian-Indonesian palm export policy shocks. Forecasts reflect documented assumptions about regulatory harmonization velocity and biotechnology-derived active substitution rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
North America Jojoba Oil Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Shea Butter Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Cosmetic Based Preservatives Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
Global Skin Lightening Market
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
Eyelash Enhancing Agents Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Cosmetic Isoparaffins Market
Cosmetic Chemicals
Cosmetics Contract Manufacturing Market
Cosmetic Chemicals
Emollients Market