
 Marine Fuel Additives Market | 2026-2036
Marine Fuel Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Fuel Additives Market Outlook
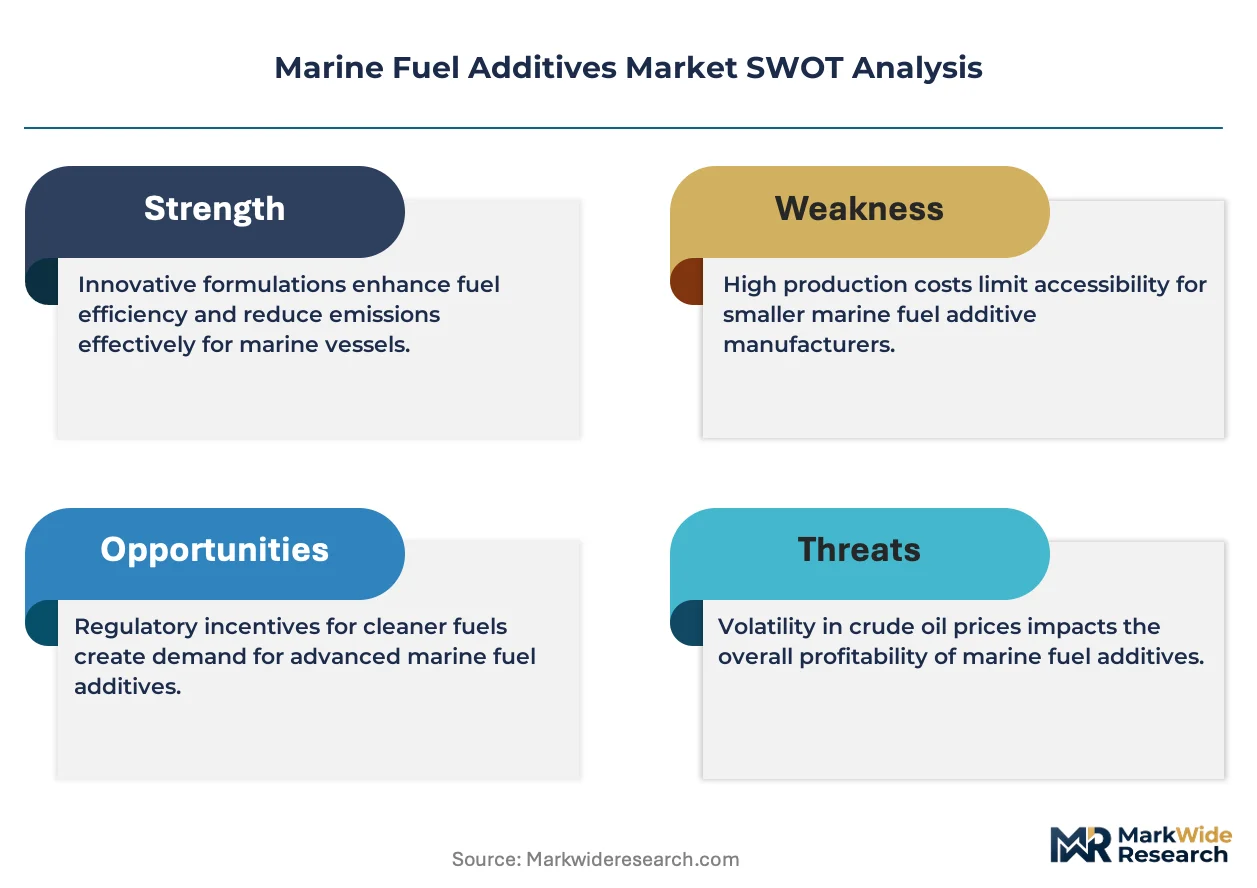
IMO 2020-compliant additive grades is rotating toward higher-specification detergent and stabilizer packages as vessel operators confront cat fine precipitation and storage stability failures in very low sulfur fuel oil. BASF SE leverages its Ludwigshafen-based integrated surfactant complex to supply detergent precursors at scale. Afton Chemical Corporation anchors its position through specialized cold-flow improver technology for paraffinic distillate blends. Innospec, Inc. differentiates via proprietary phenolic antioxidant systems that extend fuel storage life in tropical bunkering terminals.
Marine fuel additives comprise chemical formulations—typically organometallic detergents, ashless dispersants, biocidal agents, and combustion catalysts—dosed at 50 to 5000 parts per million to modify fuel stability, cleanliness, and emissions profiles during heavy fuel oil or distillate combustion in two-stroke marine diesel engines. The product-type dimension shows biocides capturing expanding share as microbial contamination proliferates in longer-stored low-sulfur fuels, while lubricity improvers face margin compression from base-fuel hydrotreating advances that already enhance natural lubricity. Technology segmentation reveals low-sulfur-compatible additive systems leading absolute volume, though emulsification technologies for water-in-fuel combustion gain traction in offshore platform power generation where NOx reduction carries operational priority.
The International Maritime Organization enforces MARPOL Annex VI sulfur caps that directly determine additive demand intensity by fuel category and operating zone. EPA and EU MRV frameworks compound this effect by tightening greenhouse gas monitoring and verification obligations that incentivize combustion-efficiency additives. Stakeholders must monitor how the IMO's carbon intensity indicator and forthcoming well-to-wake lifecycle standards reshape additive specification requirements across commercial shipping fleets.
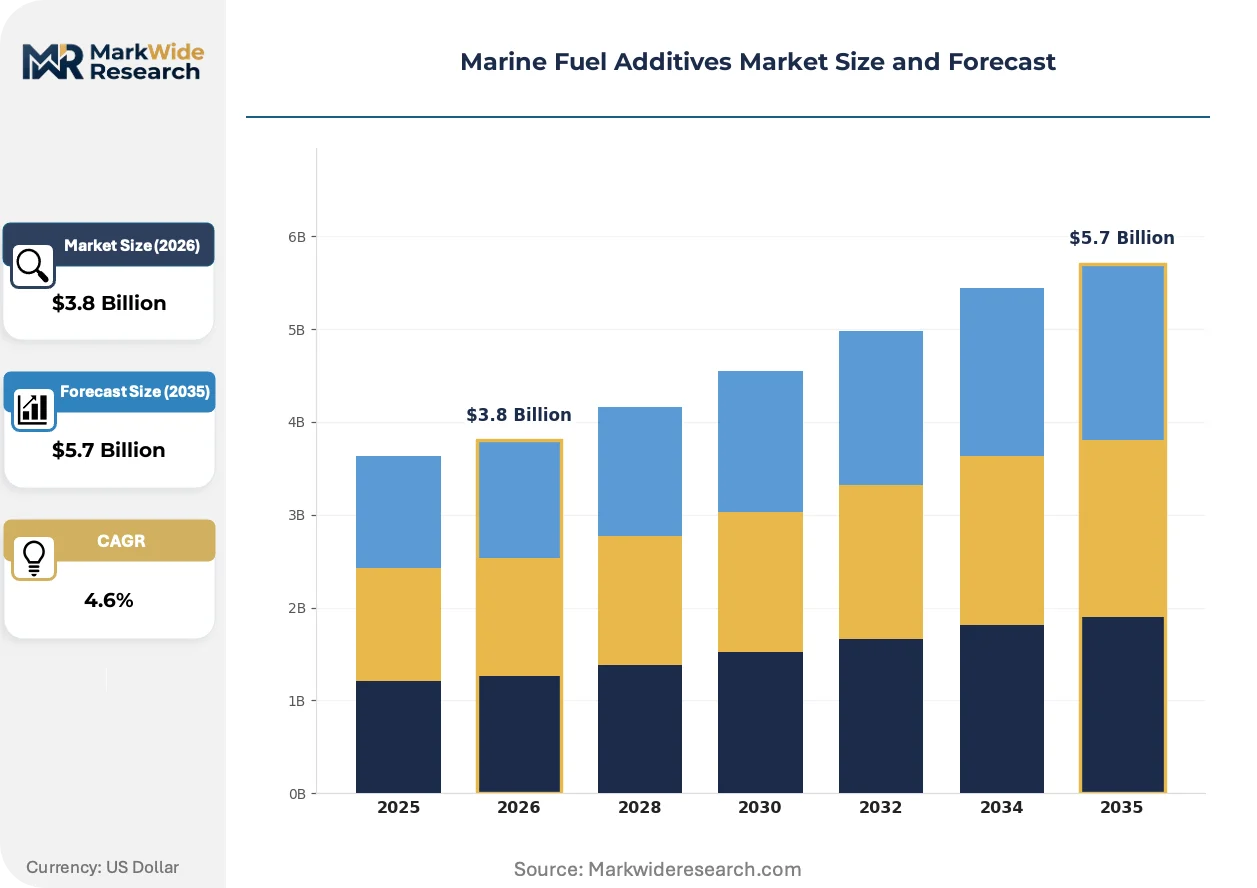
Market Dynamics
IMO 2020 sulfur caps have permanently altered marine fuel formulation requirements, forcing vessel operators to treat additive packages as essential compliance infrastructure rather than discretionary performance enhancers. The shift from high-sulfur residual fuels to very low sulfur fuel oil has introduced new operational risks—cat fine precipitation, microbial contamination, and storage instability—that only specialized chemical additives can mitigate.
Growth Catalysts
- MARPOL Annex VI enforcement:The International Maritime Organization's sulfur cap regulations mandate additive use for compliant fuel combustion across emission control areas, creating non-negotiable demand for detergent and stabilizer formulations.
- Microbial contamination in low-sulfur fuels:Extended storage periods for compliant distillates accelerate biocide demand, particularly in tropical bunkering terminals where bacterial growth degrades fuel quality.
- Container shipping procurement expansion:Major lines are consolidating additive purchasing through long-term supply agreements with integrated chemical suppliers, locking in volume commitments that stabilize manufacturer capacity utilization.
Market Restraints
- Base oil hydrotreating advances:Refinery investments in hydrocracking and hydrotreating units enhance natural lubricity of marine gasoil, compressing demand for supplemental lubricity improvers in distillate applications.
- Feedstock cost volatility:Organometallic detergent precursors rely on specialized surfactant feedstocks whose pricing tracks petrochemical complex margins, squeezing additive blender margins during crude price spikes.
- Singapore supply concentration:Over 60% of Asia-Pacific marine additive blending capacity sits within the Singapore-Jurong Island cluster, exposing procurement chains to single-point geographic risk.
Strategic Opportunities
- EU MRV and carbon intensity frameworks:The European Union's Monitoring, Reporting and Verification regulation and impending FuelEU Maritime standards incentivize combustion-efficiency additives that demonstrably reduce CO2 emissions per nautical mile.
- Water-in-fuel emulsification for offshore power:Offshore platform operators are adopting emulsified fuel systems for NOx reduction in stationary power generation, opening a specialized application segment distinct from commercial shipping.
- India port infrastructure expansion:Jawaharlal Nehru Port and Mundra Port are developing dedicated low-sulfur bunkering facilities, creating first-mover advantage for additive suppliers establishing local technical service presence.
Industry Challenges
- Formulation chemist scarcity:The specialized knowledge required to design low-sulfur-compatible additive packages—combining surfactant chemistry, fuel stability science, and marine engine combustion dynamics—resides with a shrinking cohort of experienced practitioners.
- IMO well-to-wake certification timelines:Pending lifecycle carbon standards will require additive manufacturers to document supply chain emissions and demonstrate net carbon benefit, demanding new analytical capabilities and third-party verification partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Fuel Additives Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stabilizers, Biocides, Detergents, Lubricants End User: Shipping Companies, Fisheries, Oil Refineries, Cargo Operators Application: Commercial Shipping, Fishing Vessels, Naval Ships, Offshore Platforms Technology: High-Density, Low-Sulfur, Drop-in, Emulsification |
| Companies Covered | Chevron Corporation, BASF SE, Lubrizol Corporation, Afton Chemical Corporation, Infineum International Limited, Baker Hughes Company, Innospec, Inc., TotalEnergies SE, Dorf Ketal Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Fuel Additives Market Strategic Shifts
Digital fuel quality monitoring and predictive dosing systems are transforming how vessel operators manage additive consumption, shifting from fixed-ratio treatment to condition-based optimization. This technological infusion is compressing traditional supply relationships and demanding new service capabilities from chemical suppliers.
Phenolic antioxidant systems optimized for tropical storage conditions are supplanting conventional hindered phenol formulations in major bunkering hubs. Singapore-based storage terminal operators are specifying these advanced stabilizers for fuel held beyond 30 days. The technology is enabling additive suppliers to capture premium pricing for storage-life extension guarantees that conventional chemistry cannot match.
EPA enforcement of the Act to Prevent Pollution from Ships is tightening documentation requirements for fuel oil non-availability reports in United States waters. Vessel operators must now demonstrate genuine attempts to source compliant fuel before claiming exemptions, which increases additive procurement discipline and reduces spot-market variability in North American ports. Container lines serving trans-Pacific routes are responding by pre-positioning additive inventories at Los Angeles and Long Beach.
Long-term supply agreements with fixed technical service components are displacing spot purchasing through bunker traders for large fleet operators. Major container shipping alliances are consolidating additive procurement through direct manufacturer relationships, stripping intermediaries of volume and margin. This consolidation is most visible among Asia-Europe trade lane operators headquartered in Copenhagen and Hamburg.
Marine Fuel Additives Market Segmentation
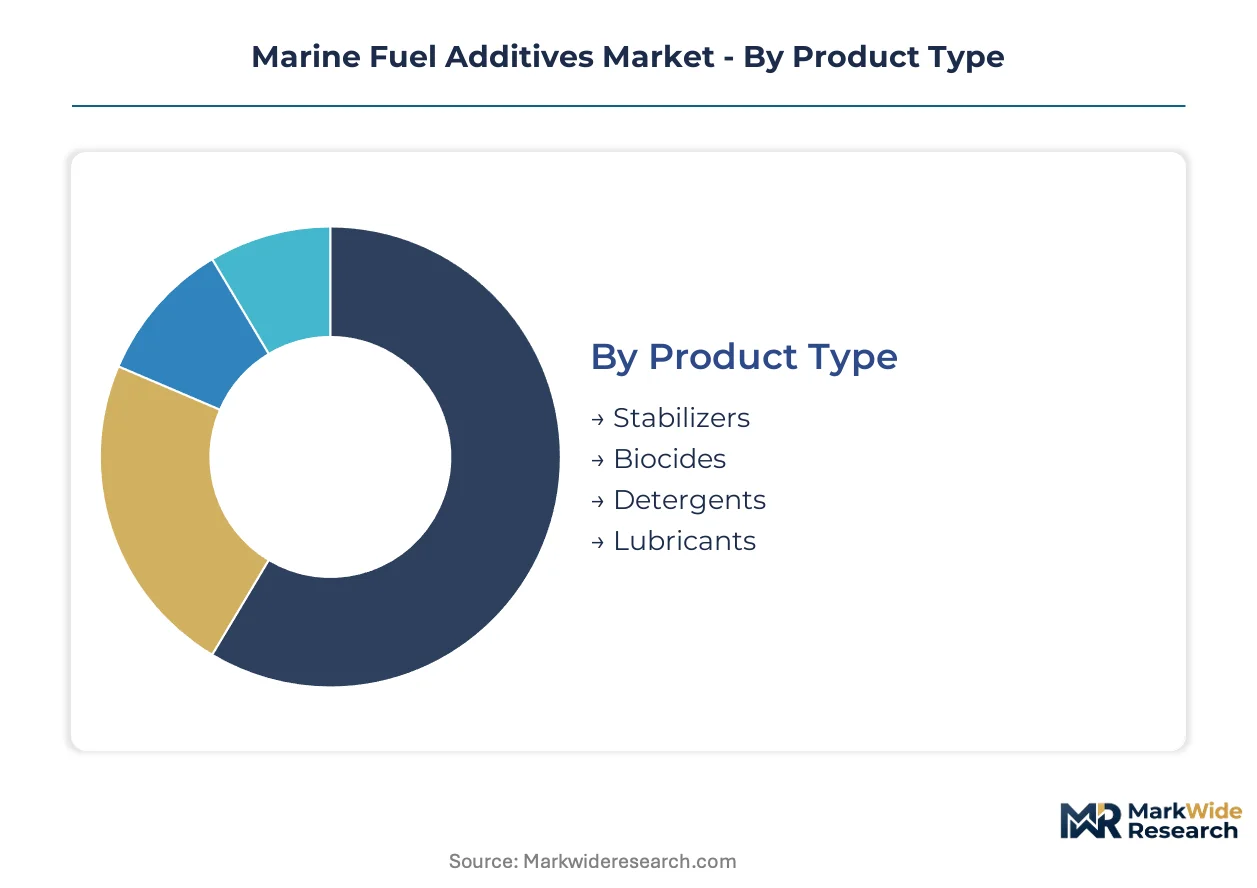
Marine fuel additive procurement varies sharply by operational intensity and regulatory exposure, with vessel type and fuel sulfur specification driving formulation selection. Understanding these segment boundaries clarifies where suppliers can capture premium pricing versus commodity volume plays.
Product Type:
Margin pools concentrate in specialty biocide and stabilizer formulations where technical differentiation commands price premiums, while detergent and lubricant segments face greater commoditization pressure from integrated refinery supply.
- Stabilizers:Phenolic antioxidant systems prevent fuel oxidation and polymerization during extended tropical storage. Singapore terminal operators specify these for fuel held beyond 30 days, with demand intensifying as low-sulfur distillates degrade faster than legacy high-sulfur residual fuels.
- Biocides:Microbial contamination proliferates in water-bottom interfaces of longer-stored compliant fuels, accelerating demand for isothiazolinone and quaternary ammonium formulations. Tropical bunkering terminals in Fujairah and Singapore drive procurement volume as bacterial growth degrades fuel quality and corrodes storage tanks.
- Detergents:Organometallic surfactant packages disperse cat fines and combustion deposits in very low sulfur fuel oil systems.
- Lubricants:Lubricity improvers face margin compression from refinery hydrotreating advances that enhance natural lubricity of marine gasoil.
Stabilizers hold installed capacity. Biocides is rotating up the share rankings.
End User:
Procurement scale and technical sophistication diverge dramatically across customer types, with container lines consolidating volume through direct manufacturer relationships while fragmented fishing fleets rely on spot bunker trader channels.
- Shipping Companies:Major container alliances headquartered in Copenhagen and Hamburg are locking in additive procurement through long-term supply agreements with integrated chemical suppliers, stripping intermediaries of volume and margin. These operators pre-position additive inventories at Los Angeles, Long Beach, and Rotterdam to ensure compliance across trans-Pacific and Asia-Europe trade lanes.
- Cargo Operators:Bulk and tanker fleets face intermittent voyage patterns that complicate fixed-ratio dosing, driving interest in condition-based optimization systems. Digital fuel quality monitoring enables these operators to shift from preventive to predictive additive consumption, compressing traditional supply relationships.
- Fisheries:Small-scale vessel operators in dispersed ports purchase through local bunker traders with limited technical service support.
- Oil Refineries:Integrated refiners with marine fuel blending operations source additive packages for captive supply to affiliated bunkering terminals.
Shipping companies hold installed capacity. Cargo operators is rotating up the share rankings.
Application:
Operational environment determines additive specification intensity, with stationary power generation and continuous commercial operations presenting contrasting technical requirements and procurement economics.
- Commercial Shipping:Two-stroke marine diesel engines burning very low sulfur fuel oil require comprehensive detergent, stabilizer, and biocide packages to manage cat fine precipitation, storage instability, and microbial contamination. Container lines serving emission control areas face the strictest dosing discipline under MARPOL Annex VI enforcement.
- Offshore Platforms:Stationary power generation applications are adopting water-in-fuel emulsification systems for NOx reduction, opening a specialized segment distinct from commercial shipping with distinct combustion-efficiency priorities.
- Naval Ships:Military fleets operate under separate procurement protocols with classified performance specifications and national security supply requirements.
- Fishing Vessels:Seasonal operations and smaller fuel tanks reduce storage stability risks but increase cold-flow challenges in high-latitude fisheries.
Commercial shipping holds installed capacity. Offshore platforms is rotating up the share rankings.
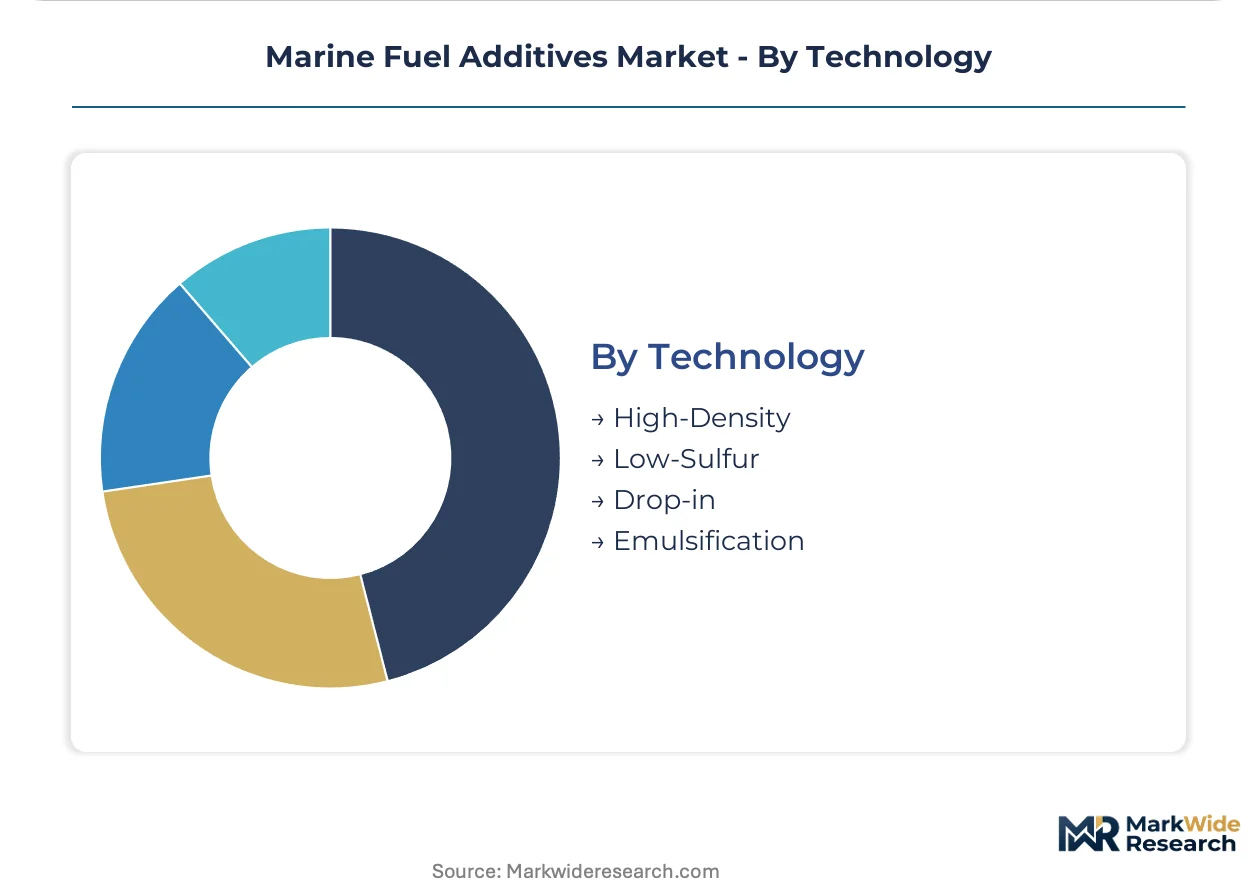
Technology:
Regulatory compliance trajectories are forcing rapid obsolescence of legacy additive systems, with low-sulfur-compatible formulations capturing absolute volume while emulsification technologies gain traction in specialized stationary applications.
- Low-Sulfur:Compatible additive systems combine ashless dispersants, phenolic antioxidants, and organometallic detergents specifically formulated for very low sulfur fuel oil combustion. These systems address the operational risks—cat fine precipitation, microbial contamination, and storage instability—that emerged from the IMO 2020 transition.
- Emulsification:Water-in-fuel emulsion technologies enable NOx reduction in offshore platform power generation where combustion efficiency carries operational priority distinct from mobile marine applications. The technology requires specialized surfactant packages and mechanical homogenization equipment.
- High-Density:Concentrated additive formulations reduce logistics costs for remote bunkering operations with limited storage infrastructure.
- Drop-in:Universal compatibility claims appeal to multi-fuel fleets seeking procurement simplification, though performance trade-offs exist against purpose-formulated systems.
Low-sulfur holds installed capacity. Emulsification is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net additive exports from integrated chemical complexes in Germany and the United States flow toward deficit bunkering hubs in Singapore and Fujairah, creating trade imbalances that concentrate formulation expertise in source markets while demand concentrates at major marine fueling nodes.
Singapore
Jurong Island houses over sixty percent of Asia-Pacific marine additive blending capacity, with terminal operators specifying phenolic antioxidant systems for low-sulfur fuel held beyond thirty days. The Maritime and Port Authority enforces strict fuel quality standards that mandate additive documentation. Container lines pre-position inventories at Singapore to ensure compliance across Asia-Europe trade lanes.
United States
Gulf Coast petrochemical complexes supply organometallic detergent precursors to domestic blenders serving Los Angeles and Long Beach. The EPA enforces Act to Prevent Pollution from Ships documentation requirements that tighten additive procurement discipline. Houston-area integrated suppliers anchor supply relationships with trans-Pacific container operators.
Germany
Ludwigshafen's surfactant complex feeds detergent precursor production for European marine additive formulation. The EU MRV framework and impending FuelEU Maritime standards incentivize combustion-efficiency additive development. Hamburg-based container alliances consolidate procurement through direct manufacturer relationships, stripping intermediaries of volume.
United Arab Emirates
Fujairah's bunkering terminals drive biocide demand as microbial contamination proliferates in longer-stored low-sulfur fuels stored in tropical conditions. The country's national petroleum regulator aligns port authority standards with MARPOL Annex VI enforcement. Local terminal operators are upgrading storage infrastructure to handle compliant fuel grades requiring specialized stabilizer packages.
Netherlands
Rotterdam's status as Europe's largest bunkering port drives formulation upgrades for very low sulfur fuel oil compliance. The port authority coordinates with EU maritime regulators on greenhouse gas monitoring obligations that affect additive specification. Integrated chemical suppliers maintain technical service presence to support vessel operators in emission control areas.
Marine Fuel Additives Market Competitive Environment
Listed leaders compete with private specialists across integrated chemical supply, with publicly traded energy majors and diversified chemical conglomerates holding scale advantages in surfactant precursor production while private additive specialists retain technical agility in formulation customization. The market structure tiers into three strategic archetypes: integrated petrochemical suppliers with captive raw material access, specialized fuel additive formulators with deep combustion chemistry expertise, and energy majors with vertical control over bunkering terminal networks. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players seek to secure long-term supply agreements with consolidating container shipping alliances.
Among integrated chemical suppliers, BASF SE anchors the surfactant precursor tier through its Ludwigshafen-based manufacturing complex, while Afton Chemical Corporation exemplifies specialized formulation expertise with dedicated marine additive development capabilities. Innospec, Inc. occupies a position within the performance chemicals segment, representing the private specialist archetype focused on proprietary antioxidant systems. These three companies illustrate the competitive spectrum from upstream chemical integration through downstream formulation specialization.
| Leading Market Players |
|---|
| Chevron Corporation |
| BASF SE |
| Lubrizol Corporation |
| Afton Chemical Corporation |
| Infineum International Limited |
| Baker Hughes Company |
| Innospec, Inc. |
| TotalEnergies SE |
| Dorf Ketal Chemicals |
| Others |
Value Chain & Pricing Dynamics
Long-term supply agreements with fixed technical service components lock in additive access for container shipping alliances while providing price visibility across volatile petrochemical feedstock cycles. These contracts tie detergent and stabilizer procurement to MARPOL Annex VI compliance milestones, embedding regulatory enforcement directly into pricing structures.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in marine fuel additives. Container lines with direct manufacturer relationships capture standard-tier economics through volume commitments, while spot purchasers at Fujairah and Singapore terminals face premium pricing for biocide and stabilizer formulations. Price differentiation hinges on certification grade under EPA and EU MRV frameworks plus geographic delivery cost to bunkering hubs. Cost compression in lubricity improvers is intensifying because refinery hydrotreating advances enhance natural marine gasoil lubricity. Small-scale fishing fleets and dispersed cargo operators exhibit highest price sensitivity due to fragmented purchasing power and limited technical service leverage.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for surfactant precursors moving from Ludwigshafen and Houston to Singapore-Jurong Island blending facilities. Formulation expertise concentrates in Germany, the United States, and Singapore, while raw material dependencies rest on organometallic detergent precursors, phenolic antioxidant feedstocks, and isothiazolinone biocide intermediates. Single-source vulnerability permeates the Singapore-Jurong Island cluster where over sixty percent of Asia-Pacific blending capacity sits. Distribution runs through integrated chemical suppliers with captive terminal access and direct vessel operator relationships, displacing traditional bunker trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialized combustion chemistry and fuel stability science required for IMO 2020-compliant additive design resides with a shrinking cohort of experienced practitioners, creating persistent capability gaps that reshape competitive positioning across formulation, technical service, and regulatory documentation layers.
For Market Incumbents: Fortify technical service presence at emerging bunkering hubs in India and the UAE to preempt new entrant access. Deepen backward integration into surfactant precursor production at Ludwigshafen-scale complexes to defend margin position against feedstock volatility. Lock in long-term supply agreements with consolidating Copenhagen and Hamburg-based container alliances before competitor capacity additions materialize. For New Entrants and Emerging Players: Technical service gaps in India's Jawaharlal Nehru Port and Mundra Port bunkering infrastructure present first-mover territory for specialized biocide and stabilizer suppliers. Target condition-based optimization systems for fragmented bulk and tanker fleets where intermittent voyage patterns complicate fixed-ratio dosing. Deploy digital fuel quality monitoring platforms as the go-to-market wedge to bypass entrenched supply relationships. For Investors and Strategic Acquirers: Capital is best deployed toward specialized additive formulators with proprietary phenolic antioxidant or cold-flow improver technology and established EPA documentation capabilities. The five-to-ten year viability window favors assets with demonstrated EU MRV compliance pathways and pending FuelEU Maritime certification traction. Watch for IMO well-to-wake lifecycle standard finalization as the inflection signal requiring supply chain emissions documentation and third-party verification partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Precursors | BASF's Ludwigshafen complex demonstrates how captive detergent feedstock supply insulates margins from petrochemical volatility. |
| Long-term Supply Agreement with Container Alliances | Direct manufacturer relationships with Copenhagen and Hamburg-based operators strip bunker traders of volume and stabilize capacity utilization. |
| Technical Service Expansion at Emerging Hubs | Local presence at India's Mundra Port captures first-mover advantage as dedicated low-sulfur bunkering facilities develop. |
| Digital Fuel Quality Monitoring Platform Launch | Predictive dosing systems enable condition-based optimization that compresses traditional fixed-ratio supply relationships. |
| EU MRV and FuelEU Maritime Certification Investment | Demonstrable CO2 reduction per nautical mile positions combustion-efficiency additives for premium pricing under impending carbon intensity frameworks. |
Study Parameters
Operator-level perspectives from vessel engineering officers, bunkering terminal managers, additive formulation chemists, and marine fuel procurement leads anchored the qualitative base for this study. Primary interviews across Singapore, Rotterdam, and Houston supply clusters combined with secondary validation from MARPOL Annex VI enforcement records, EPA Act to Prevent Pollution from Ships documentation, EU MRV emissions databases, and customs trade data for organometallic surfactant feedstocks. Bottom-up triangulation across product-type demand estimates and top-down reconciliation against bunkering port throughput statistics ensured cross-verified volume outputs.
Sensitivity analysis across sulfur specification scenarios, regulatory enforcement intensity variations, and feedstock cost volatility bands shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-user category, application environment, and technology compatibility tier alongside vessel size class and trade lane exposure. CAGRs derived from regression analysis against historical additive intensity per ton of marine fuel consumed incorporate IMO carbon intensity indicator adoption curves and well-to-wake certification timeline assumptions.
Underlying assumptions cover MARPOL Annex VI enforcement continuity, low-sulfur fuel oil storage stability degradation rates, and surfactant precursor supply elasticity, with deviation risk concentrated in IMO regulatory timeline acceleration or refinery hydrotreating technology leaps. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Viscosity Reducing Agents Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Calcium Stearate Market
Additives
Tamarind Gum Derivatives Market
Additives
Encapsulated Citric Acid Market
Additives
Biosaccharide Gum Market
Additives
Asia-Pacific Fuel Additives Market
Additives
Rosin Ester Market
Additives
Fluoropolymer Additives Market
Additives
Global Cement Additives Market
Additives
Global Slip Additives Market
Additives
Combustion Clean-Up Additives for High-Mileage Fleets Market
Additives
Global Peptone Market
Additives
Plastic Fillers Market
Additives
Global Feed Acidulants Market
Additives
Polymeric Plasticizer Market