
 Spiroglycol Market | 2026-2036
Spiroglycol Market Size, Share, and Industry Trends Forecast 2026-2036
Spiroglycol Market Analytics
Asset-light contract manufacturing and third-party tolling arrangements is fragmenting competitive dynamics among spiroglycol producers. BASF SE leverages backward integration into raw acetaldehyde streams to protect margin pools. Mitsubishi Chemical Corporation anchors its position through captive supply of high-purity grades for pharmaceutical customers. Tianhua Pharmaceutical competes on cost-adjusted output from integrated chlor-alkali complexes in eastern China.
Spiroglycol denotes a class of bicyclic diols featuring two fused tetrahydrofuran rings linked through a shared quaternary carbon, typically synthesized via acid-catalyzed cyclization of pentaerythritol derivatives with aldehydes at controlled temperature and pressure. The compound functions primarily as a rigid structural modifier in polyester and alkyd resins, conferring enhanced thermal stability, reduced hygroscopicity, and improved optical clarity in coatings and specialty polymers. Di-substituted variants command the dominant share of formulation demand owing to their balanced reactivity profile and compatibility with standard condensation chemistries. Liquid formulation types are gaining traction in continuous-process pharmaceutical manufacturing lines where metered dosing precision outweighs solid-handling economies. Direct sales channels capture the bulk of value in pharmaceutical and agrochemical end-use segments where lot-traceability and certificate-of-analysis documentation are non-negotiable.
REACH registration requirements under ECHA mandate full toxicological dossiers for spiroglycol imports above one tonne annually into the European Union, elevating compliance costs for non-European producers. EPA New Chemicals Program notifications in the United States impose pre-manufacture review on novel spiroglycol analogues, slowing product pipeline velocity for innovators. FDA Type II drug master file expectations for excipient-grade spiroglycol tighten residual solvent specifications, pushing suppliers toward dedicated pharmaceutical-grade production assets. Stakeholders must calibrate capital allocation between regulatory-compliant capacity expansion and speculative R&D on next-generation substituted variants before competitor filings harden market access barriers.
Market Dynamics
Specialty chemical producers face mounting pressure from pharmaceutical-grade purity mandates that now exceed standard industrial specifications, forcing capital reallocation toward dedicated production assets and segregated supply chains.
Growth Catalysts
- India's PLI scheme for API manufacturing:Domestic production incentives are drawing multinational pharmaceutical formulators to establish captive spiroglycol offtake agreements with local chemical parks.
- Continuous-flow pharmaceutical processing:Liquid spiroglycol grades enable precise metered dosing in automated manufacturing lines, displacing batch-oriented solid handling systems.
- REACH registration thresholds:ECHA's one-tonne annual import trigger has elevated compliance investment barriers, advantaging incumbent European producers with established toxicological dossiers.
Market Restraints
- Acetaldehyde feedstock volatility:Crude oil price swings transmit directly into pentaerythritol derivative costs, compressing margin predictability for non-integrated manufacturers.
- Eastern China supply concentration:Chlor-alkali integrated complexes in Shandong and Jiangsu provinces control bulk industrial-grade output, creating geographic single-point vulnerability.
- Di-substituted variant lock-in:Formulation chemistries optimized around standard spiroglycol architectures resist substitution by novel bicyclic diols without complete resin reformulation.
Strategic Opportunities
- Underpenetrated Brazilian agrochemical sector:ANVISA registration pathways for excipient-grade materials remain underutilized by specialty chemical exporters.
- Optical clarity coatings for electronics:Display panel manufacturers in South Korea are qualifying spiroglycol-modified polyesters for flexible substrate applications.
- EU Green Deal sustainable chemistry incentives:Bio-based acetaldehyde feedstock certification opens preferential procurement channels for European automotive coating formulators.
Industry Challenges
- Pharmaceutical-grade validation timelines:FDA Type II drug master file preparation requires 18-24 month certification cycles that strain working capital for mid-scale producers.
- Residual solvent detection capabilities:Gas chromatography method development for parts-per-billion specification compliance demands specialized analytical chemistry talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spiroglycol Market |
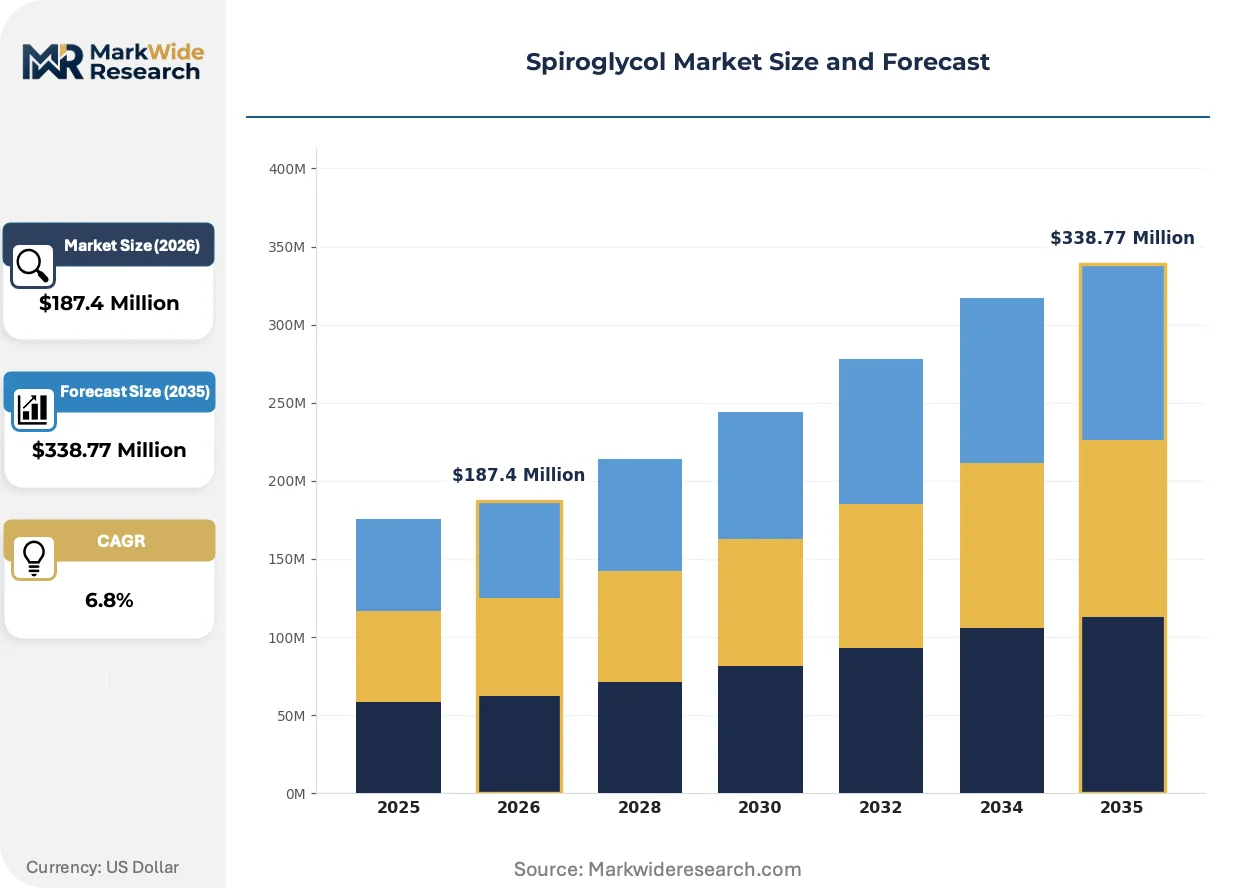
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono-substituted, Di-substituted, Tri-substituted, Tetra-substituted End Use Industry: Personal Care, Pharmaceuticals, Food & Beverages, Agrochemicals Formulation Type: Liquid, Solid, Emulsion, Gel Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, MGC, Tianhua Pharmaceutical, SHANGHAI SYNFARM, Solvay S.A., Dow Chemical Company, Eastman Chemical Company, Mitsubishi Chemical Corporation, LG Chem Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spiroglycol Market Evolving Landscape
Process intensification and regulatory harmonization are converging to redefine production economics and market access protocols across pharmaceutical and coatings end-uses.
Continuous catalytic cyclization technology is migrating from pilot-scale demonstration units to commercial pharmaceutical-grade installations. BASF SE and Mitsubishi Chemical Corporation have commissioned flow-reactor systems that eliminate batch-to-batch variability in quaternary carbon formation. This technology compression is enabling real-time quality assurance that satisfies FDA residual solvent specifications without offline testing delays.
REACH registration dossier requirements under ECHA now mandate extended one-generation reproductive toxicity studies for spiroglycol imports exceeding ten tonnes annually. Industrial chemical traders without in-house toxicology capabilities are exiting the European market, consolidating import channels through specialized regulatory consultancies. Pharmaceutical-grade suppliers with pre-submitted dossiers are capturing displaced industrial volume at premium certification spreads.
Certificate-of-analysis documentation has become the decisive procurement criterion for Indian API manufacturers operating under CDSCO export licensing. Direct sales relationships with dedicated quality assurance personnel are displacing distributor-mediated transactions in pharmaceutical end-uses. This channel compression is most visible in Hyderabad and Ahmedabad chemical clusters, where formulators now require lot-traceable supply chains for PLI scheme compliance audits.
Spiroglycol Market Segmentation
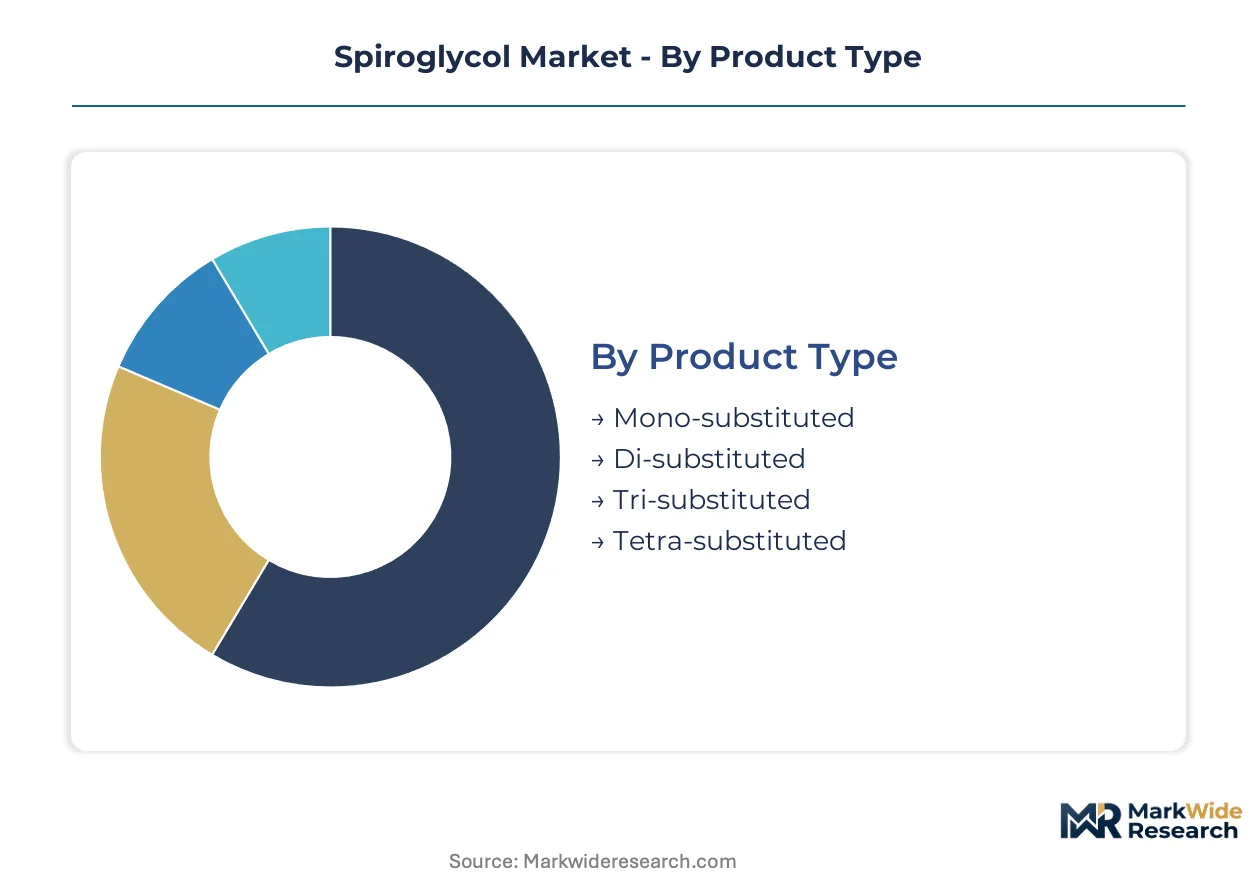
Spiroglycol's molecular architecture enables substitution patterns that align with distinct performance requirements across pharmaceutical synthesis and polymer modification. Segmentation by substitution degree, formulation state, and supply channel reveals where margin pools concentrate and where regulatory barriers reshape competitive access.
Product Type:
Substitution density governs reactivity profiles and thermal stability thresholds across polyester resin and API intermediate applications.
- Di-substituted:The balanced steric configuration delivers optimal compatibility with standard condensation polymerization chemistries. Pharmaceutical formulators in India and coating manufacturers in Germany specify this grade for its predictable viscosity response and minimal batch-to-batch deviation under PLI scheme and REACH compliance frameworks.
- Mono-substituted:Lower substitution density permits greater molecular flexibility in alkyd resin modification. Demand clusters in automotive refinish coatings where enhanced flow characteristics outweigh absolute thermal resistance.
- Tri-substituted:Elevated steric bulk serves specialized optical polymer applications requiring extreme dimensional stability under thermal cycling.
- Tetra-substituted:Maximum substitution creates ultra-rigid backbone structures for high-performance electronics substrates.
The dominant share belongs to Di-substituted variants, while Liquid formulations in continuous-process pharmaceutical lines are closing the gap fastest.
End Use Industry:
Regulatory stringency and purity premiums fragment addressable value pools across consumer-facing and industrial applications.
- Pharmaceuticals:Excipient-grade specifications demand residual solvent thresholds below 10 parts per billion. CDSCO export licensing requirements in India and FDA Type II drug master file protocols in the United States enforce certificate-of-analysis documentation that eliminates distributor-mediated procurement.
- Agrochemicals:Formulation stability under field storage conditions drives demand for hydrophobic spiroglycol derivatives. ANVISA registration pathways in Brazil remain underpenetrated by specialty chemical exporters.
- Personal Care:Cosmetic-grade purity mandates focus on heavy metal content and microbial contamination limits rather than residual solvents.
- Food & Beverages:Migration testing protocols under EFSA and FDA food contact regulations restrict approved substitution patterns.
Pharmaceuticals commands the largest value share, though Agrochemicals in Brazil and Southeast Asia shows the steepest expansion trajectory.
Formulation Type:
Physical state determines handling economics and dosing precision in automated versus batch manufacturing environments.
- Liquid:Metered pump compatibility eliminates solid-handling infrastructure and enables real-time quality adjustment in continuous-flow reactors. BASF SE and Mitsubishi Chemical Corporation have commissioned dedicated pharmaceutical-grade liquid production assets.
- Solid:Crystalline grades retain cost advantages in batch-oriented alkyd resin production where powder dissolution kinetics are well-characterized.
- Emulsion:Aqueous dispersion formats serve waterborne coating formulators seeking VOC reduction without solubility compromise.
- Gel:Thixotropic rheology targets specialized adhesive and sealant applications requiring controlled flow under shear.
Solid formulations retain volume leadership in industrial coatings, while Liquid grades are gaining share fastest in pharmaceutical toll manufacturing.
Distribution Channel:
Traceability requirements and lot-size economics determine channel viability across end-use segments.
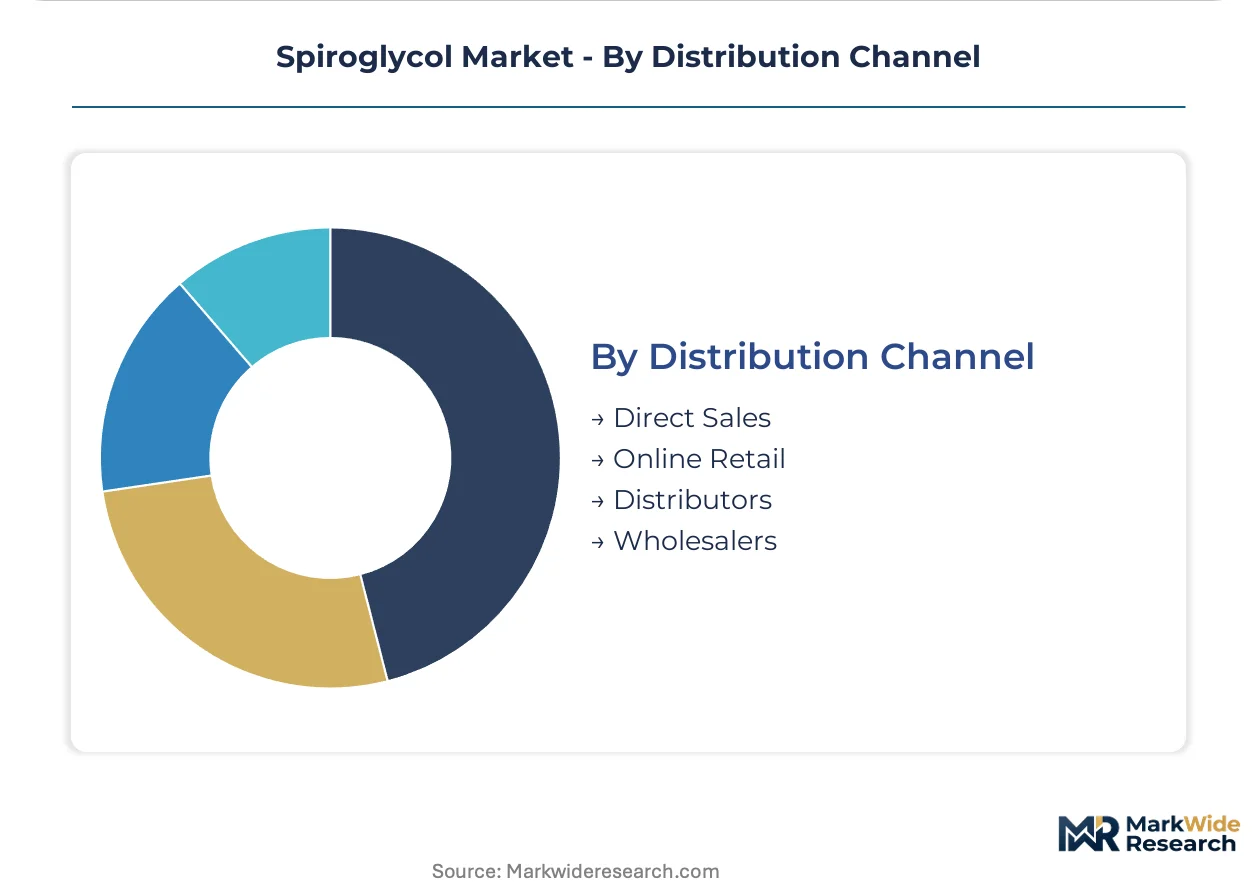
- Direct Sales:Dedicated quality assurance personnel manage certificate-of-analysis documentation and regulatory dossier transfer. Hyderabad and Ahmedabad chemical clusters in India mandate direct relationships for PLI scheme compliance audits.
- Distributors:Regional inventory positioning serves fragmented agrochemical formulators with smaller lot requirements and less stringent documentation needs.
- Online Retail:E-procurement platforms capture laboratory-scale and research-grade volumes where immediate availability outweighs lot-traceability.
- Wholesalers:Bulk industrial-grade transactions for standard resin applications tolerate longer lead times and aggregated sourcing.
Direct Sales captures the dominant value share, though Online Retail is expanding most quickly in research and development procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are reshaping regional trade flows for spiroglycol, with pharmaceutical-grade shipments concentrating in corridors where regulatory dossier pre-clearance accelerates customs clearance.
China
Chlor-alkali integrated complexes in Shandong and Jiangsu provinces dominate industrial-grade output for polyester resin applications. MEE enforcement of dual carbon goals is tightening emissions permits for pentaerythritol derivative production. Tianhua Pharmaceutical anchors pharmaceutical-grade supply from integrated assets in eastern chemical parks.
Germany
REACH-registered producers command premium spreads in excipient-grade segments across European pharmaceutical formulators. ECHA's extended reproductive toxicity study mandates for ten-tonne-plus imports are consolidating trade channels through established dossier holders. BASF SE leverages backward integration into acetaldehyde streams from Ludwigshafen operations.
India
CDSCO export licensing requirements and PLI scheme incentives are drawing multinational API manufacturers to establish captive offtake agreements. Hyderabad and Ahmedabad chemical clusters now mandate direct supplier relationships with lot-traceable documentation for compliance audits. Domestic production capacity is scaling rapidly under government production-linked incentives.
United States
EPA New Chemicals Program notifications slow pipeline velocity for novel spiroglycol analogues, advantaging incumbents with pre-cleared substance inventories. FDA Type II drug master file protocols enforce residual solvent thresholds below ten parts per billion for excipient grades. Pharmaceutical toll manufacturers in New Jersey and North Carolina are qualifying liquid-grade supply for continuous-flow processing lines.
Brazil
ANVISA registration pathways for excipient-grade spiroglycol remain underutilized by specialty chemical exporters relative to pharmaceutical market potential. Agrochemical formulators in São Paulo state are expanding demand for hydrophobic derivatives under field stability specifications. Import trade channels currently flow through distributor-mediated transactions lacking the direct quality assurance relationships seen in regulated pharmaceutical corridors.
Spiroglycol Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: integrated petrochemical majors with captive acetaldehyde supply, pharmaceutical-grade specialists with dedicated regulatory dossiers, and cost-optimized regional producers leveraging chlor-alkali integration. Competitive maneuvering centers on capacity expansion in India under PLI scheme alignment and REACH dossier acquisition to secure European market access.
Among European-registered chemical majors, BASF SE exemplifies the integrated archetype through upstream control over raw material streams, while Solvay S.A. occupies a position within the specialty-grade tier. Mitsubishi Chemical Corporation anchors the Asia-Pacific pharmaceutical-grade segment with established toxicological documentation. These three entities represent distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| BASF SE |
| MGC |
| Tianhua Pharmaceutical |
| SHANGHAI SYNFARM |
| Solvay S.A. |
| Dow Chemical Company |
| Eastman Chemical Company |
| Mitsubishi Chemical Corporation |
| LG Chem Ltd. |
| Others |
Value Network & Pricing Analysis
Shanghai-Rotterdam container freight corridors transmit crude oil volatility directly into pentaerythritol derivative costs, amplifying margin dispersion between chlor-alkali integrated producers and toll-dependent compounders while pharmaceutical buyers absorb premium spreads for certificate-of-analysis documentation.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across standard resin applications. Three-tier pricing structure across excipient-grade, technical-grade, and industrial-grade levels reflects certification investment and residual solvent testing burden. Cost compression in technical grades is intensifying because acetaldehyde feedstock swings transmit through non-integrated producers. Agrochemical formulators in Brazil exhibit highest price sensitivity, while pharmaceutical toll manufacturers in India accept premium spreads for lot-traceable supply chains.
Supply Chain Analysis
Dual-use chemical export controls limiting pentaerythritol derivative flows have tightened procurement security reviews for pharmaceutical-grade intermediates. Production gravity centers on Shandong and Jiangsu provinces in China, Ludwigshafen in Germany, and Gujarat in India. Feedstock streams draw from acetaldehyde, formaldehyde, and chlor-alkali co-product networks. Single-source vulnerability concentrates in eastern China's chlor-alkali complexes. Distribution runs through direct sales channels for pharmaceutical end-uses and distributor-mediated pathways for agrochemical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory dossier maintenance and certificate-of-analysis services represent the fastest-expanding recurring-revenue layer, outpacing base chemical sales as pharmaceutical customers outsource compliance documentation.
For Market Incumbents: Build regulatory dossier moats through ECHA REACH registration extensions and FDA Type II drug master file pre-submissions. Secure backward integration into acetaldehyde streams to insulate margin pools from crude oil transmission. Expand dedicated pharmaceutical-grade capacity in India under PLI scheme alignment before competitor filings harden market access. For New Entrants and Emerging Players: ANVISA registration pathways for excipient-grade spiroglycol in Brazil represent the most penetrable entry point among regulated pharmaceutical corridors. Liquid-grade toll manufacturing contracts for continuous-flow API processing in Hyderabad chemical parks offer second-mover access without dedicated asset investment. Partner with established regulatory consultancies to bypass toxicological study cost barriers. For Investors and Strategic Acquirers: Pharmaceutical-grade specialists with pre-cleared ECHA dossiers and captive analytical chemistry capabilities offer durable positioning across the analysis window. Monitor CDSCO export licensing acceleration in India as inflection indicator for captive offtake agreement velocity. Material consolidation of industrial-grade supply into chlor-alkali majors would compress mid-scale producer viability.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Extension | ECHA registration above ten-tonne thresholds captures displaced industrial volume at premium spreads. |
| Backward Integration into Acetaldehyde | Ludwigshafen and Shandong operations insulate margin pools from feedstock volatility transmission. |
| Pharmaceutical-Grade Capacity Expansion | Hyderabad and Ahmedabad chemical parks scale under CDSCO export licensing and PLI incentives. |
| Continuous-Flow Reactor Commissioning | BASF and Mitsubishi installations eliminate batch-to-batch variability for FDA residual solvent compliance. |
| Direct Sales Channel Investment | Lot-traceable supply chains displace distributor-mediated transactions in pharmaceutical procurement. |
Research Methodology
Operator-level perspectives from plant managers at chlor-alkali complexes, procurement leads at polyester resin manufacturers, regulatory affairs directors at pharmaceutical formulators, and technical R&D heads at specialty chemical companies anchored the qualitative base. Secondary validation drew from ECHA registration databases, CDSCO export licensing records, SEC 10-K filings of chemical majors, and customs trade data for pentaerythritol derivatives. Bottom-up capacity assessments and top-down demand modeling were triangulated against disclosed production figures.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation by substitution degree, formulation state, end-use industry, and regional regulatory cluster. CAGRs were derived from installed capacity expansion timelines, PLI scheme disbursement schedules, and REACH registration velocity. Forecast inputs incorporated MEE emissions permit tightening for dual carbon goals and FDA Type II drug master file approval cycles.
Practitioners should monitor ECHA extended reproductive toxicity study mandates, CDSCO licensing acceleration, and MEE enforcement actions for early signals. Forecasts reflect assumptions around regulatory compliance timelines and feedstock cost transmission. Material shifts in REACH registration thresholds or PLI scheme restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Asia Pacific Aerosol Cans Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Bio Polyol and Green Polyol Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
Europe Sugarcane Wax Market
Specialty Chemicals
Acrylic Powder Market