
 Horse Riding Apparel Market | 2026-2036
Horse Riding Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Horse Riding Apparel Market Outlook
Specialty equestrian retail is reconfiguring as direct-to-consumer platforms capture share from traditional tack shops. Ariat International leverages its western heritage to dominate premium boot and apparel lines across North American ranch and show circuits. Pikeur sustains its position in European competition wear through precision tailoring for dressage and show-jumping athletes. DECATHLON competes on accessibility, extending affordable riding basics through its global big-box network into emerging equestrian markets.
Horse riding apparel encompasses protective and performance garments engineered for mounted activity, typically integrating reinforced seams, stretch panels for saddle contact, and moisture-wicking textiles rated for abrasion resistance. Breathable membranes and leather reinforcement at grip points serve the primary purpose of rider safety, thermoregulation, and unrestricted movement during training or competition. The product type dimension shows boots and breeches anchoring volume sales while performance jackets command premium positioning through technical fabric innovation. By end user, amateurs and children represent the fastest-growing pool as leisure participation outpaces professional cohort expansion. The material split reveals leather and technical synthetics capturing margin concentration where durability certifications justify higher price positioning.
REACH in Europe and the US Consumer Product Safety Commission govern chemical content and flammability standards for riding apparel sold across their respective jurisdictions, with CE marking required for protective headgear and body protector categories. The EU Green Deal is accelerating scrutiny of textile supply chains, pushing manufacturers toward audited material traceability. Stakeholders must monitor evolving chemical restriction schedules and certification reciprocity between national equestrian federations to preserve cross-border product eligibility.
Market Dynamics
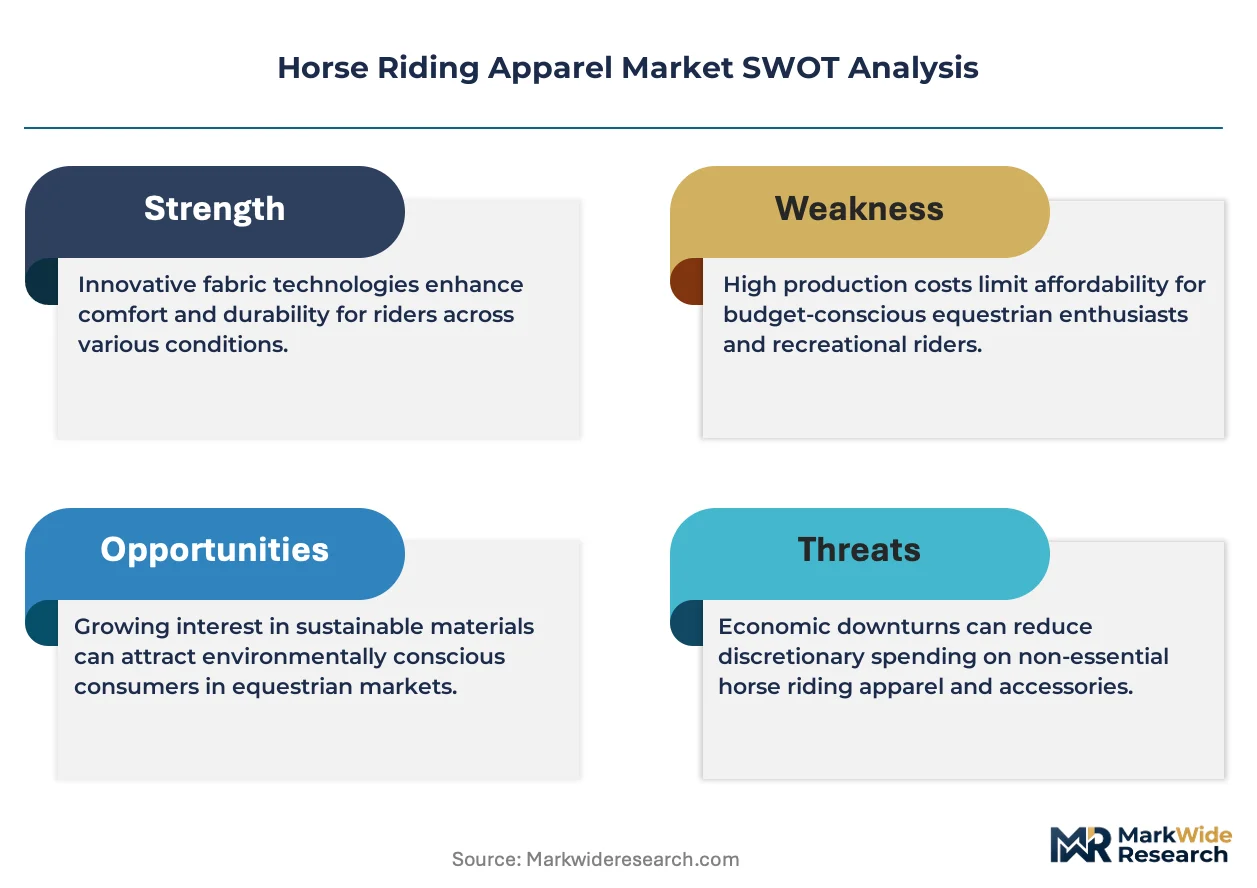
Leisure equestrianism is pulling amateur riders into premium apparel tiers, forcing brands to recalibrate product architecture around weekend enthusiasts rather than competition professionals.
Growth Catalysts
- REACH chemical compliance:Tightening European textile standards under ECHA oversight is accelerating R&D investment in bio-based treatments and water-free dyeing processes.
- Texas equestrian circuits:Concentrated amateur participation across Houston-Dallas-Austin corridor is sustaining volume demand for mid-market boots and protective gear.
- Moisture-wicking membranes:Technical fabric integration into everyday riding basics is expanding addressable market beyond competitive athletes into leisure segments.
Market Restraints
- Leather input volatility:Premium hide sourcing concentrates in Italian and Argentinian tanneries, exposing margin structures to livestock supply shocks and export tariff fluctuations.
- CE marking reciprocity gaps:Divergent body protector certification requirements between British Eventing and FEI standards create inventory fragmentation for cross-border sellers.
- Synthetic abrasion resistance:Technical fabric alternatives still fail to match leather durability at grip points, limiting full material substitution in professional-grade products.
Strategic Opportunities
- Children's safety segment:Underserved youth protective gear market in California recreational stables offers white space for sized-down certification-compliant body protectors.
- Direct-to-consumer platforms:Tack shop displacement by specialized equestrian e-commerce is compressing distribution costs and enabling made-to-measure breeches at scale.
- EU Green Deal traceability:Audited supply chain documentation requirements are creating first-mover advantage for brands with vertically controlled material sourcing.
Industry Challenges
- Pattern-making specialization:Scarcity of technical designers fluent in saddle-contact ergonomics and stretch-panel engineering constrains new product velocity.
- Multi-federation compliance:Simultaneous certification maintenance across USEF, British Dressage, and FEI protocols extends product development timelines and testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horse Riding Apparel Market |
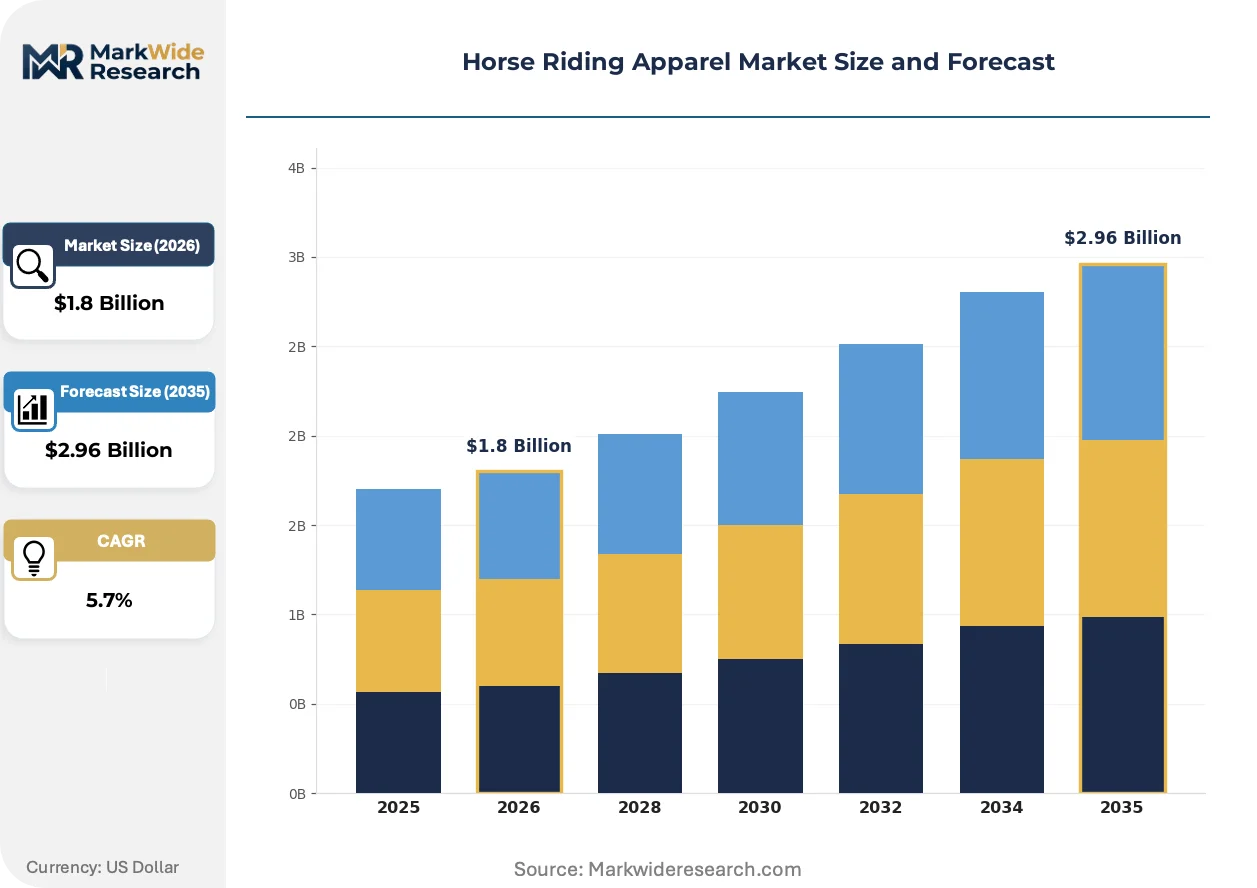
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jackets, Breeches, Gloves, Boots End User: Amateurs, Professionals, Trainers, Children Material: Cotton, Polyester, Leather, Nylon Style: Formal, Casual, Performance, Vintage |
| Companies Covered | Horseware, Mountain Horse, Ariat International, Ovation Riding, KEP Italia, Pikeur, DECATHLON, Equetech, Kerrits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horse Riding Apparel Market Strategic Shifts
Technical fabric evolution and regulatory transparency mandates are converging to redefine how riding apparel is engineered, certified, and sold across amateur and professional tiers.
Biomechanical sensor integration is hybridizing traditional protective garments with real-time posture feedback systems. Competitive dressage riders in Germany and the Netherlands are piloting pressure-mapping breeches that transmit saddle balance data to smartphone applications. This convergence of textile engineering and wearable electronics is compressing the boundary between apparel and training equipment, forcing brands to partner with sensor hardware specialists or cede this adjacent market.
REACH SVHC candidate list expansion under ECHA oversight is compelling manufacturers to eliminate per- and polyfluoroalkyl substances from water-repellent treatments. Italian and Spanish textile finishers are reformulating coatings around bio-based alternatives, though performance durability gaps persist in heavy-rain conditions. Competition wear destined for FEI-sanctioned events faces the tightest compliance scrutiny, with brands pre-emptively auditing chemical content to avoid start-line disqualification risks.
Subscription-based boot replacement programs are displacing traditional ownership models among high-frequency amateur riders. California and Texas stable operators are piloting annual refresh plans covering resoling, conditioning, and sizing exchanges as rider foot morphology changes. This service-layer unbundling is most visible in metropolitan equestrian centers where convenience premiums outweigh capital expenditure preferences for occasional competitors.
Horse Riding Apparel Market Segmentation
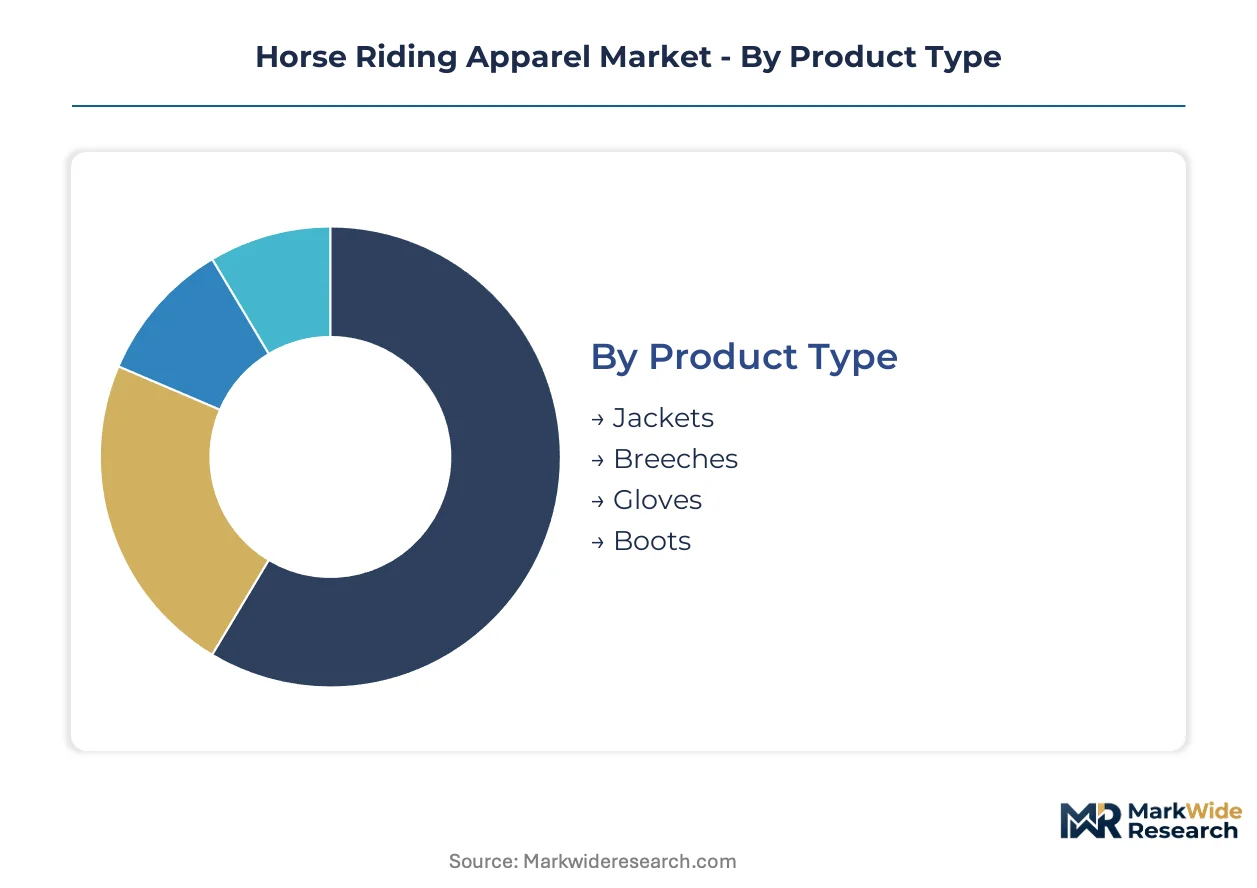
Riding apparel segmentation tracks how protective function, rider skill level, and material durability intersect with distinct replacement cycles and sizing complexity. Each dimension shapes inventory planning, certification requirements, and channel strategy differently across amateur and professional cohorts.
Product Type:
After-sales-service intensity varies sharply across product types, with boots demanding resoling and conditioning programs while jackets require minimal post-purchase support.
- Boots:Full-grain leather construction with reinforced heel counters and steel shank arch support withstands repeated stirrup abrasion. Texas amateur circuits sustain replacement demand as weekend riders cycle through entry-level and mid-tier pairs annually.
- Breeches:Four-way stretch panels at knee and seat contact points integrate silicone grip patterns for saddle stability. German and Dutch dressage academies drive premium specification for competition-grade tailoring with precise seam placement.
- Jackets:Technical shell fabrics with taped seams balance weather protection against freedom of shoulder movement.
- Gloves:Reinforced rein-grip zones in synthetic suede or leather prevent blistering during extended schooling sessions.
By volume, boots lead. By growth pace, performance-engineered breeches are climbing the fastest.
End User:
Cost tier stratification separates occasional participants from dedicated competitors, with pricing elasticity widening across the amateur-to-professional spectrum.
- Amateurs:Leisure riders purchasing entry-mid tier products through direct-to-consumer platforms represent expanding addressable market as recreational stable memberships rise. California metropolitan equestrian centers concentrate this cohort.
- Children:Sized-down protective gear with adjustable growth features addresses safety compliance gaps in youth programs. Underserved positioning exists in recreational stable networks seeking certified body protectors.
- Professionals:FEI-sanctioned competitors require federation-approved competition wear with documented chemical compliance and precise fit standards.
- Trainers:High-frequency daily use demands accelerated replacement cycles and durability prioritization over aesthetic variation.
By volume, amateurs dominate procurement. By margin capture, professional-grade specifications sustain premium positioning.
Material:
Supply concentration in Italian and Argentinian tanneries shapes leather availability, while technical synthetics offer tariff and traceability advantages under EU Green Deal auditing.
- Leather:Premium hide sourcing for boots and competition gloves concentrates durability certification value. Livestock supply volatility and export duty fluctuations compress margin predictability.
- Polyester:Moisture-wicking knit constructions dominate breeches and base layers with lower unit costs and faster dyeing throughput.
- Nylon:High-tenacity weave patterns reinforce abrasion zones in jackets and technical outerwear.
- Cotton:Natural fiber blends persist in casual stable wear with limited performance application.
By volume, polyester leads. By value concentration, leather commands the steepest premium tiers.
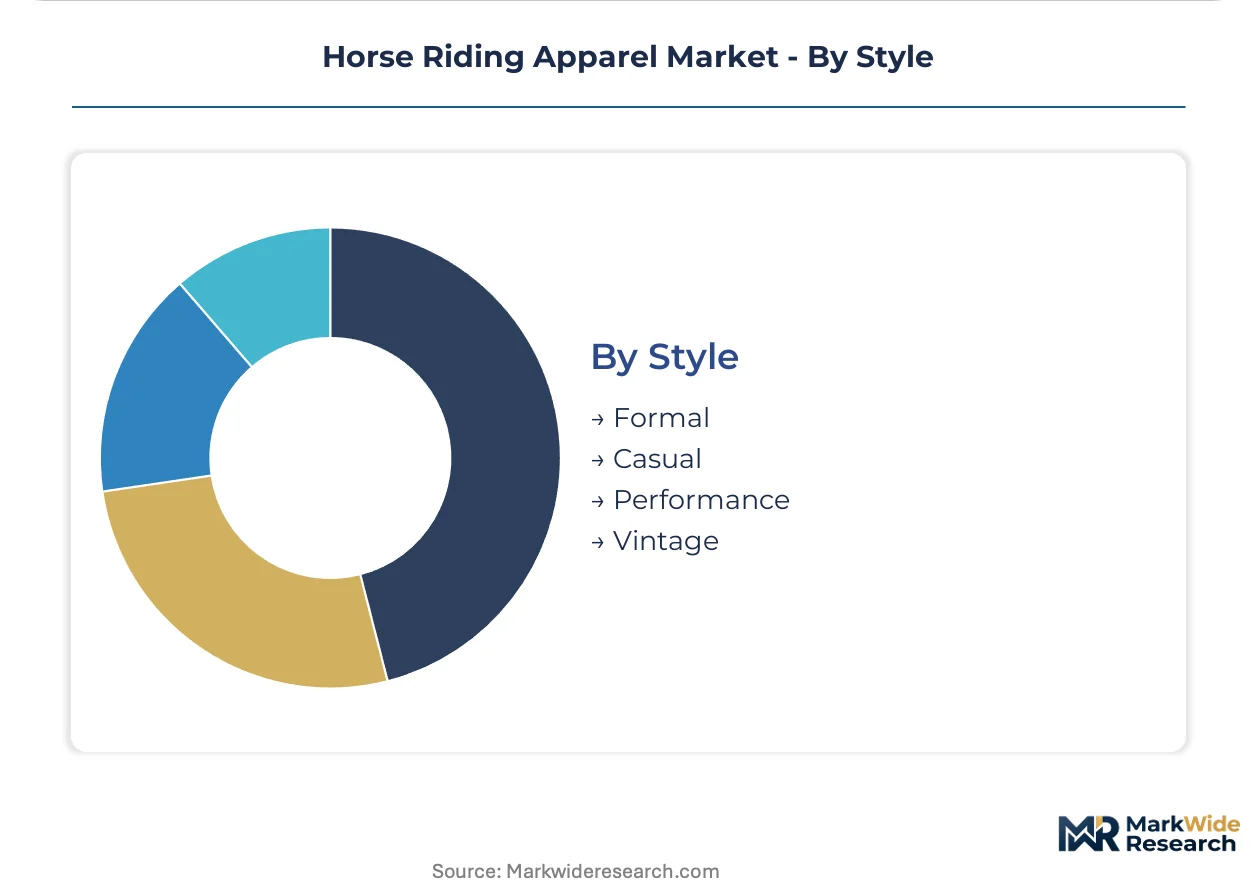
Style:
Maturity gradients separate established competition formats from emerging aesthetic preferences, with formal and performance styles holding institutional backing through federation dress codes.
- Performance:Biomechanical engineering prioritizes thermoregulation and unrestricted movement for training and competition. Sensor-integrated prototypes are gaining traction among German dressage riders.
- Formal:Traditional hunt coat silhouettes and show-appropriate colorways maintain mandatory presence in rated events. British Eventing and USEF protocols preserve this category's necessity.
- Casual:Barn-appropriate styling bridges stable management and social visibility for amateur riders.
- Vintage:Heritage-inspired detailing attracts collectors and recreational riders outside competitive circuits.
By volume, performance styling leads. By share expansion, casual crossover designs are gaining fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's textile logistics infrastructure underwrites Europe's role as the primary entry point for finished riding apparel and treated leather hides from Italian and Argentinian tanneries. Distribution networks radiating from this hub supply equestrian centers across Germany, France, and the Low Countries with competition-grade garments.
United States
Texas amateur circuits across the Houston-Dallas-Austin corridor sustain volume demand for mid-market boots and protective gear as recreational stable memberships expand. The US Consumer Product Safety Commission governs flammability standards for children's riding apparel, tightening certification requirements for youth-focused brands. California metropolitan equestrian centers concentrate leisure rider procurement, with subscription-based boot replacement programs gaining traction in Los Angeles and San Francisco Bay Area stables.
Germany
Dressage academies in North Rhine-Westphalia and Lower Saxony drive premium specification for competition-grade breeches with precise seam placement and sensor-integrated prototypes. ECHA oversight of REACH SVHC candidate list expansion compels manufacturers to eliminate per- and polyfluoroalkyl substances from water-repellent treatments. The Aachen equestrian cluster anchors technical innovation, with biomechanical sensor integration piloting pressure-mapping garments that transmit saddle balance data to smartphone applications.
United Kingdom
British Eventing's divergent body protector certification requirements from FEI standards create inventory fragmentation for cross-border sellers serving amateur and professional cohorts. The EU Green Deal's audited supply chain documentation requirements push UK-based brands toward vertically controlled material sourcing to preserve continental market access. The Cotswolds and Home Counties recreational stable networks concentrate children's safety segment demand, with sized-down certification-compliant body protectors remaining undersupplied.
Italy
Premium hide sourcing for boots and competition gloves concentrates in Italian tanneries, exposing margin structures to livestock supply shocks and export tariff fluctuations. REACH compliance deadlines accelerate R&D investment in bio-based treatments and water-free dyeing processes among Lombardy and Tuscany textile finishers. The Milan-Turin industrial corridor hosts reformulation efforts around bio-based water-repellent alternatives, though performance durability gaps persist in heavy-rain conditions.
France
Direct-to-consumer platform penetration displaces traditional tack shops in Île-de-France and Auvergne-Rhône-Alpes, compressing distribution costs for mid-market brands. CE marking requirements for protective headgear and body protector categories govern product eligibility across domestic and export markets. The Normandy equestrian breeding region anchors leisure participation growth, with amateur riders pulling into premium apparel tiers and forcing brands to recalibrate product architecture around weekend enthusiasts.
Horse Riding Apparel Market Competitive Environment
On the supply side, the industry is consolidating around heritage specialists with vertically controlled material sourcing and scale-driven sporting goods conglomerates with global retail footprints. Three strategic archetypes dominate: western heritage premium boot manufacturers, European precision tailoring houses for competition wear, and accessible big-box retailers extending affordable basics into emerging markets. Dominant competitive moves include direct-to-consumer platform expansion displacing traditional tack shop distribution and audited supply chain documentation investments securing first-mover advantage under EU Green Deal traceability mandates.
Among heritage-rooted specialists, Ariat International and Pikeur exemplify contrasting geographic positioning archetypes. Ariat leverages its western heritage to anchor premium boot and apparel lines across North American ranch and show circuits. Pikeur sustains its European competition wear position through precision tailoring for dressage and show-jumping athletes. DECATHLON occupies the accessibility tier, extending affordable riding basics through its global big-box network into emerging equestrian markets.
| Leading Market Players |
|---|
| Horseware |
| Mountain Horse |
| Ariat International |
| Ovation Riding |
| KEP Italia |
| Pikeur |
| DECATHLON |
| Equetech |
| Kerrits |
| Others |
Value Chain & Pricing Dynamics
Leather input volatility from Italian and Argentinian tannery concentration compresses margin predictability across premium boot tiers while simultaneously forcing supply chain diversification into technical synthetics. This dual pressure expands pricing spreads between full-grain leather certification tiers and bio-based alternatives as REACH compliance deadlines accelerate reformulation costs.
Pricing Analysis
Volume-discount tiering structures separate amateur weekend riders purchasing single units from stable operators negotiating annual refresh programs. Three-tier pricing stratification across premium competition-grade, standard training-tier, and economy entry-level separates FEI-certified garments from recreational basics. Cost compression in mid-market boots intensifies as direct-to-consumer platforms displace tack shop markups. Amateur leisure riders exhibit highest price sensitivity, while professional competitors prioritize certification compliance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration in Portuguese and Romanian apparel facilities holds capacity for European competition wear, while Chinese and Vietnamese producers dominate synthetic breeches and base layer production. Raw material sourcing draws from Italian tanneries for premium hides, German textile finishers for water-repellent treatments, and Taiwanese suppliers for sensor hardware components. Single-source vulnerability in Argentinian livestock supply exposes boot manufacturers to export duty fluctuations. Distribution runs through Rotterdam port logistics radiating to German dressage academies and direct-to-consumer platforms serving California metropolitan stables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomechanical sensor integration represents a high-growth disruption as wearable electronics compress the boundary between apparel and training equipment, with EU Green Deal traceability mandates simultaneously reshaping material sourcing requirements.
For Market Incumbents: Insulate premium positioning by securing captive supply agreements with Lombardy and Tuscany tanneries before REACH SVHC expansion tightens chemical input availability. Accelerate in-house production of bio-based water-repellent treatments to offset reformulation cost pressure from ECHA oversight. Defend against direct-to-consumer displacement by embedding subscription-based resoling programs into core boot offerings. For New Entrants and Emerging Players: Build out white-space positioning in children's sized-down body protectors for California and Texas recreational stable networks, where certification-compliant youth gear remains undersupplied. Target amateur leisure riders in metropolitan equestrian centers with casual crossover styling that bridges barn management and social visibility. Pursue made-to-measure breech platforms leveraging compressed distribution costs to undercut heritage tailoring houses on fit precision. For Investors and Strategic Acquirers: Heritage-rooted specialists with vertically controlled material sourcing and audited EU Green Deal documentation represent prime acquisition targets as continental market access tightens. Long-term viability hinges on 5-10 year regulatory reciprocity between federation certification protocols and supply chain transparency mandates. Monitor ECHA SVHC candidate list expansion velocity as the inflection signal for chemical compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Expansion | Compresses distribution costs for mid-market brands targeting Texas amateur circuits. |
| Sensor Hardware Partnership | Enables pressure-mapping breech prototypes for German dressage academy pilots. |
| Bio-Based Treatment Reformulation | Addresses REACH SVHC compliance for Italian textile finishers serving FEI events. |
| Subscription Service Layer Unbundling | Captures convenience premiums from California metropolitan stable operators. |
| Audited Supply Chain Documentation | Secures first-mover advantage under EU Green Deal traceability mandates. |
Study Parameters
Desk research of customs trade records, federation certification databases, and tannery export filings preceded structured interviews with apparel technical designers, stable operators, e-commerce platform managers, and textile finishing R&D directors. Primary fieldwork across the Houston-Dallas-Austin corridor and California metropolitan equestrian centers validated secondary demand indicators. Bottom-up unit economics for boot replacement cycles and top-down market sizing from customs data were triangulated to produce volume and value estimates.
Assumptions around REACH SVHC expansion timing, leather price volatility bands, and amateur participation growth rates were held fixed across baseline scenarios while sensor adoption curves and direct-to-consumer penetration were varied in sensitivity testing. Segmentation dimensions modeled include product type, end user skill tier, material certification grade, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical replacement cycle data and projected participation trends in leisure equestrianism.
Stress conditions across Argentinian export duty fluctuations, ECHA chemical restriction schedules, and federation certification reciprocity gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged revision risk from livestock supply shocks or abrupt regulatory harmonization failures. Quarterly review of SVHC candidate list updates and amateur stable membership trajectories is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Asia-Pacific Footwear Sole Material Market
Apparel Textiles
Organic Baby Clothes Market
Apparel Textiles
Hunting Apparel Market
Apparel Textiles
Hosiery Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
Uniform Market
Apparel Textiles
Zipper Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Insect Repellent Apparel Market
Apparel Textiles
China Flame Retardant Apparel Market
Apparel Textiles
Global Maternity Innerwear Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
Embroidery Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
Global Socks Market
Apparel Textiles
North America Garment Steamers Market