
 Japan Home Textile Market | 2026-2036
Japan Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Home Textile Market Foresight
Japan's hospitality sector is realigning procurement priorities as international visitor volumes recover and ryokan properties upgrade guest room standards. Nitori Holdings Co., Ltd. leverages its vertically integrated supply chain to dominate mid-market bedding and curtain categories across suburban retail networks. Toray Industries, Inc. anchors technical textile innovation through advanced polyester filament development for performance-driven home applications. Ryohin Keikaku Co., Ltd. (MUJI) differentiates via minimalist design ethos and transparent material sourcing that resonates with urban apartment dwellers in Osaka and Nagoya.
Japan home textiles encompass woven, knitted, and non-woven fabric products engineered for residential and commercial interior environments, typically specified by thread count, GSM weight, and flame-retardant treatment levels for institutional applications. Cotton bedding maintains structural dominance due to humidity-responsive breathability demanded by Japanese climate conditions, while polyester curtains gain share from rental property managers prioritizing wrinkle resistance and wash durability. The residential end-user segment occupies the deepest margin pools through repeat purchase cycles of towels and replacement bedding, whereas hospital procurement operates on stringent JIS standard compliance that limits supplier participation.
METI enforces energy efficiency labeling for textile manufacturing equipment, while the Ministry of Health, Labour and Welfare mandates flammability standards under the Fire Service Law for curtains deployed in commercial buildings. JIS L standards govern dimensional stability and colorfastness testing protocols that determine market access for domestic and imported products alike. Stakeholders must monitor evolving bioplastic fiber certifications and prefectural waste reduction ordinances that will reshape raw material qualification requirements.
Market Dynamics
METI's carbon neutrality roadmap is forcing polyester manufacturers to requalify feedstock sources, while Kanto corridor retailers compress replenishment cycles to match Tokyo's dense apartment turnover rates.
Growth Catalysts
- Ryokan renovation wave:Boutique hospitality operators in Kyoto and Osaka are expanding linen procurement volumes to meet upgraded guest room standards for recovering international tourism.
- Recycled polyester mandates:METI's textile decarbonization framework creates certified demand pull for chemically recycled filament in curtain and bedding applications.
- Humidity-responsive cotton:Breathable natural fiber bedding maintains structural dominance as Japanese climate conditions sustain replacement demand across residential end-users.
Market Restraints
- Organic cotton supply concentration:Limited domestic cultivation and import dependency on specific origins creates raw material qualification bottlenecks for certified product lines.
- JIS L testing compliance costs:Dimensional stability and colorfastness protocols impose laboratory certification burdens that filter smaller suppliers from institutional procurement channels.
- Flame-retardant chemical substitution:The Fire Service Law's curtain flammability standards limit formulation flexibility as halogen-free alternatives face performance validation gaps.
Strategic Opportunities
- Prefectural waste reduction ordinances:Emerging municipal textile collection mandates create closed-loop feedstock access for manufacturers investing in mechanical recycling infrastructure.
- Bioplastic fiber certifications:Early qualification under developing PLA and PHA standards opens premium positioning before mass-market commoditization.
- Suburban retail network densification:Mid-market bedding penetration remains underdeveloped in tertiary Kanto cities outside Tokyo's core 23 wards.
Industry Challenges
- Energy efficiency equipment retrofitting:METI's manufacturing equipment labeling rules require capital-intensive loom and finishing line upgrades for compliance.
- Multi-standard certification timelines:Simultaneous pursuit of organic content, recycled content, and carbon footprint labels stretches quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Home Textile Market |
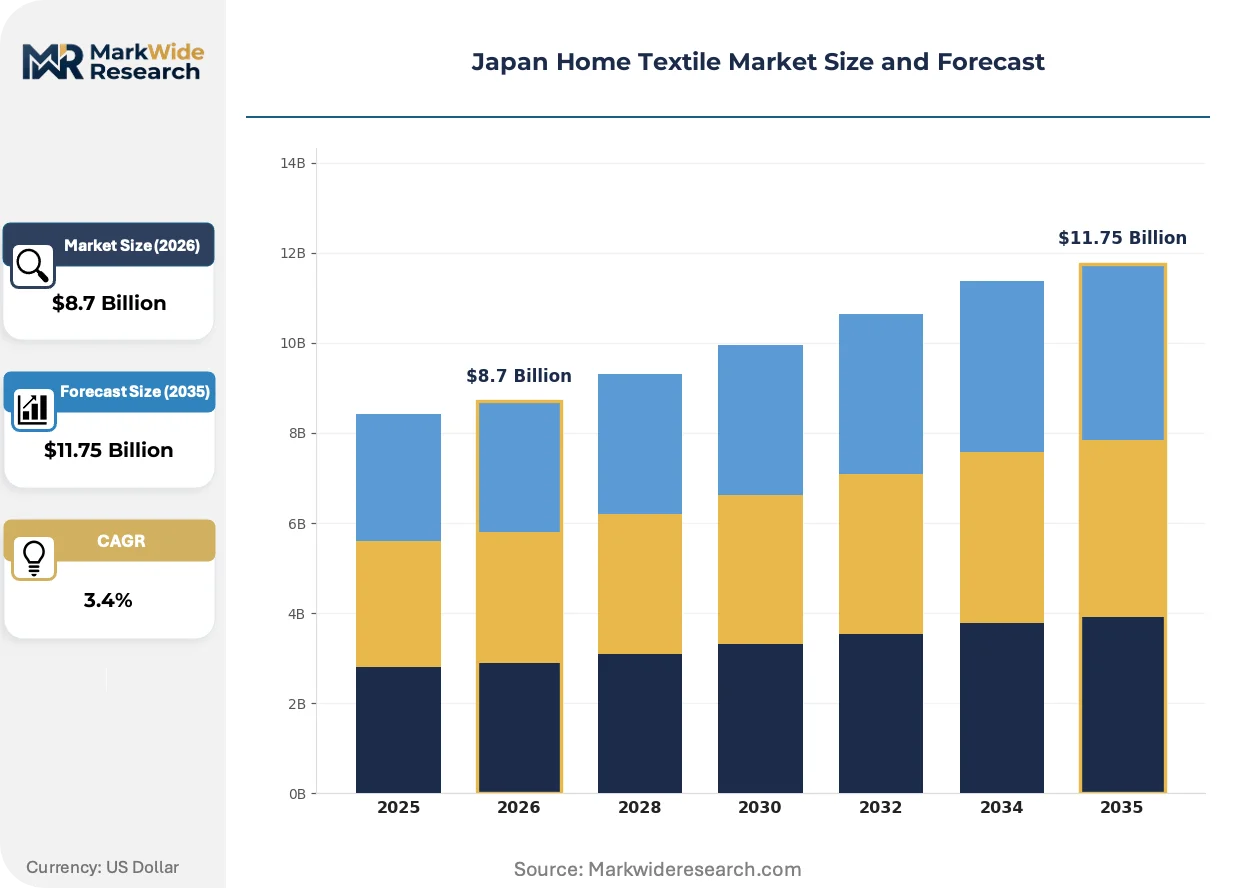
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.75 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedding, Curtains, Rugs, Towels Material: Cotton, Polyester, Linen, Silk End User: Residential, Hotels, Hospitals, Offices Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | IKEA Japan K.K., Toray Industries, Inc., Nitori Holdings Co., Ltd., Aeon Retail Co., Ltd. (Home Coordy), Teijin Frontier Co., Ltd., Nishikawa Co., Ltd., Francfranc Corporation, Uchino Co., Ltd., Ryohin Keikaku Co., Ltd. (MUJI), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Home Textile Market Shifts & Advancements
Digital production workflows and material traceability systems are compressing traditional supply chain stages, while regulatory pressure on carbon intensity accelerates fiber innovation cycles.
Automated cutting and sewing cells using computer vision guidance are automating pattern nesting and seam alignment in curtain manufacturing. Osaka-based contract producers are deploying these systems to reduce labor dependency in high-mix, low-volume production. The technology is automating throughput scaling for made-to-measure orders that previously required manual operator intervention.
METI's textile sector decarbonization roadmap mandates energy consumption benchmarking for manufacturing equipment and incentivizes renewable power purchase agreements. Fabric finishing operations face the steepest compliance costs due to thermal process intensity. Kyoto prefecture's cluster of dye houses is responding through shared biomass boiler infrastructure to aggregate renewable thermal supply.
Apartment dwellers in Tokyo's 23 wards are compressing bedding replacement cycles to match lease renewal rhythms, driving subscription-style replenishment models through direct channels. Traditional department store intermediaries are losing share to manufacturer-operated digital storefronts offering scheduled delivery. This pattern is most visible among single-person households in Saitama and Chiba commuter corridors.
Japan Home Textile Market Segmentation
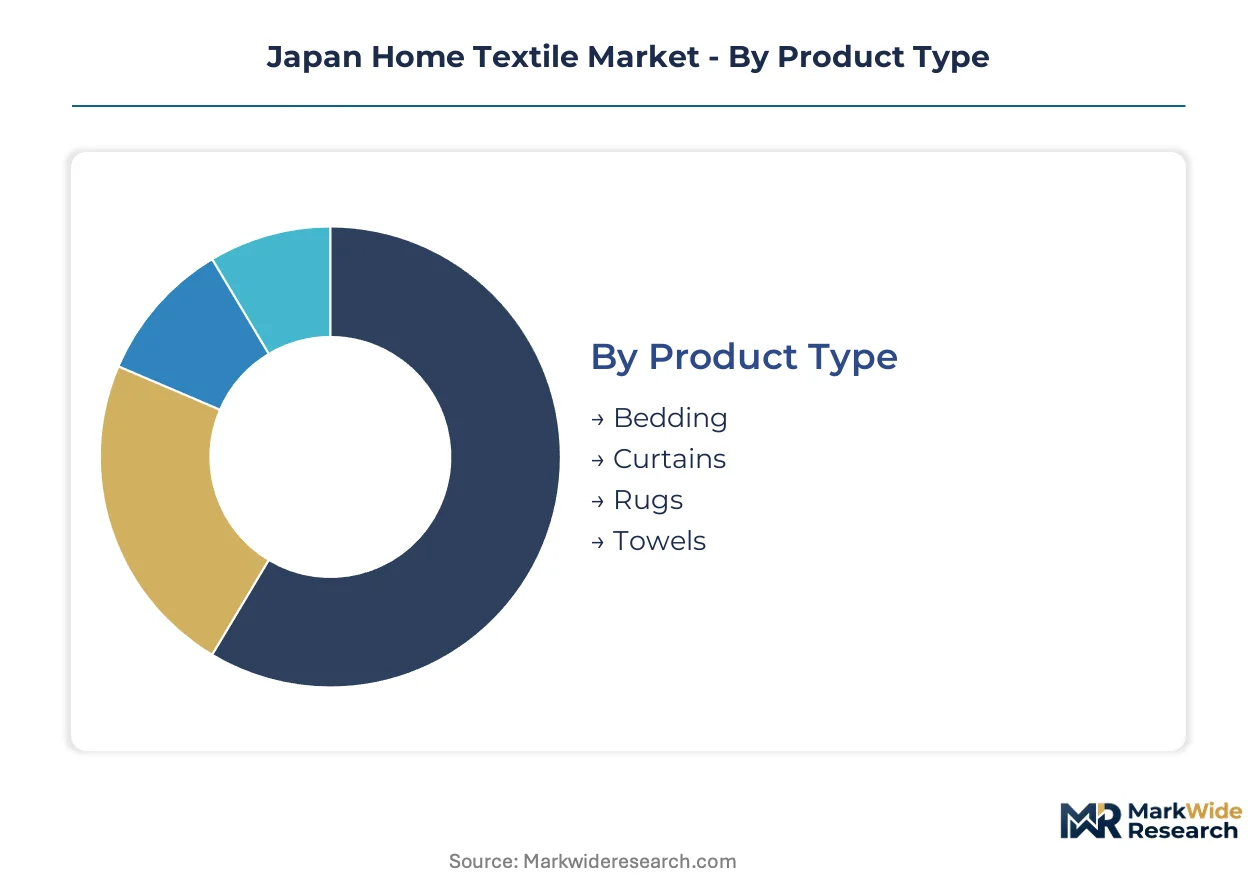
Segmentation in Japan's home textile market reveals how regulatory frameworks and procurement standards fragment demand across certification tiers. JIS compliance requirements, METI carbon labeling, and Fire Service Law specifications create distinct qualification barriers that reshape competitive access by product category and end-use channel.
Product Type:
JIS L standards apply differentially across product categories, with flame-retardant testing mandatory for curtains in commercial deployment while bedding faces dimensional stability protocols.
- Bedding:Cotton and cotton-blend sheets, duvet covers, and pillowcases dominate residential replacement cycles. Tokyo's dense apartment base sustains premium thread-count demand in Saitama and Chiba commuter corridors, where lease-aligned replenishment patterns compress purchase intervals.
- Curtains:Polyester and blackout fabrics engineered for light-blocking performance face mandatory Fire Service Law flammability certification for hotels and offices. Kyoto and Osaka hospitality renovations are expanding procurement volumes for made-to-measure thermal and acoustic specifications.
- Rugs:Woven and tufted floor coverings span natural fiber and synthetic piles for residential entryways and living spaces. Tertiary Kanto cities outside Tokyo's core 23 wards show underdeveloped mid-market penetration.
- Towels:Terrycloth and gauze-weave bath and hand towels drive repeat purchase frequency through suburban retail networks. Nitori's vertically integrated supply chain captures volume share in standard GSM weight categories.
Leading the category by volume: Bedding. Growing fastest: Curtains.
Material:
Raw material selection determines carbon intensity scores under METI's textile decarbonization framework and shapes supplier qualification for certified product lines.
- Cotton:Humidity-responsive breathability sustains structural dominance in bedding applications despite import dependency on specific origins. Organic cultivation bottlenecks limit certified line expansion as domestic production remains minimal.
- Polyester:Chemically recycled filament gains share from METI-mandated feedstock requalification in curtain and institutional bedding. Toray Industries anchors technical innovation through advanced filament development for performance-driven applications.
- Linen:Bast fiber derived from flax cultivation offers moisture-wicking properties for summer bedding and table textiles. Premium positioning targets ryokan properties seeking natural material narratives for upgraded guest room standards.
- Silk:Mulberry-derived filament commands niche luxury positioning in pillowcases and decorative throws. Limited domestic sericulture constrains volume scale.
Highest certification burden: Organic cotton. Steepest feedstock transition: Recycled polyester.
End User:
Procurement channel access varies sharply by institutional compliance requirements, with hospitals operating the most restrictive supplier qualification protocols.
- Residential:Single-person households in Tokyo's 23 wards compress replacement cycles through subscription-style direct channels. MUJI's minimalist design ethos resonates with urban apartment dwellers prioritizing transparent material sourcing.
- Hotels:Boutique ryokan operators in Kyoto and Osaka are expanding linen procurement for renovation programs targeting recovering international tourism. Custom embroidery and regional pattern specifications differentiate property positioning.
- Hospitals:JIS standard compliance for dimensional stability and sterilization durability filters smaller suppliers from institutional procurement. Flame-retardant and antimicrobial treatment requirements impose laboratory certification burdens.
- Offices:Commercial building curtain deployment faces Fire Service Law flammability mandates that limit formulation flexibility. Facility managers prioritize wrinkle resistance and wash durability in high-traffic common areas.
Deepest margin pools: Residential repeat purchase. Tightest supplier filtering: Hospital procurement.
Distribution Channel:
Channel strategy determines working capital intensity and customer data access, with digital direct models compressing traditional department store intermediation.
- Online:Manufacturer-operated digital storefronts capture scheduled delivery subscriptions from Tokyo apartment dwellers. Automated replenishment algorithms align bedding shipments with lease renewal rhythms.
- Supermarkets:Mass-market towel and basic bedding penetration targets suburban family households in tertiary Kanto cities. Price competition concentrates in standard GSM and thread-count tiers.
- Specialty Stores:Curated textile showrooms in Osaka and Nagoya offer made-to-measure curtain consultation and fabric sampling. High-touch service justifies premium positioning for custom dimensions.
- Wholesale:Contract producers supply institutional volumes to hospitality and healthcare procurement departments. Bulk pricing structures reflect volume scale and certification tier.
Fastest channel shift: Online direct. Most stable volume: Wholesale institutional.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's home textile production clusters around designated manufacturing zones where METI incentives and prefectural industrial policy converge. The Kanto corridor anchors volume output through Tokyo's dense residential base and Saitama's logistics infrastructure.
Kanto
Tokyo's 23 wards compress bedding replacement cycles through lease-aligned subscription models. METI's carbon neutrality roadmap mandates energy efficiency labeling for textile manufacturing equipment across Saitama and Chiba dye houses. Chiba's port facilities handle imported cotton feedstock for Kanto-based fabric finishers serving the capital's apartment market.
Kansai
Kyoto's boutique ryokan operators are expanding linen procurement volumes for renovation programs targeting recovering international tourism. The Fire Service Law's flammability standards for commercial curtains filter supplier participation in Osaka's hospitality procurement channels. Osaka-based contract producers deploy automated cutting cells for made-to-measure curtain orders.
Chubu
Nagoya's automotive supplier base sustains demand for technical textiles in industrial applications alongside residential bedding. JIS L standards govern dimensional stability testing for products manufactured in Aichi prefecture's textile cluster. Gifu prefecture's weaving heritage supports specialty fabric production for premium positioning.
Kyushu
Fukuoka's growing logistics hub function distributes home textile products to southwestern Japan's residential markets. Prefectural waste reduction ordinances in Saga and Nagasaki create closed-loop feedstock access for mechanical recycling investments. Kumamoto's dye houses respond to METI decarbonization mandates through shared renewable thermal infrastructure.
Hokkaido
Sapporo's cold climate sustains demand for thermal bedding and heavy-weight curtains across residential and hospitality segments. Limited domestic cotton cultivation increases import dependency for Hokkaido-based manufacturers. Local retailers source through wholesale channels anchored in Kanto production clusters.
Japan Home Textile Market Competitive Landscape
Top-tier vendors anchor premium and mass-market tiers, while mid-scale specialists occupy niche positioning. The market exhibits moderate consolidation around vertically integrated holding companies and diversified textile conglomerates. Three archetypes dominate: integrated retail-manufacturing hybrids, technical fiber developers, and minimalist design retailers. Competitive moves concentrate on backward integration into raw material sourcing and digital channel expansion to compress traditional intermediation.
Within the integrated retail tier, Nitori Holdings Co., Ltd. and Ryohin Keikaku Co., Ltd. (MUJI) exemplify divergent strategies—Nitori through suburban network densification and MUJI through transparent material sourcing narratives. Toray Industries, Inc. anchors the technical fiber developer archetype through advanced polyester filament innovation. These three entities occupy positions that reflect the market's structural segmentation between mass-market volume, design-led premium positioning, and performance-driven material science.
| Leading Market Players |
|---|
| IKEA Japan K.K. |
| Toray Industries, Inc. |
| Nitori Holdings Co., Ltd. |
| Aeon Retail Co., Ltd. (Home Coordy) |
| Teijin Frontier Co., Ltd. |
| Nishikawa Co., Ltd. |
| Francfranc Corporation |
| Uchino Co., Ltd. |
| Ryohin Keikaku Co., Ltd. (MUJI) |
| Others |
Supply & Pricing Matrix
Automated cutting and sewing cells using computer vision guidance are compressing unit economics for made-to-measure curtain production while simultaneously concentrating technical capability among Osaka-based contract manufacturers with capital deployment capacity. This production-method transition simultaneously reshapes cost structures and supplier tiering as smaller operators face exclusion from hospitality procurement channels demanding scale and precision.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Kyoto ryokan operators pay markups for expedited linen delivery during renovation windows, while spot inventory of standard GSM towels trades at discounts through suburban supermarket channels. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified institutional bedding from residential retail grades and unbranded mass-market basics. Cost compression in mid-market polyester curtains is intensifying because METI-mandated recycled feedstock requalification adds processing overhead. Suburban family households in tertiary Kanto cities exhibit highest price sensitivity, whereas boutique hospitality procurement teams prioritize certification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from hospital procurement departments require textile suppliers to maintain qualified backup production lines across multiple prefectures, fragmenting volume concentration and elevating compliance documentation burdens. Raw cotton feedstock draws from India, the United States, and Australia, while chemically recycled polyester filament sources from domestic Toray Industries facilities and selected Southeast Asian chemical processors. Single-source vulnerability persists in organic cotton cultivation where limited certified acreage concentrates supply risk with specific import origins. Distribution runs through manufacturer-operated digital storefronts for residential subscription replenishment, while wholesale institutional channels service hospitality and healthcare bulk procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
METI's textile decarbonization framework operates as a cost-of-compliance moat, elevating capital barriers for non-compliant entrants while rewarding early movers with certified feedstock access and preferred procurement positioning.
For Market Incumbents: Deepen backward integration into mechanical recycling infrastructure to capture closed-loop feedstock from prefectural waste reduction ordinances in Saga and Nagasaki. Invest in shared renewable thermal systems across dye house clusters to defend margin position against energy efficiency equipment retrofitting mandates. The priority lever rests on JIS L testing laboratory accreditation that filters smaller competitors from hospital procurement channels. For New Entrants and Emerging Players: Direct-to-consumer digital storefronts offering subscription-style bedding replenishment represent the most penetrable route for circumventing Nitori's suburban retail dominance. Target single-person households in Saitama and Chiba commuter corridors where lease-aligned replacement cycles compress purchase intervals and brand loyalty remains undeveloped. The go-to-market angle centers on automated replenishment algorithms synchronized with apartment lease renewal rhythms. For Investors and Strategic Acquirers: Exit pathways concentrate in technical fiber developers with certified recycled polyester capabilities and established METI carbon labeling qualification. Long-term viability across the projection horizon favors manufacturers with captive supply of chemically recycled filament and shared infrastructure access in Kyoto dye house clusters. The signal to watch is bioplastic fiber certification timelines under developing PLA and PHA standards that will reshape premium positioning before mass-market commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Feedstock Certification | METI-mandated carbon labeling creates preferred supplier status for early qualified producers. |
| Shared Renewable Thermal Infrastructure | Kyoto dye house clusters aggregate biomass boiler investment to defray individual compliance costs. |
| Direct-to-Consumer Digital Launch | Manufacturer-operated storefronts bypass department store intermediation and capture subscription data. |
| JIS L Testing Laboratory Accreditation | Certification investment filters hospital procurement access and defends institutional market share. |
| Automated Production Cell Deployment | Osaka contract producers reduce labor dependency in high-mix, low-volume curtain manufacturing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with textile manufacturing executives, hospitality procurement managers, dye house operations directors, and retail category buyers. METI energy efficiency labeling disclosures, JIS L standards documentation, Fire Service Law compliance filings, and prefectural waste reduction ordinance texts provided regulatory boundary conditions. Bottom-up volume modeling across product categories triangulated against top-down market sizing from production cluster output data.
Data-stream reconciliation between import customs records and domestic manufacturing output statistics established baseline volume estimates across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-user channel, and distribution format, with carbon intensity scoring under METI's textile decarbonization framework as an industry-specific overlay. CAGRs derived from historical replacement cycle analysis and regulatory-driven feedstock transition timelines, incorporating hospitality renovation pipeline data and residential lease turnover patterns.
The model holds under stable regulatory enforcement of METI carbon labeling and JIS testing protocols; deviation in recycled polyester feedstock availability or bioplastic certification timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Wool Dryer Ball Market
Home Textiles
Russia Home Textile Market
Home Textiles
Fabric Wash and Care Market
Home Textiles
Germany Home Textile Market
Home Textiles
Canada Home Textile Market
Home Textiles
Blanket Market
Home Textiles
India Home Textile Market
Home Textiles
Bangladesh Home Textile Market
Home Textiles
Plush Blanket Market
Home Textiles
Home Textile Products Market
Home Textiles
Home Textiles Market
Home Textiles
Mexico Home Textile Market
Home Textiles
United Kingdom Home Textile Market
Home Textiles
Saudi Arabia Home Textile Market
Home Textiles
Towel Market
Home Textiles
Asia-Pacific Home Textile Market