
 Solar Bench Market | 2026-2036
Solar Bench Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Bench Market Outlook
China's manufacturing corridor for photovoltaic-integrated street furniture is tilting toward higher automation and export capacity. EnGoPlanet leverages its vertically integrated solar module production to sustain cost advantages across European distribution channels. Strawberry Energy differentiates through proprietary energy management software that controls charging output and LED intensity. SEEDiA anchors its position in Central and Eastern European municipal tenders through localized assembly partnerships.
A solar bench is a street furniture unit integrating photovoltaic panels, energy storage cells, and electrical outlets to harvest sunlight and deliver off-grid power for device charging, lighting, or connectivity services. Typical units incorporate monocrystalline silicon panels rated between 60 and 150 watts, paired with lithium iron phosphate batteries rated for thousands of cycles, all housed in weather-treated aluminum or steel frames engineered for vandal resistance and pedestrian safety. Smart benches and charging stations represent the segments where margin pools concentrate, as municipalities prioritize Wi-Fi connectivity and USB-C fast-charging ports over passive seating. Fixed installation dominates current procurement volumes, though retrofits are gaining traction where existing benches require electrical augmentation without full replacement.
The European Union's F-Gas Regulation and Ecodesign Directive constrain refrigerant and standby-power thresholds for integrated cooling components, while CE marking mandates govern electrical safety and electromagnetic compatibility for grid-adjacent installations. The US Federal Communications Commission and Occupational Safety and Health Administration set parallel benchmarks for RF emissions and workplace electrical safety that shape product design for North American export variants. Stakeholders must monitor evolving battery recycling mandates and interconnection standards as procurement specifications harden around circularity and cybersecurity credentials.
Market Dynamics
Municipal procurement departments now mandate Wi-Fi connectivity and USB-C fast-charging as baseline specifications, compressing margins for passive seating-only suppliers while rewarding integrated smart-bench vendors with recurring service revenue streams.
Growth Catalysts
- EU Green Deal implementation:National smart-city mandates in Germany, France, and the United Kingdom require off-grid street furniture in new urban developments, creating guaranteed demand pools for photovoltaic-integrated seating.
- Monocrystalline silicon efficiency gains:Panel wattage ratings between 60 and 150 watts now deliver sufficient charging capacity for multiple simultaneous users, expanding addressable use cases beyond basic phone charging.
- Lithium iron phosphate chemistry maturation:Battery cycle life extending into thousands of charge-discharge rounds reduces total cost of ownership calculations for municipal finance departments evaluating ten-year procurement horizons.
Market Restraints
- Aluminum and steel input volatility:Weather-treated frame materials face commodity price swings that compress fabrication margins before products reach distribution channels.
- CE marking electromagnetic compatibility testing:Grid-adjacent installation requirements add certification timelines and third-party laboratory costs that deter smaller fabricators from European market entry.
- Vandalism repair cost structures:Pedestrian safety engineering and damage-resistant housing specifications raise unit production costs above conventional bench replacement budgets in some municipalities.
Strategic Opportunities
- Retrofit electrical augmentation:Existing bench infrastructure in aging urban cores presents addressable white space where partial electrical upgrades avoid full replacement capital expenditure.
- Central and Eastern European municipal tenders:Localized assembly partnerships reduce logistics costs and satisfy domestic content preferences in Polish, Czech, and Romanian procurement frameworks.
- F-Gas Regulation compliance differentiation:Integrated cooling components that meet Ecodesign Directive standby-power thresholds command specification premiums in heat-stressed Southern European deployments.
Industry Challenges
- Cybersecurity credential integration:Hardening Wi-Fi connectivity modules against municipal network intrusion requires embedded systems expertise scarce among traditional street furniture fabricators.
- Circular battery recovery logistics:Emerging recycling mandates demand reverse supply chain capabilities that most vendors have not yet constructed for distributed urban installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Bench Market |
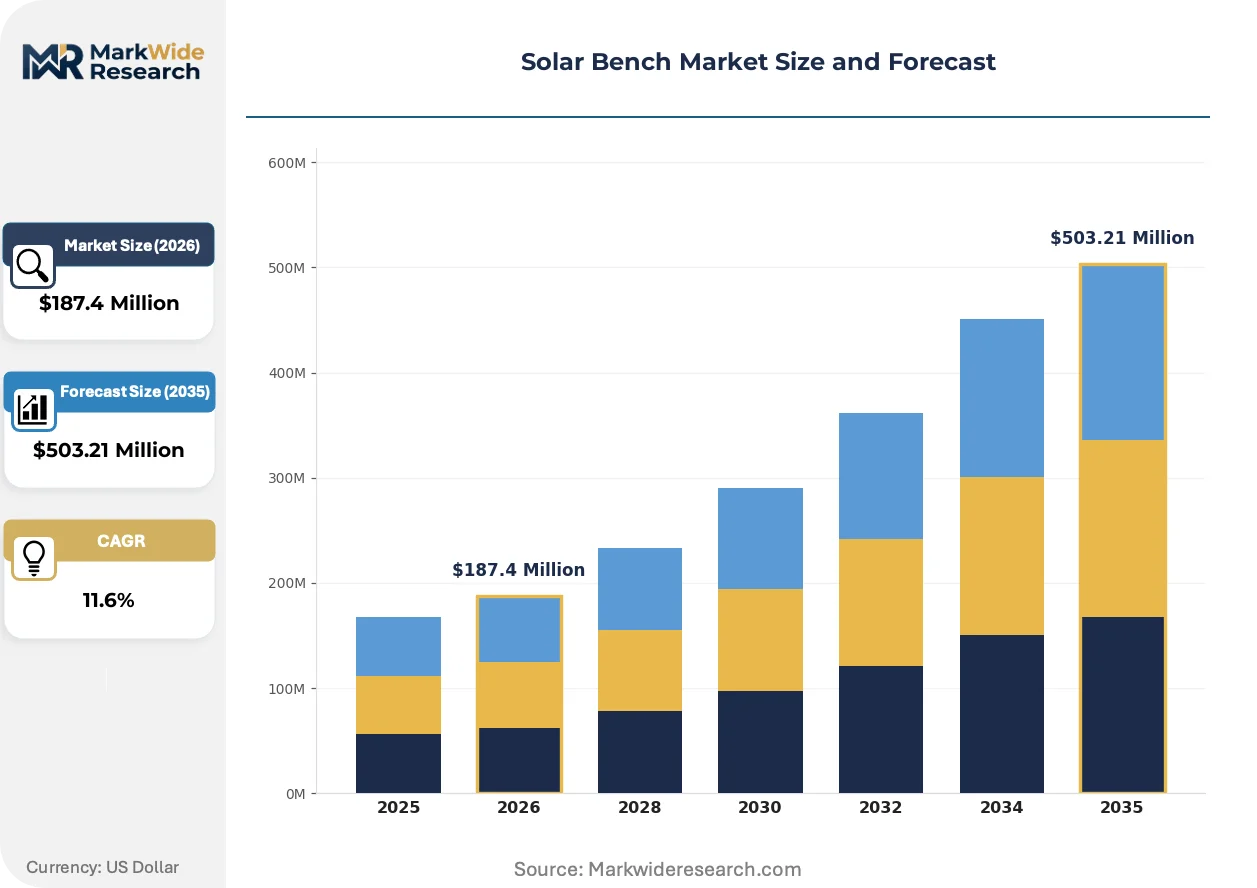
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simple Benches, Charging Stations, Smart Benches, Modular Benches End User: Parks, Universities, Public Spaces, Transportation Hubs Technology: Solar Panels, Energy Storage Systems, LED Lighting, Wi-Fi Connectivity Installation Type: Fixed Installation, Portable Installation, Custom Installation, Retrofits |
| Companies Covered | InfraMarks, Foshan Nanhai Guose Intelligent Facilities, EnGoPlanet, GreenTech Solar Solutions, Yantai Luhao Lighting, Strawberry Energy, Include, EcoBench Inc., SEEDiA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Bench Market Strategic Shifts
Photovoltaic street furniture is converging with digital service platforms, transforming benches from passive infrastructure into networked edge-computing nodes that generate recurring revenue through connectivity subscriptions rather than one-time hardware sales.
Perovskite-silicon tandem cell architectures are hybridizing with conventional monocrystalline modules in next-generation bench designs, enabling higher energy yield per surface area in variable light conditions. German urban planners are piloting these configurations in shaded plaza installations where traditional panels underperform. The technology is hybridizing product categories by merging seating, charging, and micro-grid storage functions into unified capital expenditure line items.
The European Union's F-Gas Regulation is tightening refrigerant thresholds for integrated cooling components, forcing redesign of thermal management systems in Southern European deployments. Manufacturers must now substitute alternative cooling methods or absorb compliance costs. Mediterranean municipalities are responding by prioritizing specifications that explicitly reference Ecodesign Directive standby-power limits in tender documents.
Municipal procurement departments are consolidating vendor relationships around integrated service contracts that bundle hardware, connectivity, and maintenance into multi-year subscriptions. Traditional bench suppliers without software capabilities are losing specification battles to technology-integrated competitors. This consolidation is most visible in French and British smart-city frameworks where outcome-based contracting now dominates central urban district renewals.
Solar Bench Market Segmentation
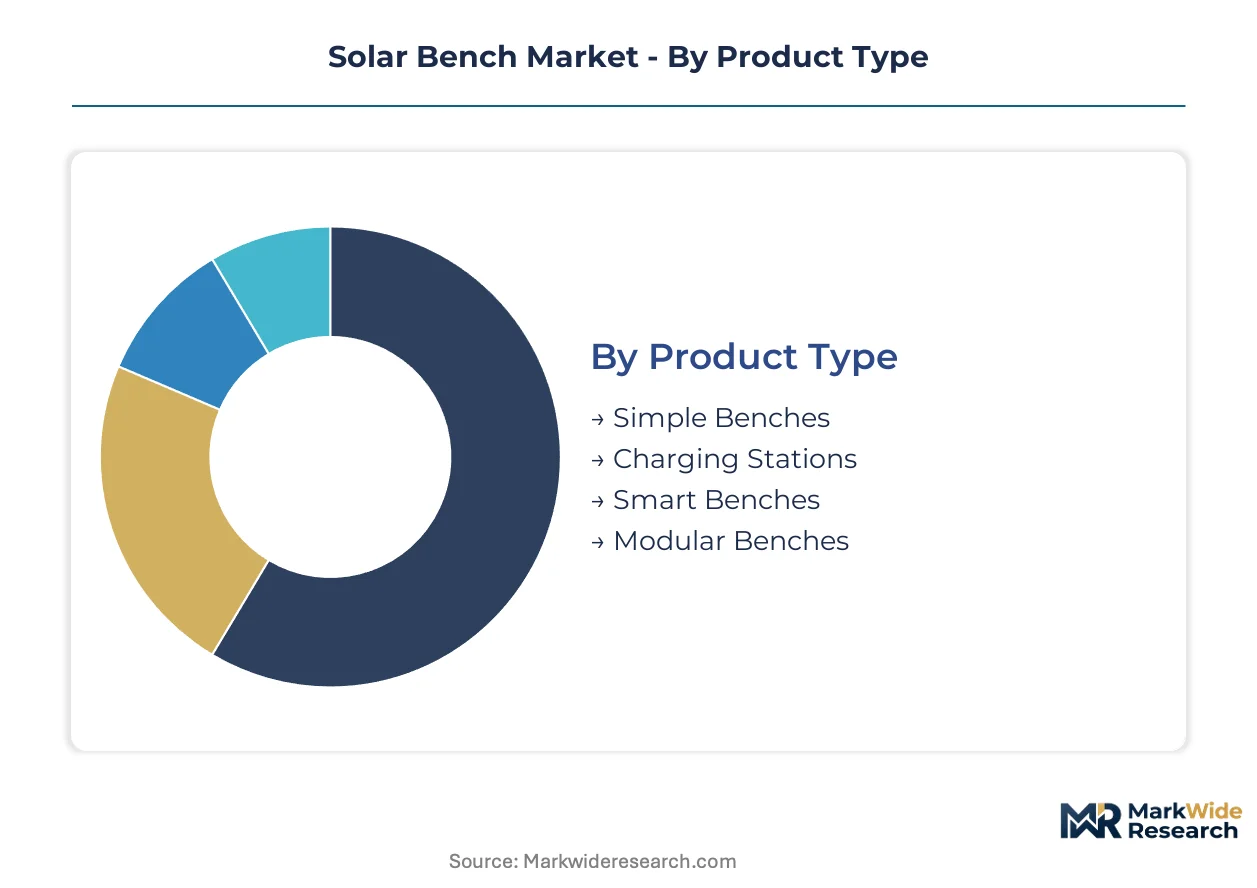
Solar bench segmentation reveals divergent margin structures across hardware complexity tiers. Municipal procurement patterns favor integrated solutions over passive seating, while retrofit pathways unlock aging urban infrastructure.
Product Type:
Mature configurations dominate current procurement volumes, yet emerging smart variants capture specification premiums in competitive tenders.
- Smart Benches:Integrated photovoltaic arrays, lithium iron phosphate storage, and edge-computing modules deliver USB-C fast-charging, Wi-Fi hotspots, and environmental sensors through unified aluminum housings. German and French municipal frameworks now mandate these specifications for central district renewals, compressing margins for passive competitors while generating recurring software revenue streams.
- Charging Stations:Purpose-built units prioritize power delivery over seating ergonomics, incorporating 60-150 watt monocrystalline panels with dedicated device docks. Transportation hubs in the United Kingdom specify these for passenger dwell zones where seating is secondary to connectivity.
- Simple Benches:Basic photovoltaic integration without active electronics serves cost-constrained parks and trail networks.
- Modular Benches:Configurable panel and battery arrays allow capacity scaling across plaza footprints.
Smart benches handle the majority of throughput; charging stations are expanding most quickly on share.
End User:
Customer-type concentration shapes pricing power, with institutional buyers commanding volume discounts unavailable to fragmented municipal purchasers.
- Public Spaces:City-center plazas and pedestrian zones drive specification intensity, requiring vandal-resistant steel framing, CE-marked electromagnetic compatibility, and cybersecurity-hardened connectivity modules. Procurement departments in Paris, Berlin, and London bundle hardware with multi-year maintenance subscriptions.
- Transportation Hubs:Rail stations and airports prioritize rapid device charging for transient populations, favoring high-output configurations with minimal seating depth. Battery cycle life specifications extend into thousands of charge-discharge rounds to satisfy ten-year capital planning horizons.
- Parks:Recreational deployments accept lower panel wattage where shade tolerance matters less than capital cost containment.
- Universities:Campus procurement favors aesthetic customization and branding integration over raw technical specifications.
Public spaces anchor procurement volume; transportation hubs are climbing the fastest on specification intensity.
Technology:
Component integration depth determines vendor differentiation, with energy management software displacing hardware-only positioning.
- Solar Panels:Monocrystalline silicon dominates at 60-150 watt ratings, though perovskite-silicon tandem architectures are hybridizing into shaded plaza designs. German pilots validate higher energy yield per surface area where conventional panels underperform.
- Energy Storage Systems:Lithium iron phosphate chemistry delivers thousands of cycles with thermal stability superior to alternative chemistries, satisfying EU battery recycling pre-positioning requirements.
- Wi-Fi Connectivity:Municipal network integration demands embedded cybersecurity credentials scarce among traditional fabricators.
- LED Lighting:Integrated illumination extends usable hours while satisfying Ecodesign Directive standby-power thresholds.
Energy storage systems handle the majority of bill-of-materials value; Wi-Fi connectivity is gaining share fastest on margin contribution.
Installation Type:
Deployment flexibility opens retrofit pathways that avoid full replacement capital expenditure in aging urban cores.
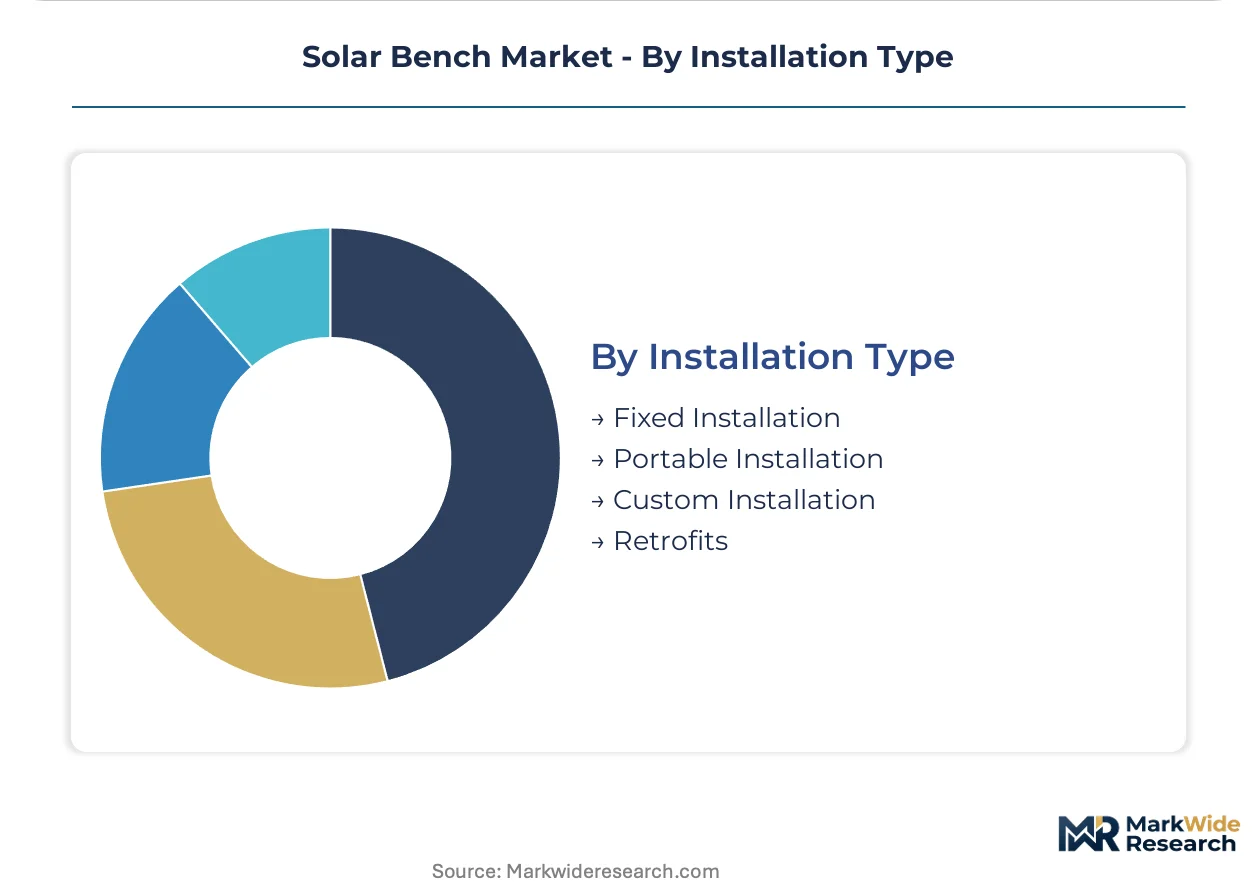
- Fixed Installation:Permanent anchoring in new developments captures the largest procurement volumes, with aluminum and steel frames engineered for pedestrian safety and vandal resistance. CE marking mandates govern electrical safety and electromagnetic compatibility for grid-adjacent deployments.
- Retrofits:Electrical augmentation of existing bench infrastructure addresses Central and Eastern European municipal budgets where full replacement is capital-constrained. Localized assembly partnerships in Poland, Czech Republic, and Romania reduce logistics costs and satisfy domestic content preferences.
- Portable Installation:Temporary deployments serve event infrastructure and construction staging zones.
- Custom Installation:Bespoke configurations accommodate heritage district aesthetic requirements or irregular site geometries.
Fixed installation handles the majority of throughput; retrofits are gaining share fastest on addressable market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European procurement volumes for photovoltaic-integrated street furniture, while manufacturing scale concentrates in China's Yangtze River Delta corridor. Municipal specifications in Germany, France, and the United Kingdom harden around cybersecurity credentials and circular battery recovery mandates.
Germany
Berlin and Munich municipal frameworks mandate Wi-Fi connectivity and USB-C fast-charging in central district renewals. The national smart-city program under the EU Green Deal requires off-grid street furniture in new urban developments. Bavarian urban planners pilot perovskite-silicon tandem configurations in shaded plaza installations where conventional monocrystalline panels underperform.
France
Paris procurement departments bundle hardware with multi-year maintenance subscriptions, consolidating vendor relationships around integrated service contracts. The Ecodesign Directive constrains standby-power thresholds for integrated cooling components in Southern European deployments. Lyon and Marseille specifications explicitly reference F-Gas Regulation compliance for thermal management systems.
United Kingdom
Transportation hubs in London and Manchester prioritize rapid device charging for transient populations, favoring high-output configurations with minimal seating depth. CE marking mandates govern electromagnetic compatibility for grid-adjacent installations. British smart-city frameworks now dominate central urban district renewals through outcome-based contracting models.
Poland
Warsaw and Kraków municipal tenders favor localized assembly partnerships that reduce logistics costs and satisfy domestic content preferences. Central and Eastern European budgets address retrofit electrical augmentation where full replacement capital expenditure is constrained. Polish procurement frameworks accelerate bench deployments in aging urban cores.
China
Foshan and Yantai manufacturing clusters tilt toward higher automation and export capacity for photovoltaic-integrated street furniture. The country's dual carbon goals reshape product specifications for international distribution channels. Yangtze River Delta fabricators sustain cost advantages through vertically integrated solar module production.
Solar Bench Market Competitive Environment
Capability concentration sits with technology-integrated vendors; scale advantage sits with manufacturing corridor incumbents. The vendor base organizes around three strategic archetypes: vertically integrated solar producers, proprietary software specialists, and localized assembly partners. Consolidation pressures mount as municipal procurement departments mandate bundled hardware-connectivity-maintenance contracts. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into energy management software.
Among European specialists, Strawberry Energy and SEEDiA occupy positions within the software-integrated tier, while EnGoPlanet exemplifies the vertically integrated archetype with manufacturing rooted in the Yangtze River Delta corridor. These three anchors represent contrasting pathways to specification compliance: proprietary energy management systems, localized tender participation, and captive solar module production. Chinese fabricators Foshan Nanhai Guose Intelligent Facilities and Yantai Luhao Lighting sit within the scale-driven manufacturing tier, supplying export markets through established distribution channels.
| Leading Market Players |
|---|
| InfraMarks |
| Foshan Nanhai Guose Intelligent Facilities |
| EnGoPlanet |
| GreenTech Solar Solutions |
| Yantai Luhao Lighting |
| Strawberry Energy |
| Include |
| EcoBench Inc. |
| SEEDiA |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta solar module production clusters concentrate upstream supply, anchoring margin pools in energy management software and multi-year municipal service contracts rather than hardware fabrication alone.
Pricing Analysis
Chinese-manufactured units trade at substantial discounts to European-assembled equivalents, though CE marking and cybersecurity certification premiums compress that spread for grid-adjacent deployments. Pricing stratifies across premium smart-bench tiers with bundled connectivity subscriptions, standard fixed-installation configurations, and economy simple-bench variants for cost-constrained parks. Cost compression in the economy tier is intensifying because aluminum and steel commodity volatility erodes fabrication margins before products reach distribution channels. Municipal procurement departments exhibit the least price sensitivity when specifications mandate Wi-Fi connectivity and USB-C fast-charging, while parks and trail networks represent the most price-sensitive buyer segment.
Supply Chain Analysis
Export-control restrictions on advanced photovoltaic manufacturing equipment limit technology transfer to emerging production hubs outside China. Module assembly draws from monocrystalline silicon wafer supply concentrated in China, South Korea, and Malaysia, with lithium iron phosphate cells sourced predominantly from Chinese and South Korean producers. Single-source vulnerability sits with Yangtze River Delta fabricators that dominate both solar module and battery cell production. Distribution runs through European distribution partnerships for German, French, and British municipal tenders, supplemented by localized assembly partnerships in Poland and Romania for Central and Eastern European procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
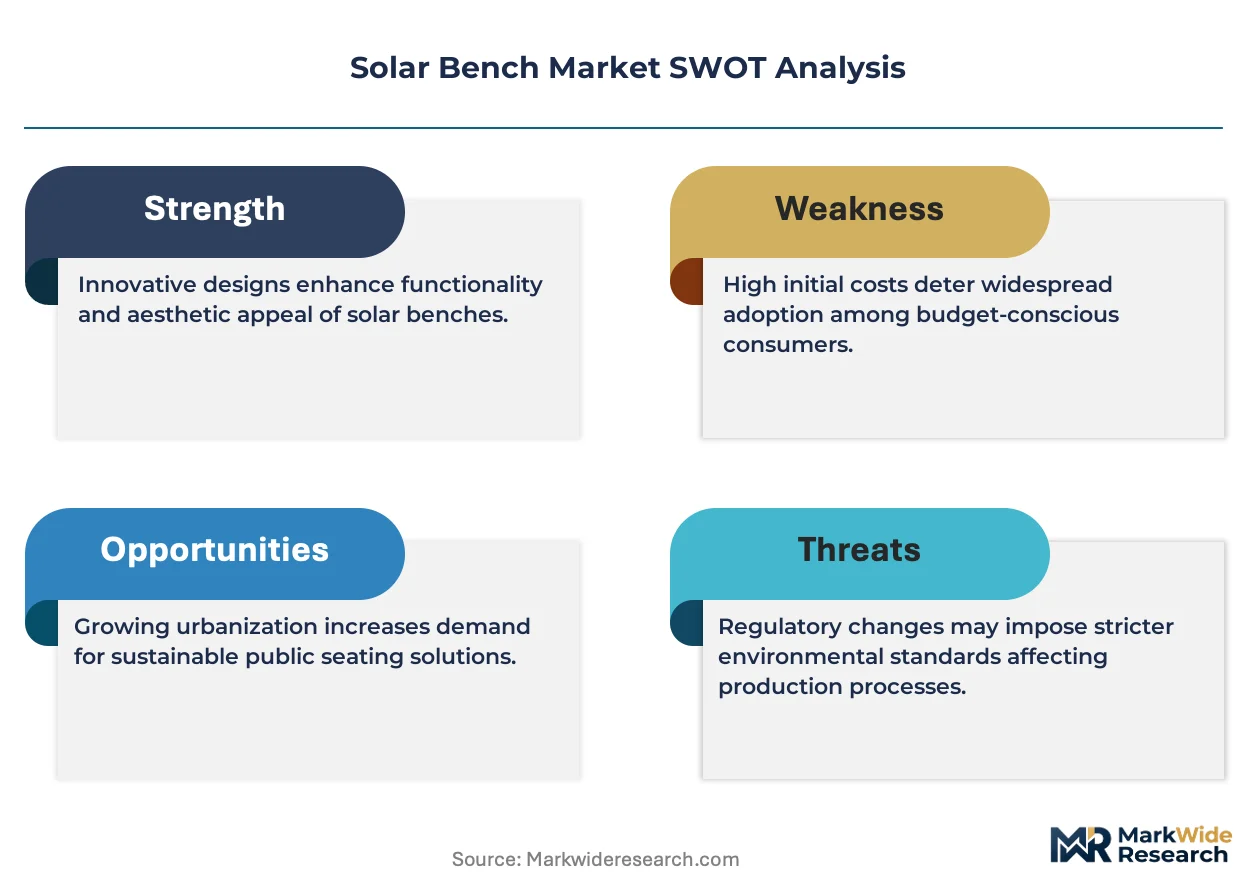
Incumbent solar bench vendors face substitution pressure from conventional street furniture suppliers that bolt on third-party charging modules, threatening to commoditize hardware margins while service revenues concentrate with software-integrated competitors.
For Market Incumbents: Entrench specification control by embedding proprietary energy management systems that lock municipalities into recurring subscription revenue streams. Deepen captive supply of lithium iron phosphate cells through backward integration into battery partnerships, insulating against cell price volatility that threatens ten-year total cost of ownership calculations. Defend against conventional furniture fabricators by accelerating cybersecurity credential integration that traditional competitors cannot replicate.
For New Entrants and Emerging Players: Build out retrofit electrical augmentation capabilities targeting aging urban cores in Central and Eastern Europe where full replacement capital expenditure is constrained. Prioritize Polish, Czech, and Romanian municipal tenders that favor localized assembly partnerships satisfying domestic content preferences. Establish go-to-market positioning through outcome-based contracting models that bundle hardware, connectivity, and maintenance into multi-year subscriptions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with software-integrated specialists like Strawberry Energy that have scaled proprietary energy management platforms but lack manufacturing scale. Long-term viability hinges on municipal procurement consolidation around bundled service contracts rather than transactional hardware sales. Watch for inflection signals in F-Gas Regulation compliance premiums as Southern European municipalities prioritize Ecodesign Directive standby-power thresholds in tender specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Energy Management Platform Development | Locks municipalities into recurring subscription revenue streams that hardware-only competitors cannot replicate. |
| Backward Integration into Battery Cell Supply | Secures lithium iron phosphate cell access against price volatility threatening ten-year procurement calculations. |
| Localized Assembly Partnership Expansion | Satisfies domestic content preferences in Polish, Czech, and Romanian municipal tender frameworks. |
| Cybersecurity Credential Hardening | Meets CE marking and GDPR-adjacent requirements that traditional street furniture fabricators cannot satisfy. |
| Outcome-Based Contracting Model Adoption | Aligns vendor incentives with municipal smart-city performance metrics in French and British frameworks. |
Study Parameters
Cross-validation between municipal procurement officer interviews and solar bench manufacturer technical disclosures anchors the qualitative findings in operational reality. Primary fieldwork encompassed urban planners in Berlin, Paris, London, Warsaw, and Kraków; distribution channel partners serving Central and Eastern European markets; and energy management software engineers at integrated vendors. Secondary validation drew from EU tender documentation databases, F-Gas Regulation implementation guidance, CE marking electromagnetic compatibility standards, and customs records tracking photovoltaic-integrated street furniture trade flows. Bottom-up unit economics modeling triangulates against top-down municipal capital expenditure projections.
Calibration against historical deployment trajectories in German and French smart-city frameworks validates forward-looking assumptions across the analysis window. Segmentation dimensions span product type complexity tiers, end-user procurement intensity, installation modality flexibility, and regional regulatory stringency. CAGRs derive from fitted adoption curves weighted by municipal budget cycle timing and EU Green Deal implementation pacing. Industry-specific inputs include monocrystalline silicon efficiency improvement curves and lithium iron phosphate cycle life degradation models.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese manufacturing corridor entrants into direct European distribution would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Smart Solar Solutions Market
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Solar Polysilicon Ingot Wafer Cell Module Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
Solar Photovoltaic (PV) Market