
 Spain Big Data Analytics in Energy Market | 2026-2036
Spain Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Big Data Analytics in Energy Market Insights
Platform modularization is rebalancing procurement patterns as Spanish energy firms unbundle monolithic analytics suites into interoperable components. Iberdrola leverages its in-house digital unit to sustain proprietary forecasting capabilities across renewable portfolios. Endesa anchors its competitive stance through cloud-native deployment architectures that reduce latency for real-time grid operations. Naturgy differentiates by specializing in demand-response algorithms tailored to Iberian market coupling dynamics.
Big data analytics in energy encompasses the computational processing of heterogeneous datasets from generation assets, transmission networks, metering infrastructure, and market transactions to extract actionable intelligence for operational and strategic decisions. Core functional parameters include sub-second stream processing for grid frequency management and machine learning pipelines trained on multi-year generation profiles. Predictive analytics leads current product configurations as utilities prioritize outage prevention and renewable intermittency smoothing. Cloud-based deployment exhibits the fastest structural expansion as Spain's electricity system operator accelerates data federation requirements. Edge computing occupies emerging margin pools where latency-sensitive applications such as distributed energy resource coordination command premium pricing.
Spain's National Markets and Competition Commission and the Ministry for the Ecological Transition jointly enforce grid code compliance that mandates telemetry standards and data interoperability for market participants. The EU AI Act and GDPR frameworks impose algorithmic transparency and data governance obligations on automated energy trading and consumer analytics platforms. Stakeholders must monitor evolving cybersecurity certification requirements under the NIS2 Directive as critical energy infrastructure designation expands to encompass cloud-hosted analytics environments.
Market Dynamics
Spain's electricity system operator is accelerating data federation mandates that force utilities to unify telemetry from distributed generation assets, creating structural pressure on legacy analytics architectures.
Growth Catalysts
- EU AI Act compliance deadlines:Automated trading platforms face algorithmic transparency mandates that drive investment in interpretable machine learning pipelines for energy markets.
- Grid-scale battery deployment:Utility-scale storage operators require predictive analytics for arbitrage optimization and degradation forecasting across Iberian market coupling zones.
- Madrid-Barcelona corridor concentration:Headquarters clustering of major utilities creates dense ecosystems for analytics vendor pilot programs and rapid procurement cycles.
Market Restraints
- GDPR data governance friction:Consumer analytics platforms face restricted cross-border data flows that complicate centralized model training for demand-response algorithms.
- Cloud infrastructure concentration:Critical energy infrastructure designation under NIS2 Directive limits vendor choice to certified hyperscale providers with Spanish sovereign cloud presence.
- Legacy SCADA integration costs:Brownfield substations require expensive protocol translation layers that extend deployment timelines for real-time analytics.
Strategic Opportunities
- Andalusian solar corridor underpenetration:Concentrated photovoltaic zones lack localized edge computing nodes for inverter-level optimization and predictive maintenance.
- Demand-response algorithm specialization:Iberian market coupling dynamics create premium niches for firms mastering cross-border balancing mechanism forecasting.
- Basque Country industrial load aggregation:Energy-intensive manufacturing clusters present untapped potential for behind-the-meter analytics and peak shaving services.
Industry Challenges
- Data engineering talent scarcity:Spanish utilities compete with fintech and telecom sectors for stream processing specialists capable of sub-second grid frequency management.
- Multi-year model retraining cycles:Renewable generation profiles require continuous pipeline updates that strain MLOps infrastructure and operational budgets.
- Cybersecurity certification bottlenecks:ENCS membership and EUCC certification timelines delay commercial deployment of cloud-hosted analytics environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Big Data Analytics in Energy Market |
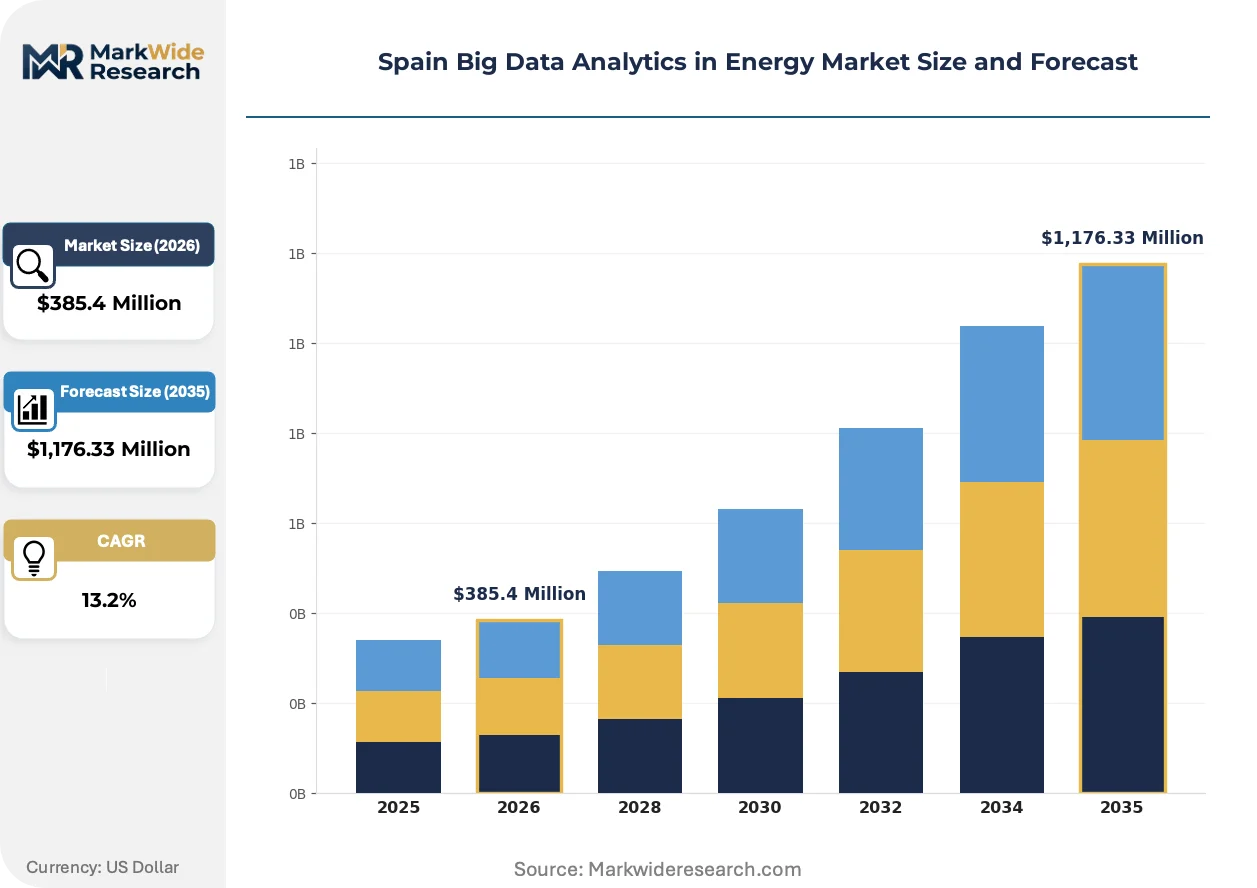
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,176.33 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predictive Analytics, Data Management, Visualization Tools, Reporting Solutions End User: Utilities, Energy Producers, Government Agencies, Research Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Application: Demand Forecasting, Asset Management, Risk Assessment, Performance Optimization |
| Companies Covered | Iberdrola, Endesa, EDP Renováveis, Acciona Energía, Naturgy, Repsol, OMIE, Baobab Soluciones, Aurora Energy Research, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Big Data Analytics in Energy Market Trends and Innovations
Computational architectures for energy analytics are fragmenting into specialized layers as latency requirements diverge across grid operations, trading floors, and consumer platforms.
Stream processing infrastructure is modularizing into interoperable components that separate ingestion, transformation, and inference workloads. Spanish utilities deploying these architectures achieve faster vendor substitution and reduced lock-in. The unbundling is compressing pricing power for integrated analytics suites while elevating specialist providers in specific functional layers.
Spain's Ministry for the Ecological Transition enforces grid code compliance through telemetry standards that mandate data interoperability for market participants. The regulation forces incumbent utilities to expose operational datasets to third-party analytics providers. Renewable asset managers and independent aggregators gain competitive leverage through access to previously siloed transmission network data.
Utility procurement of analytics capabilities is fragmenting from enterprise-wide licenses toward component-based subscriptions. Madrid-based grid operators pilot modular contracts for specific functions such as renewable forecasting or outage prediction. The shift disintermediates traditional systems integrators and elevates direct relationships between utility data science teams and specialized algorithm vendors.
Spain Big Data Analytics in Energy Market Segmentation
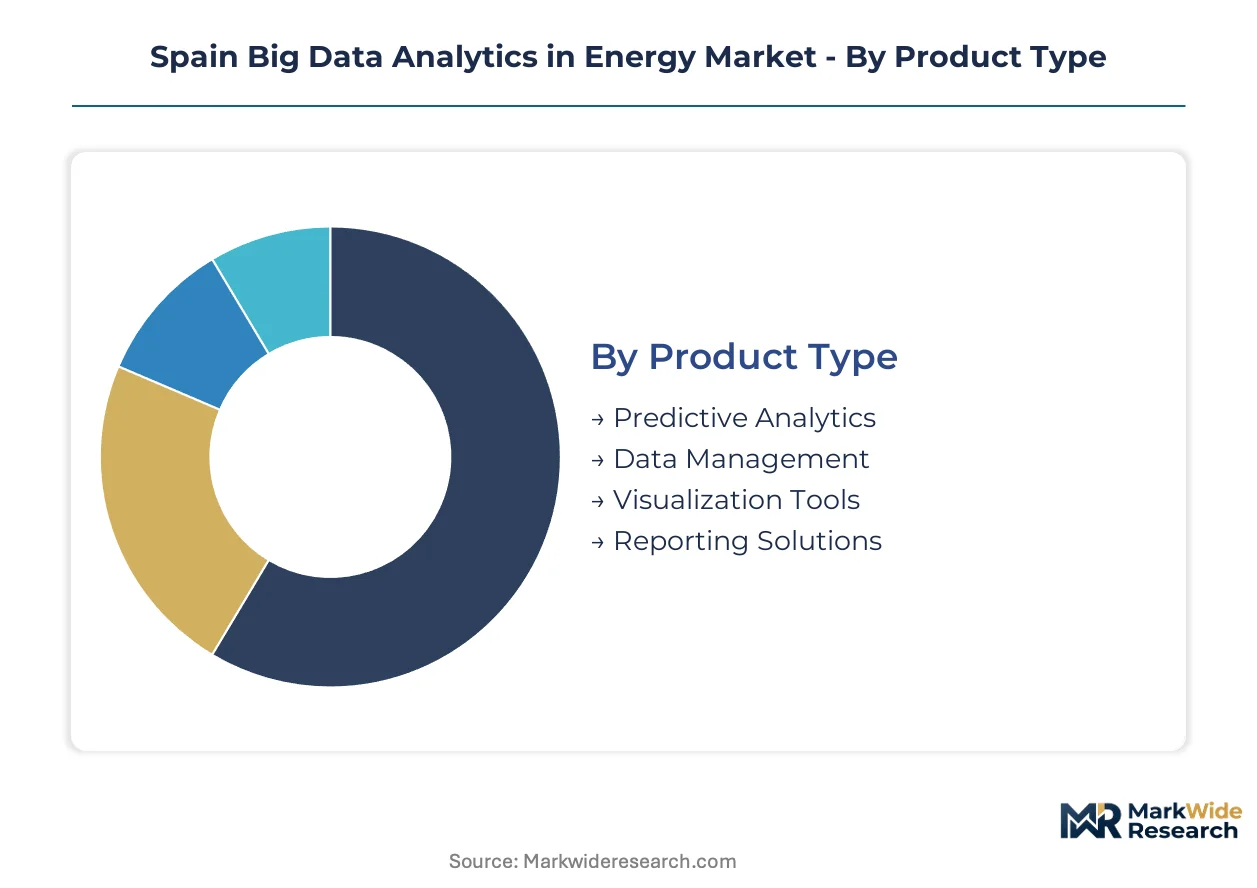
Spanish energy firms unbundle procurement across specialized analytics layers. Each segmentation dimension reveals distinct concentration patterns between established utility incumbents and emerging aggregator business models.
Product Type:
Predictive analytics commands premium pricing while visualization tools drive volume deployment across Iberian utilities.
- Predictive Analytics:Machine learning pipelines trained on multi-year generation profiles enable outage prevention and renewable intermittency smoothing. Madrid-based grid operators prioritize these capabilities for sub-second frequency management under Spain's National Integrated Energy and Climate Plan mandates.
- Data Management:Stream processing infrastructure unifies telemetry from distributed solar and wind assets. Barcelona utility headquarters drive demand for federated data lakes that comply with EU AI Act algorithmic transparency requirements.
- Visualization Tools:Dashboard layers for real-time grid monitoring.
- Reporting Solutions:Regulatory compliance documentation for CNMC grid code submissions.
Mature deployment sits with visualization and reporting tools. Newer deployment is concentrated in predictive analytics pipelines.
End User:
Utility procurement dominates contract value while energy producers represent the fastest-expanding customer type.
- Utilities:Iberdrola and Endesa anchor enterprise-wide analytics adoption through in-house digital units and cloud-native architectures. These firms mandate interoperability standards that reshape vendor qualification criteria across the Spanish market.
- Energy Producers:Independent renewable asset managers leverage newly accessible transmission network data under grid code reforms. Andalusian solar corridor developers pilot edge computing nodes for inverter-level optimization without legacy SCADA dependencies.
- Government Agencies:Ministry for the Ecological Transition monitors grid compliance telemetry.
- Research Institutions:Basque Country technical universities prototype demand-response algorithms.
Established procurement patterns favor utilities. Emerging deployment concentrates with energy producers seeking competitive leverage through data federation.
Deployment:
Cloud architectures capture growth while on-premise installations retain mission-critical workloads.
- Cloud-Based:Spain's electricity system operator accelerates data federation requirements that favor hyperscale environments. NIS2 Directive cybersecurity certifications constrain vendor selection to providers with Spanish sovereign cloud presence.
- Edge Computing:Latency-sensitive applications command premium pricing in distributed energy resource coordination. Andalusian photovoltaic zones and Basque industrial load clusters present localized deployment opportunities.
- On-Premise:Brownfield substations with legacy protocol translation layers.
- Hybrid:Split architectures separating consumer analytics from operational technology networks.
Conservative deployment remains on-premise. Steepest expansion trajectory belongs to cloud-based and edge computing configurations.
Application:
Asset management generates recurring revenue while demand forecasting attracts venture-backed specialization.
- Asset Management:Predictive maintenance algorithms for grid-scale battery degradation forecasting. Iberian market coupling dynamics create arbitrage optimization opportunities across utility-scale storage operators.
- Demand Forecasting:Cross-border balancing mechanism forecasting for demand-response aggregators. Madrid-Barcelona corridor clustering enables rapid pilot-to-deployment cycles for algorithm vendors.
- Risk Assessment:Cybersecurity posture monitoring for NIS2 compliance.
- Performance Optimization:Real-time grid frequency management for transmission system operations.
Proven deployment concentrates in asset management. Emerging specialization clusters around demand forecasting for market coupling participation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's big data analytics in energy market concentrates production of algorithmic solutions in Madrid and Barcelona while consumption spreads across generation corridors and industrial load centers. The production-consumption divide shapes vendor deployment strategies and infrastructure investment patterns.
Madrid
Utility headquarters clustering drives concentrated demand for predictive analytics and grid optimization platforms. Spain's National Markets and Competition Commission enforces telemetry standards that mandate data interoperability for market participants headquartered in the capital. The Madrid metropolitan area anchors procurement cycles for enterprise-wide analytics suites serving Iberdrola and Endesa operations.
Catalonia
Barcelona's technology ecosystem supports specialized analytics vendors and cloud-native deployment architectures. The Catalan government's digital innovation programs subsidize edge computing pilot projects for distributed energy resource coordination. Barcelona utility headquarters accelerate procurement for real-time grid operations with reduced latency requirements.
Andalusia
Concentrated photovoltaic zones in the southern region generate demand for localized edge computing nodes and inverter-level optimization. Spain's Ministry for the Ecological Transition channels grid code compliance investments toward telemetry infrastructure in high-renewable penetration areas. The Andalusian solar corridor presents deployment opportunities for predictive maintenance algorithms without legacy SCADA dependencies.
Basque Country
Energy-intensive manufacturing clusters create demand for behind-the-meter analytics and peak shaving services. Regional industrial policy supports demand-response algorithm development through technical university partnerships. Bilbao and surrounding industrial zones concentrate procurement for load aggregation platforms serving steel and chemical processing facilities.
Valencia
Port and logistics infrastructure drives demand for energy management analytics in maritime electrification and cold chain operations. The regional government aligns digital infrastructure grants with National Integrated Energy and Climate Plan objectives. Valencia's emerging technology corridor attracts specialized vendors for hybrid cloud-edge deployments.
Spain Big Data Analytics in Energy Market Competitive Landscape
The competitive structure tilts toward integrated utility digital units over independent software vendors. Iberdrola and Endesa sustain in-house capabilities that reduce external procurement for core forecasting functions. Three archetypes dominate: utility captive units, specialized algorithm vendors, and hyperscale cloud providers with sovereign infrastructure. M&A activity concentrates on acquiring data engineering talent, while strategic partnerships focus on edge computing deployment for distributed asset portfolios.
Among utility-based competitors, Iberdrola and Endesa exemplify the captive digital unit archetype through proprietary forecasting capabilities and cloud-native architectures. Naturgy occupies a position specializing in demand-response algorithms. Independent specialists including Baobab Soluciones and Aurora Energy Research represent the vendor tier serving utilities without full in-house capabilities. OMIE anchors the market infrastructure layer through data federation requirements that shape vendor qualification criteria.
| Leading Market Players |
|---|
| Iberdrola |
| Endesa |
| EDP Renováveis |
| Acciona Energía |
| Naturgy |
| Repsol |
| OMIE |
| Baobab Soluciones |
| Aurora Energy Research |
| Others |
Pricing and Supply Chain Analysis
Data engineering talent concentration in Madrid and Barcelona drives labor-cost differentials that widen pricing-tier spreads between premium algorithm vendors and standardized analytics components. Spanish utilities absorb these cost premiums for sub-second stream processing capabilities while mid-tier buyers gravitate toward modular subscription tiers.
Pricing Analysis
Margin tightening in cloud-native deployment tiers reflects hyperscale infrastructure certification requirements under NIS2 Directive cybersecurity mandates. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-cloud certified providers from uncertified alternatives and open-source toolchains. Cost-down pressure on visualization tools accelerates because Barcelona-based technology vendors commoditize dashboard layers. Energy producers exhibit highest price sensitivity due to thin margins on renewable asset operations, while transmission system operators demonstrate lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
Freight costs for edge computing hardware from Germany, Taiwan, and the USA inflate landed costs for Andalusian solar corridor deployments. Component dependencies rest on NVIDIA GPU accelerators, Intel Xeon processors, and specialized time-series database software. Single-source vulnerability concentrates in sovereign cloud infrastructure where only two hyperscale providers maintain Spanish-certified data centers. Distribution runs through Madrid-based systems integrators who bundle hardware procurement with algorithm customization services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Spain Big Data Analytics in Energy Market functions as a cost-of-compliance arena where EU AI Act algorithmic transparency mandates erect barrier-to-entry moats for vendors with interpretable machine learning pipelines. Incumbents possessing pre-certified architectures capture pricing power while challengers absorb compliance overhead.
For Market Incumbents: Cement market position by acquiring edge computing specialists in the Basque Country industrial corridor before NIS2 certification bottlenecks intensify. Deepen backward integration into stream processing infrastructure to reduce hyperscale cloud dependency. Prioritize MLOps capability retention as renewable generation profile retraining cycles strain operational budgets and create talent arbitrage opportunities. For New Entrants and Emerging Players: Cloud-native deployment specialists offer the most penetrable channel partnership avenue for bypassing Madrid-based incumbent procurement gatekeepers. Target Andalusian solar corridor developers seeking inverter-level optimization without legacy SCADA integration costs. Lead with demand-response algorithm specialization for Iberian market coupling zones where Naturgy's dominance remains incomplete. For Investors and Strategic Acquirers: Re-rating potential sits with specialized algorithm vendors possessing ENCS membership and EUCC certification progress given cybersecurity infrastructure designation expansion. Long-term viability favors firms with proven telemetry integration across brownfield substations. Watch for OMIE data federation mandate acceleration as the inflection signal for vendor qualification criteria tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Interpretability Investment | EU AI Act compliance deadlines force machine learning pipeline reconstruction for automated trading platforms. |
| Edge Computing Node Deployment | Andalusian photovoltaic zones require localized infrastructure for latency-sensitive distributed energy coordination. |
| Sovereign Cloud Certification | NIS2 Directive constraints limit vendor selection to hyperscale providers with Spanish data center presence. |
| Data Engineering Talent Acquisition | Competition with fintech and telecom sectors elevates compensation costs for stream processing specialists. |
| Modular Analytics Unbundling | Utility procurement shifts from enterprise licenses toward component subscriptions, disintermediating systems integrators. |
Research Methodology
CNMC regulatory filings, OMIE market data releases, and EU AI Act implementation guidance formed the secondary backbone for market sizing and compliance timeline validation. Primary interviews with utility planning officers, renewable asset managers, grid operators, and hyperscale cloud procurement leads combined with secondary sources through bottom-up and top-down triangulation. The analysis cross-referenced telemetry standard mandates from Spain's Ministry for the Ecological Transition against vendor deployment disclosures.
Bottom-up modeling aggregated individual utility procurement patterns across predictive analytics, data management, and visualization tiers while top-down verification anchored against National Integrated Energy and Climate Plan investment trajectories. Segmentation dimensions spanned product type, deployment architecture, end-user category, and application function across the projection horizon. CAGRs derived from utility capital expenditure disclosures and algorithm vendor contract value analysis, with renewable intermittency smoothing requirements and grid-scale battery deployment timelines serving as key demand-side inputs.
Several conditions sit outside the modeled scope, including potential GDPR enforcement shifts affecting cross-border model training and unanticipated cybersecurity certification timeline extensions. Forecasts reflect documented assumptions about regulatory compliance deadlines and technology adoption curves. Stakeholders should weight assumptions against their own operating context and monitor ENCS membership progression as a real-time validation metric.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Africa Big Data Analytics in Energy Market
Energy Analytics and Software
Smart Grid Software Market
Energy Analytics and Software
Automated Power Generation Dispatch Software Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Global Wind Turbine Condition Monitoring System Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
France Big Data Analytics in Energy Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Power Monitoring and Control Software Market
Energy Analytics and Software
Big Data in Oil and Gas Market