
 France Satellite-Based Earth Observation Market | 2026-2036
France Satellite-Based Earth Observation Market Size, Share, and Industry Trends Forecast 2026-2036
France Satellite-Based Earth Observation Market Insights
Subscription-based data processing and analytics delivery is repositioning how earth observation value reaches end users in France. Thales leverages its defense electronics heritage to anchor sovereign satellite manufacturing and secure government contracts. Airbus sustains leadership in high-resolution optical and radar payload development for both institutional and commercial buyers. KAYRROS competes through AI-driven environmental and energy analytics, differentiating its subscription offerings from raw imagery vendors.
France Satellite-Based Earth Observation encompasses the acquisition, transmission, and analysis of geospatial data from orbiting platforms carrying optical, radar, hyperspectral, or LIDAR sensors, typically operating at altitudes between 400 and 800 kilometers with spatial resolutions ranging from sub-meter to tens of meters. These systems serve defense planning, climate monitoring, infrastructure management, and natural resource assessment through repeatable, wide-area coverage unavailable from aerial or ground-based alternatives. Environmental Monitoring applications lead current deployment volumes as drought tracking and carbon verification obligations expand, while Hyperspectral technology represents the fastest-growing sensor category due to its material identification capabilities for agriculture and mineral exploration. Government Agencies remain the dominant end-user channel, though margin pools are shifting toward Data Processing and Custom Solutions as downstream analytics capture greater value than raw imagery sales.
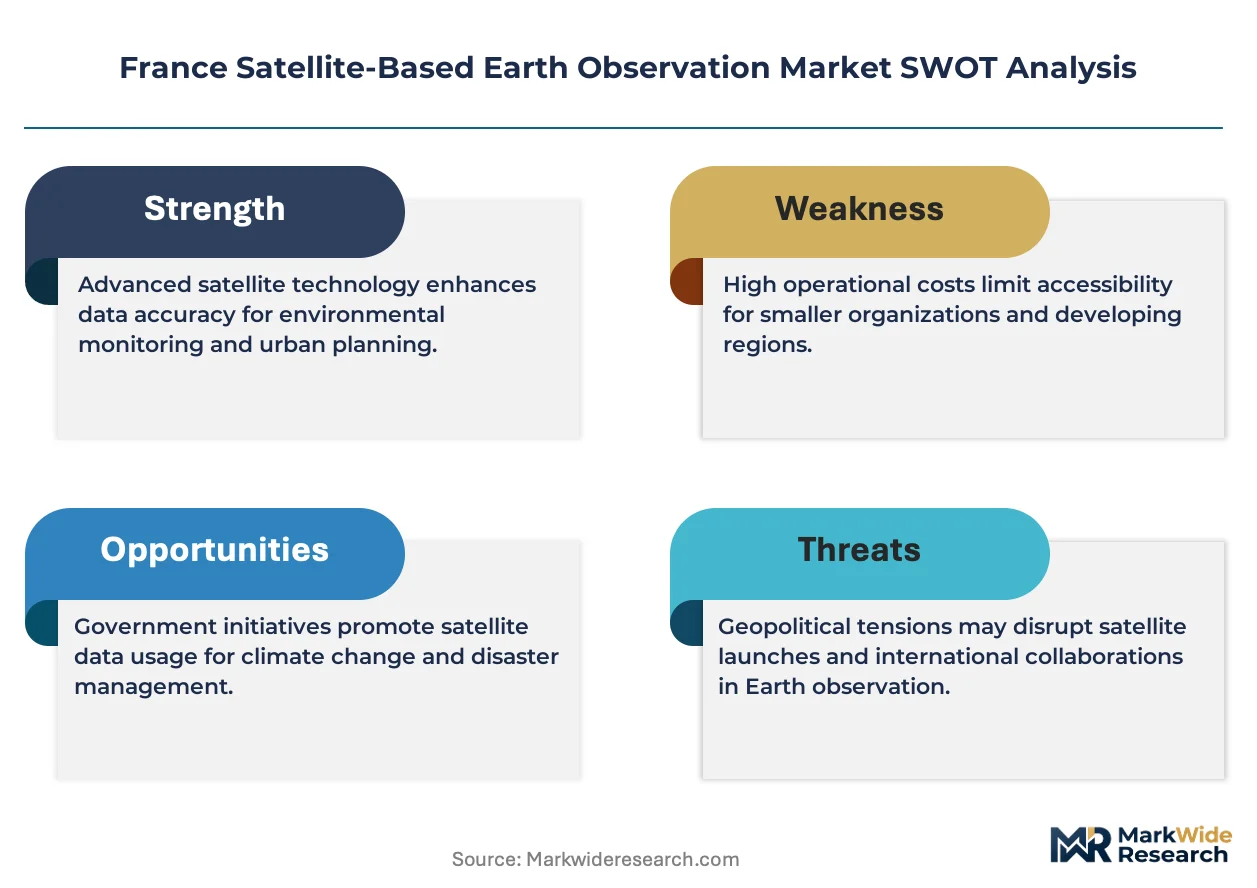
CNES, France's national space agency, shapes procurement standards and sovereign capability requirements through its satellite program investments and bilateral European partnerships. The EU Space Programme, particularly Copernicus and its downstream regulation, mandates cross-border data sharing and interoperability standards that French vendors must satisfy for institutional access. France's national military space command and GDPR-aligned data governance frameworks further constrain how geospatial intelligence products circulate domestically and across European defense networks. Stakeholders must monitor how France's implementation of the EU AI Act intersects with automated image classification systems, as compliance requirements for algorithmic transparency in geospatial analytics are still crystallizing.
Market Dynamics
Sovereign capability mandates from CNES and the EU Space Programme are compressing procurement timelines for high-resolution optical and radar payloads, while hyperspectral sensor adoption accelerates material identification applications across French agriculture and mineral exploration sectors.
Growth Catalysts
- EU Copernicus Downstream Regulation:Cross-border data sharing mandates create institutional demand for interoperable analytics platforms serving French defense and environmental monitoring agencies.
- Maritime Domain Awareness:French naval command requirements for persistent surveillance of exclusive economic zones drive procurement of sub-meter resolution optical constellations with rapid revisit capabilities.
- Carbon Verification Obligations:Corporate sustainability reporting under CSRD compels energy and industrial firms to subscribe to satellite-derived emissions monitoring services.
Market Restraints
- Launch Cost Volatility:Dependence on Ariane and foreign launch providers exposes satellite deployment schedules to payload pricing fluctuations and slot availability constraints.
- GDPR-Aligned Data Governance:Restrictions on automated geospatial intelligence circulation across European defense networks limit product portability for dual-use applications.
- Optical Sensor Limitations:Persistent cloud cover over metropolitan France and coastal regions degrades effective revisit rates for visible-spectrum imaging missions.
Strategic Opportunities
- AI-Act Compliance Services:Algorithmic transparency requirements for automated image classification create consulting and software adaptation revenue streams for analytics vendors.
- Hyperspectral-AI Convergence:Machine learning integration with material spectroscopy enables precision agriculture and rare earth exploration applications previously inaccessible to commercial buyers.
- Occitanie Aerospace Corridor:Toulouse-based manufacturing clusters offer co-location advantages for downstream analytics firms seeking proximity to payload integration facilities.
Industry Challenges
- Specialized Talent Scarcity:Competition for photonics engineers and orbital mechanics specialists from NewSpace ventures strains recruitment pipelines at established satellite manufacturers.
- ITAR-Equivalent Certification Timelines:Military-grade payload qualification processes extend development cycles and compress commercialization windows for dual-use technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Satellite-Based Earth Observation Market |
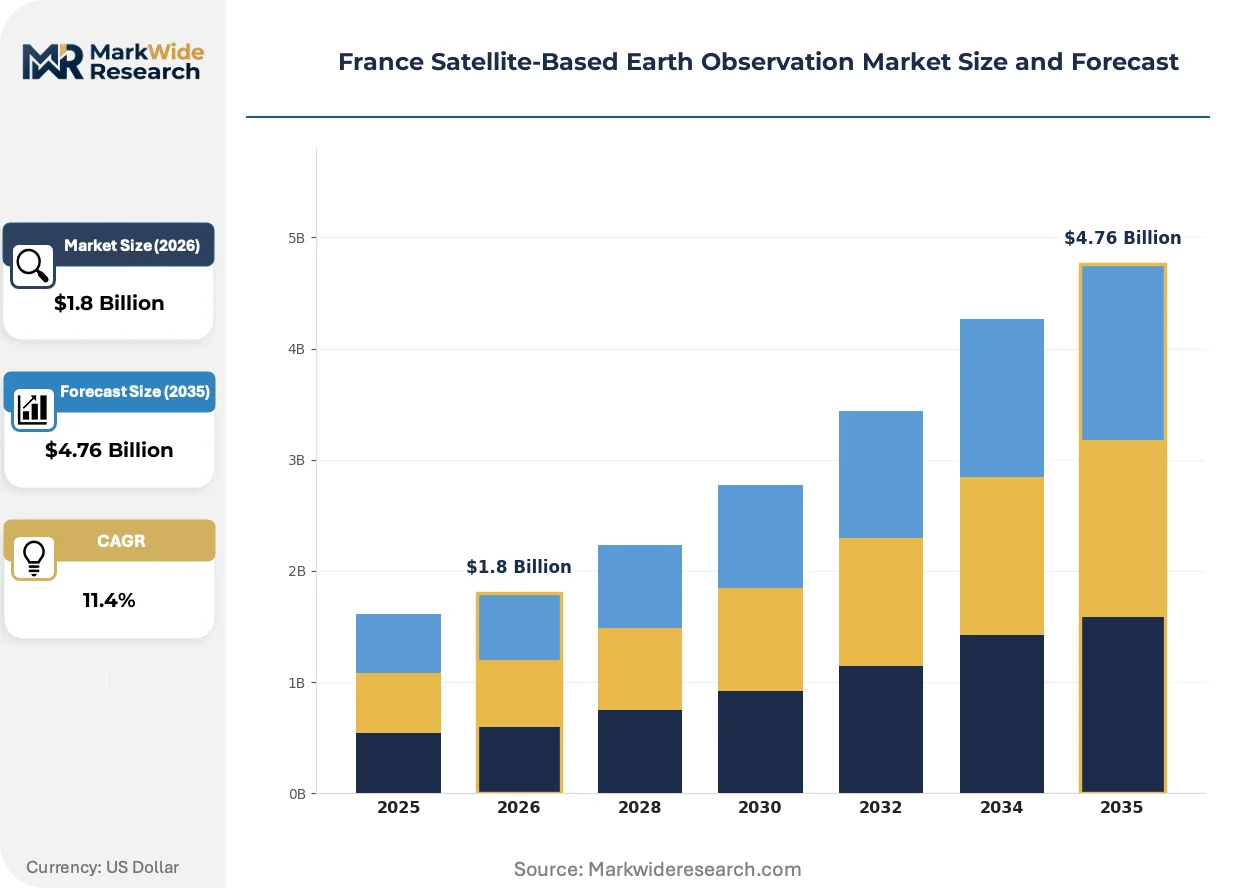
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Environmental Monitoring, Disaster Management, Urban Planning Technology: Radar, Optical, Hyperspectral, LIDAR End User: Government Agencies, Research Institutions, Private Enterprises, NGOs Service Type: Data Processing, Satellite Launch, Consultancy, Custom Solutions |
| Companies Covered | Thales, Airbus, EUTELSAT COMMUNICATIONS SA, KAYRROS, ACRI-ST SAS, CS GROUP - France, CLS sàrl, TerraNIS, E-Space SAS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Satellite-Based Earth Observation Market Trends and Innovations
Artificial intelligence is embedding into every layer of the earth observation value chain, from onboard sensor processing to subscription-based analytics delivery, while regulatory frameworks reshape competitive access to institutional procurement channels.
Synthetic aperture radar technology is integrating real-time onboard processing capabilities that reduce downlink bandwidth requirements and enable direct-to-user intelligence delivery. French defense agencies are accelerating adoption of these autonomous systems for contested electromagnetic environments. The technology is integrating secure edge-computing architectures that compress decision timelines for maritime surveillance operations.
France's implementation of the EU AI Act establishes algorithmic transparency requirements for automated geospatial classification systems used in defense and law enforcement contexts. Industrial consequence includes mandatory documentation of training data provenance and model decision boundaries for procurement eligibility. Analytics vendors serving government agencies are restructuring product architectures to satisfy ex-ante conformity assessment procedures.
Subscription-based data processing is displacing perpetual licensing for earth observation analytics across French energy and infrastructure sectors. Industrial buyers now demand outcome-verified pricing tied to detected anomalies or verified carbon stock changes rather than raw imagery volumes. This consumption-pattern shift concentrates contract value with vendors possessing proprietary AI training datasets for French territorial conditions.
France Satellite-Based Earth Observation Market Segmentation
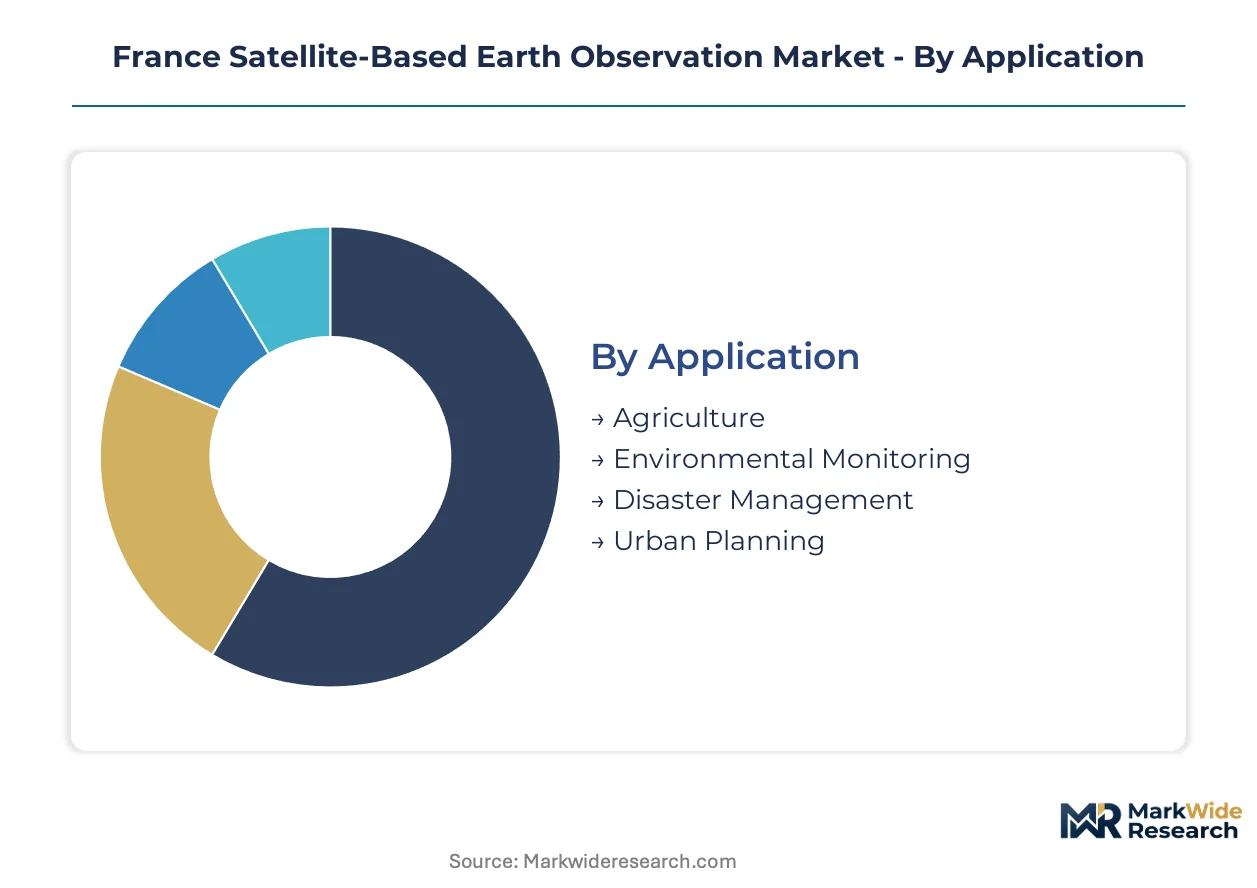
Segmentation in France's satellite-based earth observation market reveals how procurement priorities diverge between sovereign capability mandates and commercial efficiency imperatives. Understanding these divides helps vendors align product architectures with the distinct technical specifications and contracting mechanisms each buyer category demands.
Application:
Customization intensity varies sharply across this category, with sovereign missions requiring bespoke sensor configurations while commercial agriculture buyers favor standardized subscription tiers.
- Environmental Monitoring:Deployments center on drought tracking, carbon stock verification, and coastal erosion assessment using multi-spectral repeat coverage. Demand concentrates in the Paris-Saclay cluster where CNES and climate research institutes coordinate procurement for nationwide observation networks, driven by CSRD-aligned corporate sustainability reporting obligations.
- Agriculture:Precision farming applications leverage hyperspectral material identification for crop health diagnostics and yield prediction algorithms. The Occitanie region dominates uptake as large-scale cereal and vineyard operations around Toulouse adopt subscription-based analytics for irrigation optimization and disease early warning.
- Disaster Management:Rapid response protocols require guaranteed revisit rates and direct downlink priority during activation events.
- Urban Planning:Infrastructure density mapping and informal settlement detection use sub-meter optical stereo pairs for 3D modeling.
Leading the category by volume: Environmental Monitoring. Expanding most quickly: Agriculture.
Technology:
Cost tier stratification separates sovereign-grade radar systems from commercial optical offerings, with hyperspectral occupying an emerging premium niche.
- Hyperspectral:Sensors capture contiguous narrow bands across visible-to-shortwave infrared spectra, enabling material-specific identification for mineral exploration and precision agriculture. French defense research programs and rare earth mining ventures in the Massif Central drive adoption, constrained by payload mass limitations and complex calibration requirements.
- Radar:Synthetic aperture systems penetrate cloud cover and darkness for persistent maritime surveillance and terrain mapping. The French naval command anchors demand through exclusive economic zone monitoring mandates, with real-time onboard processing capabilities reducing electromagnetic vulnerability in contested environments.
- Optical:Panchromatic and multi-spectral imaging dominates commercial procurement for its maturity and cost predictability.
- LIDAR:Laser ranging enables high-precision digital elevation models for flood modeling and infrastructure engineering.
Steepest expansion trajectory: Hyperspectral. Dominant by procurement value: Radar.
End User:
Customer type determines contracting complexity, with government agencies imposing sovereign capability clauses absent from commercial relationships.
- Government Agencies:CNES, military space command, and environmental ministries specify domestic payload integration, secure supply chains, and algorithmic transparency under EU AI Act procurement guidelines. Contracts emphasize data sovereignty and cross-border sharing restrictions aligned with GDPR-aligned defense network protocols.
- Private Enterprises:Energy majors and infrastructure operators subscribe to outcome-verified analytics for emissions monitoring and asset inspection. The Ile-de-France region hosts the densest concentration as CSRD reporting deadlines compel industrial firms to outsource carbon verification to satellite-derived services.
- Research Institutions:Universities and national laboratories access subsidized data through CNES partnership programs.
- NGOs:Conservation organizations leverage donated imagery archives for biodiversity monitoring and deforestation alerts.
Highest contract value concentration: Government Agencies. Fastest-growing subscription base: Private Enterprises.
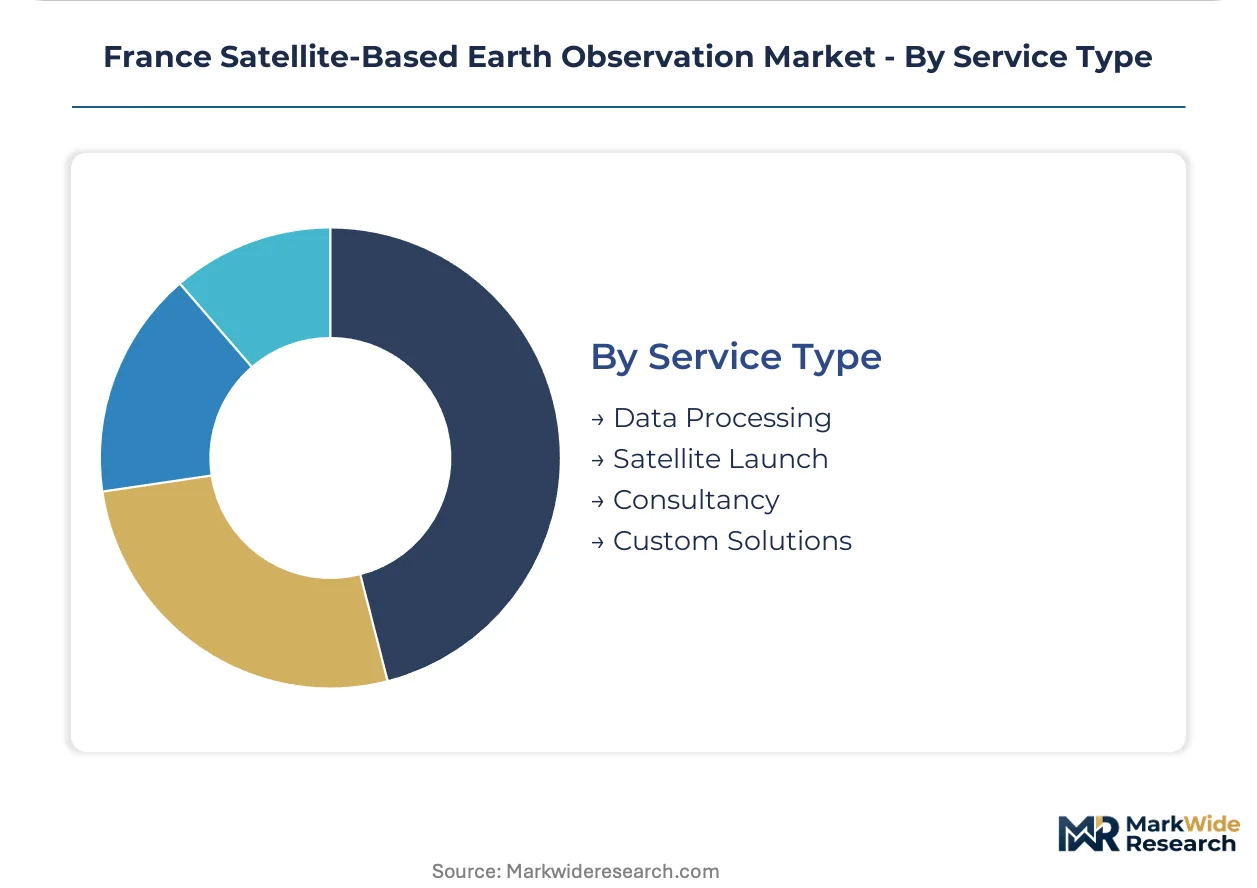
Service Type:
Margin capture shifts upstream from raw imagery delivery toward proprietary analytics as downstream processing claims expanding value pools.
- Data Processing:AI-driven classification, change detection, and feature extraction transform raw sensor outputs into decision-ready intelligence. French energy and infrastructure sectors now demand anomaly-verified pricing rather than per-square-kilometer imagery fees, concentrating revenue with vendors holding proprietary training datasets for metropolitan and coastal conditions.
- Custom Solutions:Bespoke algorithm development and integration services address mission-specific requirements for defense and specialized industrial applications. Thales and Airbus anchor this segment through classified payload adaptation and secure ground segment architecture.
- Satellite Launch:Deployment services face capacity constraints from Ariane schedule dependencies and foreign provider slot competition.
- Consultancy:Regulatory compliance advisory and mission design support assists new entrants navigating CNES qualification standards.
Gaining share fastest: Data Processing. Anchoring procurement volume: Custom Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France produces satellite payloads and ground systems for domestic and export markets while consumption concentrates in government defense contracts and corporate sustainability verification services. Manufacturing clusters in Toulouse and Paris-Saclay supply hardware to European and allied programs. Downstream analytics demand spreads across metropolitan zones where CSRD reporting obligations drive subscription growth.
Île-de-France
CNES headquarters in Paris-Saclay anchors sovereign procurement for defense and environmental monitoring missions. The EU AI Act implementation through ANSM and CNIL oversight shapes algorithmic transparency requirements for automated geospatial classification systems. Climate research institutes and energy majors in the Paris metropolitan zone subscribe to satellite-derived carbon verification services for CSRD compliance.
Occitanie
Large-scale cereal and vineyard operations around Toulouse adopt hyperspectral analytics for irrigation optimization and disease early warning. France's national military space command specifies radar payload requirements for maritime domain awareness in the Mediterranean. The Toulouse aerospace corridor hosts Thales and Airbus manufacturing facilities alongside downstream analytics development clusters.
Provence-Alpes-Côte d'Azur
Maritime surveillance demand from French naval command drives sub-meter optical constellation procurement for exclusive economic zone monitoring. The EU Space Programme's Copernicus downstream regulation mandates cross-border data sharing standards that regional defense contractors must satisfy. Sophia Antipolis technology park hosts specialized firms developing secure edge-computing architectures for contested electromagnetic environments.
Auvergne-Rhône-Alpes
Rare earth mining ventures in the Massif Central drive hyperspectral sensor adoption for mineral exploration and material identification. France's national space policy accelerates sovereign capabilities in radar and hyperspectral sensing through CNES program investments. Grenoble-based photonics research clusters supply specialized components for next-generation payload development.
Hauts-de-France
Industrial infrastructure operators in the northern manufacturing belt subscribe to outcome-verified analytics for emissions monitoring and asset inspection. GDPR-aligned data governance frameworks constrain automated geospatial intelligence circulation across European defense networks. Lille metropolitan area hosts logistics and data processing facilities supporting nationwide earth observation service delivery.
France Satellite-Based Earth Observation Market Competitive Landscape
Capital-heavy satellite manufacturers compete with asset-light analytics providers for contract value in France's earth observation market. Thales and Airbus anchor the hardware tier through defense heritage and payload integration capabilities, while specialized software firms capture expanding margin pools in AI-driven classification services. Three archetypes dominate: sovereign-grade system integrators, commercial imagery operators, and subscription-based analytics platforms. Consolidation pressure intensifies through strategic partnerships between payload developers and downstream service providers, plus vertical integration moves by defense contractors into secure ground segment architectures.
Within the sovereign system integrator tier, Thales exemplifies the defense electronics heritage model through classified payload adaptation and secure government contracting. Airbus occupies a parallel position in high-resolution optical and radar development for institutional and commercial buyers. KAYRROS represents the asset-light analytics archetype, competing through AI-driven environmental and energy subscriptions that differentiate from raw imagery vendors. These three anchors illustrate how contract value concentrates with firms possessing proprietary training datasets for French territorial conditions or established CNES qualification pathways.
| Leading Market Players |
|---|
| Thales |
| Airbus |
| EUTELSAT COMMUNICATIONS SA |
| KAYRROS |
| ACRI-ST SAS |
| CS GROUP - France |
| CLS sàrl |
| TerraNIS |
| E-Space SAS |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between sovereign-grade radar payloads and commercial optical offerings manifests in both procurement premiums and supply chain localization mandates from CNES. Three-tier pricing structure across premium, standard, and economy levels separates defense-qualified systems with ITAR-equivalent timelines from rapid-deployment commercial constellations, while payload integration geography determines tariff exposure and slot access through Ariane.
Pricing Analysis
Margin tightening in hyperspectral sensor tiers reflects payload mass limitations and complex calibration requirements that compress commercialization windows. Subscription-based data processing now dominates downstream value capture, with outcome-verified pricing tied to detected anomalies displacing per-square-kilometer imagery fees. Price differentiation hinges on proprietary AI training datasets for French territorial conditions and algorithmic transparency documentation under EU AI Act procurement guidelines. Government agencies exhibit lowest price sensitivity given sovereign capability mandates, while private enterprises purchasing CSRD-aligned carbon verification services drive standard-tier volume.
Supply Chain Analysis
Launch logistics costs and slot availability constraints from Ariane schedule dependencies expose deployment timelines to foreign provider competition. Payload manufacturing draws from France, Germany, and the United States for precision optics, radar electronics, and secure computing architectures. Supply chain risk centers on single-source vulnerability for specialized photonics components sourced from Grenoble-based research clusters. Distribution runs through Toulouse aerospace corridor integration facilities and Paris-Saclay ground segment operations serving defense and institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Launch capacity scarcity from Ariane schedule constraints and foreign provider slot competition props pricing for sovereign-grade payload integration. This supply-constrained structure favors incumbents with established CNES qualification pathways.
For Market Incumbents: To counter specialized talent scarcity from NewSpace ventures, anchor recruitment pipelines through co-location with Occitanie aerospace corridor manufacturing clusters and deepen proprietary AI training datasets for French territorial conditions that lock in outcome-verified subscription renewals. For New Entrants and Emerging Players: Capture white-space in AI-Act compliance consulting and algorithmic transparency documentation services for automated geospatial classification systems, targeting private enterprises in Ile-de-France with CSRD reporting deadlines as the most penetrable buyer segment through outcome-based pricing models. For Investors and Strategic Acquirers: Re-rating potential sits with asset-light analytics platforms possessing proprietary training datasets given the shift from raw imagery to subscription-based intelligence delivery; long-term viability favors vendors with French defense network access and GDPR-aligned data governance architectures. Monitor CNES program investment announcements as the signal indicating sovereign procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperspectral-AI Platform Integration | Machine learning convergence with material spectroscopy unlocks precision agriculture contracts in Occitanie cereal operations. |
| Secure Edge-Computing Architecture Development | Real-time onboard processing reduces electromagnetic vulnerability for French naval command maritime surveillance missions. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation satisfies ANSM and CNIL procurement eligibility for defense analytics contracts. |
| Occitanie Manufacturing Co-location | Proximity to Thales and Airbus payload integration facilities accelerates downstream analytics development cycles. |
| CSRD-Aligned Carbon Verification Service Launch | Subscription-based emissions monitoring captures private enterprise demand from Ile-de-France energy majors. |
Research Methodology
CNES program documentation, EU Space Programme Copernicus downstream regulation filings, and French military space command procurement records formed the secondary backbone, supplemented by customs data on satellite component trade flows. Primary interviews with satellite payload engineers, defense procurement officers, environmental ministry program managers, and downstream analytics platform CTOs validated technical specifications and contracting mechanisms. Bottom-up triangulation across application segments and technology categories reconciled with top-down macroeconomic indicators.
Bottom-up modeling built volume estimates from individual segment trajectories across environmental monitoring, agriculture, disaster management, and urban planning applications, while top-down analysis anchored aggregate expansion to CNES budget allocations and EU space policy investment frameworks. CAGRs were derived from curve-fitting historical procurement patterns against sovereign capability mandate acceleration timelines. Hyperspectral sensor adoption curves and AI-Act implementation schedules served as industry-specific forecast inputs across the projection horizon.
The model holds under continued CNES program investment and EU Space Programme funding continuity; deviation in launch cost volatility or foreign provider slot access would shift deployment timelines and subscription revenue recognition. Forecasts reflect these assumptions without claiming predictive certainty. Stakeholders should weight assumptions against their own operating context and sovereign customer pipeline visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
United States Satellite Communications Market
Satellite
Europe Satellite Bus Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
Satellite Backhaul Market
Satellite
Satellite Data Analytics Services Market
Satellite
North America Satellite Manufacturing Market
Satellite
Global Small Satellite Service Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
Russia Satellite Imagery Services Market
Satellite
Europe Satellite IoT Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
Global Broadband Satellite Services Market
Satellite
Italy Satellite Communication Market
Satellite
LEO Satellite System Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market