
 Satellite Operation Service Market | 2026-2036
Satellite Operation Service Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Operation Service Market Insights
Mission-critical reliability tiers are redrawing competitive requirements across the satellite operation service landscape. Inmarsat plc leverages its L-band heritage to sustain premium connectivity contracts for maritime and aviation clients. SES S.A anchors European capacity through its medium Earth orbit O3b constellation, while Iridium Communications dominates polar and remote-region coverage with its cross-linked LEO architecture. Viasat, Inc competes on bandwidth density for government and defense applications.
Satellite operation service encompasses the continuous monitoring, control, and optimization of spacecraft health, orbital positioning, and payload performance through ground station networks and cloud-based platforms. Functional parameters include sub-degree pointing accuracy, millisecond-latency telecommand execution, and automated anomaly resolution protocols that preserve mission continuity for billion-dollar assets. Telemetry telecommand and payload management segments absorb the majority of contracted spending as operators prioritize fleet automation over labor-intensive manual intervention. Cloud-based platforms represent the fastest-expanding deployment model, though hybrid systems retain margin concentration where classified or sovereign data requirements mandate on-premises control nodes.
FCC licensing frameworks govern U.S. orbital slot coordination and spectrum allocation, while ESA procurement standards and EU Space Surveillance and Tracking guidelines shape European operator compliance burdens. Japan's MIC radio law and METI space industry promotion measures create structured pathways for domestic and foreign service providers entering the Japanese market. Stakeholders must weigh sovereign data residency requirements against cloud platform economics when structuring multi-national fleet management contracts.
Market Dynamics
Fleet automation mandates from earth observation operators are compressing ground segment staffing models while expanding telemetry telecommand contract scope. Cloud-native control architectures are displacing legacy hardware-dependent operations centers.
Growth Catalysts
- ESA procurement standards:European outsourcing directives are redirecting national space agency fleet management budgets toward commercial contractors with certified ground station networks.
- Climate monitoring intensification:Earth observation firms are scaling payload management procurement as sovereign weather agencies expand satellite constellation refresh cycles.
- LEO constellation deployment:Cross-linked low Earth orbit architectures are generating recurring demand for automated anomaly resolution and millisecond-latency telecommand execution services.
Market Restraints
- Ground station infrastructure concentration:Polar orbit coverage depends on a limited set of high-latitude facilities in Norway, Alaska, and Antarctica.
- Spectrum coordination friction:FCC orbital slot allocation timelines create deployment delays for commercial constellation operators seeking contiguous frequency blocks.
- Qualified telemetry engineer scarcity:Sub-degree pointing accuracy requirements demand specialized orbital mechanics expertise that training pipelines cannot replenish rapidly.
Strategic Opportunities
- Japan's METI space industry promotion:Structured domestic market entry pathways are opening for foreign operators willing to establish local ground station partnerships.
- Hybrid cloud-on-premises architectures:Sovereign data residency requirements in defense and intelligence verticals are creating margin-rich deployment niches.
- Maritime connectivity unbundling:Aviation and shipping fleet operators are separating bandwidth procurement from managed network service contracts.
Industry Challenges
- Multi-constellation integration complexity:Operators managing heterogeneous fleets across geostationary, medium Earth orbit, and low Earth orbit assets face protocol harmonization burdens.
- Cybersecurity certification timelines:Government contract eligibility requires Common Criteria evaluation that extends sales cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Operation Service Market |
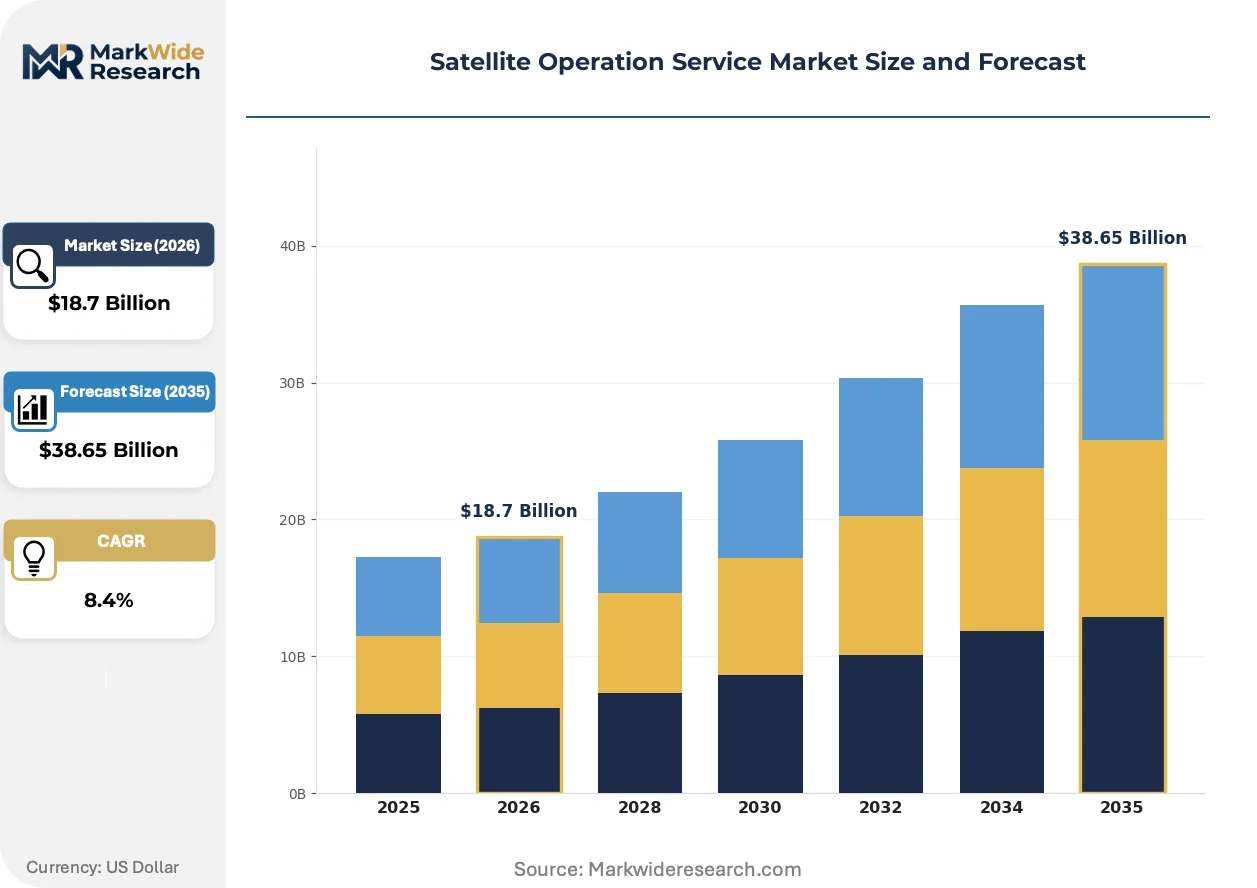
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Telemetry Telecommand, Payload Management, Orbit Control, Anomaly Resolution, Data Processing Customer Type: Telecommunication Companies, Government Agencies, Research Institutes, Broadcast Operators, Earth Observation Firms Deployment Model: Ground Station Networks, Cloud-Based Platforms, Hybrid Systems, On-Premises Facilities, Distributed Control Centers Application: Remote Sensing, Satellite Imagery Analysis, Space Science, Navigation Assistance, Weather Monitoring |
| Companies Covered | Inmarsat plc, MEASAT, PCCW Global, Intelsat, SES S.A, Eutelsat Communications SA, Viasat, Inc, Iridium Communications, Telesat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Operation Service Market Trends and Innovations
Artificial intelligence inference at the edge is redefining anomaly detection latency benchmarks across ground segment architectures. Automation is compressing operator-to-spacecraft ratios while elevating software-defined radio deployment.
Software-defined ground stations are fragmenting the traditional hardware vendor landscape. Earth observation operators are adopting universal modem architectures that decouple antenna infrastructure from baseband processing. This flexibility is fragmenting long-term equipment procurement contracts into modular, upgradeable service subscriptions.
The FCC's streamlined commercial satellite licensing frameworks are accelerating constellation deployment timelines. Orbital slot coordination now permits batch applications for distributed architectures rather than sequential single-satellite approvals. Small satellite operators are responding by front-loading spectrum requests ahead of manufacturing commitments.
Service unbundling is separating spacecraft control from payload data processing in contract structures. Defense and intelligence buyers are retaining classified mission control in-house while outsourcing telemetry telecommand to cleared commercial providers. This bifurcation is most advanced in United States federal procurement patterns.
Satellite Operation Service Market Segmentation
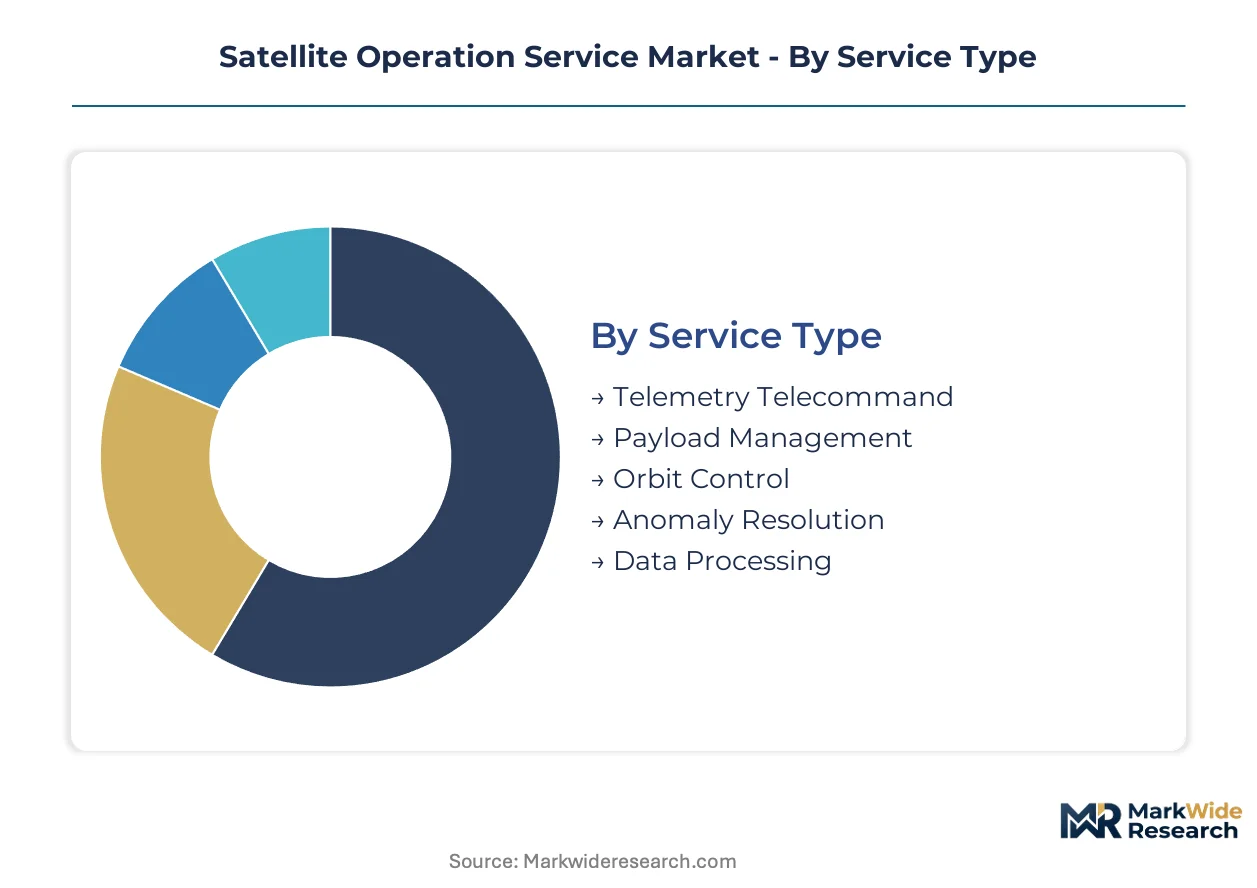
Segmentation in satellite operation services reveals where contract value pools concentrate across technical functions and buyer archetypes. Distinct margin structures emerge between commoditized telemetry services and specialized payload management for classified missions.
Service Type:
Payload management commands premium pricing where sub-degree pointing accuracy requirements intersect with sovereign data classification.
- Telemetry Telecommand:Continuous health monitoring and command uplink execution through ground station networks. Demand concentrates among LEO constellation operators in the United States and Germany as fleet sizes exceed manual operator capacity. FCC batch licensing for distributed architectures accelerates contract scope expansion.
- Payload Management:Instrument calibration, data acquisition scheduling, and performance optimization for earth observation and scientific payloads. Earth observation firms in Japan and the United States are scaling procurement as climate monitoring refresh cycles intensify, with METI promotion measures opening structured pathways for foreign providers.
- Orbit Control:Station-keeping maneuvers and collision avoidance propulsion management.
- Anomaly Resolution:Automated fault detection and recovery protocol execution.
- Data Processing:Raw telemetry transformation and downstream product generation.
Telemetry telecommand holds installed capacity. Payload management is rotating up the share rankings.
Customer Type:
Government agencies generate the longest contract tenures, though earth observation firms are expanding procurement velocity fastest.
- Telecommunication Companies:Fleet operators managing geostationary, MEO, and LEO assets requiring continuous connectivity assurance. Maritime and aviation bandwidth providers in Germany and Japan are unbundling managed network services from raw bandwidth procurement.
- Government Agencies:Defense and intelligence buyers retaining classified mission control in-house while outsourcing telemetry telecommand to cleared commercial providers. United States federal procurement patterns show the most advanced bifurcation between sovereign control and commercial service layers.
- Research Institutes:Space science and technology demonstration mission operators.
- Broadcast Operators:Content distribution satellite fleet managers.
- Earth Observation Firms:Commercial remote sensing constellation operators.
Government agencies anchor contract backlog. Earth observation firms are climbing the fastest.
Deployment Model:
Hybrid architectures capture margin concentration where defense and intelligence verticals mandate on-premises control nodes alongside cloud scalability.
- Ground Station Networks:Dedicated antenna infrastructure with localized baseband processing. Polar orbit coverage depends on high-latitude facilities in Norway, Alaska, and Antarctica, creating infrastructure concentration constraints.
- Cloud-Based Platforms:Virtualized control center operations with elastic compute scaling. Software-defined ground stations are fragmenting traditional hardware vendor landscapes as universal modem architectures decouple antenna infrastructure from baseband processing.
- Hybrid Systems:Sovereign data residency compliance combined with cloud platform economics. Margin-rich deployment niches emerge where classified requirements intersect with multi-national fleet management contracts.
- On-Premises Facilities:Fully captive control centers for national security missions.
- Distributed Control Centers:Geographically redundant operations architecture.
Ground station networks hold installed capacity. Hybrid systems are rotating up the share rankings.
Application:
Remote sensing applications concentrate procurement volume where sovereign weather agencies expand constellation refresh cycles.
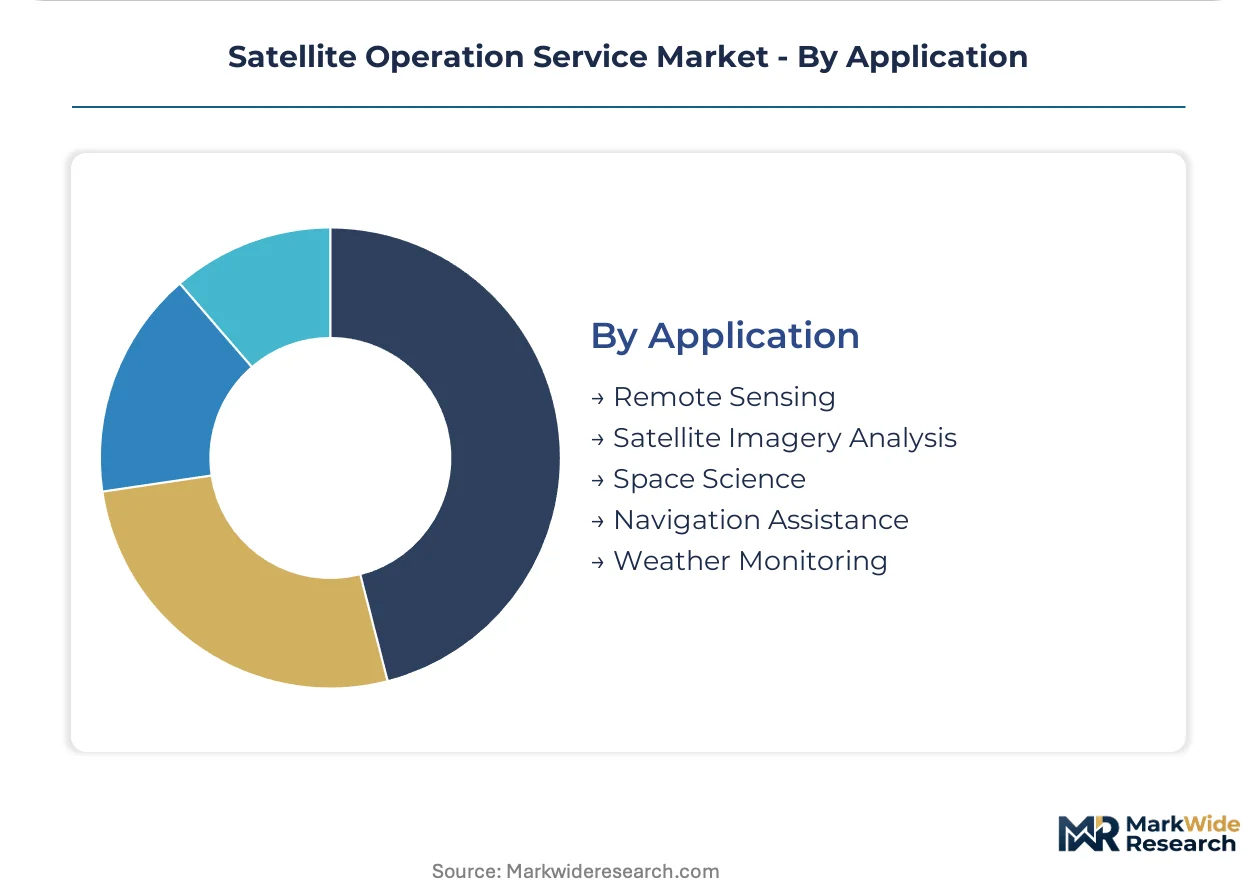
- Remote Sensing:Land use, ocean monitoring, and atmospheric composition data acquisition. Climate monitoring intensification across the United States, Germany, and Japan is scaling payload management procurement as national space agencies expand outsourcing.
- Satellite Imagery Analysis:Post-processing and feature extraction for commercial and defense customers. Artificial intelligence inference at the edge is redefining anomaly detection latency benchmarks across ground segment architectures serving this vertical.
- Space Science:Fundamental research and technology demonstration missions.
- Navigation Assistance:Precise positioning service augmentation.
- Weather Monitoring:Meteorological data collection and forecasting support.
Remote sensing holds installed capacity. Satellite imagery analysis is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense buyers in the United States demonstrate the lowest price elasticity, accepting premium telemetry contracts for classified missions, while commercial maritime operators in Germany and Japan negotiate aggressively on bandwidth procurement. Earth observation firms across all three markets show moderate elasticity, trading cost against sub-degree pointing accuracy requirements. Sovereign data residency mandates in Japan create artificial price floors that foreign providers must absorb through local partnership structures.
United States
Federal procurement patterns drive demand bifurcation, with defense agencies retaining classified mission control while outsourcing telemetry telecommand to cleared commercial contractors. FCC batch licensing for distributed LEO architectures accelerates constellation deployment timelines and expands contract scope for automated anomaly resolution services. The Colorado front range hosts the densest concentration of ground station operators, with Denver-Aurora facilities processing telemetry for polar and sun-synchronous orbits serving earth observation constellations.
Germany
Maritime and aviation bandwidth providers are unbundling managed network services from raw connectivity procurement, compressing margins on standardized telemetry while preserving premiums for payload management. ESA procurement standards redirect national space agency budgets toward commercial contractors with certified ground station networks. The Munich-Oberpfaffenhofen corridor anchors European satellite control infrastructure, with DLR facilities and commercial operators co-locating antenna arrays for medium Earth orbit constellation management.
Japan
METI space industry promotion measures create structured pathways for foreign operators establishing local ground station partnerships, particularly for climate monitoring payload management. MIC radio law compliance requirements and sovereign data residency mandates favor hybrid cloud-on-premises architectures in defense and intelligence verticals. The Tsukuba science city cluster concentrates earth observation operators scaling procurement as national weather agencies expand satellite constellation refresh cycles.
Norway
Polar orbit coverage demand concentrates procurement at high-latitude ground station facilities, creating infrastructure bottlenecks that operators resolve through multi-tenant antenna sharing agreements. National space law harmonization with ESA guidelines streamlines commercial access to Svalbard ground station assets for LEO constellation operators. The Svalbard Satellite Station and Tromsø control centers process telemetry for sun-synchronous orbits serving remote sensing constellations across European and Asian operator portfolios.
Satellite Operation Service Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the satellite operation service landscape. Heritage L-band operators with decades of orbital slot holdings command premium pricing for maritime and aviation connectivity, while software-defined ground station entrants fragment equipment procurement into modular service subscriptions. Three archetypes dominate: spectrum-rich incumbents with integrated fleet ownership, cloud-native control platform specialists, and hybrid infrastructure providers bridging sovereign data requirements with elastic compute scaling. Competitive moves concentrate on strategic partnerships for polar coverage access and portfolio diversification into payload data processing adjacent to core telemetry services.
Within the heritage operator tier, Inmarsat plc and Iridium Communications anchor premium connectivity positioning through orbital slot depth and cross-linked LEO architecture coverage respectively. SES S.A occupies a position bridging European capacity provision with medium Earth orbit constellation management. Viasat, Inc represents the bandwidth density archetype competing for government and defense applications where millisecond-latency telecommand execution requirements intersect with classified data handling protocols.
| Leading Market Players |
|---|
| Inmarsat plc |
| MEASAT |
| PCCW Global |
| Intelsat |
| SES S.A |
| Eutelsat Communications SA |
| Viasat, Inc |
| Iridium Communications |
| Telesat |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month lead times for radiation-hardened flight computers concentrate procurement leverage among a handful of qualified suppliers, compressing margin pools for ground segment operators while amplifying pricing power for component vendors with ITAR certification.
Pricing Analysis
After-sales telemetry service contracts drive lifetime value across satellite operation portfolios. Three-tier pricing structure across premium, standard, and economy levels segments buyers by mission-criticality and data classification requirements. Price differentiation rests on FCC licensing tier and sovereign data handling certification. Cost compression in standardized telemetry telecommand is intensifying because software-defined ground stations fragment hardware procurement into modular subscriptions. Commercial maritime operators in Germany exhibit highest price sensitivity, while United States defense agencies demonstrate lowest elasticity for classified mission support.
Supply Chain Analysis
Polar ground station access through Svalbard facilities underwrites coverage economics for sun-synchronous orbit operators. Manufacturing concentration in the United States, Germany, and Japan supplies radiation-tolerant processors, high-precision antenna systems, and secure telemetry modems. Raw material dependencies include gallium nitride semiconductors, carbon fiber composites, and cryogenic cooling systems. Single-source vulnerability in qualified telemetry engineer pipelines threatens capacity expansion timelines. Distribution runs through certified ground station network operators and cloud platform integrators serving constellation deployers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FCC batch licensing frameworks for distributed LEO architectures constitute a regulatory inflection accelerating market disruption, compressing deployment timelines and expanding addressable contract scope for automated fleet management services.
For Market Incumbents: Secure polar coverage access through partnership structures in Norway and Alaska before infrastructure bottlenecks harden. Invest in hybrid cloud-on-premises certification to capture defense vertical margins as sovereign data residency mandates proliferate. Software-defined ground station entrants threaten equipment procurement relationships; backward integration into universal modem architectures preserves supplier leverage. For New Entrants and Emerging Players: Lead with AI-augmented anomaly resolution capabilities targeting earth observation firms in Japan where METI promotion measures lower market entry barriers. Climate monitoring payload management offers the most penetrable segment given national weather agency outsourcing trends. Go-to-market positioning should emphasize millisecond-latency telecommand execution benchmarks against legacy operator architectures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native control platform deployments as software-defined infrastructure displaces hardware-dependent operations centers. Long-term viability favors hybrid infrastructure providers bridging sovereign compliance with elastic scaling. Acquisition targets should demonstrate cleared personnel pools and existing ground station partnerships. The signal to watch is FCC enforcement action on orbital debris mitigation compliance as a capacity constraint trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Polar Infrastructure Partnership | Svalbard and Alaska facility access locks in sun-synchronous orbit coverage economics for LEO operators. |
| Hybrid Cloud Certification Investment | Common Criteria evaluation opens defense procurement eligibility extending sales cycles but securing premium contract tiers. |
| Software-Defined Ground Station Deployment | Universal modem architectures fragment traditional hardware vendor landscapes into modular service subscriptions. |
| AI-Edge Anomaly Detection Integration | Millisecond-latency inference redefines competitive benchmarks for automated fault recovery protocol execution. |
| Maritime Connectivity Unbundling | Separation of bandwidth procurement from managed network services creates specialized telemetry contract opportunities. |
Research Methodology
Desk research of FCC licensing databases, ESA procurement registries, and METI industry filings preceded structured interviews with constellation operations directors, ground station network managers, and defense procurement officers. Primary fieldwork with satellite operators in the United States, Germany, and Japan validated service demand patterns and pricing benchmarks. Secondary sources included ITU spectrum allocation records, national space agency budget disclosures, and commercial launch manifests. Bottom-up contract value analysis triangulated against top-down market sizing from fleet deployment projections.
Variance decomposition across service type, customer archetype, and deployment model dimensions structured the analytical framework over the projection horizon. Segmentation modeling captured telemetry telecommand, payload management, and hybrid system deployment patterns. CAGRs derived from fleet size expansion curves and automation penetration assumptions. Industry-specific inputs included LEO constellation deployment schedules and sovereign data residency mandate implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained LEO constellation deployment rates and stable spectrum allocation frameworks would require recalibration. Forecasts reflect documented assumptions regarding FCC licensing velocity and qualified engineering pipeline replenishment. Orbital debris regulatory tightening or geopolitical restrictions on ground station access represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Imaging Market
Satellite
Global Small Satellite Service Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
Japan Satellite Communication Market
Satellite
Military Satellite Market
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
France Satellite Connectivity Market
Satellite
India Satellite-Based Earth Observation Market
Satellite
Broadband Satellite System Market
Satellite
Satellite Transponder Market
Satellite
Satellite Link Emulator Market
Satellite
Africa Satellite Connectivity Market
Satellite
Commercial Satellite Launch Service Market
Satellite
China Satellite Communication Market
Satellite
Satellite Broadband Market