
 North America Military Satellite Market | 2026-2036
North America Military Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
North America Military Satellite Market Insights
Project finance and long-term leasing of orbital assets is fragmenting traditional ownership structures among prime contractors. Lockheed Martin Corporation leverages captive manufacturing of classified bus platforms to sustain program margins across multi-year production blocks. Northrop Grumman Corporation anchors its position through vertical integration into sensor payloads and ground segment integration. Cesium Astro competes by specializing in software-defined radio architectures that reduce hardware refresh cycles for tactical users.
North America military satellites are purpose-built spacecraft operating in geostationary, medium, and low Earth orbits with hardened electronics, anti-jam signal processors, and nuclear event detection circuitry; their primary function is to provide beyond-line-of-sight command, control, communications, and intelligence for contested operational environments. Communication satellites occupy the largest revenue share within product type segmentation due to persistent bandwidth requirements for unmanned systems and joint force coordination. Reconnaissance satellites represent the fastest-expanding category as multi-spectral imaging resolution standards tighten and refresh rates accelerate under modern targeting doctrines.
FCC spectrum allocation proceedings, U.S. Space Force orbital debris mitigation mandates, and NHTSA-linked timing standards for GPS augmentation shape procurement specifications and vendor qualification pathways across the continent. ITAR export controls and classified security clearance requirements further constrain supplier pools and reinforce domestic manufacturing obligations. Stakeholders must monitor evolving Space Force procurement rhythms and congressional appropriation priorities for next-generation proliferated architectures.
Market Dynamics
The U.S. Space Force's proliferated architecture mandate is fragmenting traditional prime contractor dominance by dispersing satellite procurement across smaller, more frequent production blocks. This directive compresses development cycles and forces incumbents to restructure manufacturing footprints across Arizona and California.
Growth Catalysts
- FCC Accelerated Licensing:Compressed spectrum allocation timelines for military Ka and X-band frequencies enable faster constellation deployment by reducing regulatory lag between contract award and orbital insertion.
- Unmanned Systems Bandwidth:Persistent beyond-line-of-sight command requirements for MQ-9 Reaper and future attritable platforms drive dedicated military communication payload procurement independent of commercial lease capacity.
- Software-Defined Radio:Reconfigurable signal processing architectures allow tactical users to adapt waveforms in orbit, extending satellite operational life and reducing hardware refresh frequency.
Market Restraints
- ITAR Classification Density:Export control restrictions on bus platforms and encryption modules constrain supplier pools to cleared domestic manufacturers, inflating component costs and extending lead times.
- Rad-Hard Semiconductor Concentration:Dependency on a limited number of qualified foundries for radiation-hardened electronics creates single-point-of-failure risk across multiple satellite programs.
- Launch Capacity Bottlenecks:Eastern Range scheduling constraints and Western Range recovery limitations restrict deployment velocity for proliferated architectures requiring dozens of annual insertions.
Strategic Opportunities
- Canadian Arctic Coverage:Underpenetrated northern latitudes present white space for dedicated polar-orbiting reconnaissance and communication assets serving NORAD integrated warning missions.
- GPS Augmentation Timing:NHTSA-linked automotive precision requirements create dual-use demand for military-grade atomic clock payloads with civilian navigation spillover applications.
- Orbital Servicing Convergence:Robotic refueling and component swap technologies extend geostationary asset life, converting capital expenditure models toward service-based revenue streams.
Industry Challenges
- Clearance Pipeline Constraints:TS/SCI adjudication backlogs delay engineering staffing for classified bus development, stretching program schedules and inflating labor premiums.
- Legacy Ground Segment Integration:New proliferated constellations must interoperate with decades-old command infrastructure, forcing expensive middleware development and cybersecurity retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Military Satellite Market |
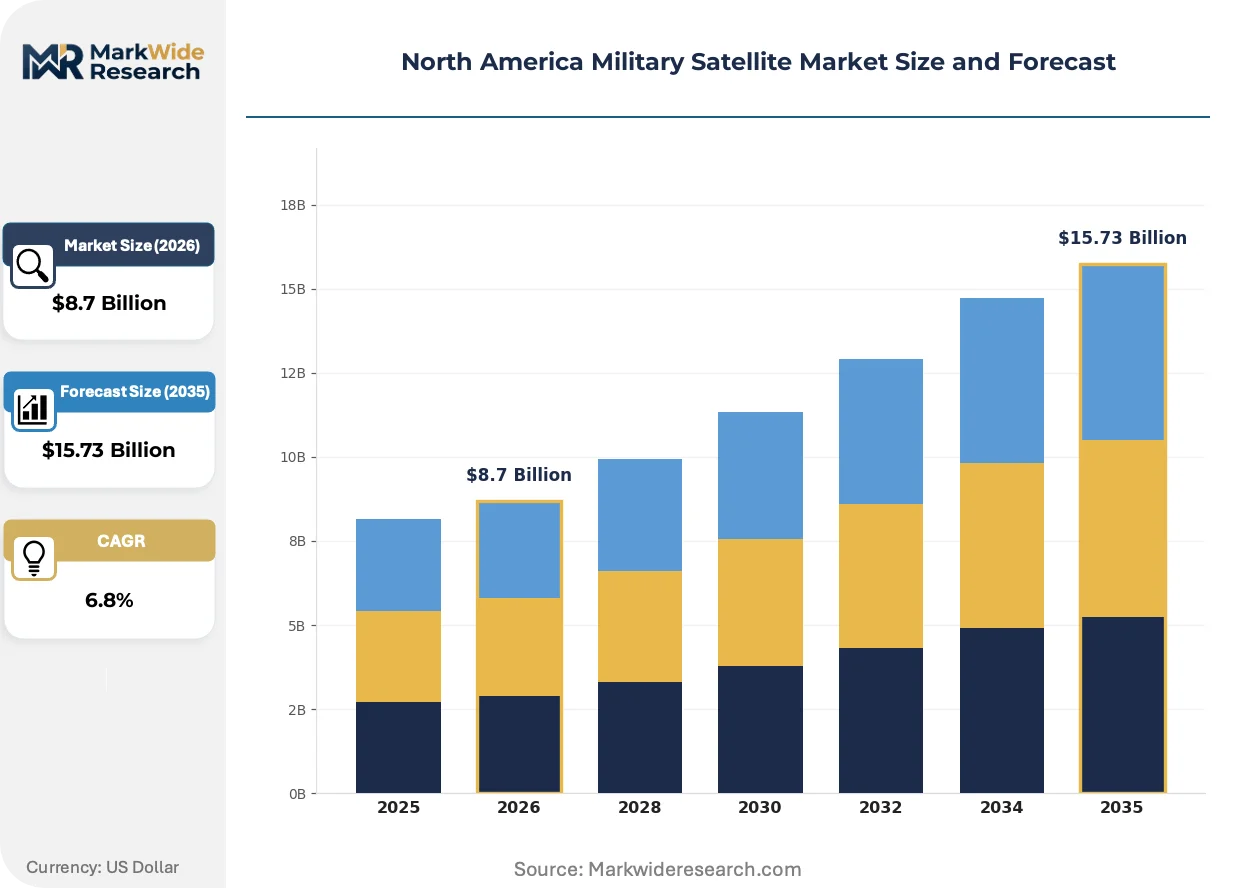
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communication Satellites, Reconnaissance Satellites, Navigation Satellites, Surveillance Satellites End User: Defense Forces, Government Agencies, Intelligence Organizations, Research Institutions Deployment Type: On-orbit Satellites, Ground Stations, Satellite Launch Vehicles, Spacecraft Application: Secure Communications, Target Tracking, Geographic Mapping, Data Relay |
| Companies Covered | The Boeing Company, L3Harris Technologies, Inc., Lockheed Martin Corporation, Cesium Astro, Maxar Technologies, Northrop Grumman Corporation, Ball Corporation, Thales Alenia Space, Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Military Satellite Market Trends and Innovations
Proliferated low-Earth-orbit architectures are compressing the traditional geostationary satellite model by distributing mission functions across dozens of smaller, replaceable platforms. This shift demands new manufacturing rhythms and supply chain configurations across the southwestern United States.
Software-defined payload architectures are collapsing the hardware refresh cycle for tactical communication satellites. Reprogrammable signal processors allow in-orbit waveform adaptation without physical component replacement. U.S. Space Force units operating in contested electromagnetic environments adopt these platforms aggressively. The technology is collapsing the traditional ten-year satellite replacement timeline toward three-year technology insertion cycles.
FCC Part 25 licensing reforms for military spectrum are compressing contractor regulatory compliance timelines. The streamlined framework reduces orbital debris documentation requirements for small satellites under designated mass thresholds. California-based manufacturers and Arizona launch integrators benefit most directly, reconfiguring production schedules to match accelerated authorization windows.
Multi-orbit service contracts are displacing single-architecture procurement across defense agencies. Unified bandwidth purchasing across geostationary, medium, and low Earth orbits consolidates vendor relationships and simplifies user equipment standardization. U.S. Indo-Pacific Command operations demonstrate this shift most visibly, demanding seamless handoff between orbital regimes during contested logistics scenarios.
North America Military Satellite Market Segmentation
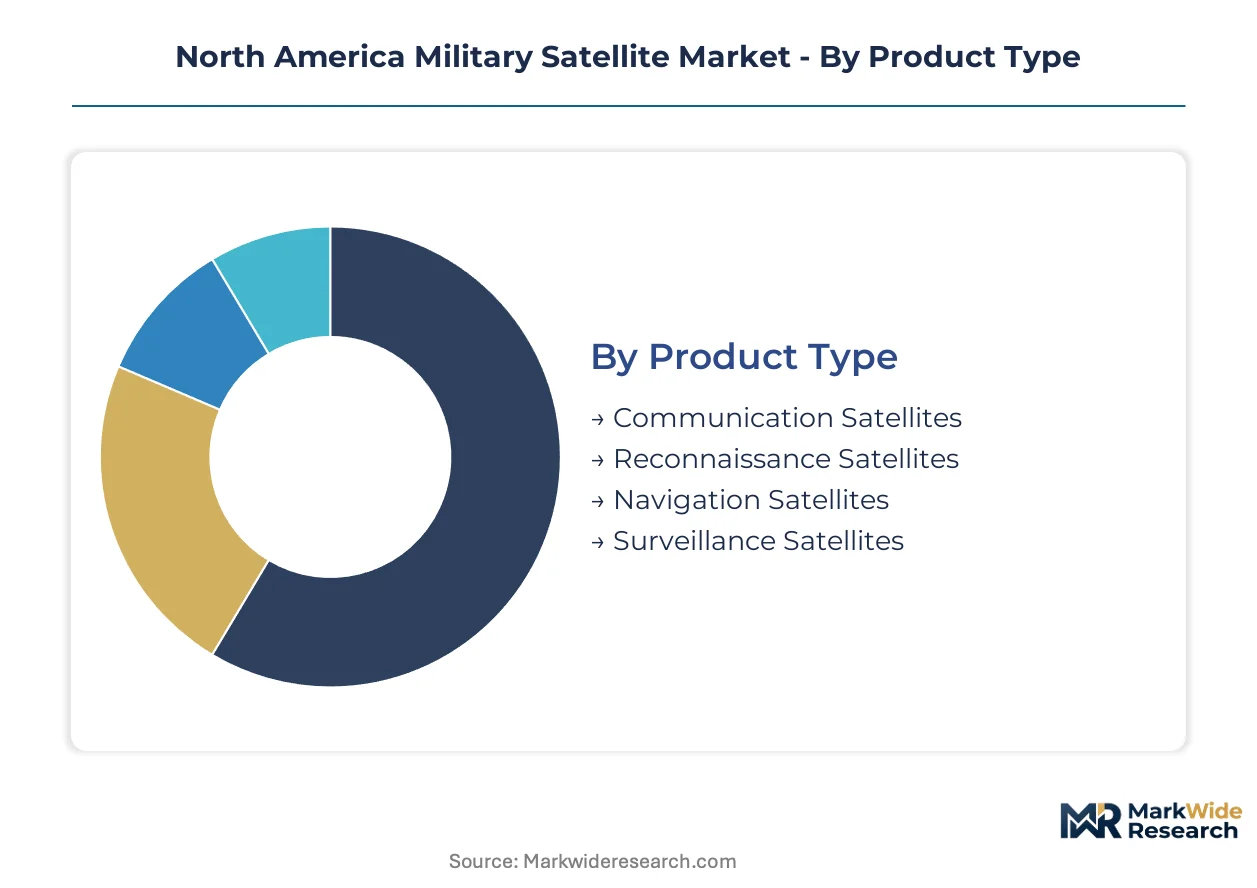
Military satellite procurement in North America fragments across orbital function, user classification, and deployment mode. Each dimension carries distinct ITAR handling requirements and FCC spectrum obligations that reshape vendor qualification pathways.
Product Type:
Mature geostationary platforms anchor established revenue streams while proliferated low-Earth-orbit architectures accelerate refresh cycles across the southwestern manufacturing corridor.
- Communication Satellites:Hardened Ka and X-band payloads with anti-jam signal processors serve beyond-line-of-sight command requirements for unmanned systems operating across the southwestern United States. Arizona and California manufacturing clusters concentrate procurement for these assets under compressed FCC licensing timelines.
- Reconnaissance Satellites:Multi-spectral imaging platforms with nuclear event detection circuitry support modern targeting doctrines demanding accelerated refresh rates. NORAD integrated warning missions in Canadian Arctic latitudes drive specialized polar-orbiting variants.
- Navigation Satellites:Military-grade atomic clock payloads with GPS augmentation capabilities serve NHTSA-linked automotive precision requirements.
- Surveillance Satellites:Persistent wide-area motion imagery platforms track mobile targets across contested electromagnetic environments.
Communication Satellites retains volume leadership; Reconnaissance Satellites holds the steepest expansion curve.
End User:
Procurement authority concentrates with cleared defense entities while intelligence organizations impose the most stringent security compartmentalization requirements.
- Defense Forces:U.S. Space Force orbital architecture directives reshape multi-year production blocks across prime contractor portfolios. U.S. Indo-Pacific Command operations demand seamless multi-orbit handoff capabilities during contested logistics scenarios.
- Intelligence Organizations:TS/SCI-cleared programs for classified bus development face adjudication backlogs that stretch engineering schedules. These entities drive software-defined radio adoption for in-orbit waveform adaptation without physical component replacement.
- Government Agencies:Civil-military coordination bodies manage spectrum allocation proceedings and orbital debris mitigation mandates.
- Research Institutions:Federally funded laboratories prototype next-generation sensor payloads and robotic refueling technologies.
Defense Forces commands the dominant procurement share; Intelligence Organizations generate the most specialized technical requirements.
Deployment Type:
On-orbit assets absorb capital concentration while ground infrastructure demands legacy interoperability investment.
- On-orbit Satellites:Geostationary, medium, and low Earth orbit platforms with hardened electronics operate under U.S. Space Force proliferated architecture mandates. These assets require radiation-hardened semiconductors from qualified domestic foundries.
- Ground Stations:Command and control infrastructure must interoperate with decades-old systems, forcing expensive middleware development and cybersecurity retrofitting across existing networks.
- Satellite Launch Vehicles:Eastern Range and Western Range scheduling constraints restrict deployment velocity for architectures requiring dozens of annual insertions.
- Spacecraft:Manned and unmanned orbital platforms with integrated sensor suites serve dual-use military-civilian applications.
On-orbit Satellites captures the largest capital allocation; Ground Stations demands the most complex integration expenditure.
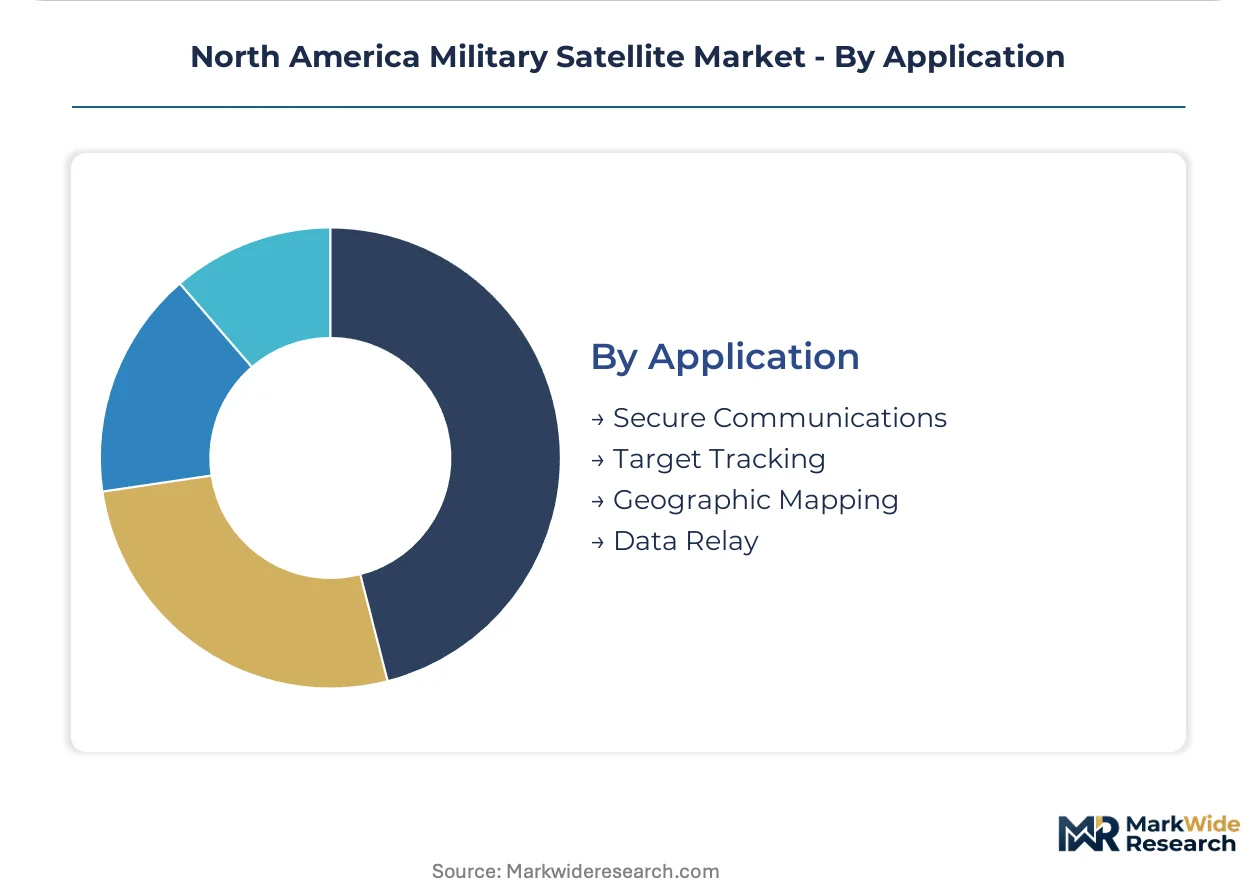
Application:
Secure communications bandwidth requirements expand fastest while target tracking precision standards tighten most aggressively.
- Secure Communications:Beyond-line-of-sight command links for MQ-9 Reaper and attritable platforms drive dedicated military payload procurement independent of commercial lease capacity. FCC Part 25 licensing reforms compress regulatory compliance timelines for these systems.
- Target Tracking:Multi-spectral resolution standards and refresh rate acceleration under modern targeting doctrines reshape sensor payload specifications. NORAD integrated warning missions in northern latitudes depend on these capabilities.
- Geographic Mapping:Precision terrain data supports mission planning and navigation across denied operational environments.
- Data Relay:Cross-linked orbital networks enable persistent connectivity for distributed tactical units.
Secure Communications leads procurement volume; Target Tracking imposes the most demanding technical evolution pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement authorities concentrate satellite manufacturing and launch infrastructure across southwestern United States clusters, with Canadian Arctic coverage demands emerging as a specialized growth vector.
United States
U.S. Space Force orbital architecture directives compress multi-year production blocks for hardened communication payloads. FCC Part 25 licensing reforms accelerate military Ka and X-band spectrum allocation timelines. Arizona and California manufacturing clusters host concentrated satellite bus assembly and launch integration operations serving proliferated low-Earth-orbit mandates.
Canada
NORAD integrated warning missions drive specialized polar-orbiting reconnaissance requirements across underpenetrated northern latitudes. Canadian defense procurement coordinates with U.S. Space Force on Arctic communication coverage gaps. Ontario and Quebec host ground segment integration facilities supporting cross-border satellite command infrastructure.
Mexico
Geographic positioning for southern hemisphere coverage extension supports U.S. military data relay network expansion. Mexican regulatory frameworks accommodate shared spectrum coordination for cross-border tactical communications. Northern border states concentrate ground station infrastructure serving regional bandwidth aggregation.
North America Military Satellite Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Prime contractors with captive manufacturing capabilities anchor multi-year production relationships with defense agencies. Specialist vendors disrupt traditional hardware refresh cycles through software-defined architectures. Competitive moves concentrate on vertical integration into sensor payloads and strategic partnerships for ground segment interoperability.
Among U.S.-based defense primes, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify the integrated-systems archetype through classified bus platform manufacturing and payload-to-ground vertical control. Cesium Astro occupies a specialist position representing the software-defined radio disruption vector that compresses tactical satellite refresh timelines.
| Leading Market Players |
|---|
| The Boeing Company |
| L3Harris Technologies, Inc. |
| Lockheed Martin Corporation |
| Cesium Astro |
| Maxar Technologies |
| Northrop Grumman Corporation |
| Ball Corporation |
| Thales Alenia Space |
| Raytheon Technologies Corporation |
| Others |
Pricing and Supply Chain Analysis
The I-10 freight corridor linking Arizona and California manufacturing clusters to Eastern Range launch facilities concentrates logistics costs for radiation-hardened components, compressing margins for non-integrated suppliers while allowing captive producers to maintain price premiums through controlled component flow.
Pricing Analysis
Cost-plus contracts with Defense Federal Acquisition Regulation Supplement indexation dominate procurement for classified bus platforms, insulating prime contractors from semiconductor foundry cost volatility while exposing subcontractors to raw material pass-through risk. Price differentiation separates TS/SCI-cleared programs from standard ITAR tiers, with security clearance premiums widening as adjudication backlogs intensify. Pricing pressure stems from U.S. Space Force proliferated architecture mandates dispersing orders across smaller production blocks. Intelligence Organizations exhibit lowest price sensitivity due to mission-critical waveform requirements; commercial derivative buyers face acute cost compression.
Supply Chain Analysis
Contract manufacturing concentrates at Honeywell Aerospace, BAE Systems, and CAES Space Systems for radiation-hardened electronics packaging, with these facilities anchoring qualified supplier pools under ITAR constraints. Geographic supply concentration centers on the United States for classified bus assembly, Canada for ground segment integration, and domestic foundries for rad-hard semiconductors. Raw material dependencies include gallium arsenide substrates, depleted uranium shielding, and space-grade aluminum-lithium alloys. Single-source vulnerability pervades qualified semiconductor foundries. Distribution runs through U.S. Space Force program offices with direct contractor relationships, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market enters cyclical recovery driven by congressional appropriation acceleration for next-generation proliferated architectures, reversing procurement stagnation from prior budget continuing resolutions.
For Market Incumbents: Build clearance pipeline moats by sponsoring TS/SCI adjudication fast-track programs for engineering talent, securing staffing advantages as competitor programs stall. Expand captive manufacturing in Arizona to absorb dispersed production block volumes from U.S. Space Force mandates. Software-defined radio specialists threaten hardware refresh cycle compression; counter through in-house production of reconfigurable signal processors.
For New Entrants and Emerging Players: Canadian Arctic coverage gaps present white-space entry points for polar-orbiting reconnaissance payloads serving NORAD integrated warning missions. NORAD coordination requirements create partnership pathways with established ground segment integrators in Ontario and Quebec. Target civil-military dual-use timing payloads for NHTSA-linked automotive precision applications as lower-barrier entry vector.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense prime non-core satellite divisions seeking portfolio rationalization toward space domain awareness. Long-term viability hinges on positioning within proliferated architecture supply chains rather than legacy geostationary platforms. Monitor U.S. Space Force procurement rhythm announcements as inflection signal for production block acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Proliferated Architecture Manufacturing Scale-Up | Arizona and California facilities expand capacity to meet U.S. Space Force multi-orbit deployment mandates. |
| Software-Defined Payload Integration | Reprogrammable signal processors extend satellite operational life under compressed FCC licensing timelines. |
| Canadian Arctic Ground Segment Partnership | Ontario and Quebec facilities capture NORAD cross-border command infrastructure expenditure. |
| Rad-Hard Semiconductor Supply Agreement | Long-term foundry contracts mitigate single-source vulnerability for radiation-hardened electronics. |
| Multi-Orbit Service Contract Consolidation | U.S. Indo-Pacific Command operations demand seamless bandwidth handoff between orbital regimes. |
Research Methodology
The analysis maps communication payload architectures, reconnaissance sensor platforms, and ground segment integration tiers, each validated through program managers at U.S. Space Force, procurement officers at U.S. Indo-Pacific Command, engineering directors at satellite bus manufacturers, and regulatory specialists at FCC. Primary interview findings triangulate against U.S. congressional appropriation records, FCC Part 25 licensing databases, Department of Defense budget justification materials, and U.S. Space Force orbital architecture directives. Bottom-up segment sizing reconciles with top-down defense expenditure allocation patterns.
Assumptions hold U.S. Space Force proliferated architecture mandates as fixed policy direction while varying congressional appropriation timing and ITAR regulatory stringency across sensitivity scenarios. Segmentation models incorporate orbital regime, payload function, security classification tier, and end-user procurement authority. CAGRs derive from production block volume trajectories and refresh cycle compression rates. Forecast inputs include Eastern Range launch capacity constraints and TS/SCI clearance pipeline throughput.
The forecast holds incumbent behavior within observed patterns; aggressive moves by commercial space entrants or accelerated ITAR liberalization would shift outcomes beyond modeled ranges. Quarterly review of U.S. Space Force procurement rhythm announcements and congressional defense subcommittee markup schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
LEO Satellite System Market
Satellite
Global Small Satellite Service Market
Satellite
UK Satellite-Based Earth Observation Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
Satellite Communications Service Market
Satellite
ASEAN Satellite Communications Market
Satellite
Satellite Internet Market
Satellite
Russia Satellite Communications Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
Satellite Services Market
Satellite
Earth Observation Satellite Market
Satellite
China Satellite Imagery Services Market
Satellite
Satellite Connectivity Market
Satellite
Africa Satellite Connectivity Market
Satellite
High-Throughput Satellite Market
Satellite
US Satellite Connectivity Market