
 Spain Rice Market | 2026-2036
Spain Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Rice Market Analytics
Wheat flour is decoupling from traditional paella and arroz dishes in Spanish food manufacturing, creating margin opportunities for specialty rice cultivars. Ebro Foods leverages its vertical milling infrastructure across the Ebro Delta to sustain supply consistency for retail chains. Nomen Foods SL anchors its portfolio on Denominación de Origen certifications, while ARROCERA DEL PIRINEO competes through mountain-grown heritage varieties with limited acreage.
Spain rice comprises Oryza sativa grains cultivated in irrigated paddies, with amylose content ranging from 17% to 22% determining cooking texture and starch release profiles. The crop serves as a staple carbohydrate source across commercial food processing, restaurant service, and direct household consumption channels. White rice occupies the largest volume share in retail distribution, though Arborio rice generates disproportionate margin contribution through premium pricing in food service channels. Brown rice registers the fastest expansion within health-oriented supermarket segments, while bulk packaging dominates institutional procurement despite rigid containers capturing value in specialty store networks.
Spain's Ministry of Agriculture enforces EU Common Agricultural Policy rice-specific payments, while FSSAI-equivalent border standards govern import quality for non-EU origins. The country's national organic regulator certifies pesticide-free paddy under EU Green Deal sustainable farming mandates, restricting conventional chemical applications in protected wetland zones. Stakeholders must monitor water allocation rulings from the Confederaciones Hidrográficas as climate stress intensifies competition for irrigation rights across the Guadalquivir and Segura basins.
Market Dynamics
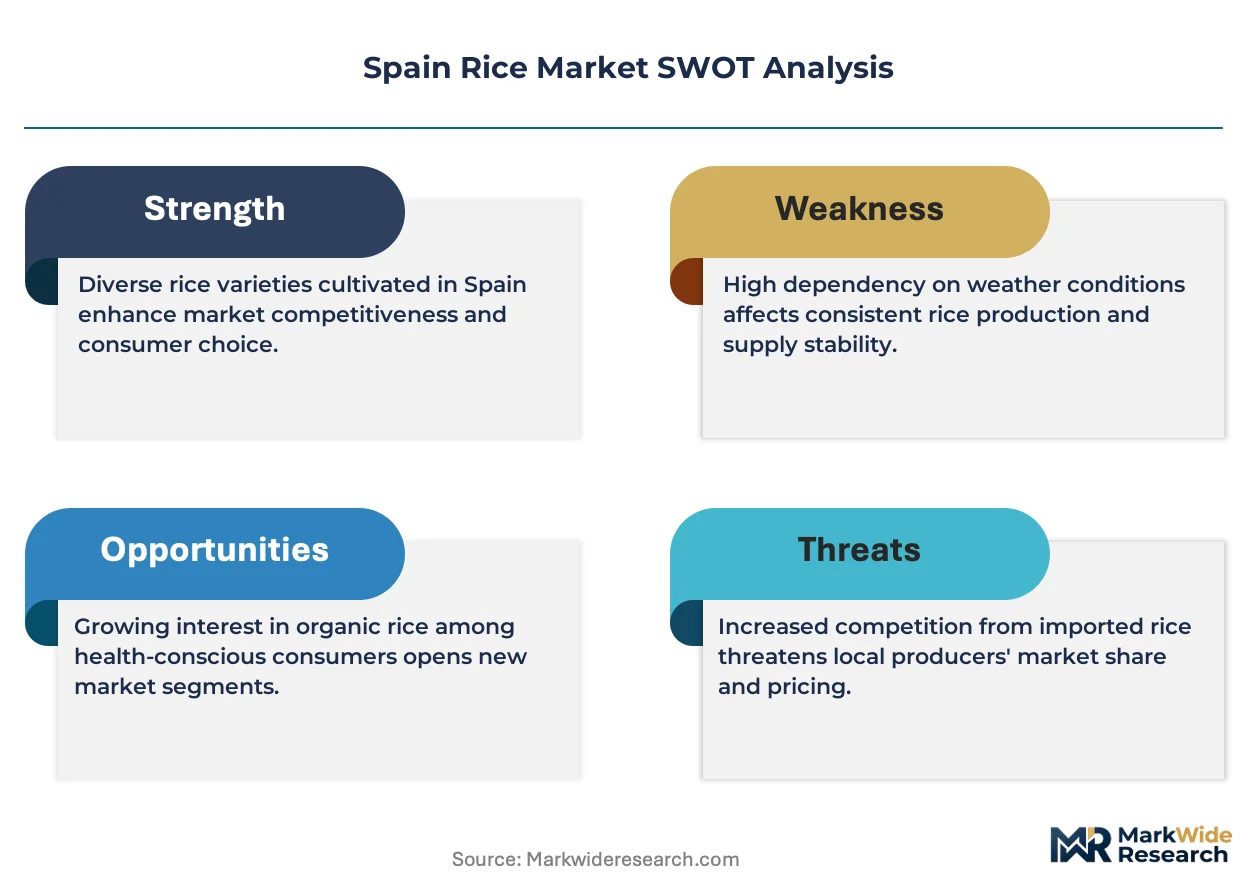
Water scarcity rulings from Spain's Confederaciones Hidrográficas are redistributing irrigation rights away from traditional paddy zones toward higher-value horticulture, compressing planted acreage for heritage rice varieties while elevating input costs for remaining growers.
Growth Catalysts
- EU Green Deal organic transition incentives:Spain's national organic certification scheme subsidizes pesticide-free paddy conversion, accelerating farmer enrollment in protected wetland programs across Valencia's Albufera zone.
- Food service premiumization in Barcelona and Madrid:Restaurant channels command price premiums for Denominación de Origen Bomba and Senia cultivars, pulling volume toward specialty milling grades.
- Amylose-content differentiation:Starch profile specifications ranging from 17% to 22% enable texture-tailored supply contracts for paella-focused manufacturers seeking consistent cooking performance.
Market Restraints
- Irrigation water allocation compression:Confederaciones Hidrográficas rulings in the Guadalquivir and Segura basins restrict flood-irrigation permits, constraining yield potential for established growers.
- Input cost volatility for fertilizer and fuel:Natural gas-derived nitrogen prices and diesel for mechanized harvesting create margin pressure on rain-fed mountain operations in the Pyrenean foothills.
- Substitution by wheat flour in industrial formulations:Food manufacturers reformulate traditional arroz-based products using durum wheat alternatives, eroding bulk white rice demand in processing channels.
Strategic Opportunities
- Andalusian organic acreage expansion:Underpenetrated paddies in Córdoba and Seville provinces await certification conversion, offering first-mover positioning for export-oriented cooperatives.
- Direct-to-restaurant distribution platforms:Digital procurement channels bypass traditional wholesale mercados, enabling heritage variety producers to capture margin from Madrid's Michelin-tier kitchens.
- EU Common Agricultural Policy rice-specific payments:Coupled subsidies for traditional varieties create structural support for Senia and Bomba preservation programs, insulating certified growers from price volatility.
Industry Challenges
- Denominación de Origen compliance timeline:Multi-year certification processes for Albufera and Calasparra designations delay market access for new entrants, favoring incumbent producers with established audit histories.
- Climate-adaptive cultivar development capacity:Public breeding programs lack funding to accelerate drought-tolerant germplasm releases, leaving growers dependent on water-intensive heritage genetics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Rice Market |
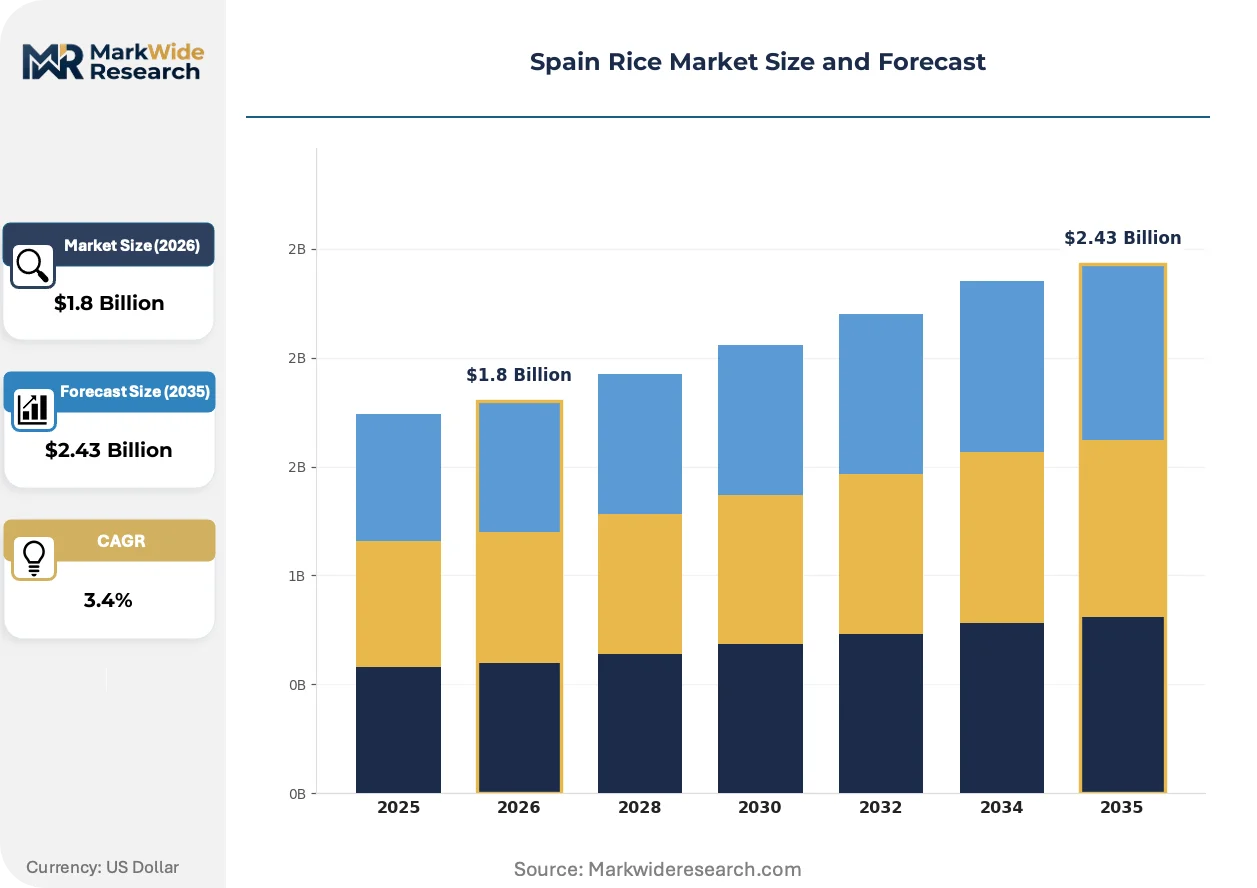
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice, Brown Rice, Basmati Rice, Arborio Rice End Use: Food Processing, Retail Sales, Food Service, Export Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Packaging Type: Bags, Boxes, Bulk, Rigid Containers |
| Companies Covered | Kristov, PESCAVIAR SL, Nomen Foods SL, Valorem Trading Company, ARROCERA DEL PIRINEO, Km Trader, Global Commodity Us, Ebro Foods, Oftex Internacionalizacion SL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Rice Market Evolving Landscape
Precision irrigation and starch analytics are converging to redefine quality assurance across Spain's fragmented rice value chain, compressing information asymmetries between paddy and plate while elevating transparency requirements for origin claims.
Hyperspectral imaging for amylose content verification is expanding into commercial milling operations, enabling real-time starch profile sorting that previously required laboratory analysis. Large-scale processors in the Ebro Delta deploy this technology to guarantee texture consistency for food service contracts. The capability is expanding into mid-tier cooperatives, compressing quality premiums previously captured by laboratory-equipped exporters.
Spain's Ministry of Agriculture enforces tightened EU Green Deal alignment on water-efficiency metrics for agricultural subsidies, requiring documented irrigation reductions to maintain coupled payment eligibility. Industrial rice processors face audit requirements for supply-chain water footprint disclosure. Medium-scale operations in Extremadura respond by retrofitting paddies with subsurface drip systems to preserve certification status.
Restaurant procurement teams in Barcelona and Madrid now specify cultivar provenance and harvest year in supply agreements, displacing anonymous bulk purchasing through traditional wholesale channels. This specification behavior concentrates volume with vertically integrated millers capable of lot-level traceability. The shift is most visible in Valencia's paella-specialist segment, where menu transparency requirements drive direct contracting with Albufera grower cooperatives.
Spain Rice Market Segmentation
Segmentation in Spain's rice market reveals how capital deployment, regulatory compliance, and channel economics fragment value capture across distinct product tiers and customer interfaces. Understanding these divisions exposes where margin concentrates and where infrastructure investments face structural barriers.
Product Type:
Capital intensity varies sharply across milling and processing stages, with polished white rice demanding the heaviest installed infrastructure while heritage varieties require lighter equipment but higher certification overhead.
- White Rice:Polished grains with bran and germ removed through abrasive milling, yielding extended shelf stability and neutral flavor profiles. Spanish retail chains in Madrid and Barcelona concentrate procurement of standard white rice for private-label programs, though water allocation rulings from the Confederaciones Hidrográficas are elevating input costs for Ebro Delta processors.
- Arborio Rice:Short-grain cultivar with high amylopectin content enabling creamy texture release during slow cooking. Michelin-tier kitchens across Catalonia specify lot-level provenance for risotto applications, pulling volume toward vertically integrated millers with traceability systems.
- Brown Rice:Whole-grain format retaining bran layer, commanding shelf space in health-oriented supermarket segments. Spain's national organic certification scheme under EU Green Deal alignment accelerates farmer conversion for pesticide-free paddy.
- Basmati Rice:Aromatic long-grain variety imported primarily for ethnic food service channels and specialty retail. Quality verification relies on DNA authentication to distinguish true Pakistani and Indian origin from cross-bred alternatives.
Most installed capacity flows through White Rice. Expansion is steepest in Brown Rice.
End Use:
Customer concentration patterns determine working capital cycles, with food manufacturers locking in annual contracts while food service buyers operate on spot-market flexibility with premium tolerance.
- Food Service:Restaurant and institutional channels specifying cultivar-grade rice for texture-critical preparations. Valencia's paella-specialist segment drives direct contracting with Albufera grower cooperatives, bypassing traditional wholesale mercados.
- Retail Sales:Branded and private-label packaged rice distributed through supermarket and specialty store networks. Denominación de Origen certifications command price premiums in urban centers where menu transparency requirements influence home cooking behavior.
- Food Processing:Industrial manufacturers incorporating rice flour, starch, or whole grains into formulated products. Wheat flour substitution is eroding bulk white rice demand as reformulators seek cost-advantaged durum alternatives.
- Export:Cross-border shipment of certified heritage varieties to EU and non-EU destinations. FSSAI-equivalent border standards govern import quality for non-EU origins, adding compliance layers for Spanish cooperatives.
Volume concentrates in Retail Sales. Margin expansion is most pronounced in Food Service.
Distribution Channel:
Channel infrastructure requirements scale with traceability demands, from bulk wholesale's minimal handling to specialty retail's lot-level documentation systems.
- Supermarkets:Mass-market retail commanding largest volume share through centralized procurement and private-label development. Chains leverage vertical milling infrastructure across the Ebro Delta to sustain supply consistency.
- Specialty Stores:Curated retail emphasizing Denominación de Origen Bomba and Senia cultivars with harvest-year transparency. Rigid container packaging captures value in this channel where provenance storytelling justifies price elevation.
- Wholesale:Institutional and food service supply through traditional mercado structures. Bulk packaging dominates procurement despite compressing margins for heritage variety producers.
- Online Retail:Digital platforms enabling direct-to-restaurant and direct-to-consumer distribution. Madrid's procurement teams now specify cultivar provenance in supply agreements, displacing anonymous bulk purchasing.
Supermarkets absorb the greatest throughput. Online Retail is climbing the fastest.
Packaging Type:
Packaging capital requirements stratify by automation level, with bulk handling at the low end and rigid container lines demanding precision forming equipment.
- Bulk:Unpackaged rice for institutional procurement and industrial processing. Dominates food manufacturing input channels where texture specifications matter less than unit economics.
- Bags:Flexible packaging for standard retail distribution across white and brown rice segments. Spain's Ministry of Agriculture enforces EU Green Deal alignment on water-efficiency metrics affecting supplier eligibility.
- Rigid Containers:Durable packaging for specialty store networks and premium food service channels. Enables lot-level traceability required by Barcelona and Madrid restaurant procurement teams.
- Boxes:Carton formats for organic and heritage variety positioning. Supports Denominación de Origen compliance documentation and harvest-year labeling.
Bulk formats handle the greatest tonnage. Rigid Containers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Valencia's Albufera rice-growing zone anchors national production capacity through heritage Bomba and Senia cultivars that command sustained price premiums in domestic and export channels.
Madrid
Food service procurement teams in Madrid's Michelin-tier kitchens specify cultivar provenance and harvest year in supply agreements, displacing anonymous bulk purchasing through traditional wholesale mercados. Spain's Ministry of Agriculture enforces EU Green Deal alignment on water-efficiency metrics affecting supplier eligibility. Restaurant channels concentrate demand for Denominación de Origen certifications, pulling volume toward vertically integrated millers with traceability systems.
Catalonia
Barcelona's paella-specialist segment drives direct contracting with grower cooperatives, bypassing traditional distribution structures. The EU Common Agricultural Policy rice-specific payments create structural support for traditional variety preservation programs. Precision irrigation retrofits spread across mid-scale operations to maintain subsidy eligibility under tightened environmental audit requirements.
Andalusia
Underpenetrated paddies in Córdoba and Seville provinces await organic certification conversion, offering positioning for export-oriented cooperatives. Spain's national organic regulator certifies pesticide-free paddy under EU Green Deal sustainable farming mandates. Subsurface drip systems preserve certification status as Confederaciones Hidrográficas rulings restrict flood-irrigation permits across the Guadalquivir basin.
Basque Country
Mountain-grown heritage varieties from the Pyrenean foothills compete through limited acreage and distinct terroir positioning. Input cost volatility for fertilizer and fuel creates margin pressure on rain-fed operations dependent on diesel for mechanized harvesting. ARROCERA DEL PIRINEO anchors production in this sub-region where water scarcity elevates input costs for remaining growers.
Ebro Delta
Large-scale processors deploy hyperspectral imaging for amylose content verification to guarantee texture consistency for food service contracts. Ebro Foods leverages vertical milling infrastructure across this zone to sustain supply consistency for retail chains. The capability is expanding into mid-tier cooperatives, compressing quality premiums previously captured by laboratory-equipped exporters.
Spain Rice Market Competitive Landscape
Portfolio diversification dominates the current landscape as heritage variety preservation programs intersect with organic certification expansion. The vendor base stratifies across three tiers: multinational processors with integrated milling infrastructure, regional cooperatives holding Denominación de Origen credentials, and mountain-based specialists cultivating limited-acreage landraces. Strategic archetypes include scale-driven volume players, certification-dependent premium positioners, and terroir-focused niche operators. M&A activity remains muted while capacity expansion concentrates in organic acreage conversion and precision irrigation retrofitting.
Among Spain-based operators, Ebro Foods exemplifies the scale-driven archetype through its Ebro Delta milling infrastructure, while Nomen Foods SL occupies a position within the certification-dependent tier through its Denominación de Origen portfolio. ARROCERA DEL PIRINEO represents the terroir-focused specialist model, anchoring its market presence on mountain-grown heritage varieties with constrained supply availability.
| Leading Market Players |
|---|
| Kristov |
| PESCAVIAR SL |
| Nomen Foods SL |
| Valorem Trading Company |
| ARROCERA DEL PIRINEO |
| Km Trader |
| Global Commodity Us |
| Ebro Foods |
| Oftex Internacionalizacion SL |
| Others |
Value Network & Pricing Analysis
Skilled paddy workers concentrated in Valencia's Albufera zone command wage premiums that compress margins for heritage variety producers, widening spreads between Denominación de Origen Bomba and standard white rice tiers as labor costs transmit through milling stages.
Pricing Analysis
Input-cost pass-through from water allocation rulings and diesel-powered mechanized harvesting is intensifying margin pressure across rain-fed mountain operations. Pricing stratifies across premium, standard, and economy tiers, with certification grade and cultivar provenance as primary differentiation drivers. Cost compression in bulk white rice channels stems from wheat flour substitution in industrial formulations. Food manufacturers exhibit highest price sensitivity, while Madrid's Michelin-tier kitchens tolerate premiums for lot-level traceability.
Supply Chain Analysis
Single-source vulnerability sits with Ebro Delta processors for large-scale milling capacity, though Valencia's Albufera cooperatives provide heritage variety alternatives. The supply chain draws from Spain's irrigated paddy zones, with dependencies on natural gas-derived nitrogen fertilizers, diesel fuel, and certified seed stock. Tariff exposure looms for Basmati rice imports from Pakistan and India under evolving EU border standards. Distribution runs through vertically integrated millers serving retail chains, alongside direct contracting channels bypassing traditional wholesale mercados.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's rice market represents a late-cycle quality story, as restaurant procurement teams in Barcelona and Madrid pivot toward cultivar-grade specifications that reward traceability investments and compress anonymous bulk channels.
For Market Incumbents: Deploy precision irrigation retrofits as the primary lever to preserve EU Common Agricultural Policy subsidy eligibility under tightened water-efficiency audits. Ebro Foods and Nomen Foods SL should deepen backward integration into certified organic acreage to defend against input cost volatility and emerging export-oriented cooperatives from Andalusia. Channel control through direct-to-restaurant platforms insulates against wholesale margin erosion.
For New Entrants and Emerging Players: The price-point gap between Denominación de Origen Bomba and standard supermarket white rice offers entry latitude for mid-tier heritage positioning. Underpenetrated organic paddies in Córdoba and Seville provinces present the most penetrable geography, with digital procurement platforms enabling bypass of established mercado structures. Target food service channels specifying amylose content verification as the go-to-market angle.
For Investors and Strategic Acquirers: Food conglomerates with existing milling infrastructure are the most active acquirer in this space, seeking Denominación de Origen credentials to complete premium portfolio coverage. Long-term viability hinges on water rights security and organic certification capacity rather than volume scale. Monitor Confederaciones Hidrográficas rulings in the Guadalquivir basin as the signal for irrigation-dependent asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Irrigation Retrofit | Preserves EU Green Deal subsidy eligibility for Ebro Delta and Albufera growers under tightened audit protocols. |
| Direct-to-Restaurant Platform Launch | Captures margin from Madrid's Michelin-tier kitchens specifying cultivar provenance and harvest-year transparency. |
| Organic Certification Conversion | Unlocks first-mover positioning in underpenetrated Andalusian paddies for export-oriented cooperative structures. |
| Hyperspectral Imaging Deployment | Enables real-time amylose content verification that guarantees texture consistency for food service contracts. |
| Heritage Variety Preservation Program | Secures EU Common Agricultural Policy coupled payments insulating Bomba and Senia growers from price volatility. |
Research Methodology
Bottom-up food service and retail channel modeling reconciled against top-down paddy acreage and milling capacity tracking forms the analytical core. Primary interviews with rice mill operations managers, restaurant procurement directors at Barcelona and Madrid establishments, Albufera grower cooperative leaders, and Confederaciones Hidrográficas water resource officials combined with secondary validation from EU Common Agricultural Policy payment databases, Spain's Ministry of Agriculture harvest statistics, customs records for Basmati imports, and Denominación de Origen certification registries. Triangulation between demand-side specification trends and supply-side water allocation constraints ensures coherence.
Historical trendline analysis across planted acreage, yield per hectare, and price realization by cultivar grade established baseline trajectories. The projection framework segments by product type (white, Arborio, brown, Basmati), end use (food service, retail, processing, export), and distribution channel (supermarkets, specialty stores, wholesale, online retail), with CAGRs derived from regression against water availability scenarios and organic conversion enrollment rates. Climate stress indicators and EU subsidy policy continuity serve as key forecast inputs.
Caveats apply where Confederaciones Hidrográficas rulings, natural gas price spikes affecting fertilizer costs, or accelerated wheat flour substitution in industrial formulations could materially shift the outlook. Forecasts reflect documented assumptions about water rights stability and organic certification timeline adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
North America Wheat Market
Grains
Asia-Pacific Rice Market
Grains
Paraguay Grains Market
Grains
Uganda Grains Market
Grains
Precooked Flour Market
Grains
Global Rice Market
Grains
Global Quinoa Market
Grains
China Wheat Protein Market
Grains
Cornmeal Market
Grains
Quinoa Flour Market
Grains
South America Rice Market
Grains
Europe Maize Market
Grains
Global Oats Market
Grains
Oatmeal Market
Grains
Argentina Grains Market
Grains
United States Maize Market