
 Cornmeal Market | 2026-2036
Cornmeal Market Size, Share, and Industry Trends Forecast 2026-2036
Cornmeal Market Intelligence
Demand from industrial food processors for specialized cornmeal grades is bifurcating the market from traditional household consumption patterns. Cargill leverages its vast logistics network to supply bulk quantities to major food manufacturers. Archer Daniels Midland Company specializes in a diverse ingredient portfolio, offering multiple cornmeal granulations. Gruma dominates the production of corn masa flour, a key ingredient in tortillas and related products, particularly in the Americas.
Cornmeal is a flour ground from dried corn, with particle size ranging from coarse to fine. The milling process, using either steel rollers for degerminated meal or traditional stones, determines its texture and nutritional profile. Yellow cornmeal constitutes the largest product segment by volume, while stone-ground cornmeal commands higher prices in artisanal baking applications. Within applications, the snack foods category represents the fastest-growing area, outpacing mature segments like breakfast cereals.
Food safety standards from bodies like the U.S. FDA and the European Food Safety Authority (EFSA) mandate strict limits on mycotoxin contamination. Labeling regulations concerning genetically modified organisms also impact sourcing and market access in various countries, including those following EU guidelines. Future competitiveness depends on managing raw material price volatility and investing in traceability systems to verify product origin and attributes.
Market Dynamics
The bifurcation of the cornmeal market between industrial-grade demand from food processors and traditional household use is the central structural force. This split influences milling technology requirements, logistics networks, and pricing structures for different product grades.
Growth Catalysts
- Gluten-Free Demand:The expanding gluten-free food sector utilizes cornmeal as a primary flour in snacks, baked goods, and batters, creating substantial demand from industrial food manufacturers in North America and Europe.
- Traditional Cuisines:Sustained consumption of corn-based staples like tortillas and arepas in markets such as Mexico and Brazil provides a consistent volume foundation, particularly for corn masa flour.
- Food Safety Premiums:Increasingly stringent food safety standards, including FDA and EFSA regulations, create a market for certified, low-mycotoxin cornmeal, which commands higher price points from quality-conscious buyers.
Market Restraints
- Raw Material Volatility:The price of corn, the primary input, is subject to significant fluctuations based on weather, agricultural policy, and global commodity trading, creating margin pressure for millers.
- Substitution Threats:In certain baking and food processing applications, other flours such as rice, wheat, or tapioca can serve as viable substitutes, limiting pricing power for cornmeal producers.
- Regulatory Barriers:Strict labeling laws for genetically modified organisms in regions like the European Union create sourcing complexities and market access challenges for producers using GM corn.
Strategic Opportunities
- Plant-Based Formulations:Cornmeal's potential as a texturizing agent and base ingredient in plant-based meat and dairy alternatives offers a new, high-value application segment for specialized milled products.
- Fortified Products:There is an opportunity to develop and market cornmeal fortified with vitamins and minerals for public health initiatives and consumer wellness products, particularly in developing nations.
- Traceability Technology:Implementing blockchain or other digital traceability systems to verify origin, non-GMO status, or organic certification can unlock premium pricing and build trust with industrial buyers.
Industry Challenges
- Supply Chain Integrity:Maintaining strict segregation between GMO, non-GMO, and organic corn from farm to mill is an operational challenge that requires significant investment in identity preservation systems.
- Mycotoxin Management:Consistently meeting the stringent mycotoxin limits set by regulators like the EFSA requires costly and continuous testing, sorting, and sourcing protocols, impacting operational efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cornmeal Market |
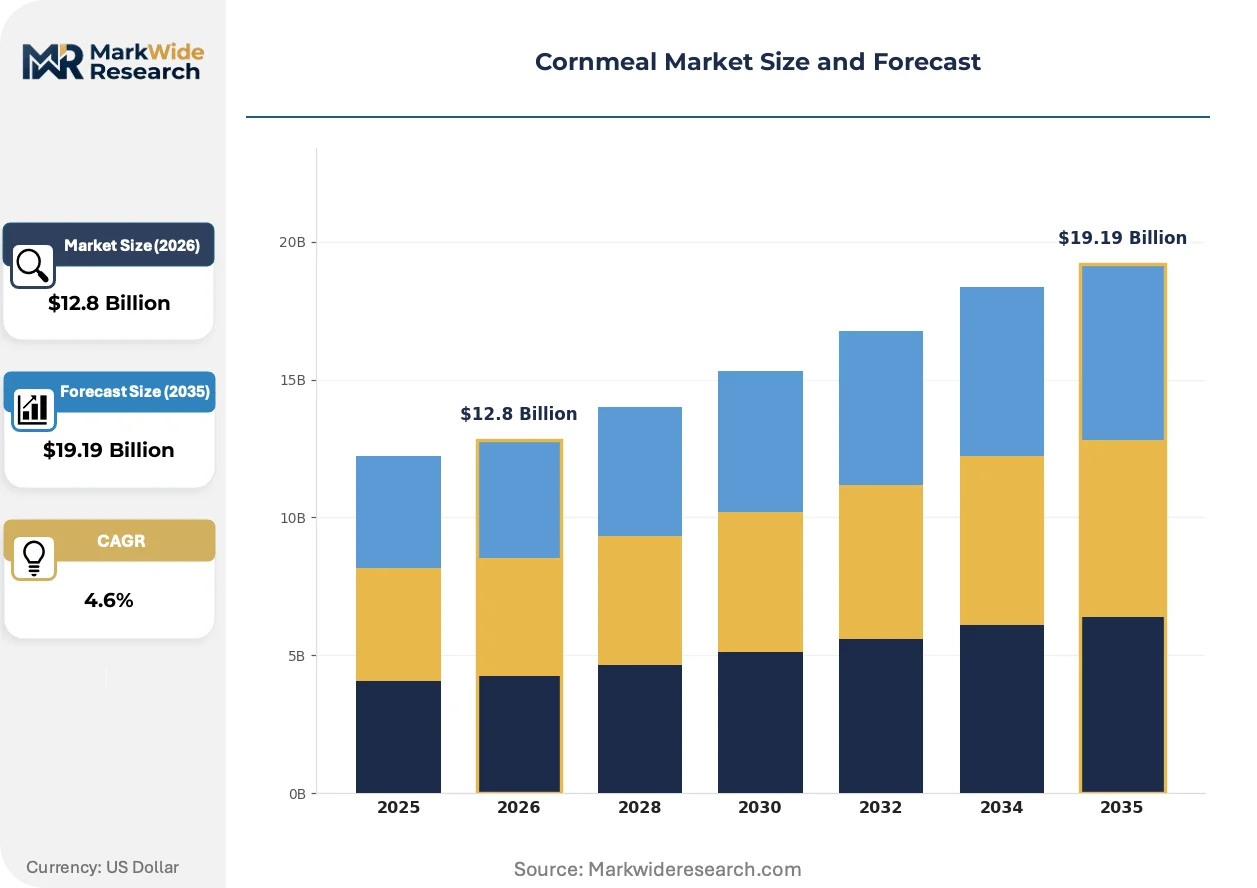
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Cornmeal, White Cornmeal, Blue Cornmeal, Degerminated Cornmeal, Stone-Ground Cornmeal Application: Baking, Breakfast Cereals, Snack Foods, Thickening Agent, Coating Batter End User: Bakeries, Foodservice Providers, Confectionery Manufacturers, Households, Frozen Food Producers Packaging Type: Plastic Bags, Paper Bags, Bulk Containers, Pouches, Jars |
| Companies Covered | Cargill, Archer Daniels Midland Company, Bunge, General Mills, Grain Millers, Gruma, Associated British Foods, Lifeline Foods, Semo Milling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cornmeal Market Strategic Shifts & Innovations
Modernization of cornmeal from a commodity staple to a functional ingredient is driven by food science advancements and consumer health consciousness. This evolution affects processing methods, sourcing verification, and end-product formulation across the value chain.
Precision milling technology, which uses advanced steel rollers and sifters, allows for the creation of cornmeal with highly specific particle sizes and densities. Industrial food manufacturers, especially in the snack foods sector, are rapidly adopting these specialized grades. This capability is supplanting traditional, broadly defined grinds, enabling precise texture and cooking performance in processed foods like extruded snacks and batters.
Regulations from the European Food Safety Authority (EFSA) mandate strict maximum levels for mycotoxins in all maize-derived food products. This directive compels processors to invest in advanced sorting and testing equipment and secure supply chains from low-risk agricultural zones. The infant food and breakfast cereal segments are most impacted, prioritizing certified cornmeal to ensure compliance.
Consumer demand for ingredient transparency is altering procurement patterns for food manufacturers. This shift prioritizes cornmeal with verified attributes like non-GMO or organic certification over conventional bulk supply. The trend is most visible within the premium packaged foods and artisanal baking sectors in North America and Europe.
Cornmeal Market Segmentation
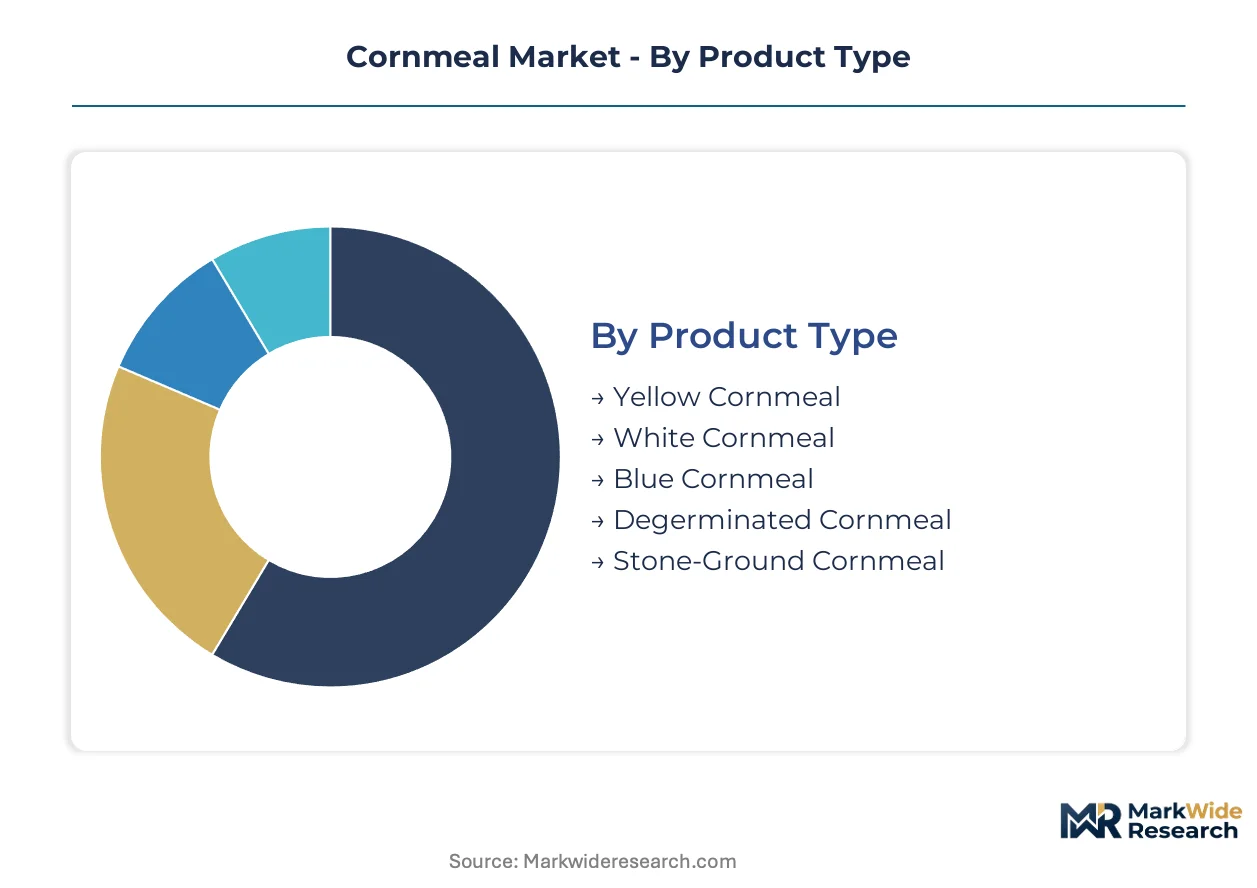
The cornmeal market exhibits diverse characteristics across its value chain. Understanding these distinct segments allows producers to tailor milling processes, distribution strategies, and product formulations. This granular analysis illuminates specific demand drivers and competitive dynamics within the global cornmeal supply.
Product Type:
The distribution of cornmeal product types often reflects regional culinary traditions, with certain varieties dominating domestic consumption while others are more prevalent in export markets.
- Yellow Cornmeal:Ground from yellow corn kernels, providing a characteristic color and slightly sweet flavor. Demand concentrates in North America and Europe for industrial snack food production, driven by its versatility in extruded products.
- Stone-Ground Cornmeal:Milled using traditional stone grinding, retaining germ and bran for a richer flavor and coarser texture. Demand concentrates in artisanal baking sectors in the United States, valued for its nutritional profile and heritage appeal.
- White Cornmeal:Produced from white corn, offering a milder flavor and lighter color, primarily used in Latin American cuisines like arepas.
- Blue Cornmeal:Derived from blue corn, known for its distinct color and earthy taste, finding niche applications in specialty snacks and chips.
- Degerminated Cornmeal:Processed to remove the germ and bran, extending shelf life and resulting in a finer, lighter product preferred for specific baking applications.
Yellow Cornmeal commands the established base. The steepest expansion runs through Stone-Ground Cornmeal.
Application:
Cornmeal's functional versatility allows its integration across a spectrum of food applications, each requiring specific particle sizes and processing attributes.
- Snack Foods:Utilized as a primary flour in extruded snacks, corn chips, and puffed products, contributing texture and structure. Demand concentrates in North America and Europe's processed food industry, fueled by gluten-free consumer trends.
- Baking:Incorporated into breads, muffins, and cornbread, providing a distinct texture and flavor profile. Demand concentrates in household consumption and commercial bakeries, reflecting long-standing culinary practices.
- Breakfast Cereals:Employed in the production of corn flakes and other cereal products, valued for its crisp texture and nutritional content.
- Thickening Agent:Used in soups, stews, and gravies for its ability to increase viscosity, particularly in traditional home cooking.
- Coating Batter:Provides a crisp texture for fried foods like fish and chicken, popular in foodservice and quick-service restaurants.
Snack Foods are gaining share fastest, while Baking maintains substantial volume.
End User:
The diverse end-user landscape for cornmeal necessitates tailored product specifications and supply chain solutions, from bulk industrial deliveries to retail packaging.
- Households:Consumers purchase cornmeal for home cooking, baking, and traditional recipes, often in smaller retail packages. Demand concentrates in regions with strong corn-based culinary heritage, such as Mexico and Brazil, for daily meal preparation.
- Foodservice Providers:Restaurants, cafes, and institutional kitchens utilize cornmeal for various menu items, including batters, coatings, and side dishes. Demand concentrates in urban centers and hospitality industries, driven by consumer dining preferences.
- Bakeries:Commercial bakeries use cornmeal for specialty breads, muffins, and other baked goods, requiring consistent quality and specific grind sizes.
- Confectionery Manufacturers:Employ cornmeal as a dusting agent or ingredient in certain sweets and candies, where fine particle size is crucial.
- Frozen Food Producers:Integrate cornmeal into ready-to-eat meals, breaded items, and frozen snacks, demanding stable and consistent bulk supply.
Industrial users, including Foodservice Providers, are driving innovation. Household consumption provides a stable foundation.
Packaging Type:
Packaging solutions for cornmeal vary significantly, reflecting product volume, shelf-life requirements, and consumer convenience across different distribution channels.
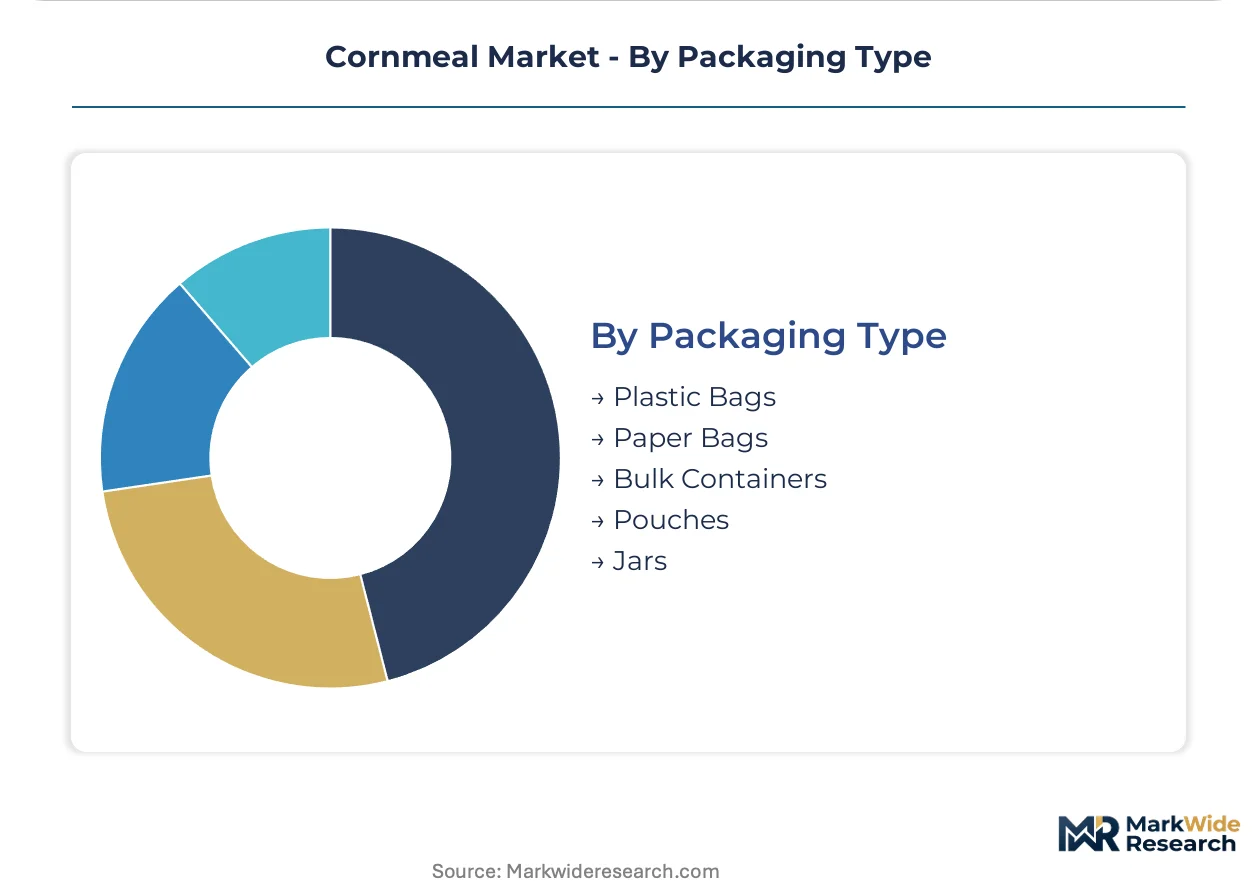
- Bulk Containers:Large-volume packaging like super sacks or silos, designed for efficient transport and storage by major food manufacturers. Demand concentrates among large industrial food processors and commercial bakeries, prioritizing cost-effectiveness and logistical efficiency.
- Paper Bags:Multi-wall paper bags, typically ranging from 1kg to 25kg, offering breathability and cost-effectiveness for retail and commercial use. Demand concentrates in traditional retail channels and smaller bakeries, valued for its affordability and ease of handling.
- Plastic Bags:Offers moisture resistance and durability, commonly used for smaller retail quantities and often featuring re-sealable options.
- Pouches:Flexible packaging providing convenience and extended shelf life, increasingly popular for specialty and organic cornmeal products.
- Jars:Used for premium or specialty cornmeal, offering a high-end presentation and often preferred for smaller, artisanal quantities.
Bulk Containers dominate industrial supply. Pouches are experiencing rapid growth in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in cornmeal often originate from major agricultural producers like the United States, supplying industrial food manufacturers across Europe and Asia. These global movements are influenced by regional culinary preferences and specific processing requirements. Cornmeal demand concentrates in markets with established corn-based food traditions.
United States
United States demand for cornmeal is driven by the expanding gluten-free snack food sector and large-scale industrial baking. The FDA's Food Safety Modernization Act (FSMA) mandates stringent processing and traceability standards for all food ingredients. Major food manufacturers in Chicago and other Midwest hubs utilize specialized cornmeal grades for extruded products.
Mexico
Mexico's cornmeal market is anchored by consistent demand for corn masa flour, essential for traditional tortillas and other staples. National food safety regulations ensure the quality and safety of corn-derived products for widespread consumption. Industrial masa producers in Mexico City and Guadalajara manage vast supply chains for daily food production.
Brazil
Brazilian consumption of cornmeal remains robust, fueled by traditional dishes such as cuscuz and the growing industrial food sector. ANVISA regulations govern the quality and labeling of cornmeal products, impacting both domestic and imported goods. Food processing clusters in São Paulo and Paraná drive significant volume for diverse cornmeal applications.
Germany
Germany exhibits strong demand for high-quality cornmeal, particularly for gluten-free formulations and specialty baking applications. The European Food Safety Authority (EFSA) sets strict maximum levels for mycotoxin contamination in maize products. Food ingredient suppliers in Bavaria and North Rhine-Westphalia focus on certified, compliant cornmeal grades.
Japan
Japanese demand for cornmeal is driven by its use in processed snacks, breakfast cereals, and health-conscious consumer products. The Ministry of Health, Labour and Welfare (MHLW) enforces rigorous food safety standards, including limits on contaminants. Major food manufacturers in Tokyo and Osaka integrate specialized cornmeal into diverse product lines.
Cornmeal Market Key Industry Players
Player mix skews toward large-scale agricultural processors and specialized food ingredient manufacturers. The market exhibits a tiered structure, with global commodity traders alongside regional specialists in corn-based products. These players often pursue portfolio diversification to serve varied end-user segments, from industrial food production to household consumption. Geographic expansion is a key competitive move, targeting both mature and emerging markets.
Within the global commodity trading and processing tier, Cargill and Archer Daniels Midland Company exemplify extensive supply chain integration and diverse ingredient portfolios. These entities leverage vast logistical networks to supply bulk cornmeal to industrial food manufacturers worldwide. Gruma, in contrast, anchors the specialized corn masa flour segment, particularly dominating the Americas with its focus on traditional corn-based food products. These companies collectively shape the market's supply dynamics and product availability across different regions.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Bunge |
| General Mills |
| Grain Millers |
| Gruma |
| Associated British Foods |
| Lifeline Foods |
| Semo Milling |
| Others |
Cost & Logistics Intelligence
Substitution threats from alternative flours like rice or tapioca simultaneously reshape cornmeal supply geography and pricing economics, particularly impacting commodity-grade volumes. This dynamic compels millers to differentiate through specialized products or face margin pressure from readily available substitutes.
Pricing Analysis
The pricing gap between conventional cornmeal and certified, specialized grades is widening due to stringent food safety demands. Commodity spot pricing dominates bulk conventional sales, while contract-based long-term offtake agreements secure specialized grades. Price differentiation stems from quality certification, such as low-mycotoxin status, and the volume scale of purchase. Pricing softness stems from raw material volatility, particularly corn prices, and the availability of substitute flours. Industrial food manufacturers demonstrate lower price sensitivity for certified, functional cornmeal grades, while household consumers remain highly sensitive to conventional product prices.
Supply Chain Analysis
United States, Mexico, and Brazil anchor global cornmeal production, serving both domestic culinary traditions and export markets. The supply chain relies heavily on consistent availability of dried corn kernels as the primary input. Commodity price volatility for corn represents a significant structural risk, impacting miller margins and procurement strategies. Distribution channels include bulk deliveries to large industrial food processors and commercial bakeries, alongside retail packaging for household consumption through traditional and modern trade outlets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cornmeal market operates as a defensive moat story, primarily due to regulatory entrenchment from strict food safety standards that create high barriers to entry for new producers.
For Market Incumbents: Shield existing market share by investing heavily in advanced traceability systems to verify origin and mycotoxin compliance. Expand specialized cornmeal grade production capacity, particularly for gluten-free snack applications, to counter emerging substitute technologies. Pursue vertical integration into corn sourcing to mitigate raw material price volatility and ensure consistent quality for certified products.
For New Entrants and Emerging Players: Differentiate on verified attributes like non-GMO or organic certification to target premium segments in North America and Europe. The artisanal baking sector and plant-based food formulations represent penetrable applications for specialized, high-value cornmeal. Emphasize sustainable sourcing and transparent labeling as a key go-to-market angle for health-conscious consumers.
For Investors and Strategic Acquirers: Increased regulatory scrutiny from bodies like the EFSA reshapes the acquisition landscape, favoring companies with robust compliance and testing infrastructure. Long-term viability hinges on sustained demand from traditional cuisines and the expanding gluten-free sector. Target specialized milling operations with strong food safety certifications and established supply chains for niche products. Watch for increased M&A activity in plant-based ingredient suppliers as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Specialized Grades | Increases supply of high-value cornmeal for industrial snack food manufacturers. |
| Blockchain Traceability Implementation | Verifies product origin and attributes, unlocking premium pricing from quality-conscious buyers. |
| Fortified Product Development | Addresses public health initiatives and consumer wellness trends in developing nations. |
| Strategic Partnership with Plant-Based Food Brands | Integrates cornmeal into high-growth alternative protein formulations. |
| Acquisition of Regional Stone-Grinding Mills | Secures market share in artisanal baking and premium packaged food sectors. |
Research Approach
A spread of perspectives from food scientists, procurement managers, mill operators, and regulatory compliance officers converged on the working assumptions that underpin this market analysis. Primary interviews with these industry stakeholders were combined with extensive secondary validation from sources including FDA guidelines, EFSA reports, agricultural commodity exchanges, and industry association publications. The research employed both bottom-up and top-down triangulation to ensure data accuracy and comprehensive market understanding.
The segmentation dimensions modeled include product type, application, end user, packaging type, and regional consumption patterns across the analysis window. Compound Annual Growth Rates were derived from a rigorous analysis of historical trends and future growth projections for each segment. Key industry-specific forecast inputs included the expansion trajectory of the gluten-free market and global corn harvest yields.
The analysis sits within stated boundaries; outcomes outside significant shifts in global agricultural policy, extreme weather events impacting corn harvests, or unforeseen technological disruptions would require recalibration. Forecasts reflect assumptions documented through extensive research and expert consensus. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Global Maize Market
Grains
Pea Grits Market
Grains
North America Wheat Protein Market
Grains
Green Banana Flour Market
Grains
Argentina Grains Market
Grains
North America Wheat Flour Market
Grains
Grain Dryers Market
Grains
Black Gram Market
Grains
Wheat Flour Market
Grains
Egypt Rice Market
Grains
Asia-Pacific Rice Market
Grains
Fortified Rice Market
Grains
Rice Flour Market
Grains
Soya Flour Market
Grains
South America Wheat Market
Grains
Global Quinoa Market