
 Oatmeal Market | 2026-2036
Oatmeal Market Size, Share, and Industry Trends Forecast 2026-2036
Oatmeal Market Intelligence
Advancements in enzymatic hydrolysis for oat processing is reshaping the production of instant oatmeal and beverage additives. The Quaker Oats Company leverages its extensive distribution network to command shelf space in retail. Kellogg Company competes by integrating fortified oat products into its broader breakfast cereal portfolio. Bob’s Red Mill Natural Foods, Inc. differentiates through its focus on minimally processed and organic oat varieties, catering to health-conscious consumers.
Oatmeal is a food product derived from hulled oat grains, or groats, that have been milled, steel-cut, or rolled. Its key functional component is beta-glucan, a soluble fiber known for its cholesterol-lowering properties. Instant oatmeal formats lead in volume due to consumer convenience, while rolled oats maintain a strong position in traditional breakfast cereals. The bakery ingredients application represents a significant, high-margin outlet for specialized oat flours and flakes utilized by food processing companies.
Regulations from bodies like the US FDA and the European EFSA govern health claims related to beta-glucan content and heart health, directly influencing product labeling. In India, FSSAI standards for fortified foods shape market entry requirements for breakfast cereal manufacturers. Future competitive advantage will depend on navigating these disparate regulatory landscapes while innovating in texture and flavor profiles to meet evolving consumer tastes.
Market Dynamics
The convergence of consumer demand for functional foods and advancements in ingredient science is the central force shaping the oatmeal market. The recognition of oat-derived beta-glucan for its health benefits is driving innovation beyond traditional breakfast bowls into higher-value nutraceutical and food ingredient applications.
Growth Catalysts
- Regulatory Health Claims:The European Food Safety Authority (EFSA) permits health claims linking oat beta-glucan consumption to the maintenance of normal blood cholesterol levels, directly enabling manufacturers to market products for heart health.
- Nutraceutical Integration:Demand from nutraceutical manufacturers for oat extracts and beta-glucan concentrates is expanding the market, as these ingredients are incorporated into dietary supplements, functional beverages, and fortified food products.
- Gluten-Free Processing:The implementation of advanced optical and mechanical sorting technologies to remove gluten-containing grains allows producers to certify products as gluten-free, opening the market to consumers with celiac disease or gluten sensitivity.
Market Restraints
- Input Price Volatility:Oat crop yields are highly susceptible to adverse weather conditions and climate variability in key producing regions, leading to unpredictable fluctuations in raw grain prices and pressuring manufacturer margins.
- Threat of Substitution:The market faces competition from other healthy grains and seeds such as quinoa, chia, buckwheat, and amaranth, which are also marketed for their high fiber and protein content in the breakfast category.
- Agronomic Constraints:A limited genetic diversity in commercially cultivated oat varieties can increase vulnerability to specific plant diseases and pests, posing a systemic risk to the stability of the global oat supply.
Strategic Opportunities
- Fortification Programs in Asia:Government-backed food fortification initiatives in countries like India, guided by FSSAI standards, create opportunities for fortified oatmeal to address nutritional deficiencies and enter expanding consumer markets.
- Savory Applications:There is an untapped opportunity in developing savory oat-based products, such as meal bases, savory porridges, and meat extenders, appealing to consumers seeking versatile and healthy plant-based meal options.
- Upcycled Oat Side-Streams:Utilizing oat hulls and other processing byproducts to create value-added ingredients like soluble fiber, antioxidants, or biofuel feedstock presents a circular economy opportunity that improves sustainability and profitability.
Industry Challenges
- Cross-Contamination Auditing:Maintaining the integrity of a gluten-free supply chain requires rigorous and costly auditing, testing protocols, and dedicated equipment to prevent cross-contamination from wheat, barley, or rye at every stage.
- Navigating Global Labeling Laws:Manufacturers face operational complexity in aligning product labels with the disparate health claim and nutritional labeling regulations set by bodies like the US FDA, Health Canada, and the EFSA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oatmeal Market |
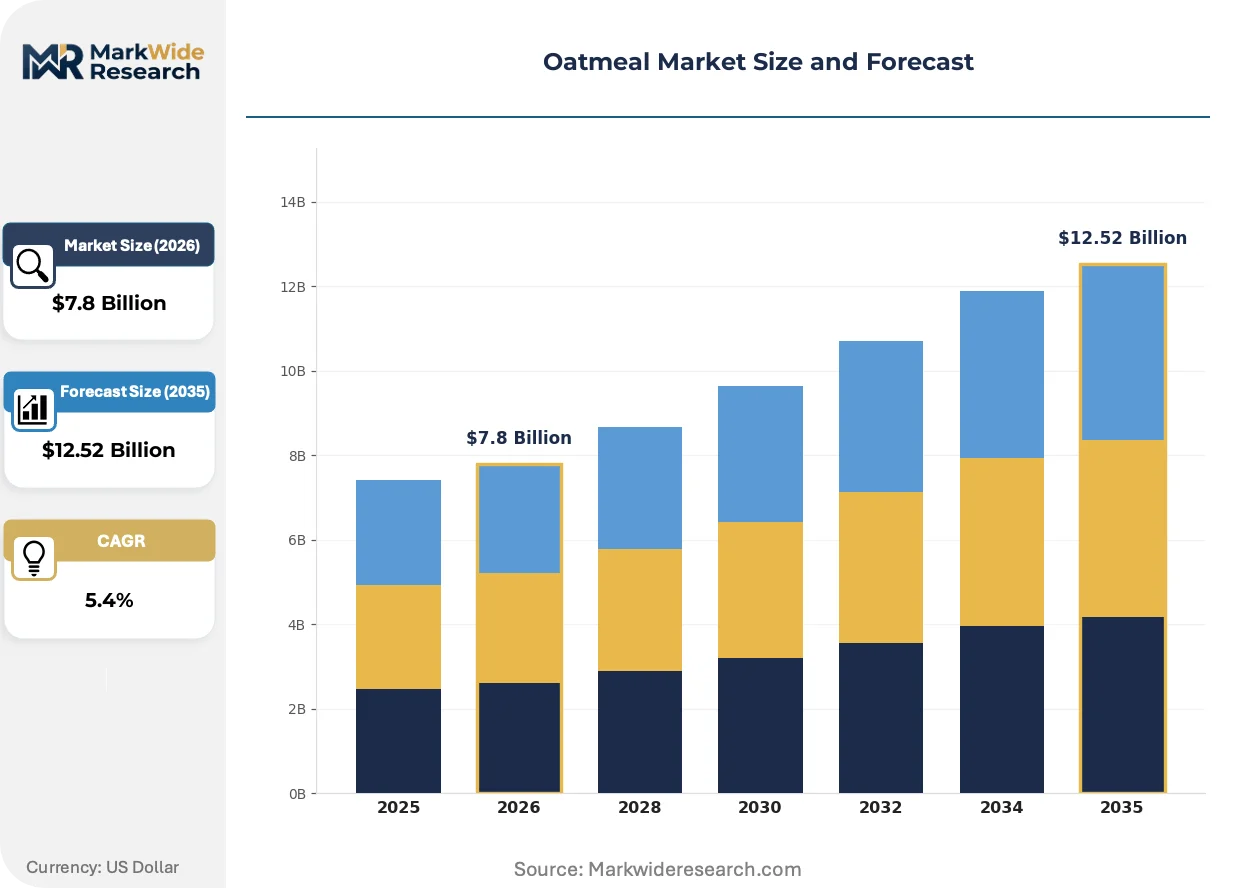
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Oatmeal, Rolled Oats, Steel-Cut Oats, Oat Flour, Scottish Oats Form: Flakes, Powder, Granules, Organic, Fortified Application: Breakfast Cereals, Bakery Ingredients, Snack Production, Beverage Additives, Animal Feed End User: Food Processing Companies, Nutraceutical Manufacturers, Foodservice Industry, Retail Consumers |
| Companies Covered | Kellogg Company, Nature’s Path Foods, Inc., The Quaker Oats Company, Grain Millers, Inc., Post Holdings, Inc., Nestlé S.A., Bob’s Red Mill Natural Foods, Inc., Hain Celestial Group, Inc., General Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oatmeal Market Strategic Shifts & Innovations
The market is being redefined by a focus on textural innovation and the extraction of high-value functional ingredients from oats. This shift moves the category beyond simple convenience to deliver specialized sensory experiences and targeted nutritional benefits, meeting the demands of more discerning consumers.
Advanced Processing Technologies Digital twin modeling is an emerging technology for optimizing oat processing. R&D departments within large food conglomerates are adopting this software to simulate outcomes of processes like enzymatic hydrolysis and extrusion. This approach is virtualizing the product development cycle, enabling rapid prototyping of new textures and nutritional profiles while minimizing costly and time-consuming pilot plant trials.
Whole Grain Labeling Standards Regulations from the US FDA governing "whole grain" content claims are influencing product formulation. These rules compel manufacturers to ensure their products meet specific compositional criteria to legally use marketing terms associated with heart health and fiber. The ready-to-eat cereal and snack bar segments are most affected, investing in analytical testing to validate on-pack claims and maintain consumer trust.
Consumption Pattern Diversification A notable behavioral shift sees oats transitioning from a breakfast-exclusive food to a versatile, all-day ingredient. This movement disrupts the traditional breakfast aisle by creating new demand points in baking sections and online for oat flours, flakes, and groats. This trend is particularly prominent in North American and German households, where consumers actively seek plant-based ingredients for home cooking and baking.
Oatmeal Market Segmentation
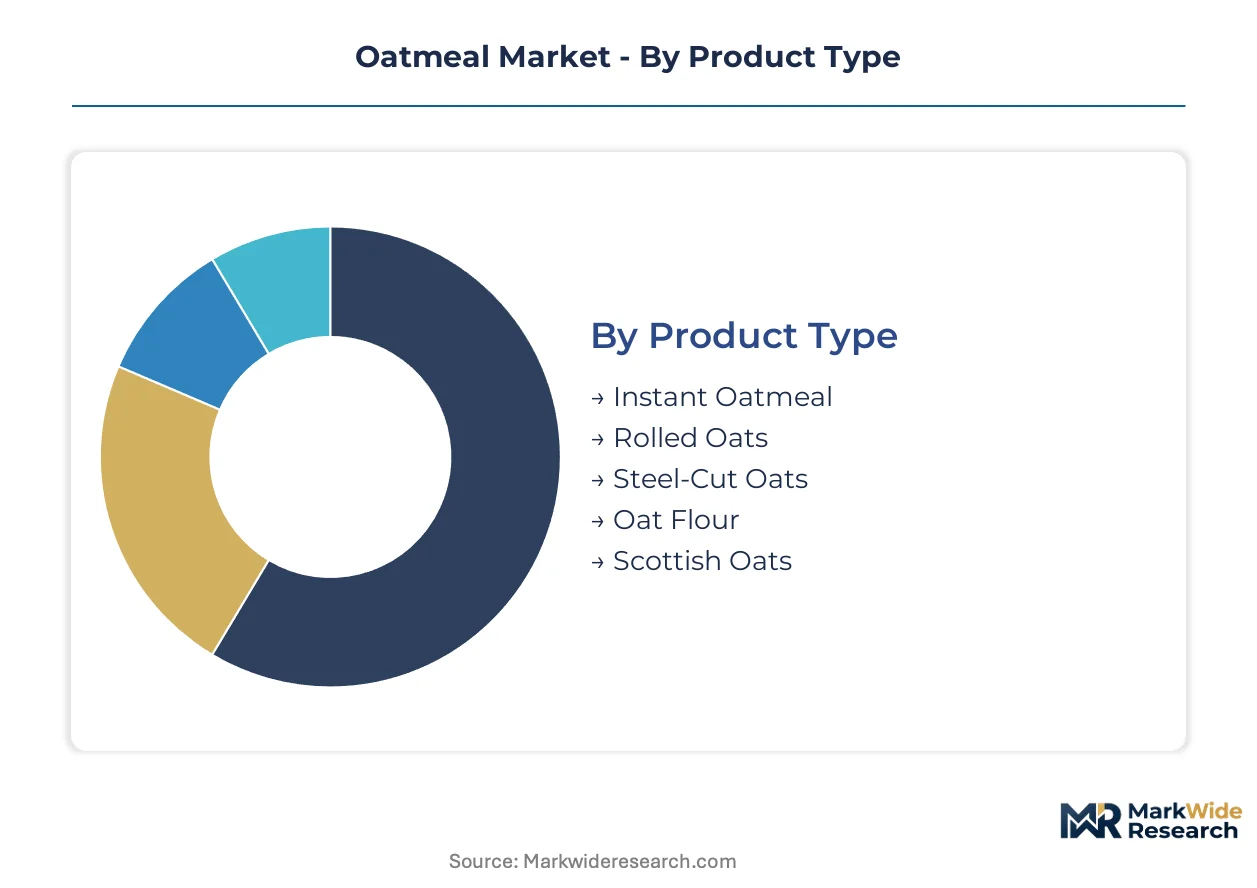
The oatmeal market exhibits diverse segmentation, reflecting varied processing technologies, consumer preferences, and end-use applications. Understanding these distinct segments is crucial for manufacturers to tailor product development and market strategies effectively. This detailed classification highlights key demand drivers and competitive dynamics across the oat value chain.
Product Type:
The diversity in product type reflects varied processing methods and consumer preferences for oat-based foods, driving distinct market sub-segments.
- Instant Oatmeal:This product type undergoes extensive pre-cooking and rolling, requiring minimal preparation time for consumers. Demand concentrates in urban households seeking quick breakfast solutions, driven by busy lifestyles and convenience.
- Rolled Oats:Produced by steaming and flattening oat groats, these oats offer a chewy texture and moderate cooking time. They maintain a strong position in traditional breakfast cereals, particularly in North American and German households valuing sustained energy release.
- Steel-Cut Oats:These are whole oat groats cut into pieces, retaining a robust texture and nutty flavor. Steel-cut oats appeal to health-conscious consumers valuing minimal processing.
- Oat Flour:Finely ground from whole oats, oat flour serves as a versatile ingredient in baking and gluten-free food production.
- Scottish Oats:Traditionally stone-ground, these oats have a creamy texture when cooked, favored for their unique mouthfeel.
Rolled Oats holds installed capacity. Instant Oatmeal is rotating up the share rankings.
Form:
The physical form of oatmeal products directly influences their application and handling characteristics across various industrial and consumer uses.
- Flakes:This common form results from steaming and flattening oat groats, providing quick cooking properties and versatility. Demand for oat flakes is high in breakfast cereals and snack bar production due to their textural contribution.
- Powder:Finely milled oat powder offers excellent solubility and dispersibility, making it ideal for beverage additives and functional food formulations. Nutraceutical manufacturers integrate oat powder for its beta-glucan content.
- Granules:Oat granules provide a coarser texture than powder, suitable for specific bakery applications and as a topping.
- Organic:This form denotes oats cultivated without synthetic pesticides or fertilizers, appealing to consumers seeking natural and sustainable options.
- Fortified:Fortified oats contain added vitamins, minerals, or other nutrients, addressing nutritional deficiencies in target populations. Government-backed fortification initiatives in India drive this segment.
Consumer demand for Organic formats is expanding most quickly, while Flakes maintain significant industrial utility.
Application:
The end-use applications for oatmeal extend beyond traditional breakfast, reflecting its versatility as an ingredient in diverse food categories.
- Breakfast Cereals:This traditional application remains a primary market for various oat product types, including rolled and instant oats. Consumer preference for high-fiber and heart-healthy options in Germany drives consistent demand.
- Bakery Ingredients:Specialized oat flours and flakes serve as key components in bread, cookies, and other baked goods, offering texture and nutritional benefits. Food processing companies leverage these ingredients for high-margin product development.
- Snack Production:Oats are incorporated into energy bars, granola, and other snack items, catering to convenience-oriented consumers.
- Beverage Additives:Oat-derived ingredients enhance nutritional profiles and texture in plant-based milks, smoothies, and functional drinks.
- Animal Feed:Oats serve as a nutritious and digestible feed component for livestock, particularly horses and poultry, providing essential energy.
Beverage Additives applications are gaining share fastest, driven by evolving dietary trends. Breakfast Cereals continues to anchor market volume.
End User:
Different end-user segments drive distinct demand patterns for oat-based products across the value chain, from industrial processing to direct consumer sales.
- Food Processing Companies:These entities purchase bulk oat ingredients for manufacturing a wide array of consumer food products, including cereals, baked goods, and snacks. Innovations in enzymatic hydrolysis offer these companies new ingredient functionalities.
- Nutraceutical Manufacturers:This segment utilizes oat extracts and beta-glucan concentrates for dietary supplements and functional foods due to their health benefits. Demand from nutraceutical manufacturers is expanding the market significantly.
- Foodservice Industry:Restaurants, cafes, and institutional kitchens use oatmeal products for breakfast menus and ingredient applications.
- Retail Consumers:Households directly purchase packaged oatmeal products from supermarkets and online channels for home consumption.
Nutraceutical Manufacturers represents a significant growth trajectory, while Food Processing Companies maintain foundational market stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oat processing capabilities in countries like Canada and the United States facilitate significant exports of oat ingredients to consumer markets in Europe and Asia. These trade corridors underpin global supply chains for diverse oat-based products. Demand for functional foods drives regional market dynamics.
Germany
Consumer preference for high-fiber and heart-healthy breakfast options drives demand in Germany. The European Food Safety Authority (EFSA) permits health claims linking oat beta-glucan to cholesterol reduction, influencing product marketing. Food processing hubs in regions like North Rhine-Westphalia focus on integrating oat-derived ingredients into functional foods.
India
Government-backed food fortification initiatives create opportunities for fortified oatmeal in India. FSSAI standards for fortified foods shape market entry requirements for breakfast cereal manufacturers. Delhi-NCR and Mumbai serve as key distribution centers for both imported and domestically produced oat products.
United States
Demand for instant oatmeal and gluten-free varieties fuels market expansion in the United States. The US FDA regulates health claims related to beta-glucan content and whole grain labeling, ensuring consumer trust. Major food manufacturers in the Midwest, particularly around Chicago, drive innovation in oat-based product development.
Canada
Canada's strong agricultural base positions it as a major supplier of oats for both domestic consumption and export. Health Canada's regulations support the marketing of oat products with recognized health benefits. Processing facilities in Saskatchewan and Manitoba form the core of the country's oat milling industry.
France
Increasing consumer interest in plant-based diets and natural ingredients boosts oat consumption in France. The national food safety authority, ANSES, provides guidance on nutritional recommendations for whole grains. Food innovation clusters in regions like Brittany explore new applications for oat flours and flakes.
Oatmeal Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share across the oatmeal value chain. The market structure exhibits a tiered consolidation, with large food conglomerates operating alongside niche organic and minimally processed brands. Portfolio diversification and strategic partnerships represent dominant competitive moves among industry participants.
At the scale-driven end, The Quaker Oats Company leverages its extensive distribution network to command retail shelf space. Kellogg Company integrates fortified oat products into its broader breakfast cereal portfolio, appealing to a wide consumer base. Bob’s Red Mill Natural Foods, Inc. exemplifies a specialist archetype, focusing on minimally processed and organic oat varieties to cater to health-conscious consumers.
| Leading Market Players |
|---|
| Kellogg Company |
| Nature’s Path Foods, Inc. |
| The Quaker Oats Company |
| Grain Millers, Inc. |
| Post Holdings, Inc. |
| Nestlé S.A. |
| Bob’s Red Mill Natural Foods, Inc. |
| Hain Celestial Group, Inc. |
| General Mills, Inc. |
| Others |
Cost & Logistics Intelligence
Oat crop yield volatility, driven by adverse weather conditions, determines both pricing tier spreads for oat products and the supply chain shape for manufacturers. This inherent agricultural risk directly influences raw material costs across the value chain.
Pricing Analysis
The pricing gap between minimally processed steel-cut oats and highly processed instant oatmeal reflects differing production complexities and consumer convenience premiums. Finished product pricing operates on a value-based model, where organic certification and gluten-free claims drive significant price differentiation. Input price volatility from raw oat grains exerts continuous pricing pressure across all product categories. Retail consumers purchasing traditional breakfast cereals exhibit higher price sensitivity compared to nutraceutical manufacturers sourcing high-purity beta-glucan concentrates.
Supply Chain Analysis
Upstream oat grain feedstock sourcing centers primarily on major agricultural producers like Canada and the United States. The supply chain relies heavily on bulk commodity shipments of oat groats to milling facilities globally. A structural risk arises from agronomic constraints, including limited genetic diversity in cultivated oat varieties, increasing vulnerability to plant diseases. Downstream distribution runs through established retail channels for consumer products and specialized B2B ingredient suppliers for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Oatmeal market offers a service-attach opportunity, with oat-derived beta-glucan concentrates expanding faster than traditional oat grain sales. This shift emphasizes functional ingredients over base commodity volumes.
For Market Incumbents: Insulate core market share by diversifying product portfolios beyond traditional breakfast cereals into functional food ingredients. Invest in advanced processing technologies like enzymatic hydrolysis to extract higher-value beta-glucans, mitigating the threat of substitution from other healthy grains. Strengthen distribution networks in emerging markets, particularly those with government-backed fortification programs. Pursue vertical integration into gluten-free processing to control supply chain integrity.
For New Entrants and Emerging Players: Build out niche market positions by focusing on untapped savory applications and specialized organic offerings. Target health-conscious consumers in urban centers seeking minimally processed and sustainable options. Develop unique flavor profiles and textural innovations to differentiate from established brands. A direct-to-consumer go-to-market strategy can foster brand loyalty and capture higher margins for premium products.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors vertically integrated ingredient specialists and brands with strong organic certifications. Long-term viability is anchored in the sustained consumer demand for functional foods and plant-based diets. Target acquisition profiles include nutraceutical manufacturers specializing in oat beta-glucan extraction or small-to-medium-sized organic oat processors. The signal to watch is the expansion of regulatory health claims for oat-derived ingredients in new geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Enzymatic Hydrolysis Investment | Optimizes beta-glucan extraction for high-value nutraceutical applications. |
| Gluten-Free Certification Expansion | Opens new consumer segments with celiac disease or gluten sensitivity. |
| Savory Oat Product Launch | Diversifies consumption patterns beyond breakfast, expanding market reach. |
| Strategic Partnerships with Nutraceuticals | Integrates oat ingredients into functional beverages and dietary supplements. |
| Upcycled Oat Side-Stream Development | Enhances sustainability and creates new value-added ingredients from waste. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade publications, and agricultural commodity reports. This approach involved extensive interviews with food scientists, procurement managers at food processing companies, regulatory affairs specialists, and brand managers. The analysis triangulated insights from both bottom-up market sizing and top-down industry validations.
Forecast inputs considered include consumer dietary shifts, regulatory mandates for fortification, and advancements in processing technologies. The analytical framework modeled market dynamics across product type, form, application, end user, and regional consumption patterns over the projection horizon. Compound annual growth rates were derived from historical data trends and projected market influences, incorporating specific inputs like beta-glucan content and gluten-free certification rates.
Sensitivities concentrate around climate variability impacting oat crop yields and evolving international trade policies. Forecasts reflect assumptions regarding consumer health trends and regulatory stability. Material shifts in global agricultural output or health claim regulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Masa Corn Products Market
Grains
Asia-Pacific Wheat Market
Grains
Durum Wheat Flour Market
Grains
Oat Flour Market
Grains
Oat Bran Market
Grains
Argentina Grains Market
Grains
Europe Wheat Market
Grains
Africa Maize Market
Grains
Whole-Wheat Flour Market
Grains
Non-Basmati Rice Market
Grains
Global Precooked Corn Flour Market
Grains
Organic Wheat Flour Market
Grains
Grain Augers Market
Grains
India Rice Market
Grains
Sorghum Flour Market
Grains
Red Rice Market