
 Asia-Pacific Rice Market | 2026-2036
Asia-Pacific Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Rice Market Outlook
Food service operators is rotating toward aromatic and premium-grade rice as hotel and restaurant chains expand across Southeast Asia. China National Cereals, Oils and Foodstuffs Corporation anchors state-level procurement through its control of strategic reserves and milling infrastructure. KRBL Limited dominates the basmati export channel with integrated operations spanning Punjab and Haryana. Olam International Limited navigates origin diversification across multiple ASEAN supply bases to manage climate risk.
Asia-Pacific rice comprises the starchy seed of Oryza sativa and Oryza glaberrima species, typically milled to 5-20% moisture content for human consumption as a dietary staple providing caloric and micronutrient intake across diverse cuisines. White rice sustains the largest volume share due to its extended shelf stability and universal cooking adaptability, though margin pools are thinning amid commodity competition. Aromatic rice captures premium positioning through terroir-linked varieties such as Thai hom mali and Indian basmati, with GI certifications protecting price architecture. The export market segment is accelerating fastest as Middle Eastern and African buyers deepen procurement ties with Mekong Delta and Kakinada port corridors.
India's FSSAI mandates iron and folic acid fortification in distributed rice, reshaping miller capital expenditure toward blending and coating equipment. Thailand's Department of Rice enforces hom mali DNA authentication and moisture standards under its national GI framework, restricting market access for non-compliant origins. Vietnam's Ministry of Agriculture and Rural Development operates pesticide residue monitoring protocols aligned with EU MRL thresholds for European-bound shipments. Stakeholders must monitor evolving phytosanitary barriers and origin certification requirements as import jurisdictions tighten traceability demands.
Market Dynamics
India's FSSAI fortification mandates and Thailand's hom mali GI protections are restructuring miller capital allocation and export corridor access across Southeast Asia, concentrating processing capacity in Vietnam's Mekong Delta and eastern India's parboiling belt.
Growth Catalysts
- Fortification mandates:India's FSSAI requires iron and folic acid enrichment in distributed rice, forcing millers to install blending and coating equipment that creates captive demand for micronutrient premix suppliers.
- Hotel and restaurant procurement:Food service operators across Southeast Asia are expanding aromatic and specialty grade sourcing as international chains penetrate secondary cities.
- Hom mali GI protections:Thailand's Department of Rice enforces DNA authentication and moisture standards, restricting non-compliant origins and preserving price premiums for certified exporters.
Market Restraints
- Input cost volatility:Fertilizer and diesel prices swing with energy markets, compressing margins for smallholder-dependent supply bases in Myanmar and Cambodia.
- Supply concentration risk:The Mekong Delta processing cluster dominates export-ready white rice, exposing buyers to single-region flood and salinity intrusions.
- Substitution pressure:Wheat and cassava starch displace rice in industrial applications across Bangladesh and Indonesia where price spreads widen.
Strategic Opportunities
- Underpenetrated Myanmar:Sanctions easing and port modernization at Yangon could unlock delta production for Middle Eastern buyers currently sourcing through Vietnamese intermediaries.
- EU-bound residue compliance:Vietnam's Ministry of Agriculture and Rural Development operates pesticide monitoring protocols aligned with EU MRL thresholds, creating a certification arbitrage window for premium European contracts.
- Blockchain traceability:Converging IoT sensors and distributed ledger systems enable origin verification that satisfies tightening Japanese and South Korean import documentation requirements.
Industry Challenges
- Blending equipment retrofit timelines:Small and mid-size millers in Bihar and Uttar Pradesh face 18-24 month capex recovery periods for fortification-compliant infrastructure.
- Phytosanitary certification complexity:Australia's Department of Agriculture and Water Resources and Saudi Arabia's SFDA impose divergent weed seed and moisture protocols, forcing exporters to maintain parallel quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Rice Market |
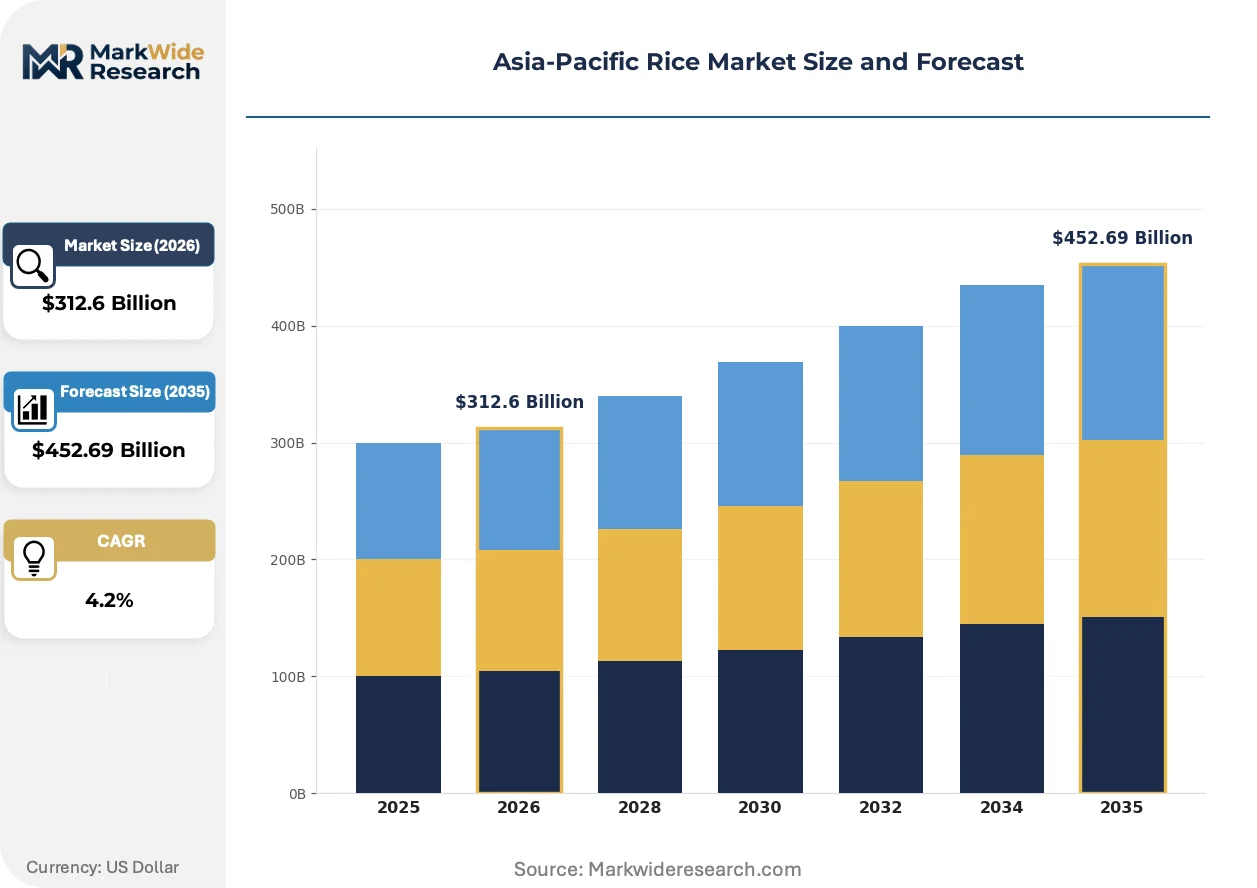
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $452.69 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice, Brown Rice, Aromatic Rice, Sticky Rice End User: Food Services, Retail Consumers, Industrial Use, Export Market Packaging Type: Bags, Boxes, Bulk, Vacuum Sealed Distribution Channel: Supermarkets, Online Retail, Wholesale, Local Markets |
| Companies Covered | Ricegrowers Limited, LT Foods Limited, China National Cereals, Oils and Foodstuffs Corporation, Vietnam Northern Food Corporation, Adani Wilmar, Charoen Pokphand Foods Public Company Limited, KRBL Limited, ITC Limited, Olam International Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Rice Market Strategic Shifts
Processing technology and certification infrastructure are actively compressing the gap between commodity and specialty rice, with automation and traceability systems redefining what constitutes export-ready product.
Optical sorting systems equipped with near-infrared spectrometry are decomposing the traditional reliance on manual grading for aromatic variety authentication. Large millers in Thailand's central plains and Vietnam's An Giang province are deploying these units at 40-60 tonne per hour throughput. The technology is decomposing price premiums previously captured by experienced sorters, compressing quality verification into a capital-intensive standardized step.
Thailand's Department of Rice has tightened hom mali GI enforcement through mandatory DNA testing and 14% moisture caps, rejecting shipments that fail either threshold. The regulation has redirected non-compliant volumes toward domestic feed markets and lower-tier export channels. Cambodian and Lao millers are responding by developing parallel fragrant varieties outside the protected designation.
Direct contracting between Mekong Delta processors and Middle Eastern importers is displacing the historical dominance of Singapore and Hong Kong trading houses. Large Saudi and UAE buyers now maintain quality inspectors at Long An and Dong Thap facilities, shortening chains and compressing working capital cycles. This pattern is most visible in the basmati-competing long-grain segment where volume commitments exceed 25,000 tonnes annually.
Asia-Pacific Rice Market Segmentation
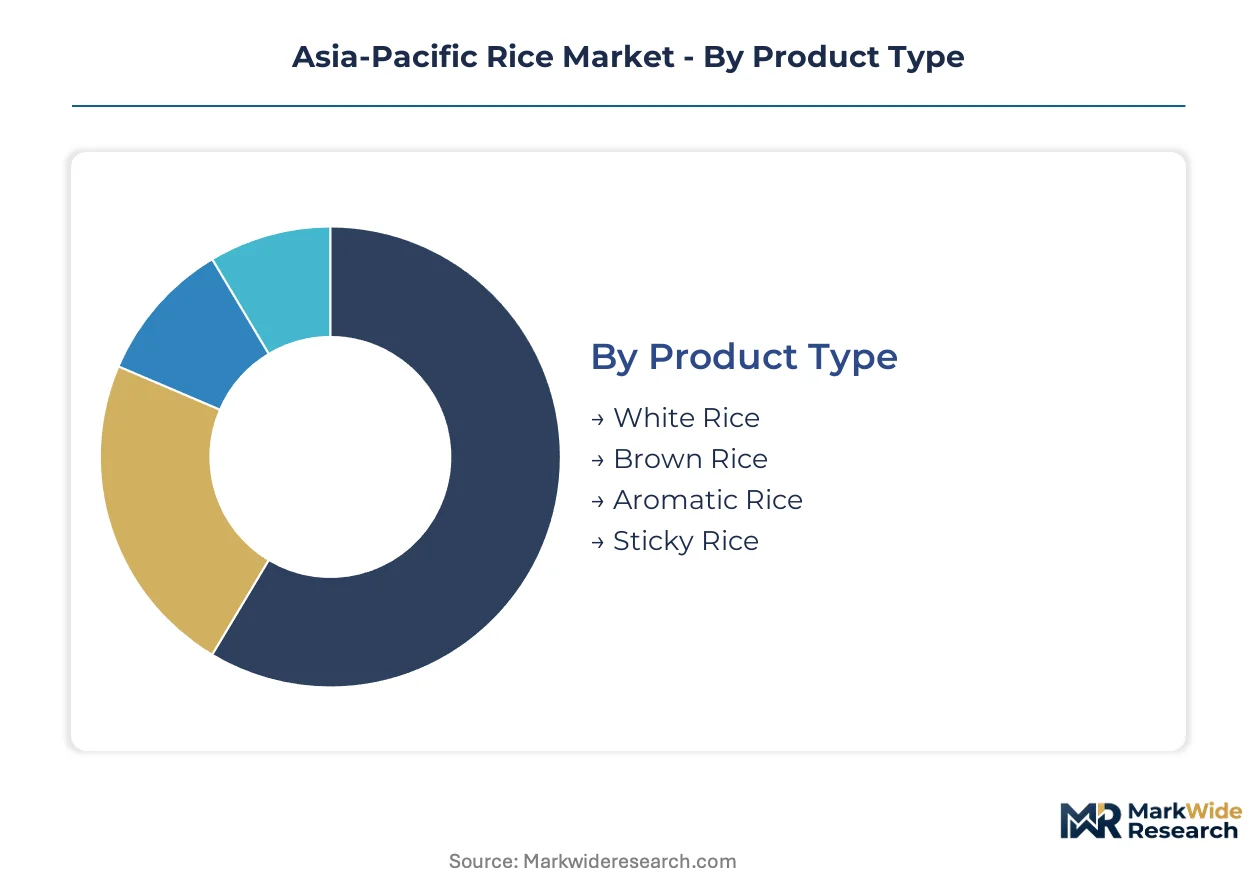
Segmentation in Asia-Pacific rice reveals how processing depth, end-use specifications, and channel economics partition value capture across the value chain. Each dimension carries distinct regulatory exposure and margin architecture that shapes miller investment priorities.
Product Type:
Substitution pressure from wheat and cassava starch hits commodity grades hardest while aromatic varieties defend position through terroir-linked certification barriers.
- White Rice:Milled to 5-20% moisture with bran and germ removed, delivering extended shelf stability for institutional procurement. Demand concentrates in Vietnam's Mekong Delta processing cluster where flood and salinity intrusions threaten supply security for Middle Eastern buyers.
- Aromatic Rice:Terroir-linked varieties including Thai hom mali and Indian basmati carry GI certifications that restrict market access for non-compliant origins. Procurement is accelerating through direct contracts between Mekong Delta processors and Saudi and UAE buyers who now station quality inspectors at Long An and Dong Thap facilities.
- Brown Rice:Retains bran layer with higher fiber content, appealing to health-conscious urban consumers in Japan and South Korea where METI import documentation requirements tighten traceability demands.
- Sticky Rice:High-amylopectin glutinous varieties dominate ceremonial and dessert applications across Laos and northeastern Thailand, with limited export penetration outside diaspora communities.
White rice anchors the volume base while aromatic rice gains share at the steepest rate.
End User:
Channel economics diverge sharply between price-tender institutional buyers and premium-seeking food service operators expanding across Southeast Asian secondary cities.
- Food Services:Hotel and restaurant chains drive aromatic and specialty grade procurement as international brands penetrate Jakarta, Ho Chi Minh City, and Manila suburbs. Volume commitments exceeding 25,000 tonnes annually compress working capital cycles through direct processor relationships.
- Export Market:Middle Eastern and African buyers deepen procurement ties with Kakinada port corridors and Mekong Delta origins, displacing historical Singapore and Hong Kong trading house dominance.
- Retail Consumers:Urban households in India and Bangladesh prioritize fortified variants under FSSAI iron and folic acid mandates, forcing capital expenditure toward blending and coating equipment.
- Industrial Use:Wheat and cassava starch displace rice in Bangladesh and Indonesian processed food applications where price spreads widen, eroding volume in brewing and starch extraction.
Export markets climb fastest while industrial use contracts under substitution pressure.
Packaging Type:
Packaging selection tracks customer scale and shelf-life requirements, with bulk formats dominating inter-regional trade and vacuum technologies penetrating premium urban retail.
- Bulk:Loose shipment formats dominate port-to-port trade between Mekong Delta processors and Middle Eastern importers, minimizing unit costs for volume buyers with captive bagging facilities.
- Vacuum Sealed:Oxygen-exclusion packaging extends shelf life for Japanese and South Korean import channels where tightening documentation requirements favor traceability-enhanced presentation formats.
- Bags:Woven polypropylene remains standard for domestic distribution across India and Indonesia, balancing cost and handling durability for local market intermediaries.
- Boxes:Retail-ready cartons serve premium gift segments in urban China and Thailand, carrying higher unit margins but limited volume scale.
Bulk shipments dominate trade value while vacuum sealed formats expand most quickly in premium channels.
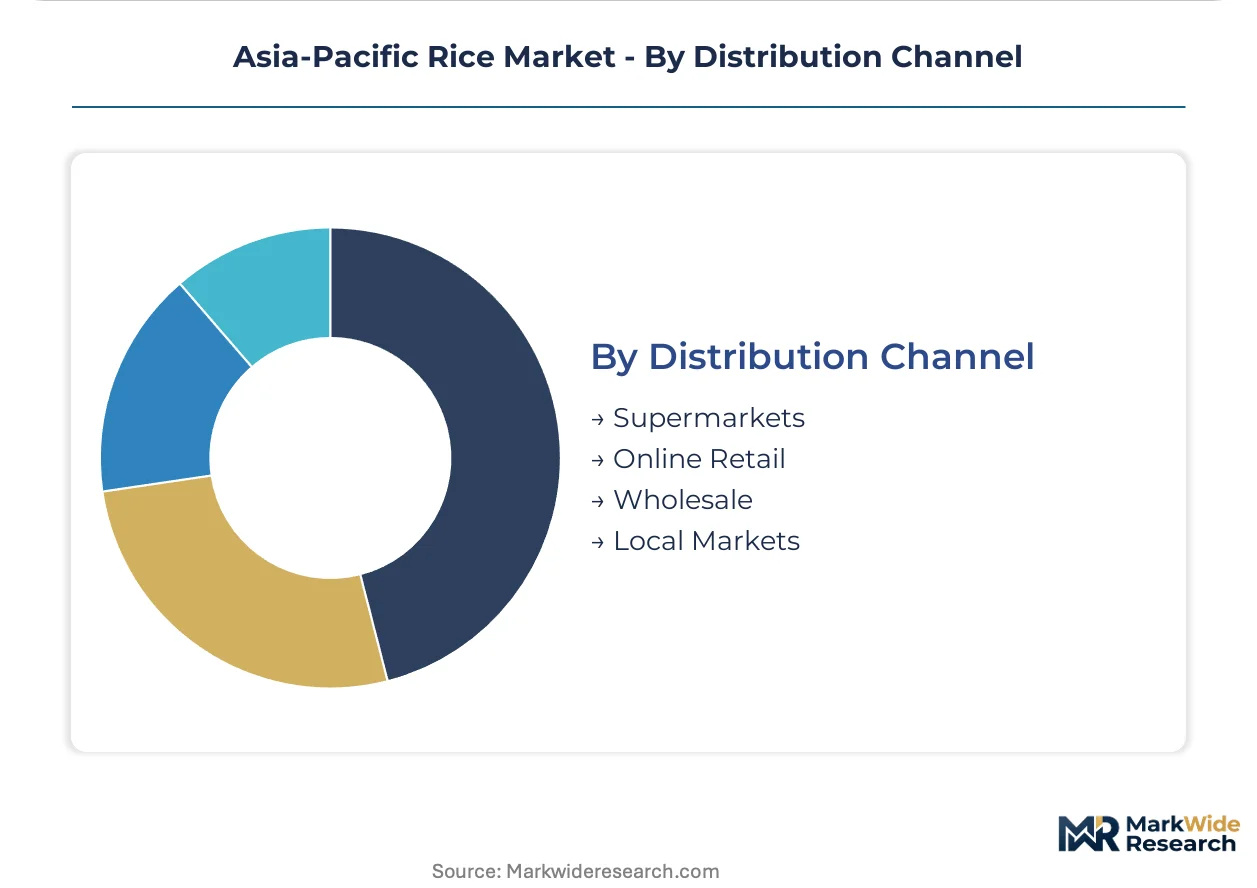
Distribution Channel:
Channel structure reflects infrastructure maturity and buyer sophistication, with wholesale networks retaining dominance in fragmented South Asian markets while online penetration accelerates in developed East Asian cities.
- Wholesale:Aggregator networks in eastern India's parboiling belt and Myanmar's Yangon corridor consolidate smallholder output for export-ready sorting and certification.
- Online Retail:E-commerce platforms penetrate Seoul, Tokyo, and Singapore metro areas with direct-to-consumer fortified and organic variants, bypassing traditional multi-layer distribution.
- Supermarkets:Modern trade formats in Bangkok, Kuala Lumpur, and Manila standardize hom mali DNA-authenticated and EU MRL-compliant product lines for middle-class households.
- Local Markets:Traditional wet markets retain volume dominance in rural Vietnam and Indonesia, though price transparency pressures mount from mobile-enabled price discovery.
Wholesale channels anchor volume flows while online retail posts the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hotel and restaurant chains across Southeast Asia concentrate procurement decisions in four national markets where aromatic grade demand is reshaping trade corridors. State reserve managers and export millers in each territory respond to distinct regulatory and infrastructure pressures.
Thailand
Hom mali GI protections drive capital allocation toward DNA-authenticated processing lines. The Department of Rice enforces moisture caps and origin verification that redirect non-compliant volumes to feed markets. Central plains millers deploy optical sorting systems at 40-60 tonne per hour throughput to defend premium positioning.
Vietnam
Mekong Delta processors contract directly with Saudi and UAE buyers who station inspectors at Long An and Dong Thap facilities. The Ministry of Agriculture and Rural Development operates pesticide monitoring protocols aligned with EU MRL thresholds. This certification infrastructure creates arbitrage windows for European-bound shipments.
India
FSSAI fortification mandates force millers in Bihar and Uttar Pradesh toward 18-24 month capex recovery timelines for blending equipment. Iron and folic acid requirements reshape eastern India's parboiling belt capital flows. KRBL Limited anchors the basmati export channel through integrated Punjab and Haryana operations.
China
China National Cereals, Oils and Foodstuffs Corporation controls state-level procurement through strategic reserve and milling infrastructure. Urban retail demand for fortified and organic variants penetrates developed eastern cities through e-commerce platforms. Yangtze River Delta processing clusters concentrate import documentation compliance for Japanese and South Korean buyers.
Myanmar
Sanctions easing and Yangon port modernization could unlock delta production for Middle Eastern buyers currently sourcing through Vietnamese intermediaries. Smallholder-dependent supply bases face fertilizer and diesel price volatility that compresses margins. Wholesale aggregator networks consolidate output for export-ready sorting and certification.
Asia-Pacific Rice Market Competitive Environment
Player mix skews toward state-affiliated grain traders and integrated millers with captive origination networks. Market structure concentrates around three tiers: reserve managers with strategic stockpile control, aromatic specialists with GI-linked certification infrastructure, and diversified agribusinesses with multi-origin sourcing capabilities. Competitive moves center on direct processor-to-importer contracting and optical sorting technology deployment that compresses quality verification into capital-intensive standardized steps.
Among integrated basmati specialists, KRBL Limited and LT Foods Limited occupy positions defined by Punjab and Haryana origination control. State-backed traders include China National Cereals, Oils and Foodstuffs Corporation and Vietnam Northern Food Corporation, each representing reserve management archetypes with strategic infrastructure dominance. Diversified agribusinesses such as Olam International Limited exemplify multi-ASEAN sourcing strategies designed to navigate climate risk across fragmented supply bases.
| Leading Market Players |
|---|
| Ricegrowers Limited |
| LT Foods Limited |
| China National Cereals, Oils and Foodstuffs Corporation |
| Vietnam Northern Food Corporation |
| Adani Wilmar |
| Charoen Pokphand Foods Public Company Limited |
| KRBL Limited |
| ITC Limited |
| Olam International Limited |
| Others |
Value Chain & Pricing Dynamics
Mill scale economies in Vietnam's Mekong Delta and Thailand's central plains compress unit processing costs below smaller competitors, anchoring price floors for export-ready white rice and concentrating procurement power among 40-60 tonne per hour optical sorting operators. This capacity clustering reinforces tiered margin structures where GI-certified aromatic varieties command substantial premiums over commodity grades, while smallholder-dependent origins in Myanmar and Cambodia face persistent cost disadvantages.
Pricing Analysis
Cost-plus contracts with Thai hom mali and Indian basmati exporters index base prices to FAO rice price indicators plus fixed processing margins, creating transparent pass-through mechanisms for input cost swings. Price differentiation rests on GI certification status and volume scale, with DNA-authenticated hom mali capturing substantial premiums over non-compliant fragrant varieties. Pricing pressure intensifies in commodity white rice as Mekong Delta flood risks and fertilizer cost volatility compress margins for undifferentiated grades. Institutional buyers in Middle Eastern import markets exhibit highest price sensitivity, while European food service operators prioritize EU MRL compliance over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Middle East trade lanes and Yangon port congestion elevate inbound logistics costs for Myanmar delta production seeking direct export access. Geographic supply concentrates in Vietnam, Thailand, and India, with Cambodia and Myanmar serving residual volume roles. Raw material dependencies center on urea and phosphate fertilizers, diesel for mechanized harvesting, and certified seed stock for GI variety purity. Single-region flood and salinity exposure in the Mekong Delta presents structural supply risk. Distribution runs through direct processor-to-importer contracts displacing Singapore and Hong Kong trading house intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific rice market sits in cyclical recovery as El Niño-induced supply disruptions and India's periodic export restrictions tighten tradable surpluses, supporting price firming across aromatic and specialty grades.
For Market Incumbents: Shield premium positioning by accelerating optical sorting deployment and securing captive origination through contract farming arrangements in Punjab and Haryana basmati belts. Counter substitution pressure from wheat and cassava starch in Bangladeshi and Indonesian industrial applications by reinforcing traceability investments that satisfy tightening Japanese and South Korean import documentation requirements.
For New Entrants and Emerging Players: Differentiate on blockchain-enabled origin verification targeting premium European retail channels where EU MRL compliance creates certification arbitrage windows. Myanmar's underpenetrated delta production offers the most penetrable geography as sanctions easing and port modernization progress. Pursue direct contracting with Saudi and UAE buyers who now station quality inspectors at Mekong Delta facilities.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated millers with captive origination and multi-year offtake agreements with Middle Eastern state buyers. Long-term viability across the projection horizon favors operators with GI certification infrastructure and climate-resilient sourcing footprints. Monitor FSSAI fortification mandate enforcement as an inflection indicator for capital expenditure cycles in eastern India's parboiling belt.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Technology Deployment | DNA-authenticated processing lines defend Thai hom mali GI premiums against manual grading competitors. |
| Direct Processor-Importer Contracting | Saudi and UAE buyer inspector placement at Long An facilities compresses working capital cycles. |
| Fortification Equipment Retrofit | FSSAI-compliant blending infrastructure captures institutional procurement mandates in Bihar and Uttar Pradesh. |
| Blockchain Traceability Integration | IoT sensor and distributed ledger systems satisfy METI documentation requirements for Japanese import channels. |
| Myanmar Port Access Development | Yangon modernization unlocks delta production for Middle Eastern buyers currently sourcing through Vietnamese intermediaries. |
Study Parameters
Initial hypotheses were tested against primary input from mill operations managers, export trading house procurement leads, food service chain category buyers, and agricultural ministry policy officers and refined through secondary validation against customs trade databases, FAO rice market reports, FSSAI regulatory filings, and EU MRL compliance records. Bottom-up volume estimates from processor capacity utilization and top-down demand calibration from import statistics were triangulated to converge on market sizing.
Variance decomposition across the projection horizon isolates volume drivers by product type, end user channel, and national regulatory cluster. Analytical frameworks modeled white rice, aromatic, brown, and sticky rice segments separately with end-use splits across food service, export, retail, and industrial applications. CAGRs were derived from trend extrapolation adjusted for policy intervention effects, with specific inputs including FSSAI fortification rollout timelines and Thai Department of Rice GI enforcement intensity.
Material uncertainties — El Niño recurrence patterns, Indian export restriction reinstatement, and EU MRL threshold revisions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory continuity and climate volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Sorghum Market
Grains
South America Wheat Market
Grains
Organic Rice Flour Market
Grains
Wheat Flour Market
Grains
Global Flour Market
Grains
China Wheat Protein Market
Grains
Ancient Grain Market
Grains
Rolled Oats Market
Grains
Asia-Pacific Guar Market
Grains
GMO Corn Market
Grains
Organic Rice Market
Grains
Tunisia Grain Market
Grains
United States Rice Market
Grains
00 Flour Market
Grains
Organic Oats Market
Grains
IQF Rice Market