
 Precooked Flour Market | 2026-2036
Precooked Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Precooked Flour Market Analytics
The price-performance gap between premium and commodity precooked flour is hardening as ingredient sourcing transparency and fortification standards diverge. Archer Daniels Midland Company leverages its North American grain origination network to sustain supply security for large-scale bakery clients. Cargill, Incorporated anchors its position through backward integration into specialty corn breeding programs. Goya Foods, Inc. differentiates via brand recognition and channel control across Hispanic retail corridors in the United States.
Precooked flour consists of grains or starches subjected to thermal treatment—typically extrusion, roasting, or steaming—followed by drying and milling to achieve instant rehydration properties with gelatinization levels exceeding 80%. This processing transforms native flours into cold-water soluble ingredients for arepas, instant porridges, and thickened sauces. White flour and corn flour dominate current volume, though cassava flour represents the fastest-growing category as gluten-free formulation expands across European and North American food processing lines. The food processing industry commands the largest end-user share, while online retail distribution is gaining traction as direct-to-restaurant procurement platforms proliferate.
The FDA governs food additive and labeling standards for precooked flour sold in the United States, while EFSA and the EU Green Deal shape fortification mandates and sustainability disclosures across European supply chains. Colombia's INVIMA and Venezuela's national health authority enforce local product standards that constrain import substitution for traditional arepa flours. Stakeholders must monitor evolving mycotoxin thresholds and carbon accounting requirements that will reshape supplier qualification criteria and regional sourcing decisions.
Market Dynamics
The F-Gas Regulation in Europe is compressing thermal processing margins and forcing dry-mix technology adoption across industrial bakeries, fundamentally restructuring how precooked flour achieves gelatinization without steam-intensive extrusion.
Growth Catalysts
- EU Green Deal carbon accounting:Food processors in Germany and the Netherlands are retrofitting facilities to meet Scope 3 disclosure requirements, accelerating demand for low-thermal-footprint precooked flour production methods.
- Arepa flour consumption:Colombian and Venezuelan diaspora communities in the United States are sustaining double-digit volume growth for white corn precooked flour through Hispanic retail corridor expansion.
- Extrusion technology advancement:Continuous twin-screw systems are reducing energy input per kilogram by enabling higher throughput at lower moisture levels, improving unit economics for mid-scale producers.
Market Restraints
- Maize price volatility:White corn futures on the Chicago Board of Trade expose millers to input cost swings that compress blending margins and destabilize contract pricing with food service distributors.
- Andean supply concentration:Over 60% of specialty cassava flour origination depends on Colombian llanos processing cooperatives, creating geographic vulnerability to weather and logistics disruptions.
- Fortification mandate fragmentation:Divergent iron and folic acid requirements between Colombia's INVIMA and Venezuela's national health authority prevent standardized cross-border formulations.
Strategic Opportunities
- Direct-to-restaurant platforms:Online procurement marketplaces are disintermediating traditional food service distributors, enabling precooked flour mills to capture margin through subscription-based replenishment models.
- Gluten-free bakery expansion:Cassava flour penetration into European artisan bread formulations represents underexploited white space as celiac certification programs expand in France and Italy.
- PLI scheme alignment:India's production-linked incentive framework for food processing infrastructure offers capital cost offsets for extrusion capacity installation targeting export markets.
Industry Challenges
- Extrusion operator scarcity:Skilled technicians capable of calibrating twin-screw parameters for consistent gelatinization levels above 80% command premium wages that erode facility-level returns.
- Retrofit capex burden:Converting steam-based gelatinization lines to dry-mix thermal systems requires seven-figure capital commitments that strain mid-tier mill balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precooked Flour Market |
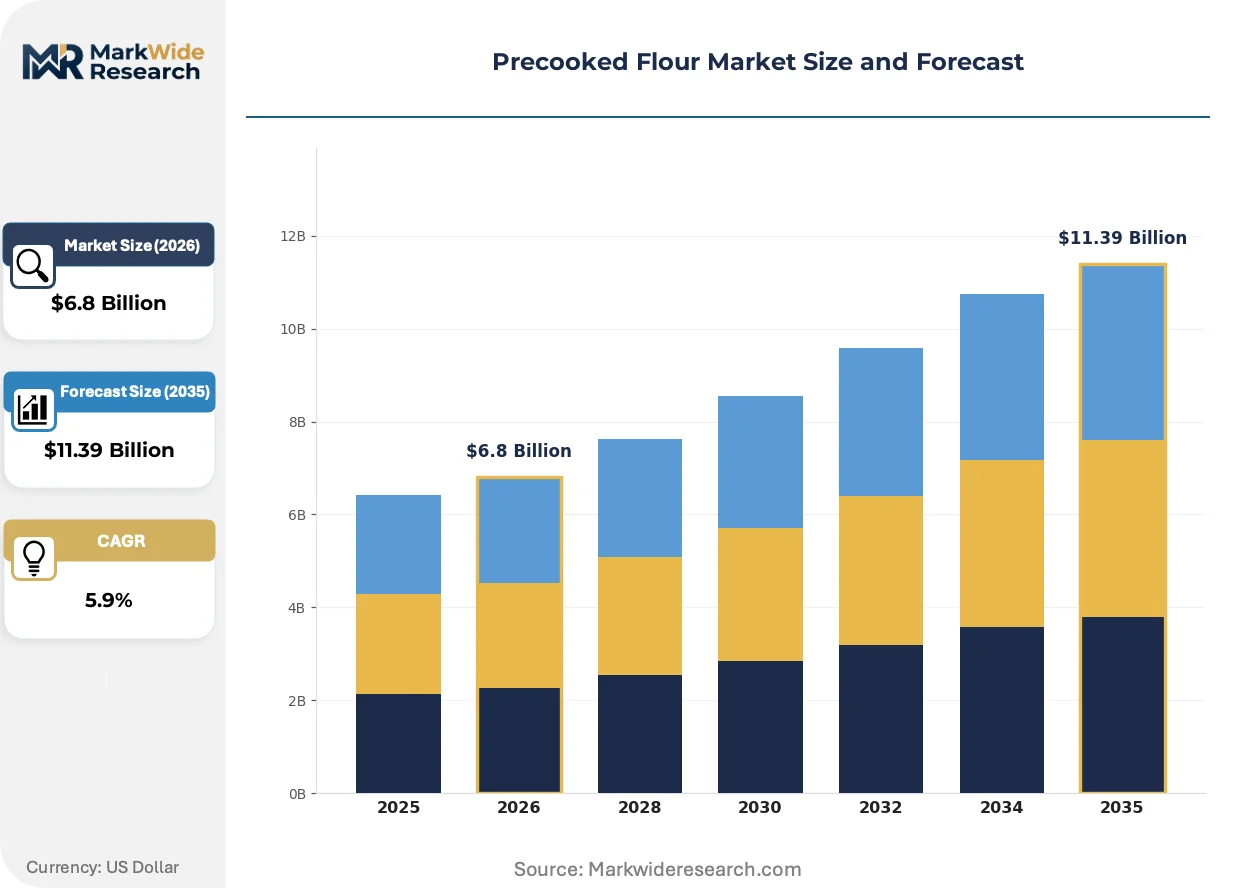
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Flour, Whole Wheat Flour, Corn Flour, Cassava Flour End User: Food Processing Industry, Bakeries, Restaurants, Household Use Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Specialty Stores Packaging Type: Bags, Boxes, Bulk Containers, Sachets |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Bunge Limited, Goya Foods, Inc., Empresas Polar, Limagrain, ITC Limited, Harinera del Valle, Molino Peila SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precooked Flour Market Evolving Landscape
Automation of thermal treatment workflows is compressing labor dependence and enabling real-time quality control, while regulatory pressure on carbon intensity and shifting procurement behaviors are reconfiguring how precooked flour reaches end-users.
Near-infrared spectroscopy integrated into extrusion lines is automating moisture and gelatinization monitoring, eliminating batch-to-batch variation that previously required manual laboratory verification. Large-scale bakery clients in the United States are mandating this sensor deployment as a supplier qualification condition. The technology is automating quality assurance staffing reductions of 30-40% at integrated milling facilities.
REACH chemical safety registrations and the EU F-Gas Regulation are constraining hydrofluorocarbon-based cooling systems used in flour drying stages, compelling processors to adopt ammonia or CO2 refrigeration alternatives. Industrial bakeries in Germany and Poland face 18-month compliance timelines that accelerate capital replacement cycles. Cassava flour processors with existing low-temperature drying infrastructure capture competitive advantage under these rules.
Restaurant procurement teams are consolidating supplier relationships through vertical integration with mill-direct platforms, bypassing legacy food service distribution markups. This channel compression is most pronounced in Florida and Texas, where Hispanic restaurant density supports dedicated arepa flour logistics networks. Third-party distributors respond by unbundling warehousing from transportation services to retain partial wallet share.
Precooked Flour Market Segmentation
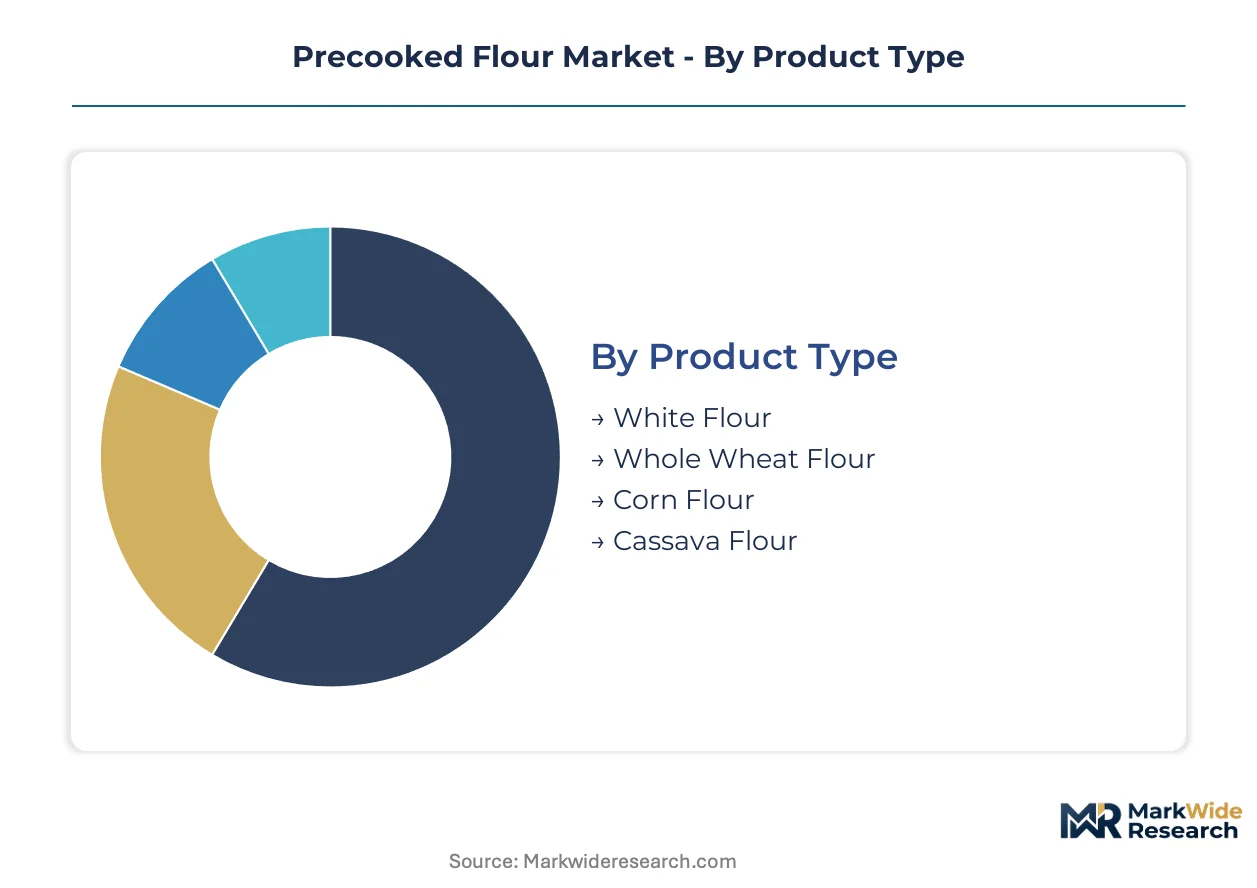
Precooked flour procurement patterns diverge sharply between industrial-scale food processors optimizing for gelatinization consistency and household buyers prioritizing convenience and heritage authenticity. Understanding these segment boundaries clarifies where formulation investments concentrate versus where packaging and channel efficiency drive margin capture.
Product Type:
Volume concentrates in commodity starches while premium tiers command pricing power through specialty breeding programs and gluten-free positioning.
- White Flour:Milled from endosperm-only wheat with protein content standardized between 9-11%, white precooked flour delivers neutral flavor profiles for industrial sauce thickening and instant porridge bases. Demand clusters in Colombian arepa manufacturing where INVIMA fortification mandates require iron and folic acid integration at milling stage.
- Corn Flour:Derived from nixtamalized or extruded maize with gelatinization levels exceeding 85%, this segment supplies the arepa flour supply chains anchoring Venezuelan and Colombian diaspora consumption in Florida and Texas. White corn futures volatility on the Chicago Board of Trade directly compresses blending margins for regional millers.
- Whole Wheat Flour:Retains bran and germ fractions for fiber content above 12%, serving health-positioned bakery formulations in European markets where EFSA nutrition claims require substantiation.
- Cassava Flour:Extracted from Manihot esculenta roots processed through low-temperature drying, this gluten-free alternative penetrates European artisan bread segments in France and Italy as celiac certification programs expand.
Today's leader: Corn Flour. Tomorrow's challenger: Cassava Flour.
End User:
Industrial buyers specify extrusion parameters while food service and household segments respond to brand recognition and cultural familiarity.
- Food Processing Industry:Large-scale manufacturers of ready-to-eat meals and instant soups require batch-to-batch gelatinization consistency above 80%, mandating near-infrared spectroscopy integration as a supplier qualification condition. German and Dutch processors retrofit facilities to meet EU Green Deal Scope 3 disclosure requirements.
- Restaurants:Hispanic restaurant corridors in Florida and Texas consolidate procurement through mill-direct platforms, bypassing traditional distributor markups for arepa flour replenishment. Subscription-based models capture margin through predictable volume commitments.
- Bakeries:Artisan and industrial bakeries in Italy and France formulate cassava flour into gluten-free product lines as EFSA labeling standards harden.
- Household Use:Diaspora communities in the United States sustain double-digit volume growth for heritage corn flours through Hispanic retail channel expansion.
Food Processing Industry commands current volume. Restaurants are climbing the fastest through channel disintermediation.
Distribution Channel:
Traditional wholesale networks face compression as digital procurement platforms and retail consolidation reshape access economics.
- Wholesale Distributors:Legacy food service networks retain position in institutional catering and remote geography fulfillment where logistics density supports multi-product consolidation.
- Online Retail:Direct-to-restaurant marketplaces and consumer platforms disintermediate traditional tiers, enabling mill-direct relationships with predictable replenishment scheduling.
- Supermarkets:Mass retail chains in the United States anchor Hispanic grocery corridor presence for heritage corn flour brands.
- Specialty Stores:Ethnic grocery formats in Texas and Florida concentrate arepa flour merchandising with cultural authenticity positioning.
Wholesale Distributors defend incumbent position. Online Retail gains share fastest through procurement workflow integration.
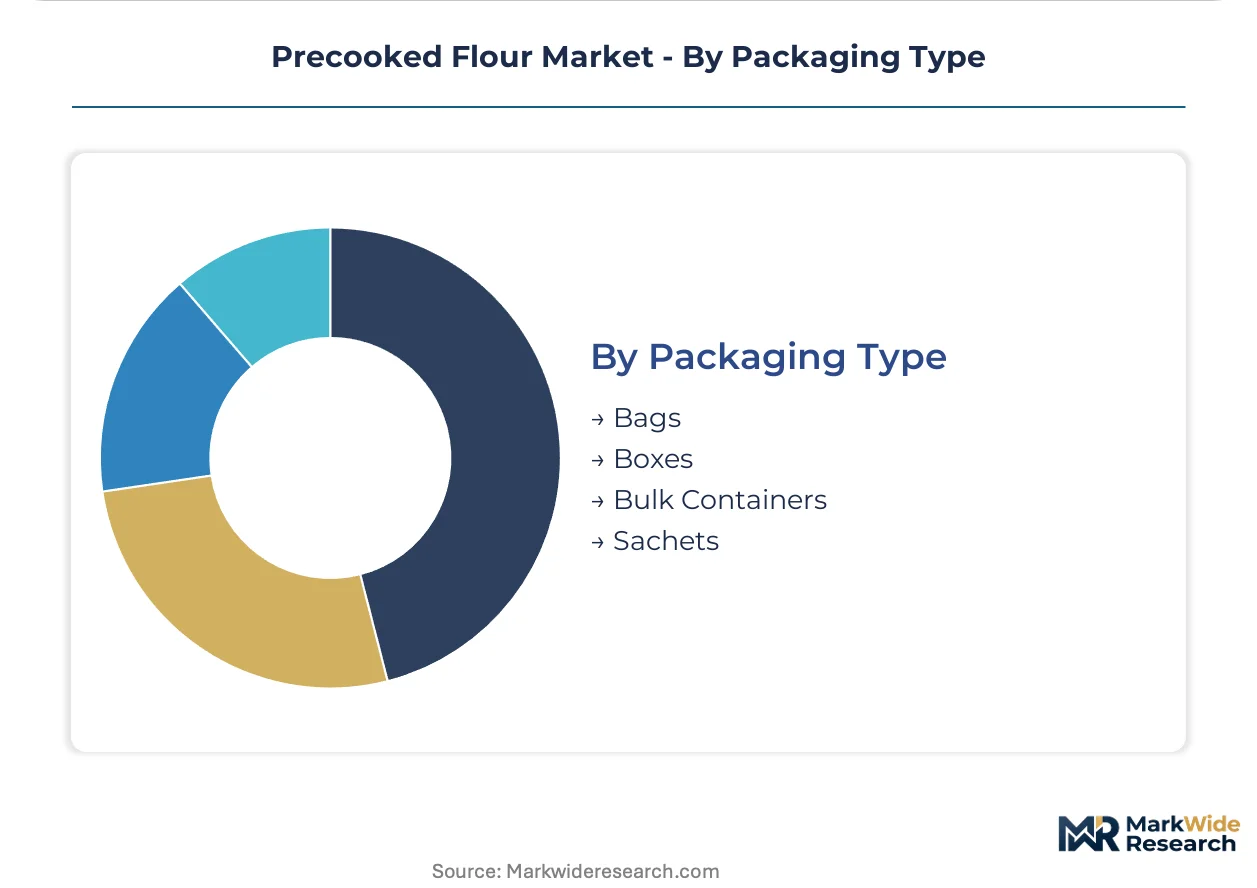
Packaging Type:
Format selection tracks use-case scale from bulk industrial throughput to single-serve household convenience.
- Bulk Containers:Tote and silo formats serve food processing lines with automated handling systems, minimizing per-kilogram packaging cost at volume thresholds above 500kg.
- Bags:1-25kg woven polypropylene dominates restaurant and small bakery procurement, balancing handling efficiency with inventory turnover flexibility.
- Boxes:Corrugated formats protect premium cassava flour products through European retail distribution where shelf presentation influences purchase decision.
- Sachets:Single-serve portions target instant porridge and sauce applications in household convenience segments.
Bags hold current volume leadership. Bulk Containers expand most quickly through processor vertical integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombia and Venezuela anchor arepa flour consumption patterns, while Germany and the United States reshape processing standards through divergent regulatory pressures on thermal footprint and supply chain transparency.
Colombia
Arepa flour demand concentrates in Bogotá and Medellín manufacturing corridors where INVIMA fortification mandates require iron and folic acid integration at the milling stage. The national health regulator enforces mycotoxin thresholds that constrain import substitution for traditional white corn formulations. Processing cooperatives across the Colombian llanos supply over 60% of specialty cassava flour origination, creating geographic vulnerability to weather disruptions.
Venezuela
Diaspora communities in Florida and Texas sustain cross-border demand for heritage precooked corn flour through informal supply networks and licensed distributors. The national health authority maintains divergent fortification requirements from neighboring Colombia, preventing standardized cross-border formulations. Industrial clusters in Valencia and Maracaibo historically anchored production capacity, though operational continuity depends on raw material access economics.
United States
Hispanic retail corridor expansion across Florida and Texas drives double-digit volume growth for white corn precooked flour among Colombian and Venezuelan diaspora communities. The FDA governs food additive and labeling standards that large-scale bakery clients mandate as supplier qualification conditions. Near-infrared spectroscopy deployment is automating quality assurance staffing reductions at integrated milling facilities serving restaurant procurement teams.
Germany
Industrial bakeries retrofit facilities to meet EU Green Deal Scope 3 disclosure requirements, accelerating demand for low-thermal-footprint precooked flour production methods. The F-Gas Regulation compresses thermal processing margins and forces dry-mix technology adoption across extrusion-dependent operations. Processing clusters in North Rhine-Westphalia face 18-month compliance timelines for ammonia or CO2 refrigeration alternatives.
India
The production-linked incentive framework for food processing infrastructure offers capital cost offsets for extrusion capacity installation targeting export markets. BIS standards govern domestic quality parameters while export-oriented processors align with EFSA and FDA requirements for European and North American destinations. Gujarat and Maharashtra host emerging milling capacity serving gluten-free formulation demand in developed economies.
Precooked Flour Market Competitive Landscape
Top-tier vendors anchor supply security through grain origination networks and backward integration, while mid-scale specialists compete on thermal efficiency and channel disintermediation. The market exhibits tiered concentration around commodity volume players, heritage brand owners, and regional processing cooperatives. Three archetypes dominate: North American grain traders with captive origination, Hispanic heritage brands with retail corridor control, and European breeding specialists with specialty corn programs. Competitive moves center on twin-screw extrusion technology licensing and direct-to-restaurant platform development.
Within the heritage brand tier, Goya Foods, Inc. exemplifies channel control through Hispanic retail corridor presence, while Empresas Polar occupies a position tied to arepa flour authenticity among Venezuelan diaspora communities. Archer Daniels Midland Company represents the grain-origination archetype through its North American network infrastructure. These three entities illustrate how competitive positioning diverges between commodity scale, cultural brand equity, and supply security vectors.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Bunge Limited |
| Goya Foods, Inc. |
| Empresas Polar |
| Limagrain |
| ITC Limited |
| Harinera del Valle |
| Molino Peila SpA |
| Others |
Value Network & Pricing Analysis
Backward integration into specialty corn breeding programs anchors supply security for large-scale bakery clients while simultaneously insulating pricing power against white corn futures volatility on the Chicago Board of Trade. This structural choice concentrates margin capture upstream for grain-origination leaders, forcing mid-tier millers to compete on thermal efficiency rather than input cost control.
Pricing Analysis
Capacity additions in India are reshaping price floors for export-oriented extrusion capacity as the PLI scheme offsets capital costs for new entrants. Three-tier pricing structure across premium, standard, and economy levels separates heritage arepa flour brands from commodity white corn formulations and gluten-free cassava alternatives. Price differentiation tracks fortification grade and gelatinization consistency certification, with large-scale food processors least sensitive due to contract-based long-term offtake agreements. Cost compression in standard-tier corn flour is intensifying because maize price volatility exposes blending margins.
Supply Chain Analysis
Near-infrared spectroscopy deployment is emerging as a supplier qualification gate that large-scale bakery clients mandate before contract execution. Geographic supply concentration centers on Colombia, Venezuela, and the United States for arepa flour origination, while India and Germany anchor extrusion technology and low-thermal-footprint processing respectively. Raw material dependencies rest on white corn futures, cassava root harvests from Colombian llanos cooperatives, and ammonia refrigeration systems for F-Gas Regulation compliance. Single-source vulnerability concentrates in Andean cassava flour origination where over sixty percent flows through weather-exposed processing cooperatives. Distribution runs through mill-direct platforms disintermediating legacy food service networks in Florida and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precooked flour market reads as a late-cycle quality story where food processors now mandate near-infrared spectroscopy integration and gelatinization consistency above eighty percent as baseline supplier qualifications. This specification creep favors integrated millers with captive breeding programs over commodity traders.
For Market Incumbents: Hedge against maize price volatility through forward contracting with Colombian llanos cooperatives for cassava flour diversification, while retrofitting steam-based gelatinization lines to dry-mix thermal systems ahead of EU F-Gas Regulation enforcement timelines. Channel control through Hispanic retail corridors remains defensible against direct-to-restaurant platform disintermediation only with real-time inventory replenishment capabilities. For New Entrants and Emerging Players: Direct-to-restaurant procurement platforms represent the most penetrable white space for subscription-based arepa flour replenishment models in Florida and Texas Hispanic restaurant corridors. Target gluten-free bakery formulation demand in France and Italy where EFSA labeling standards harden and celiac certification programs expand. Lead with thermal efficiency credentials and mill-direct pricing transparency rather than brand heritage. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale extrusion specialists with existing near-infrared spectroscopy deployment because large-scale bakery clients are consolidating supplier relationships around automated quality assurance capabilities. Five-to-ten year viability hinges on carbon accounting compliance infrastructure for EU Green Deal Scope 3 disclosure requirements. Monitor F-Gas Regulation compliance timelines in Germany and Poland as inflection indicators for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Corn Breeding | Cargill's captive programs insulate input costs from Chicago Board of Trade volatility. |
| Dry-Mix Thermal System Retrofit | German processors face eighteen-month F-Gas Regulation compliance deadlines accelerating capital replacement. |
| Direct-to-Restaurant Platform Launch | Mill-direct relationships bypass distributor markups in Florida and Texas Hispanic corridors. |
| Near-Infrared Spectroscopy Deployment | Large-scale bakery clients mandate sensor integration as supplier qualification condition. |
| Gluten-Free Cassava Flour Expansion | European artisan bread segments in France and Italy drive celiac-certified formulation demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extrusion technology specialists, procurement leads at ready-to-eat meal manufacturers, regulatory affairs directors navigating EFSA and FDA fortification mandates, and channel managers at Hispanic retail distributors. Secondary validation drew from customs and trade data, SEC filings of grain-origination networks, EU Green Deal policy documentation, and BIS standards for Indian food processing infrastructure. Bottom-up volume modeling across product type, end user, and distribution channel segments triangulated against top-down macroeconomic anchors.
Historical reference periods anchored the projection horizon through verified shipment data and installed extrusion capacity assessments across Colombia, Venezuela, the United States, Germany, and India. Segmentation dimensions modeled include product type tier, end-use industry concentration, packaging format scale, and regional regulatory cluster alignment. CAGRs derived from slope-consistency checks against comparable processed food ingredient categories, with forecast inputs weighted toward EU F-Gas Regulation compliance timelines and PLI scheme disbursement schedules for Indian capacity additions.
The model assumes a particular technology adoption path for continuous twin-screw extrusion systems; alternative pathways for batch steam gelatinization would alter the outlook if energy cost differentials shift materially. Forecasts reflect documented assumptions on mycotoxin threshold enforcement and carbon accounting disclosure stringency. A model refresh is warranted upon material change in white corn futures volatility or F-Gas Regulation amendment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Whole-Wheat Flour Market
Grains
Grain Dryers Market
Grains
GCC Basmati Rice Market
Grains
United States Gluten-Free Oats Market
Grains
Africa Wheat Protein Market
Grains
Global Grain Analysis Market
Grains
Corn Flour Market
Grains
Europe Wheat Protein Market
Grains
Cameroon Grains Market
Grains
North America Wheat Protein Market
Grains
Lentil Market
Grains
United States Rice Market
Grains
Colombia Grains Market
Grains
Millet Flour Market
Grains
Rolled Oats Market
Grains
Soya Flour Market