
 Arteriovenous Fistula Devices Market | 2026-2036
Arteriovenous Fistula Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Arteriovenous Fistula Devices Market Analytics
A shortage of interventional nephrologists trained in vascular access creation is redrawing competitive dynamics across the arteriovenous fistula devices landscape. Medtronic leverages its integrated portfolio spanning imaging guidance through closure systems to sustain procedure throughput for health systems. B. Braun SE anchors European supply chains through specialized manufacturing of dialysis access needles and catheters. Fresenius Medical Care AG & Co. KGaA dominates the downstream channel by operating captive dialysis centers that internalize device procurement decisions.
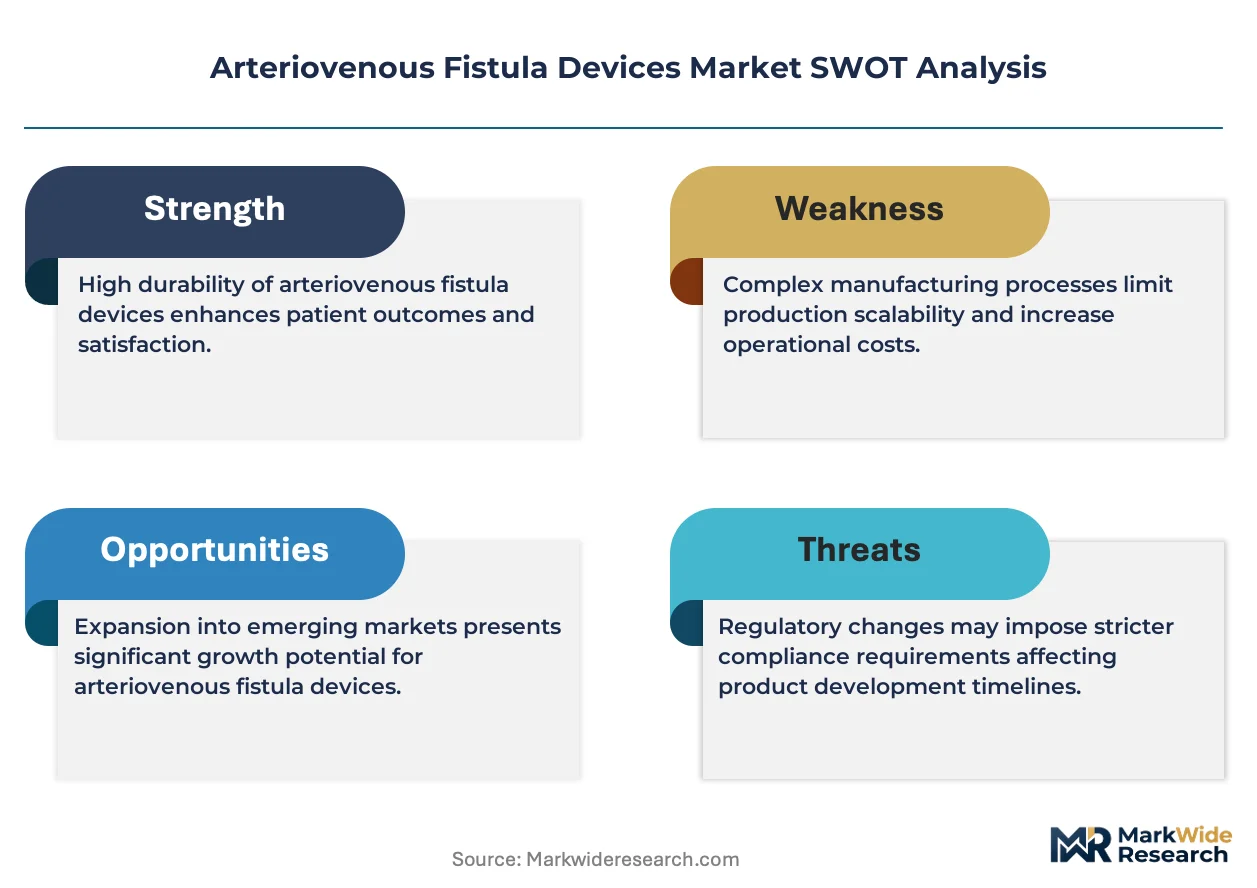
Arteriovenous fistula devices encompass needles, catheters, planners, and connectors engineered to create and maintain vascular access circuits connecting arteries to veins for hemodialysis blood withdrawal and return. Silicone and polycarbonate formulations predominate in catheter construction due to biocompatibility requirements and kink resistance under cyclic flow conditions. Needles and catheters occupy the largest product type positions, though antimicrobial-coated technologies are gaining fastest traction as infection control protocols tighten in dialysis centers and hospitals. Biodegradable material innovations remain nascent but attract R&D allocation from manufacturers seeking differentiation against commoditized stainless steel alternatives.
The US FDA governs 510(k) clearance pathways for these devices, while the EU MDR imposes strengthened clinical evidence requirements for vascular access products seeking CE marking. Health Canada's PMRA and Japan's PMDA maintain parallel review frameworks that manufacturers must navigate for multi-regional commercialization. Stakeholders should monitor how reimbursement policy shifts at CMS and analogous national payers reshape site-of-care migration between hospitals and independent dialysis centers.
Market Dynamics
The arteriovenous fistula devices market is being fundamentally restructured by CMS reimbursement policies that now penalize catheter-dependent dialysis and reward fistula maturation rates, forcing providers to upgrade vascular access infrastructure.
Growth Catalysts
- ESRD Prospective Payment System:Medicare's bundled reimbursement model incentivizes dialysis centers to invest in fistula creation devices rather than temporary catheters, accelerating permanent access adoption.
- Antimicrobial coating chemistry:Silver-ion and chlorhexidine surface treatments are reducing bloodstream infection rates, satisfying Joint Commission accreditation standards for dialysis facilities.
- Interventional nephrology training expansion:American Society of Diagnostic and Interventional Nephrology credentialing programs are enlarging the specialist pool capable of performing ultrasound-guided fistula procedures.
Market Restraints
- Silicone raw material concentration:Medical-grade silicone supply chains cluster in Northeast Asian chemical processors, exposing device manufacturers to freight cost volatility and geopolitical disruption.
- MDR clinical evidence burden:The EU Medical Device Regulation now demands prospective clinical data for vascular access catheters seeking CE marking, extending approval timelines and R&D burn rates.
- Peritoneal dialysis substitution:Home-based peritoneal modalities are capturing incident ESRD patients who might otherwise require hemodialysis vascular access, compressing addressable procedure volume.
Strategic Opportunities
- India dialysis infrastructure buildout:The Pradhan Mantri National Dialysis Program is expanding government-funded hemodialysis centers into tier-2 and tier-3 cities, creating first-time device procurement demand.
- Bioresorbable fistula maturation scaffolds:Polycaprolactone-based temporary stents that dissolve post-maturation represent unclaimed white space between permanent synthetic grafts and native fistulas.
- Remote patient monitoring integration:Implantable flow sensors paired with cloud-based surveillance platforms enable predictive thrombosis alerts, opening recurring revenue streams beyond device sale.
Industry Challenges
- Ultrasound-guided cannulation proficiency:Dialysis technician training programs struggle to produce sufficient operators skilled in Doppler-assisted needle placement, constraining procedure throughput at high-volume centers.
- 510(k) predicate device erosion:FDA's narrowing acceptance of substantial equivalence arguments for vascular access devices is forcing more manufacturers toward de novo pathways with extended review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arteriovenous Fistula Devices Market |
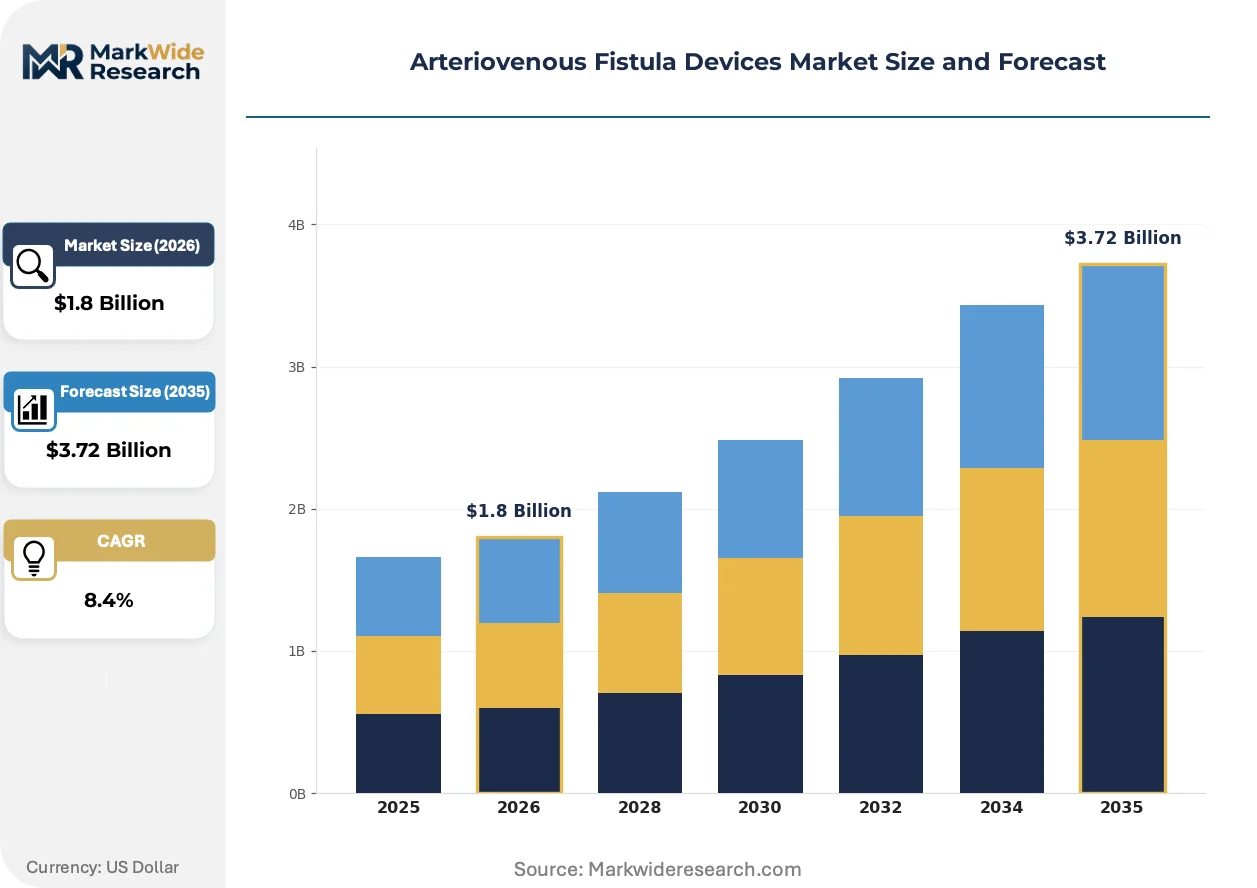
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needles, Catheters, Planners, Connectors End User: Dialysis Centers, Hospitals, Home Care, Clinics Material: Silicone, Polycarbonate, Polyethylene, Stainless Steel Technology: Biodegradable, Antimicrobial, Coated, Non-coated |
| Companies Covered | Medtronic, BD, Teleflex Incorporated, Fresenius Medical Care AG & Co. KGaA, B. Braun SE, Polymedicure, NxStage Medical, Cook Medical, W. L. Gore & Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arteriovenous Fistula Devices Market Evolving Landscape
Device manufacturers are racing to integrate bioelectronics and advanced materials into vascular access systems, transforming fistula creation from a mechanical procedure into a monitored, data-generating therapeutic intervention.
Antimicrobial-impregnated polyurethane catheters are displacing standard silicone formulations in hospital-based dialysis units. Fresenius Medical Care and DaVita procurement committees have mandated infection-resistant materials for all new catheter placements. This displacement is compressing commodity catheter margins while concentrating premium pricing power with coating technology licensors.
The EU MDR's strengthened post-market surveillance requirements are forcing vascular access manufacturers to maintain European Authorized Representatives with clinical expertise. Device vigilance reporting obligations now extend to thrombosis and stenosis events previously considered routine complications. German notified bodies are demanding real-world evidence registries for fistula planners and connectors, reshaping product lifecycle management budgets.
Consolidated purchasing through group purchasing organizations is concentrating procurement decisions at fewer decision nodes. Premier and Vizient contracting committees now bundle vascular access devices with dialysis machine leases, marginalizing standalone device vendors. This concentration is most visible in the United States, where independent dialysis centers have surrendered purchasing autonomy to corporate parent entities.
Arteriovenous Fistula Devices Market Segmentation
Vascular access procurement flows through distinct channel configurations that reshape how manufacturers allocate sales resources across product categories. Each segment category carries specific margin profiles and regulatory burdens that determine competitive positioning.
Product Type:
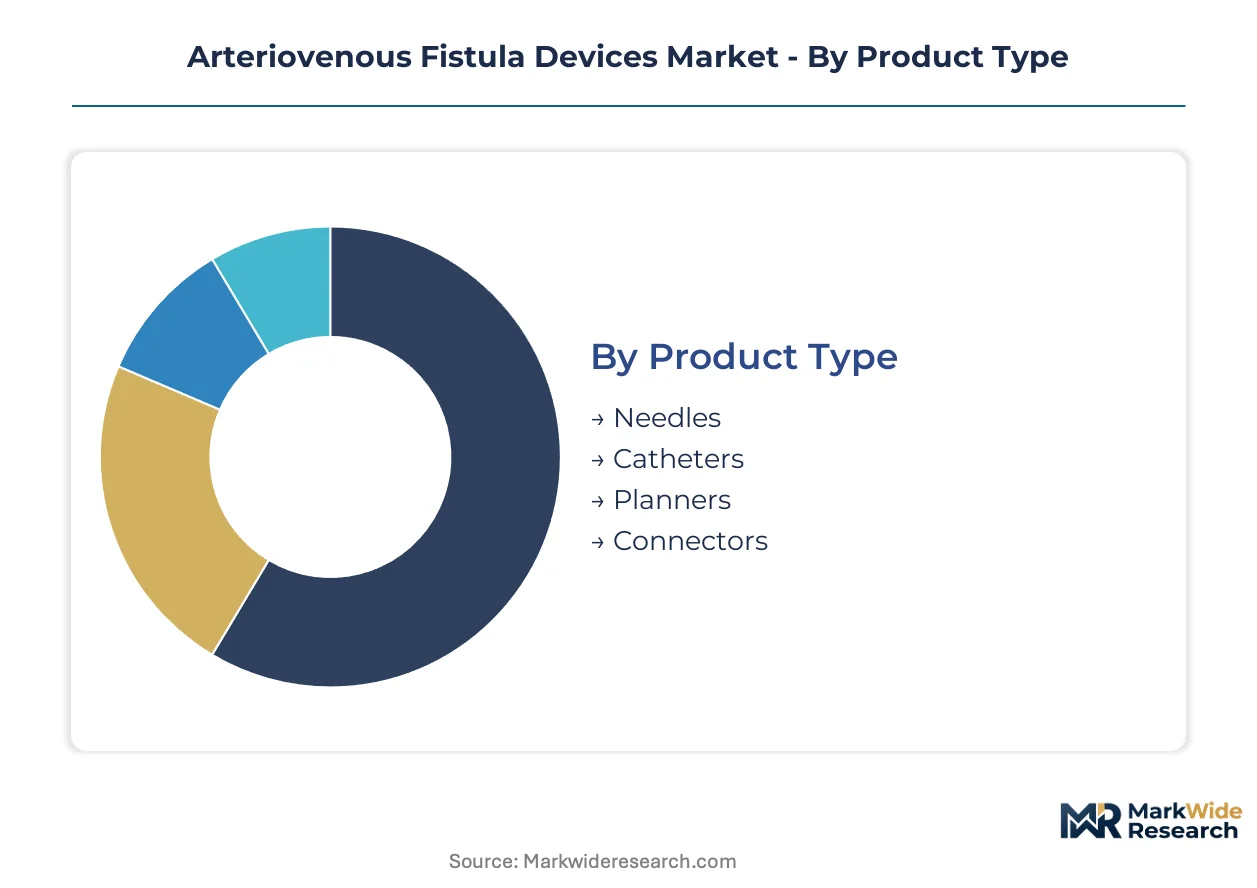
Channel mix varies sharply by product complexity — needles and catheters move through high-volume GPO contracts while planners and connectors require specialist distribution partnerships.
- Needles:Stainless steel and tungsten alloy configurations with bevel geometries optimized for ultrasound-guided cannulation. Demand concentrates in United States dialysis centers where CMS reimbursement penalties for catheter dependence drive permanent access creation. Technician training bottlenecks constrain throughput at high-volume facilities.
- Catheters:Dual-lumen silicone or polyurethane constructions with kink-resistant wall architecture and radiopaque stripe markers. Hospital procurement committees in Germany and France mandate antimicrobial-impregnated formulations under EU MDR post-market surveillance requirements. Fresenius Medical Care captive centers internalize bulk purchasing decisions.
- Planners:Surgical planning software and measurement tools for preoperative vessel mapping.
- Connectors:Luer-lock and needleless valve designs for circuit integrity during dialysis sessions.
Needles dominate installed base. Catheters represent where expansion concentrates as infection-resistant coatings gain procurement mandates.
End User:
Cost tier stratification separates capital-intensive hospital installations from lean dialysis center operations with compressed device budgets.
- Dialysis Centers:Freestanding outpatient facilities operating under Medicare's ESRD Prospective Payment System bundled reimbursement. United States centers face CMS quality metrics penalizing catheter dwell time. DaVita and Fresenius Medical Care procurement committees centralize purchasing through Premier and Vizient GPOs.
- Hospitals:Acute care settings managing inpatient dialysis and vascular access surgery. German hospitals under EU MDR implement enhanced vigilance reporting for thrombosis events. Antimicrobial catheter premiums absorbable within DRG-based reimbursement.
- Home Care:Patient-managed hemodialysis requiring simplified connection interfaces and training support.
- Clinics:Physician office-based vascular access procedures with lower procedure volume and price sensitivity.
Dialysis centers capture volume concentration. Home care represents the steepest expansion trajectory as patient self-management protocols mature.
Material:
Supply concentration in Northeast Asian chemical processors creates geographic vulnerability for silicone-dependent manufacturers.
- Silicone:Medical-grade platinum-cured elastomers with Shore A durometer specifications for catheter construction. Japanese and South Korean chemical processors dominate upstream supply. Freight cost volatility and geopolitical disruption expose device manufacturers to margin compression.
- Polycarbonate:High-impact thermoplastic formulations for connector housings and luer components. European compounding specialists under REACH regulation manage bisphenol-A migration testing protocols. Bayer and Covestro supply chains anchor German manufacturing clusters.
- Polyethylene:Low-density formulations for temporary catheter sheaths and introducers.
- Stainless Steel:304 and 316L grades for needles and surgical instruments facing commodity pricing pressure.
Silicone dominates catheter installed base. Polycarbonate is where material substitution concentrates as manufacturers seek supply chain diversification.
Technology:
Application requirements separate acute infection control from long-term biocompatibility in material selection decisions.
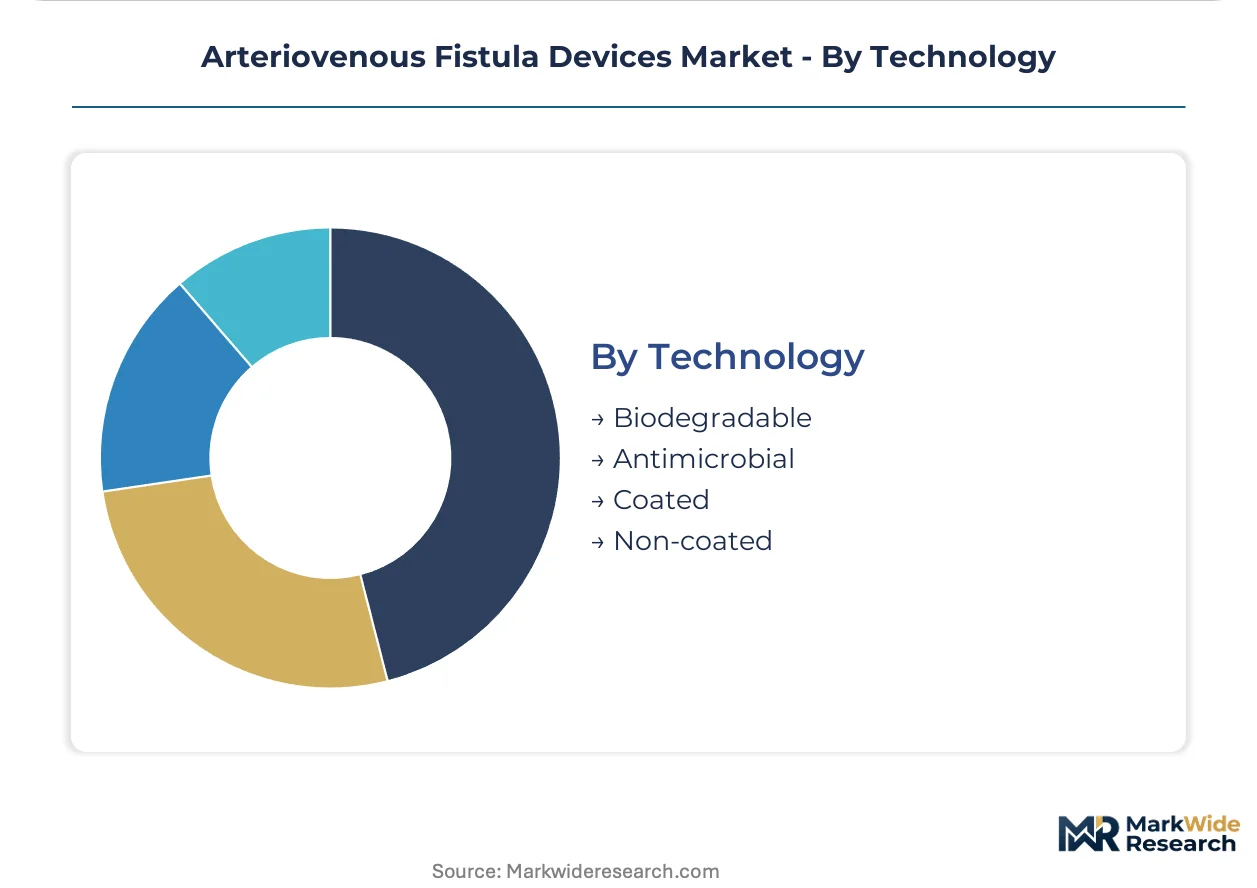
- Antimicrobial:Silver-ion, chlorhexidine, and minocycline-rifampin surface treatments integrated during extrusion or applied as topcoats. Joint Commission accreditation standards for United States dialysis facilities mandate infection rate thresholds. Coating technology licensors capture premium pricing as Fresenius and DaVita procurement committees mandate resistant materials.
- Biodegradable:Polycaprolactone and polylactic acid scaffolds for temporary fistula maturation support. Experimental formulations attract R&D allocation from manufacturers seeking differentiation against permanent synthetic grafts. Clinical evidence requirements under EU MDR extend development timelines.
- Coated:Hydrophilic and heparin-bonded surfaces for thrombosis resistance.
- Non-coated:Base material constructions without surface modification for cost-sensitive procurement.
Antimicrobial dominates hospital procurement. Biodegradable is where technology investment concentrates as manufacturers pursue fistula maturation differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification requirements anchor United States procurement patterns, while EU MDR clinical evidence mandates reshape European commercialization timelines. Device manufacturers navigate parallel regulatory frameworks across Japan's PMDA and Health Canada's PMRA for multi-regional market access.
United States
Medicare's ESRD Prospective Payment System bundles reimbursement for dialysis services, pressuring providers toward permanent fistula creation over temporary catheter dependence. CMS quality metrics penalize extended catheter dwell time, accelerating device procurement for vascular access programs. The Cleveland Clinic and Mayo Clinic anchor interventional nephrology training expansion in the Midwest.
Germany
EU MDR post-market surveillance obligations now extend thrombosis reporting requirements to fistula planners and connectors, extending product lifecycle management costs. German notified bodies demand real-world evidence registries for vascular access devices seeking CE marking renewal. The Rhine-Ruhr industrial corridor concentrates polycarbonate compounding operations for connector housings under REACH bisphenol-A migration protocols.
Japan
PMDA review frameworks for vascular access catheters maintain parallel documentation requirements to FDA 510(k) pathways, though timeline predictability exceeds American variability. METI industrial policy supports domestic silicone elastomer production to reduce Northeast Asian supply chain exposure. Osaka-based chemical processors specialize in medical-grade platinum-cured formulations for kink-resistant catheter construction.
India
The Pradhan Mantri National Dialysis Program expands government-funded hemodialysis infrastructure into tier-2 and tier-3 cities, creating first-time procurement demand for fistula creation devices. CDSCO medical device registration requirements are harmonizing with ASEAN regulatory frameworks to accelerate import clearance. Tamil Nadu and Karnataka anchor private dialysis center buildout in South India.
Brazil
ANVISA medical device registration pathways for vascular access products require in-country clinical testing, extending commercialization timelines for foreign manufacturers. SUS public health system procurement favors cost-optimized needle configurations over antimicrobial-coated premiums. São Paulo state concentrates private dialysis operator consolidation, compressing vendor negotiation leverage.
Arteriovenous Fistula Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidation pressure intensifying through group purchasing organization contracting. Tier-one participants span imaging guidance through closure systems, while mid-cap specialists concentrate on single-product categories. Three archetypes dominate: diversified medtech conglomerates with dialysis channel integration, European manufacturing specialists with regional supply chain anchoring, and emerging-market cost optimizers with commodity needle production. Competitive moves concentrate on GPO contract bundling and antimicrobial coating technology licensing.
Among diversified medtech conglomerates, Medtronic and Fresenius Medical Care AG & Co. KGaA exemplify vertical integration strategies spanning device production through downstream service delivery. B. Braun SE represents the European manufacturing specialist archetype, with SE corporate structure indicating regional supply chain anchoring. These three entities illustrate how regulatory compliance scale and channel ownership determine positioning against standalone device vendors.
| Leading Market Players |
|---|
| Medtronic |
| BD |
| Teleflex Incorporated |
| Fresenius Medical Care AG & Co. KGaA |
| B. Braun SE |
| Polymedicure |
| NxStage Medical |
| Cook Medical |
| W. L. Gore & Associates |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Japanese and South Korean silicone processors runs above 85%, compressing margin buffers for catheter manufacturers and establishing price floors that resist downward pressure from dialysis center procurement committees. This concentration of medical-grade elastomer production in Northeast Asia simultaneously limits supply alternatives and amplifies freight cost pass-through into landed device costs.
Pricing Analysis
United States antimicrobial catheter premiums exceed German hospital contract prices by 15-25%, reflecting CMS bundled reimbursement absorption capacity versus EU MDR compliance cost allocation. Three-tier pricing structure across premium, standard, and economy levels separates infection-resistant coated formulations from base silicone and commodity stainless steel needles. Cost compression in economy needle tiers intensifies as Indian and Brazilian manufacturers scale output for government dialysis programs. Dialysis centers operating under fixed ESRD Prospective Payment System rates exhibit highest price sensitivity, while hospital procurement committees absorb antimicrobial premiums within DRG-based reimbursement.
Supply Chain Analysis
Inventory buffers for medical-grade silicone catheter tubing extend to 90-120 days at major device manufacturers, reflecting vulnerability to Northeast Asian chemical processor disruption. Raw material sourcing concentrates in Japan, South Korea, and Germany, with platinum-cured elastomer formulations drawing from Osaka-based specialists and polycarbonate connector housings anchored in Rhine-Ruhr compounding operations. Single-source vulnerability pervades antimicrobial coating chemistry, where silver-ion and chlorhexidine licensors control premium formulation access. Distribution runs through consolidated group purchasing organization contracts at Premier and Vizient, marginalizing standalone device vendors from high-volume dialysis center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward consolidated dialysis operators, with DaVita and Fresenius Medical Care procurement committees now centralizing vascular access decisions that independent centers previously managed autonomously.
For Market Incumbents: Fortify GPO contract bundling with dialysis machine leases and imaging guidance systems to lock out standalone device competitors. Deepen backward integration into antimicrobial coating chemistry through exclusive licensing arrangements with silver-ion and chlorhexidine technology holders, neutralizing coating cost pass-through threats from raw material suppliers. For New Entrants and Emerging Players: Anchor in India's Pradhan Mantri National Dialysis Program infrastructure buildout, where first-time device procurement in tier-2 and tier-3 cities lacks incumbent supplier relationships. Target bioresorbable fistula maturation scaffolds as the most penetrable white space, positioning polycaprolactone-based temporary stents between permanent synthetic grafts and native fistulas with specialist interventional nephrology distribution partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coating technology licensors and integrated imaging-to-closure system vendors over commodity needle manufacturers facing pricing erosion. Long-term viability over a 5-10 year window hinges on regulatory compliance scale and channel ownership depth. Acquisition target archetype: European manufacturing specialists with EU MDR Authorized Representative infrastructure and established notified body relationships. Monitor FDA 510(k) predicate device erosion as the critical inflection signal accelerating de novo pathway requirements and extending review timelines for new market entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Licensing | Silver-ion and chlorhexidine technology holders capture premium pricing as Fresenius and DaVita mandate infection-resistant materials. |
| EU MDR Authorized Representative Establishment | German notified bodies demand clinical expertise for CE marking renewal, extending product lifecycle management costs for vascular access devices. |
| India Distribution Partnership | CDSCO harmonization with ASEAN frameworks accelerates import clearance for devices targeting government-funded dialysis center expansion. |
| Remote Patient Monitoring Integration | Implantable flow sensors paired with cloud surveillance enable predictive thrombosis alerts and recurring revenue beyond device sale. |
| Interventional Nephrology Training Sponsorship | American Society of Diagnostic and Interventional Nephrology credentialing programs enlarge the specialist pool capable of ultrasound-guided fistula procedures. |
Research Methodology
A spread of perspectives from interventional nephrologists, dialysis center procurement managers, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR notified body guidance documents, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up device shipment estimates and top-down reimbursement flow analysis were triangulated to establish market sizing boundaries.
Segmentation dimensions modeled include product type complexity tier, end-user facility reimbursement structure, material formulation grade, and antimicrobial versus biodegradable technology application. CAGRs across the analysis window were derived from procedure volume elasticity to ESRD incidence projections and device replacement cycle assumptions. Forecast inputs incorporated CMS quality metric penalty structures and EU MDR post-market surveillance cost trajectories specific to vascular access catheter vigilance reporting.
Decision-makers should treat outputs as directional under assumptions of stable Northeast Asian silicone supply and continued CMS bundled reimbursement favoring fistula over catheter dependence; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Global Injectable Drug Delivery Devices Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Global Advanced Bipolar Direct Energy Device Market
Medical Devices
Spinal Needles Market
Medical Devices
Extremity Tissue Expanders Market
Medical Devices
Asthma Spacers Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Cyclotron Market
Medical Devices
Dosage Unit Sampling Apparatus Market
Medical Devices
Breast Pump Flange Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
General Surgery Devices Market