
 Cold-Climate Optimized EV Battery Systems Market | 2026-2036
Cold-Climate Optimized EV Battery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cold-Climate Optimized EV Battery Systems Market Insights
UN ECE R100 certification for battery safety in electric powertrains is collapsing the supplier field to firms with validated cold-cycle test data. CATL leverages its in-house sodium-ion pilot lines to anchor bids for Nordic OEM contracts. Tesla sustains vertical control over thermal firmware, which differentiates its pack performance below minus twenty degrees Celsius. LG Energy Solution competes on European homologation speed, having secured multiple ECE R100 extensions ahead of rivals.
Cold-climate optimized EV battery systems integrate electrolyte formulations with depressed freezing points, ceramic-coated separators, and active heating circuits to sustain discharge efficiency at sub-zero temperatures; their primary purpose is to eliminate range loss and lithium plating failures that disable standard packs in arctic operating conditions. Lithium Iron Phosphate chemistry dominates installed base economics for municipal electric buses where cycle life outweighs energy density premiums. Solid-state cells represent the fastest-growing chemistry segment as pilot lines demonstrate stable conductivity at minus thirty degrees Celsius. Heat pump thermal management technology captures expanding margin pools by replacing resistive heating with coefficient-of-performance gains that extend effective range.
EPA tailpipe regulations and the EU Green Deal fleet CO2 mandates jointly force OEMs to certify electric drivetrains across extended temperature maps, which elevates cold-weather validation to a market-access gate. China's GB standards for power battery safety and Norway's zero-emission fjord ferry requirements create divergent but equally stringent test protocols that fragment certification costs. Stakeholders must monitor solid-state manufacturing yield trajectories and thermal management patent filings to anticipate which chemistry-thermal pairing will capture the next wave of arctic fleet tenders.
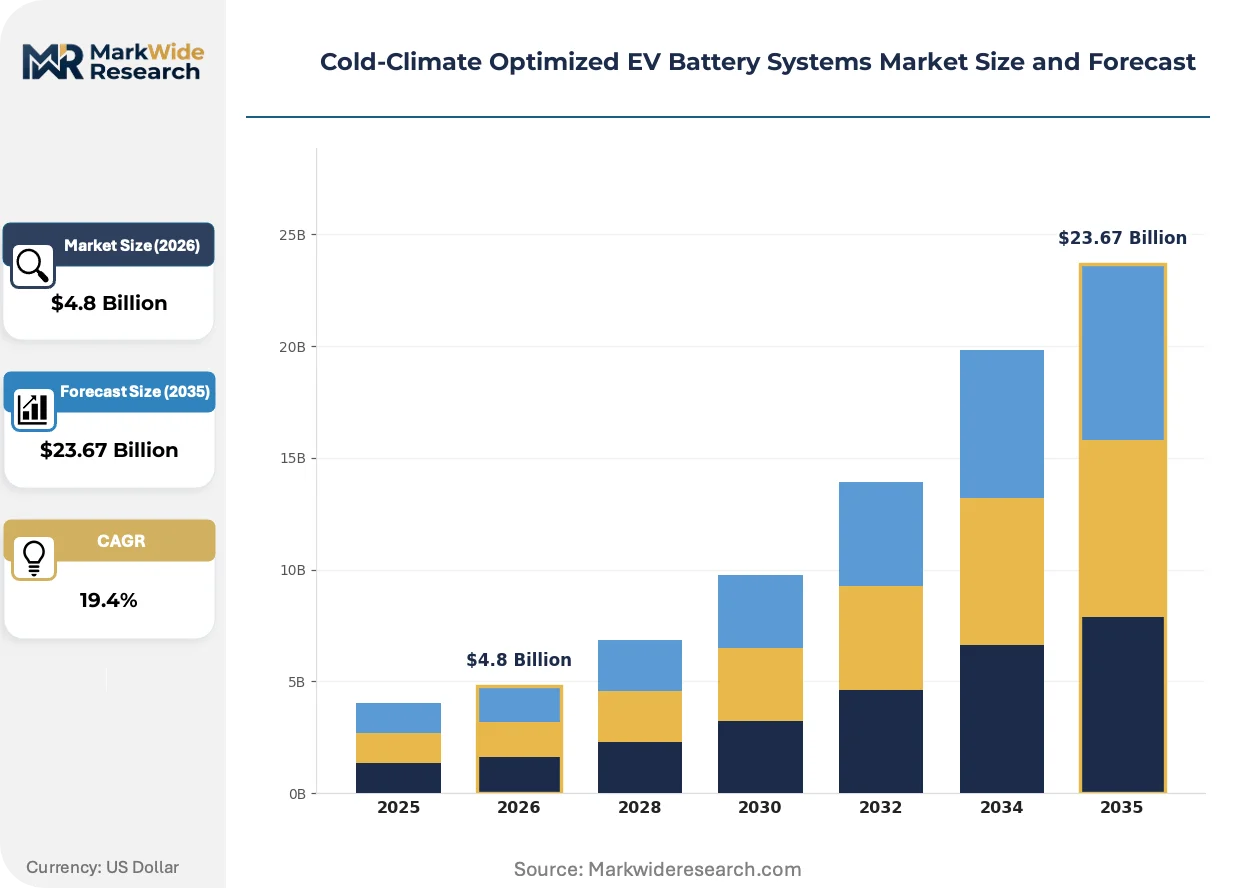
Market Dynamics
Sodium-ion chemistry advances are compressing lithium supply dependencies while UN ECE R100 certification requirements filter supplier qualification to firms with validated arctic-cycle test protocols.
Growth Catalysts
- Nordic Fleet Electrification Mandates:Norway's zero-emission fjord ferry requirements and Sweden's public transit diesel phase-outs are accelerating tender volumes for cold-optimized packs in municipal bus and marine applications.
- EU Green Deal Fleet CO2 Mandates:Extended temperature map certification requirements now force OEMs to validate drivetrains across sub-zero operating envelopes, elevating cold-weather battery performance to market-access criteria.
- Solid-State Pilot Line Demonstrations:Stable ionic conductivity at minus thirty degrees Celsius in ceramic-electrolyte cells is opening performance gaps that incumbent liquid-electrolyte systems cannot close.
Market Restraints
- Lithium Carbonate Price Volatility:Raw material input swings compress pack margins and deter long-term contract pricing for cold-optimized variants with premium electrolyte formulations.
- East Asian Cell Concentration:Cathode active material supply and pilot-scale solid-state manufacturing capacity cluster in China and South Korea, creating geographic single-source vulnerability for European OEM qualification timelines.
- Resistive Heating Energy Penalty:Legacy thermal management architectures consume fifteen to twenty-five percent of pack energy at minus twenty degrees Celsius, degrading effective range below commercial viability thresholds for long-haul freight operators.
Strategic Opportunities
- Arctic Corridor Testing Infrastructure:Finland's Rovaniemi and Norway's Tromsø validation centers offer controlled sub-zero proving grounds that attract OEM development programs seeking ECE R100 certification efficiency.
- Heat Pump Thermal Convergence:Coefficient-of-performance gains from refrigerant-based heating circuits are replacing resistive elements and extending range metrics that differentiate bid submissions for Scandinavian electric bus tenders.
- GB Standards Alignment Pathways:China's power battery safety certification reciprocity negotiations with EU regulators could streamline dual-homologation costs for cell suppliers serving both domestic and European OEM pipelines.
Industry Challenges
- Solid-State Manufacturing Yield Gaps:Ceramic electrolyte densification and dry electrode coating processes require capital-intensive pilot line reconfiguration before gigafactory scale-up becomes economically viable.
- Multiphysics Simulation Talent Scarcity:Coupled thermal-electrochemical modeling for arctic operating conditions demands specialized computational engineering capabilities that outpace current university pipeline output in Europe and North America.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold-Climate Optimized EV Battery Systems Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $23.67 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Chemistry: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lithium Iron Phosphate, Sodium-Ion Thermal Management Technology: Active Heating, Passive Insulation, Phase Change Materials, Heat Pumps, Liquid Cooling Vehicle Type: Passenger Cars, Commercial Vans, Electric Buses, Delivery Trucks, Utility Vehicles Charging Infrastructure Compatibility: Fast Charging, Wireless Charging, Standard AC Charging, Ultra-Fast Charging, Destination Charging |
| Companies Covered | Tesla, BYD Company, CATL, LG Energy Solution, Samsung SDI, Panasonic, Robert Bosch, Valeo, Hanon Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold-Climate Optimized EV Battery Systems Market Trends and Innovations
Electrolyte formulation chemistry and thermal management architecture are converging to eliminate the range penalty that has constrained electric vehicle penetration in sub-zero climates.
Sodium-ion cells with hard carbon anodes and Prussian white cathodes are displacing lithium iron phosphate in municipal electric bus applications where energy density requirements are modest and cycle life economics dominate procurement evaluations. Nordic transit authorities are piloting these packs in Stockholm and Oslo depots. The chemistry shift is compressing lithium supply contract durations and redirecting cathode procurement toward sodium carbonate suppliers.
UN ECE R100 extensions for battery safety in electric powertrains now mandate thermal runaway propagation testing across extended temperature maps. European OEMs must submit cold-cycle abuse data to KBA and Swedish Transport Agency validators before type approval. The requirement is compressing supplier qualification timelines and favoring firms with in-house arctic test chambers over third-party validation dependencies.
Electric bus fleet operators are consolidating procurement around performance-based service contracts that unbundle battery asset ownership from vehicle acquisition. Municipal transit agencies in Norway and Finland now specify guaranteed range maintenance clauses across eight-year service lives. The model shift is transferring degradation risk to cell suppliers and requiring predictive analytics integration into pack management firmware.
Cold-Climate Optimized EV Battery Systems Market Segmentation
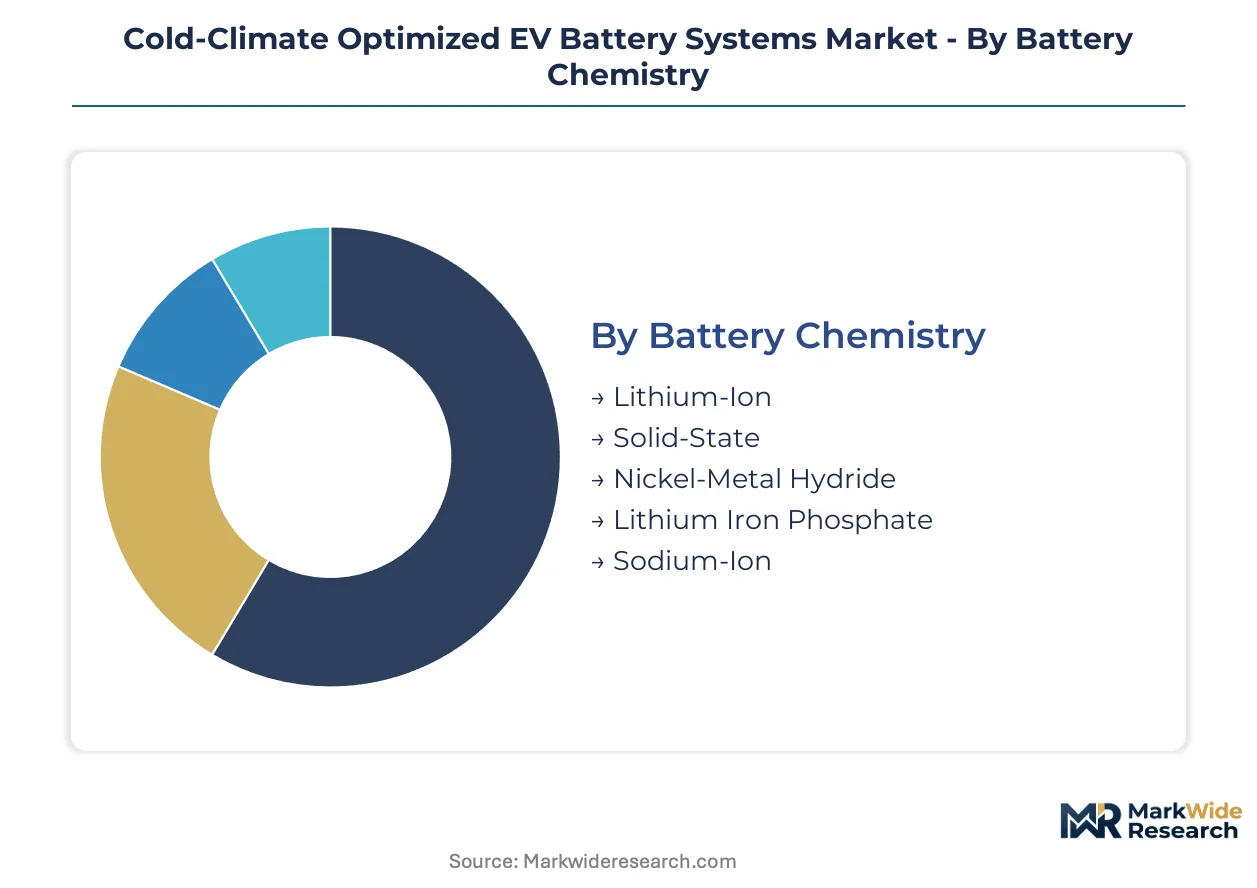
Cold-climate battery procurement channels diverge sharply by chemistry and thermal architecture. Fleet operators prioritize service-life guarantees, while passenger OEMs chase energy density premiums.
Battery Chemistry:
Channel mix splits between long-term fleet contracts favoring durable chemistries and consumer OEMs demanding energy density leadership.
- Lithium-Ion:Liquid electrolyte cells with graphite anodes deliver mature manufacturing scale and established cold-weather performance baselines. Demand concentrates in Norwegian passenger EV programs where OEMs require immediate ECE R100 certification without pilot-line risk.
- Solid-State:Ceramic electrolyte architectures eliminate dendrite formation at minus thirty degrees Celsius while sustaining ionic conductivity. Sweden's electric bus tenders in Stockholm and Gothenburg are absorbing pilot-line output as operators accept premium pricing for eight-year service-life guarantees.
- Nickel-Metal Hydride:Legacy hybrid applications retain installed base in cold-climate regions with mild electrification requirements.
- Lithium Iron Phosphate:Olivine cathode chemistry dominates municipal procurement where cycle life economics outweigh gravimetric density.
- Sodium-Ion:Hard carbon anode systems with Prussian white cathodes are displacing LFP in depot-charged bus fleets seeking supply chain independence from lithium carbonate volatility.
By volume, Lithium-Ion leads. By growth pace, Solid-State is expanding most quickly.
Thermal Management Technology:
Cost tier stratification separates premium heat pump architectures from resistive heating legacy systems in fleet retrofit decisions.
- Active Heating:Resistive element circuits embedded in cell modules consume pack energy to maintain operating temperature. Finnish electric bus operators in Helsinki specify active heating for depot-charged vehicles with guaranteed preconditioning infrastructure.
- Heat Pumps:Refrigerant-based thermal circuits deliver coefficient-of-performance gains that extend effective range fifteen to twenty-five percent versus resistive alternatives. Norwegian fjord ferry electrification mandates are capturing heat pump premiums in marine battery tenders.
- Passive Insulation:Aerogel and vacuum panel barriers reduce thermal loss without energy consumption penalty.
- Phase Change Materials:Paraffin or salt hydrate buffers absorb and release latent heat across temperature swings.
- Liquid Cooling:Ethylene glycol circuits manage thermal runaway propagation risk in high-energy-density packs.
By installed base, Active Heating dominates. By margin capture, Heat Pumps are climbing the fastest.
Vehicle Type:
Application urgency varies by duty cycle severity and revenue-at-risk from cold-weather downtime.
- Electric Buses:Depot-charged municipal fleets with predictable routes and preconditioning infrastructure. Norway's zero-emission fjord ferry requirements are extending battery system specifications to marine variants with similar thermal demands.
- Delivery Trucks:Last-mile logistics vehicles with high utilization rates and revenue sensitivity to range degradation. Swedish postal and parcel operators are consolidating procurement around cold-optimized pack guarantees.
- Passenger Cars:Consumer retail channel with fragmented buyer education on cold-climate performance differentiation.
- Commercial Vans:Small fleet and tradesman applications with moderate daily mileage requirements.
- Utility Vehicles:Construction and agricultural equipment with intermittent duty cycles and extreme exposure tolerance.
By tender volume, Electric Buses lead. By contract value growth, Delivery Trucks are gaining share fastest.
Charging Infrastructure Compatibility:
Customer type segmentation separates fleet depot operators from public network dependent users.
- Fast Charging:DC rapid infrastructure with thermal preconditioning protocols to enable safe high-current intake at sub-zero temperatures. Finnish and Norwegian highway corridor networks are mandating cold-weather performance certification for station qualification.
- Ultra-Fast Charging:Megawatt-scale systems for commercial vehicle turnaround with aggressive thermal management requirements.
- Standard AC Charging:Residential and workplace Level 2 infrastructure with extended dwell times.
- Wireless Charging:Inductive pad systems with alignment tolerance and thermal coupling challenges in frozen conditions.
- Destination Charging:Hotel and retail installations with overnight or extended-parking duty cycles.
By port count, Standard AC Charging leads. By infrastructure investment growth, Ultra-Fast Charging shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Cape electrical grid interconnect and Finland's Arctic Railway corridor anchor Nordic testing infrastructure for sub-zero battery validation programs.
Norway
Zero-emission fjord ferry mandates drive marine battery tenders from Tromsø to Bergen. The Norwegian Maritime Authority enforces strict cold-weather safety protocols for electrified coastal routes. Rovaniemi-adjacent proving grounds attract OEM winter validation programs seeking ECE R100 certification efficiency.
Sweden
Stockholm and Gothenburg transit authorities tender electric bus fleets with eight-year service-life guarantees. The Swedish Transport Agency mandates thermal runaway propagation testing across extended temperature maps. Västerås battery test chambers host multiple supplier qualification programs simultaneously.
China
NMPA cell-grade certification and GB standards compliance reshape supplier pipelines for domestic and export markets. MIIT dual carbon goals accelerate sodium-ion pilot line investments. Ningde manufacturing clusters anchor CATL's cold-optimized cell output for Nordic OEM contracts.
Germany
KBA type approval requirements filter market access to firms with validated arctic-cycle test data. EU Green Deal fleet CO2 mandates force OEMs to certify drivetrains across sub-zero operating envelopes. Munich engineering centers specialize in coupled thermal-electrochemical modeling for cold-climate packs.
United States
EPA tailpipe regulations push commercial fleet electrification into northern tier states with severe winter conditions. NHTSA battery safety guidelines influence thermal management design for Alaska and Upper Midwest operators. Detroit automotive clusters integrate cold-weather validation into platform development cycles.
Cold-Climate Optimized EV Battery Systems Market Competitive Landscape
Listed leaders compete with private specialists across certification speed and thermal firmware differentiation. The supplier field compresses around firms with validated cold-cycle test data and in-house arctic validation infrastructure. Three archetypes dominate: vertically integrated OEMs controlling pack thermal management, pure-play cell manufacturers racing European homologation timelines, and thermal system specialists integrating heat pump architectures. Competitive moves concentrate on backward integration into electrolyte formulation and strategic partnerships with Nordic fleet operators.
Within the premium-tier vector, Tesla exemplifies closed-loop thermal firmware control, while CATL anchors sodium-ion chemistry advancement for municipal bus applications. LG Energy Solution occupies a position defined by European homologation speed, having secured multiple ECE R100 extensions. These three represent divergent strategic postures: captive supply chain integration, alternative chemistry scale-up, and regulatory compliance acceleration.
| Leading Market Players |
|---|
| Tesla |
| BYD Company |
| CATL |
| LG Energy Solution |
| Samsung SDI |
| Panasonic |
| Robert Bosch |
| Valeo |
| Hanon Systems |
| Others |
Pricing and Supply Chain Analysis
UN ECE R100 certification gates both supplier qualification and price differentiation simultaneously, compressing the vendor field to firms with validated arctic-cycle test data while allowing certified players to command premiums for cold-optimized cell formulations. Municipal transit authorities in Norway and Sweden now bundle eight-year range guarantees into procurement evaluations, shifting pricing power toward suppliers with predictive analytics-integrated firmware.
Pricing Analysis
Volume-discount tiering structures separate Nordic fleet tenders from passenger OEM spot purchases. Three-tier pricing stratifies across premium certified, standard qualified, and economy provisional levels based on ECE R100 extension status and thermal management architecture. Pricing pressure stems from sodium-ion chemistry scale-up compressing lithium carbonate contract premiums. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership procurement models, while marine electrification mandates show lowest sensitivity given regulatory compliance deadlines.
Supply Chain Analysis
Cathode active material refining in China and South Korea anchors cell-grade output for cold-optimized formulations. Raw material procurement draws from lithium carbonate spot markets, sodium carbonate industrial streams, and ceramic electrolyte precursor chemicals. Single-source vulnerability concentrates in Ningde manufacturing clusters where CATL pilots sodium-ion lines. Distribution runs through European homologation hubs in Germany and Sweden before Nordic OEM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
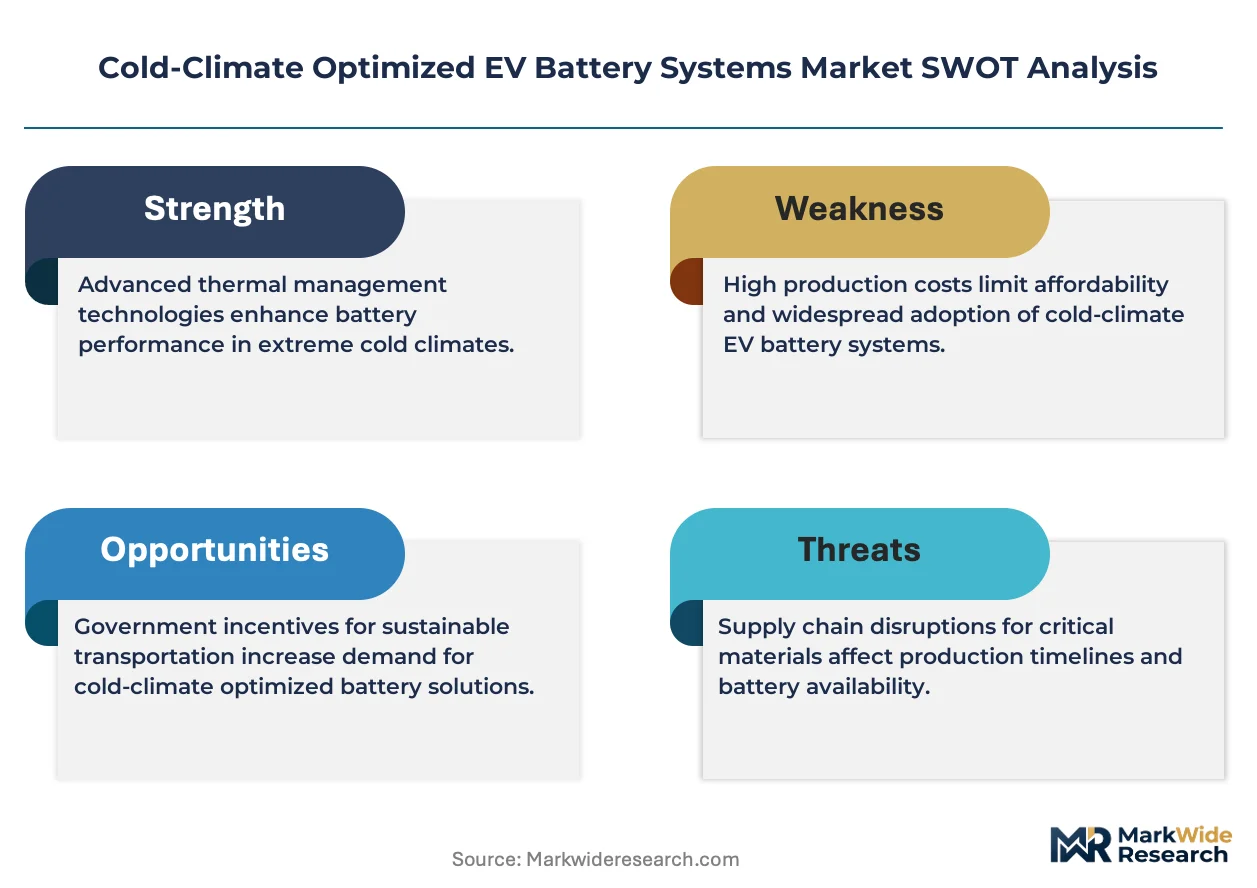
Cold-climate battery procurement is restructuring around performance-based service contracts where predictive maintenance subscriptions expand faster than hardware margins. Municipal operators now unbundle battery asset ownership from vehicle acquisition, creating recurring revenue layers that outpace pack sales growth.
For Market Incumbents: Shield installed base relationships by backward integration into electrolyte formulation and captive arctic testing infrastructure. Sodium-ion chemistry advances threaten lithium-dependent incumbents with supply chain disintermediation. Certification speed investments at Västerås and Rovaniemi validation centers defend Nordic tender participation rights.
For New Entrants and Emerging Players: Lead with heat pump thermal management specialization targeting Swedish electric bus retrofit programs. Last-mile delivery truck fleets in Finland show penetrable white space with unconsolidated procurement and revenue-at-risk sensitivity to range degradation. Partner with Finnish highway corridor charging networks for integrated thermal preconditioning validation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed thermal management specialists holding heat pump patents but lacking cell supply partnerships. Five-to-ten year viability hinges on solid-state manufacturing yield trajectories and chemistry-thermal convergence outcomes. Monitor GB standards reciprocity negotiations as inflection signal for dual-homologation cost compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Arctic Testing Infrastructure Expansion | Finland's Rovaniemi validation centers attract OEM programs seeking ECE R100 certification efficiency. |
| Sodium-Ion Chemistry Scale-Up | CATL's Ningde pilot lines compress lithium supply dependencies for municipal bus applications. |
| Heat Pump Thermal Convergence | Refrigerant-based heating circuits extend range metrics that differentiate Scandinavian electric bus tenders. |
| Performance-Based Service Contracts | Norwegian transit agencies transfer degradation risk to cell suppliers through guaranteed range clauses. |
| GB Standards Alignment Pathways | China's power battery safety certification reciprocity negotiations could streamline dual-homologation costs. |
Research Methodology
Desk research of UN ECE regulatory filings, GB standards documentation, and Nordic tender databases preceded structured interviews with battery platform engineers, fleet procurement directors, thermal management R&D leads, and homologation specialists. Secondary validation drew from KBA type approval records, Swedish Transport Agency test protocols, and MIIT pilot line investment disclosures. Bottom-up cell chemistry demand modeling triangulated against top-down fleet electrification mandates.
Variance-decomposition across chemistry, thermal architecture, and vehicle type segments shaped the analytical framework over the projection horizon. CAGRs derived from coupled thermal-electrochemical performance modeling and arctic fleet deployment trajectories. Solid-state manufacturing yield curves and sodium-ion commercialization timelines fed industry-specific forecast inputs alongside ECE R100 extension approval rates.
The analysis sits within stated boundaries; outcomes outside sustained Nordic electrification policy support and ceramic electrolyte densification breakthroughs would require recalibration. Forecasts reflect documented assumptions about thermal management patent filings and chemistry-thermal pairing adoption curves. Practitioners should keep alternative scenarios live as GB standards reciprocity negotiations and solid-state pilot line yields evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Europe Electric Vehicle Battery Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
European EV Battery Systems Market
EV Batteries
Europe LFP Battery Pack Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
North America LFP Battery Pack Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market