
 Europe Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
Europe Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Battery Manufacturing Equipment Market Insights
Modular cell production line configurations is hardening as the dominant procurement model across European battery gigafactories. Duerr AG leverages its paint-shop heritage to automate coating and assembly stages for pouch and cylindrical formats. Schuler AG anchors the press and forming segment with heavy-duty equipment calibrated to European automotive tolerances. Buhler Holding AG competes on thermal processing expertise, sustaining its position in electrode drying and sintering systems.
Europe Electric Vehicle Battery Manufacturing Equipment encompasses the specialized machinery, automated systems, and process controls required to fabricate electrochemical cells and assemble them into battery packs, with line speeds typically calibrated to achieve throughput rates exceeding 200 cells per minute for high-volume automotive applications. Cell Production Lines command the largest installed base among equipment categories, reflecting the capital intensity of electrode coating, stacking, and formation stages. Solid-state technology represents the fastest-growing segment within the technology dimension, though Lithium-ion retains dominant share through the forecast horizon as European OEMs scale NMC and LFP chemistries. Testing Equipment captures concentrated margin pools due to validation requirements under the EU Battery Regulation and automotive OEM qualification protocols.
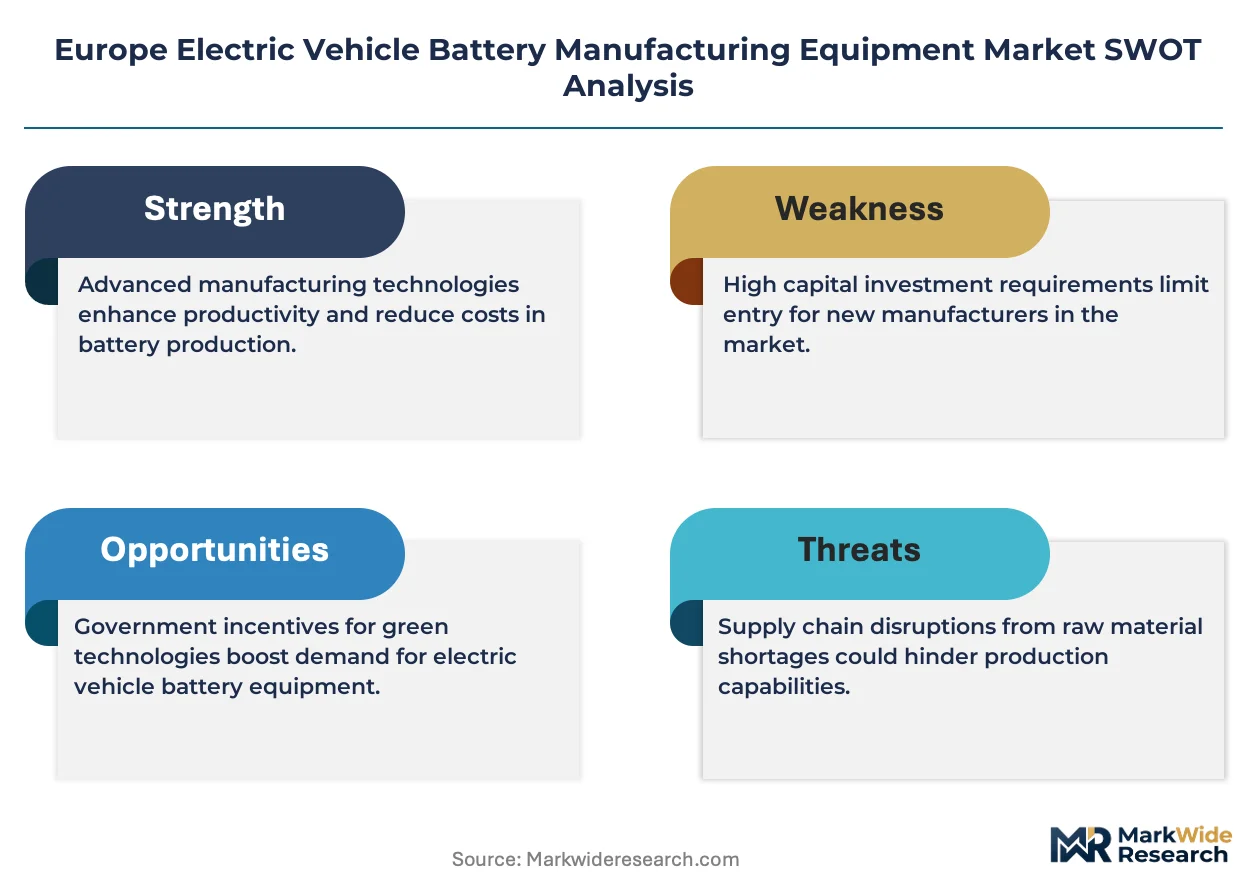
The EU Green Deal and F-Gas Regulation directly shape equipment specifications by mandating low-carbon production pathways and restricting fluorinated greenhouse gases in thermal processes. ECHA's REACH framework governs chemical handling in electrode manufacturing, while CE marking requirements ensure interoperability across national production networks. Stakeholders must monitor how the EU AI Act intersects with automated quality inspection systems, as machine vision and predictive maintenance modules face emerging compliance obligations for high-risk industrial applications.
Market Dynamics
Modular cell production line configurations are hardening as the dominant procurement model across European battery gigafactories, compressing equipment vendor margins while accelerating factory commissioning timelines. This structural shift toward standardized, reconfigurable platforms is forcing equipment makers to abandon bespoke engineering in favor of scalable architectures.
Growth Catalysts
- EU Green Deal:Mandates for low-carbon production pathways are driving OEM demand for energy-efficient electrode coating and formation equipment calibrated to Scope 3 emissions targets.
- Solid-state chemistry advancement:European research consortia are scaling dry electrode processing techniques that eliminate solvent-based coating, creating pull for next-generation thermal and pressing systems.
- Polish manufacturing corridor:Aggressive site development near LG Energy Solution and SK On facilities is concentrating demand for automated stacking and welding modules.
Market Restraints
- Specialized component supply concentration:Precision linear motion systems and high-vacuum chambers rely heavily on German and Swiss suppliers, creating single-source vulnerability for gigafactory timelines.
- REACH compliance complexity:ECHA's evolving substance restrictions on NMP solvents and cobalt compounds are extending qualification cycles for electrode manufacturing equipment by 8-14 months.
- Lithium-ion cost curve:Mature cell chemistry economics are compressing capital expenditure budgets for formation and aging equipment, favoring refurbished or leased asset models.
Strategic Opportunities
- Hungary secondary corridor:CATL and Samsung SDI expansion around Debrecen is creating greenfield demand for fully integrated module-to-pack assembly lines with minimal legacy retrofit burden.
- EU AI Act intersection:Automated optical inspection and predictive maintenance modules face emerging high-risk classification, opening compliance-as-a-service revenue streams for equipment vendors.
- Solid-state pilot scaling:BMW and Volkswagen qualification programs for sulfide and oxide electrolyte cells are generating equipment orders for thin-film deposition and lamination systems.
Industry Challenges
- Electrochemical process engineering talent:European universities produce insufficient graduates with combined materials science and high-volume manufacturing expertise, forcing equipment vendors to poach from Asian cell makers.
- CE marking and automotive qualification concurrency:Parallel approval tracks for machinery safety and OEM process validation are creating timeline conflicts that delay revenue recognition.
- Legacy paint-shop automation retrofit:Volkswagen and Stellantis facilities repurposing internal combustion engine plants face spatial constraints for battery line integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Battery Manufacturing Equipment Market |
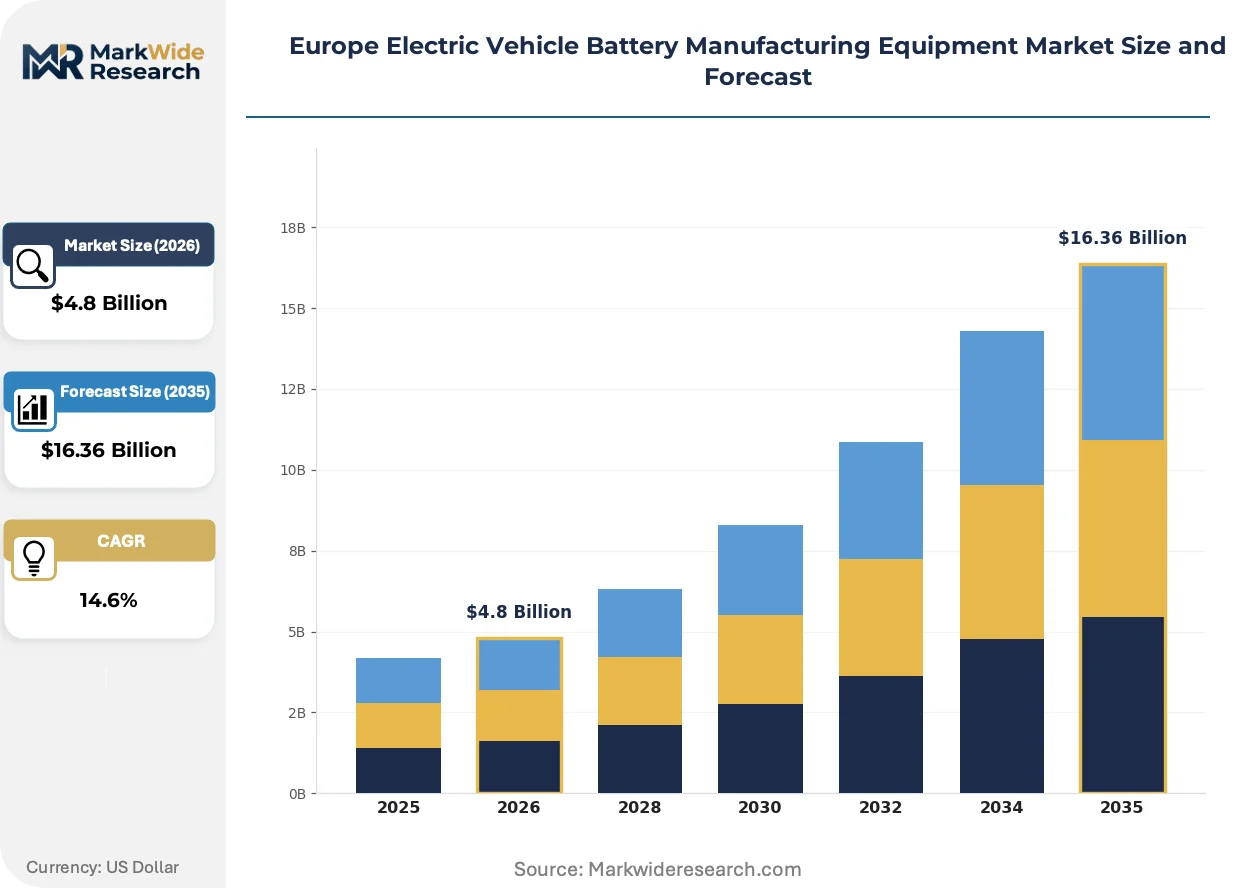
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Battery Assembly Machines, Cell Production Lines, Drying Ovens, Testing Equipment Technology: Lithium-ion, Solid-state, Nickel-Metal Hydride, Lead-acid End User: Automobile Manufacturers, Battery Suppliers, Research Institutions, Aftermarket Providers Application: Electric Buses, Passenger Vehicles, Two-wheelers, Energy Storage Systems |
| Companies Covered | Duerr AG, Hitachi Ltd, Schuler AG, Buhler Holding AG, Sovema Group S.p.A., ACEY New Energy Technology, IPG Photonics Corporation, Xiamen Tmax Battery Equipments Limited, Robert Bosch Manufacturing Solutions GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Dry electrode processing is unifying formerly discrete coating and calendering stages, collapsing capital intensity while tightening environmental compliance. Equipment architectures are converging around platform designs that accommodate both NMC and LFP chemistries through software-parameter adjustment rather than mechanical reconfiguration.
Roll-to-roll dry electrode coating is unifying binder fibrillation and active material dispersion into continuous solid-state deposition. European OEM pilot lines at BMW Group and Northvolt are validating throughput parity with wet coating by 2027. This unification is compressing factory footprints by 40% and eliminating solvent recovery infrastructure.
The EU F-Gas Regulation is restricting hydrofluorocarbon use in thermal management systems for electrode drying and cell formation. Equipment vendors are substituting CO2 heat pumps and electric infrared arrays for conventional gas-fired ovens. German gigafactory projects are most affected, with ECHA enforcement timelines accelerating replacement cycles.
Cell manufacturer purchasing departments are consolidating equipment procurement under long-term framework agreements with penalty clauses for commissioning delays. Tier 1 automotive suppliers are displacing direct vendor relationships in favor of integrated line responsibility contracts. This concentration is most visible in Germany, where Volkswagen PowerCo and Mercedes-Benz battery operations have reduced qualified supplier pools to 4-6 platform vendors per equipment category.
Europe Electric Vehicle Battery Manufacturing Equipment Market Segmentation
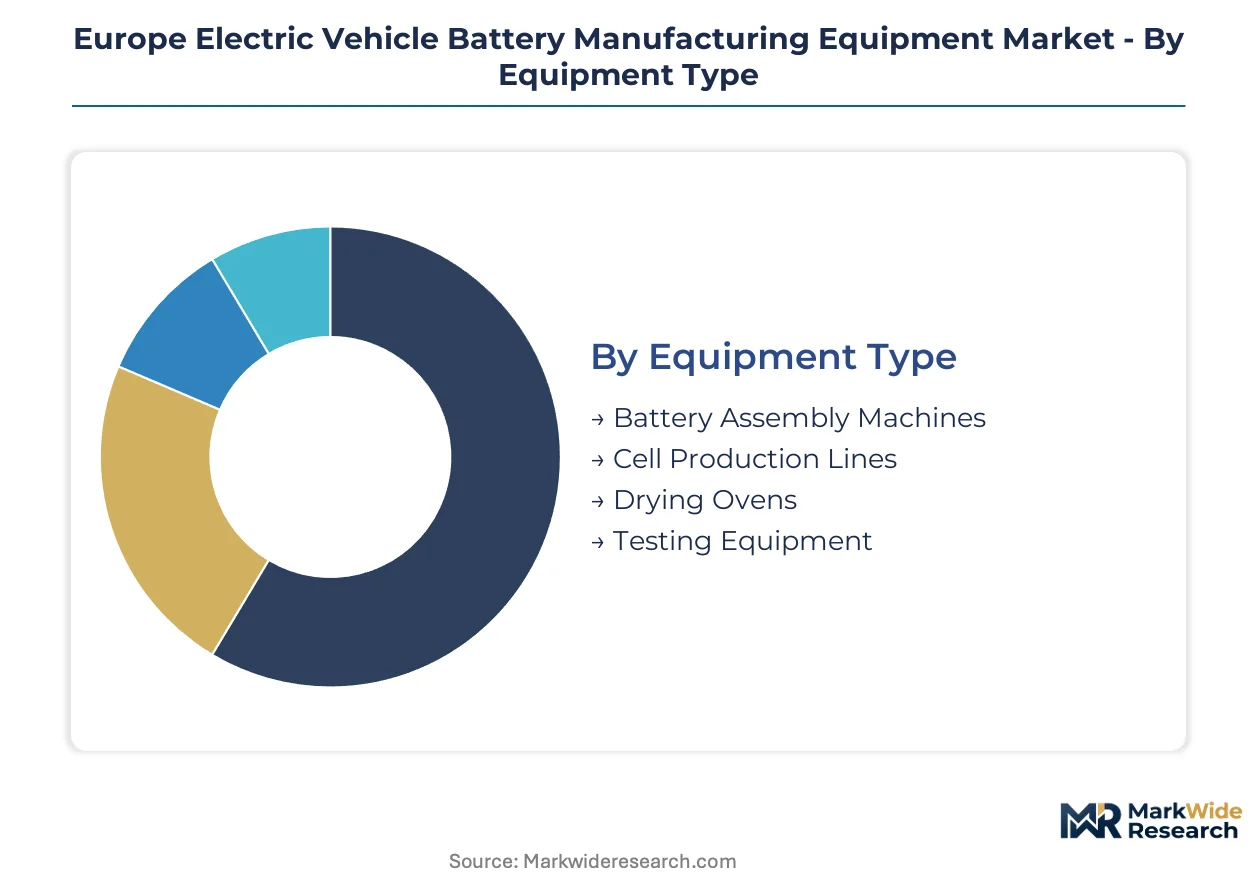
Equipment procurement patterns across European battery gigafactories diverge sharply by production scale and chemistry maturity. Understanding these segment boundaries clarifies where capital deployment concentrates and which technology transitions threaten incumbent positions.
Equipment Type:
Volume lines dominate capital allocation, yet premium-margin pockets persist in validation and thermal processing stages.
- Cell Production Lines:Integrated systems for electrode coating, stacking, and formation absorb the majority of gigafactory capex. German OEM buildouts by Volkswagen PowerCo and Mercedes-Benz concentrate demand here, driven by EU Green Deal Scope 3 compliance timelines.
- Testing Equipment:Automated validation systems for electrochemical performance and safety certification command concentrated margins. ECHA REACH substance tracking and EU Battery Regulation compliance requirements extend qualification cycles, entrenching specialized vendors.
- Battery Assembly Machines:Module-to-pack integration systems serving final assembly stages.
- Drying Ovens:Thermal processing equipment for electrode dehydration and cell formation.
Today's leader: Cell Production Lines. Tomorrow's challenger: Testing Equipment.
Technology:
Application requirements split procurement between proven chemistries and emerging solid-state architectures.
- Lithium-ion:NMC and LFP formats retain dominant equipment demand through the forecast window. Polish and Hungarian manufacturing corridors anchor volume, with BMW Group and Northvolt scaling dry electrode processing variants.
- Solid-state:Sulfide and oxide electrolyte cells are climbing the fastest, generating equipment orders for thin-film deposition and lamination systems. BMW and Volkswagen qualification programs are validating pilot-line throughput.
- Nickel-Metal Hydride:Legacy hybrid vehicle applications sustaining limited equipment refresh demand.
- Lead-acid:Aftermarket and industrial storage applications with minimal European automotive relevance.
Established chemistry retains the installed base. Solid-state pilots threaten equipment vendor incumbency.
End User:
Customer concentration shapes contract structures and vendor qualification pathways.
- Automobile Manufacturers:Volkswagen, Mercedes-Benz, and Stellantis battery operations consolidate procurement under framework agreements with penalty clauses. Direct OEM relationships displace tiered supplier channels for cell production line categories.
- Battery Suppliers:LG Energy Solution and SK On facilities in Poland generate concentrated demand for automated stacking and welding modules, with CATL and Samsung SDI expansion around Debrecen following similar patterns.
- Research Institutions:European research consortia validating dry electrode and solid-state processing techniques.
- Aftermarket Providers:Secondary market cell replacement and refurbishment operations with limited new equipment demand.
OEM captive production commands vendor attention. Independent cell suppliers are gaining procurement leverage.
Application:
Vehicle class determines line speed specifications and formation protocol intensity.
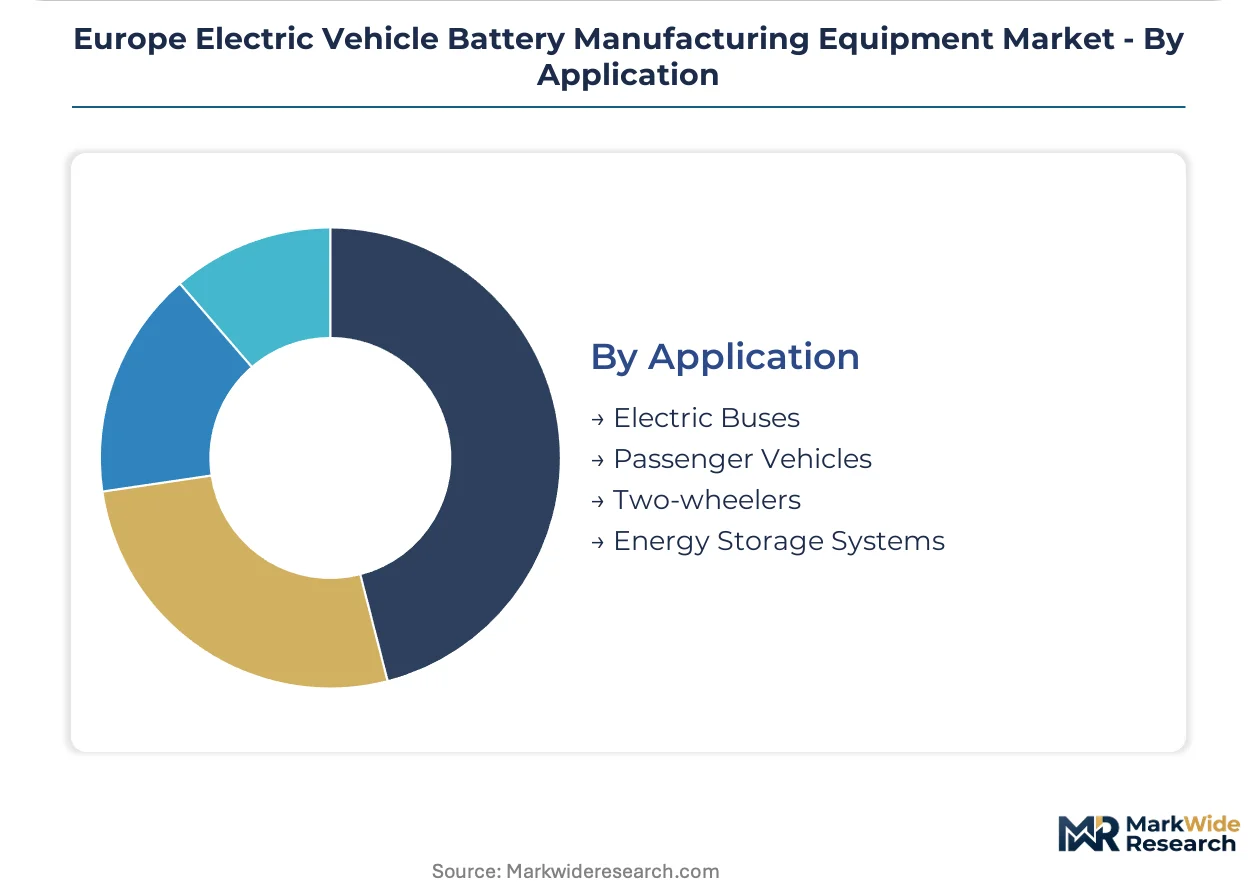
- Passenger Vehicles:High-throughput cylindrical and pouch cell formats calibrated to exceed 200 cells per minute. German and French automobile manufacturers anchor demand, with gigafactory buildouts accelerating across the region.
- Electric Buses:Large-format prismatic cells with extended formation and aging cycles. Municipal fleet electrification programs in France and the Netherlands sustain specialized equipment demand.
- Energy Storage Systems:Grid-scale battery production with distinct thermal management and safety testing protocols.
- Two-wheelers:Compact cell formats with lower capital intensity per production line.
Passenger vehicle scale dominates capex. Electric bus specifications create niche vendor opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive engineering heritage established Europe's battery equipment sector, with precision-tooling traditions migrating from internal combustion engine plants to electrochemical cell fabrication. French and Italian industrial clusters subsequently developed specialized competencies in thermal processing and automation controls.
Germany
Volkswagen PowerCo and Mercedes-Benz battery operations drive concentrated demand for integrated cell production lines. The EU F-Gas Regulation accelerates replacement cycles for thermal management equipment in electrode drying stages. North Rhine-Westphalia hosts Duerr AG and Schuler AG engineering centers supplying coating and press-forming systems to domestic gigafactories.
Poland
LG Energy Solution and SK On facilities generate automated stacking and welding module procurement at scale. ECHA REACH compliance timelines for NMP solvent handling extend equipment qualification cycles. Lower Silesian manufacturing corridors near Wrocław concentrate South Korean cell maker expansion and associated machinery demand.
Hungary
CATL and Samsung SDI expansion around Debrecen creates greenfield demand for module-to-pack assembly lines without legacy retrofit constraints. The EU Green Deal Scope 3 emissions benchmarks shape vendor selection for low-carbon production pathways. Eastern Hungary's industrial zones attract fully integrated line responsibility contracts from Asian battery suppliers.
France
Automotive OEM captive production by Stellantis and Renault anchors demand for high-throughput cylindrical and pouch cell formats. CE marking requirements ensure machinery interoperability across national production networks. Auvergne-Rhône-Alpes research consortia validate dry electrode processing techniques for next-generation thermal systems.
Italy
Sovema Group S.p.A. and specialized automation vendors serve European formation and aging equipment demand from Lombardy engineering bases. The EU AI Act intersects with automated optical inspection modules for high-risk industrial classification. Northern Italian industrial districts supply precision linear motion components to German and Polish gigafactory projects.
Europe Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal processing and validation equipment categories, while standardized cell line configurations compress returns in electrode coating and stacking segments. The vendor base stratifies between diversified industrial conglomerates with automotive heritage and specialized electrochemical equipment pure-plays. Three archetypes dominate: paint-shop automation specialists repurposing coating expertise, heavy machinery fabricators with press-forming scale, and precision thermal processing engineers. Competitive moves concentrate on long-term framework agreements with penalty clauses and compliance-as-a-service bundling for emerging EU AI Act obligations.
Among German diversified industrials, Duerr AG and Schuler AG occupy positions leveraging automotive manufacturing heritage toward battery cell fabrication, while Buhler Holding AG exemplifies the thermal processing specialist archetype with electrode drying and sintering system concentration.
| Leading Market Players |
|---|
| Duerr AG |
| Hitachi Ltd |
| Schuler AG |
| Buhler Holding AG |
| Sovema Group S.p.A. |
| ACEY New Energy Technology |
| IPG Photonics Corporation |
| Xiamen Tmax Battery Equipments Limited |
| Robert Bosch Manufacturing Solutions GmbH |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate price volatility cascades through European battery equipment supply chains, compressing margins for electrode coating system vendors while amplifying procurement leverage for German and French OEMs with captive gigafactory operations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs European equipment procurement, with CE marking and automotive OEM qualification tier separating premium vendors from commodity suppliers. Price differentiation hinges on software-parameter flexibility and after-sales service bundling. Cost compression in standard-tier electrode stacking equipment is intensifying because South Korean battery suppliers are consolidating procurement under framework agreements. Independent cell manufacturers in Poland exhibit highest price sensitivity, while Mercedes-Benz and Volkswagen PowerCo operations prioritize qualification speed over unit economics.
Supply Chain Analysis
Workforce scarcity in precision electrochemical engineering across Germany, Switzerland, and Italy constrains equipment vendor expansion and elongates commissioning timelines for dry electrode processing systems. Supply concentrates in German industrial clusters for thermal processing and Italian precision motion components, with vacuum chamber fabrication anchored in Swiss engineering bases. The supply chain draws from cobalt compound and NMP solvent imports subject to ECHA REACH restriction volatility. Single-source vulnerability pervades high-vacuum linear motion systems. Distribution runs through Tier 1 automotive suppliers assuming integrated line responsibility contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Electric Vehicle Battery Manufacturing Equipment Market compounds steadily as EU Green Deal Scope 3 mandates harden into binding procurement specifications across German and French OEM operations.
For Market Incumbents: Anticipate margin erosion from modular platform standardization by accelerating compliance-as-a-service bundling for EU AI Act obligations on automated inspection systems. Defend position through backward integration into precision linear motion component production, reducing exposure to Swiss single-source bottlenecks. Prioritize long-term framework agreements with penalty clause structures that lock out emerging Asian equipment vendors.
For New Entrants and Emerging Players: The gap between premium CE-marked systems and economy-tier refurbished asset models opens viable entry points in Hungarian and Polish manufacturing corridors where greenfield buildouts lack legacy retrofit constraints. Target module-to-pack assembly line categories where incumbent concentration remains lowest. Pursue qualification partnerships with CATL and Samsung SDI expansion projects around Debrecen as reference-building pathway.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized thermal processing expertise overlaps with drying oven commoditization trends. Frame long-term viability around solid-state pilot scaling trajectories and dry electrode processing validation timelines. Acquisition targets should exhibit captive relationships with BMW Group or Northvolt qualification programs. Monitor ECHA enforcement acceleration on F-Gas Regulation replacement cycles as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Reduces Swiss single-source dependency for vacuum chamber and linear motion systems. |
| Compliance-as-a-Service Bundling | Captures EU AI Act revenue streams from automated optical inspection module classification. |
| Dry Electrode Processing Scale-Up | Validates throughput parity with wet coating for BMW Group and Northvolt pilot lines. |
| Framework Agreement Consolidation | Locks procurement relationships with Volkswagen PowerCo and Mercedes-Benz battery operations. |
| Solid-State Pilot Line Qualification | Positions vendors for sulfide and oxide electrolyte equipment orders from European research consortia. |
Research Methodology
Bottom-up gigafactory capacity modeling reconciled against top-down equipment vendor order book tracking forms the analytical core of this study. Primary interviews with plant engineering directors, OEM battery procurement leads, Tier 1 supplier integration specialists, and ECHA regulatory affairs officers combined with secondary validation against EU Battery Regulation implementation timelines, SEC filings from listed equipment vendors, German federal state investment promotion databases, and customs records for precision machinery trade flows. Triangulation across these sources calibrated segment-level penetration rates.
Historical trendline analysis of cell production line deployment velocities informed the projection framework across the analysis window. Segmentation dimensions modeled include equipment type, cell chemistry format, end-user concentration, and regional manufacturing corridor maturity. CAGRs derived from fitted growth curves applied to disclosed capacity buildout schedules and vendor backlog data. Forecast inputs incorporated EU Green Deal Scope 3 compliance deadlines and F-Gas Regulation replacement cycle acceleration.
Caveats apply where ECHA REACH substance restriction expansions or solid-state chemistry breakthroughs could materially shift the outlook. Forecasts reflect assumptions about German and French OEM captive production timelines and Polish manufacturing corridor expansion continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
France Electric Vehicle Battery Manufacturing Market
EV Batteries
US EV Battery Pack Market
EV Batteries
North America LFP Battery Pack Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Asia-Pacific LFP Battery Pack Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
China Electric Vehicle Battery Materials Market