
 Middle East and Africa Rechargeable Battery Market | 2026-2036
Middle East and Africa Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Rechargeable Battery Market Insights
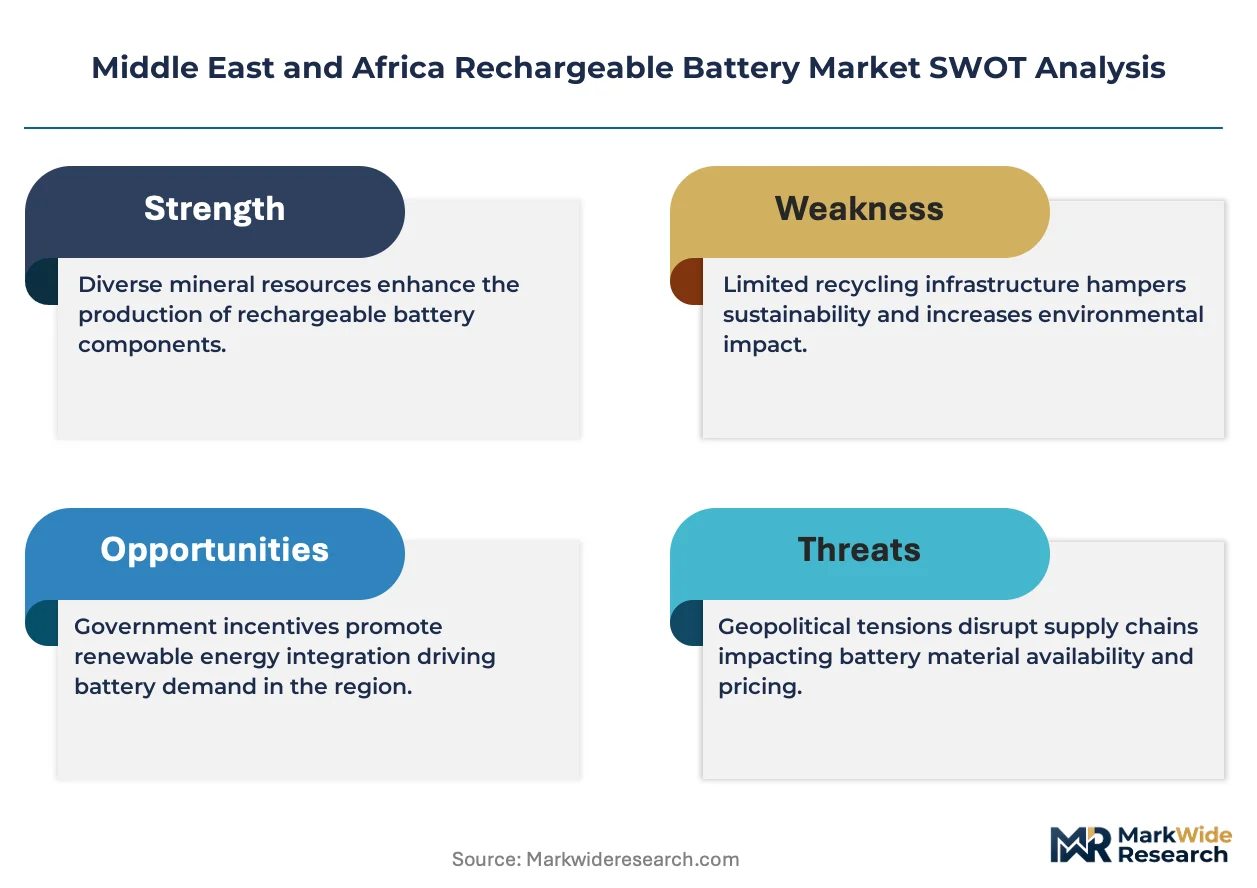
High-cycle lithium iron phosphate chemistry is collapsing the total cost of ownership gap against diesel generators for telecom towers and microgrids across Nigeria and Kenya. BYD Company Ltd leverages its integrated cell-to-pack architecture to dominate utility-scale tenders in Morocco and Egypt. Samsung SDI Co., Ltd. sustains premium positioning through nickel-cobalt-manganese cathode supply agreements with Gulf-based energy developers. LG Energy Solution, Ltd. competes aggressively on cylindrical cell formats for emerging electric two-wheeler assembly plants in Tunisia.
A rechargeable battery stores electrochemical energy through reversible redox reactions, with lithium-ion variants achieving 150-250 Wh/kg energy density and cycle lives exceeding 4,000 charges at 80% depth of discharge; these devices buffer intermittent renewable generation and power electric drivetrains. Lithium-Ion chemistry anchors the value pool given its dominance in grid storage and passenger EV contracts across the Gulf Cooperation Council states. Lead-Aid technology occupies a residual but defensible niche in backup power for banking and hospital infrastructure where capital constraints limit upfront lithium spending. The Stationary deployment category leads order volumes as Saudi Arabia and the UAE tender gigawatt-hour storage projects alongside solar photovoltaic expansions.
South Africa's National Energy Regulator enforces grid connection codes that mandate frequency response capabilities from battery assets, while the UAE's Emirates Authority for Standardization and Metrology certifies thermal runaway containment standards for imported cells. Saudi Arabia's Quality of Life Program and renewable energy localization rules are redirecting procurement toward assembly partners with domestic manufacturing commitments. Stakeholders must monitor how Egypt's new consumer protection regulations on battery warranties and the Gulf's emerging carbon disclosure requirements reshape supplier qualification criteria and contract structures.
Market Dynamics
Declining lithium-ion cell costs and solar-plus-storage procurement mandates across the Gulf Cooperation Council states are compressing payback periods for grid-scale battery assets below five years, redirecting capital from conventional peaking plants.
Growth Catalysts
- South Africa's Renewable Energy Independent Power Producer Procurement Programme:Gigawatt-hour storage tenders bundled with solar photovoltaic capacity create guaranteed offtake for battery developers.
- Telecom tower electrification:High-cycle lithium iron phosphate chemistry collapses total cost of ownership against diesel generators across Nigeria and Kenya's off-grid tower portfolios.
- Electric mobility infrastructure:The UAE and Morocco are tendering charging networks and battery swapping stations for two-wheeler and passenger vehicle fleets.
Market Restraints
- Cathode material cost volatility:Nickel and cobalt price swings from Congolese and Indonesian supply concentrate margin risk for nickel-cobalt-manganese cell producers.
- Import dependency concentration:Cell manufacturing capacity clusters in East Asia, exposing Middle Eastern developers to shipping cost spikes and currency mismatch.
- Thermal runaway containment standards:The UAE's Emirates Authority for Standardization and Metrology certification requirements extend qualification timelines for new suppliers.
Strategic Opportunities
- Egypt's consumer protection regulations:Mandatory battery warranty disclosures create first-mover advantage for suppliers with established service networks.
- Grid-forming inverter convergence:Integration of battery storage with synthetic inertia capabilities opens frequency response revenue streams in Saudi Arabia's tendering rounds.
- Commercial rooftop solar-plus-storage:Underpenetrated C&I segments in Tunisia and Jordan offer direct sales channels bypassing utility procurement cycles.
Industry Challenges
- Battery management system firmware integration:Legacy SCADA architectures in South African municipal grids require costly middleware development for seamless dispatch.
- Cell-to-pack thermal engineering talent:Shortage of specialists capable of designing passive propagation resistance slows localization efforts in Morocco and Egypt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Rechargeable Battery Market |
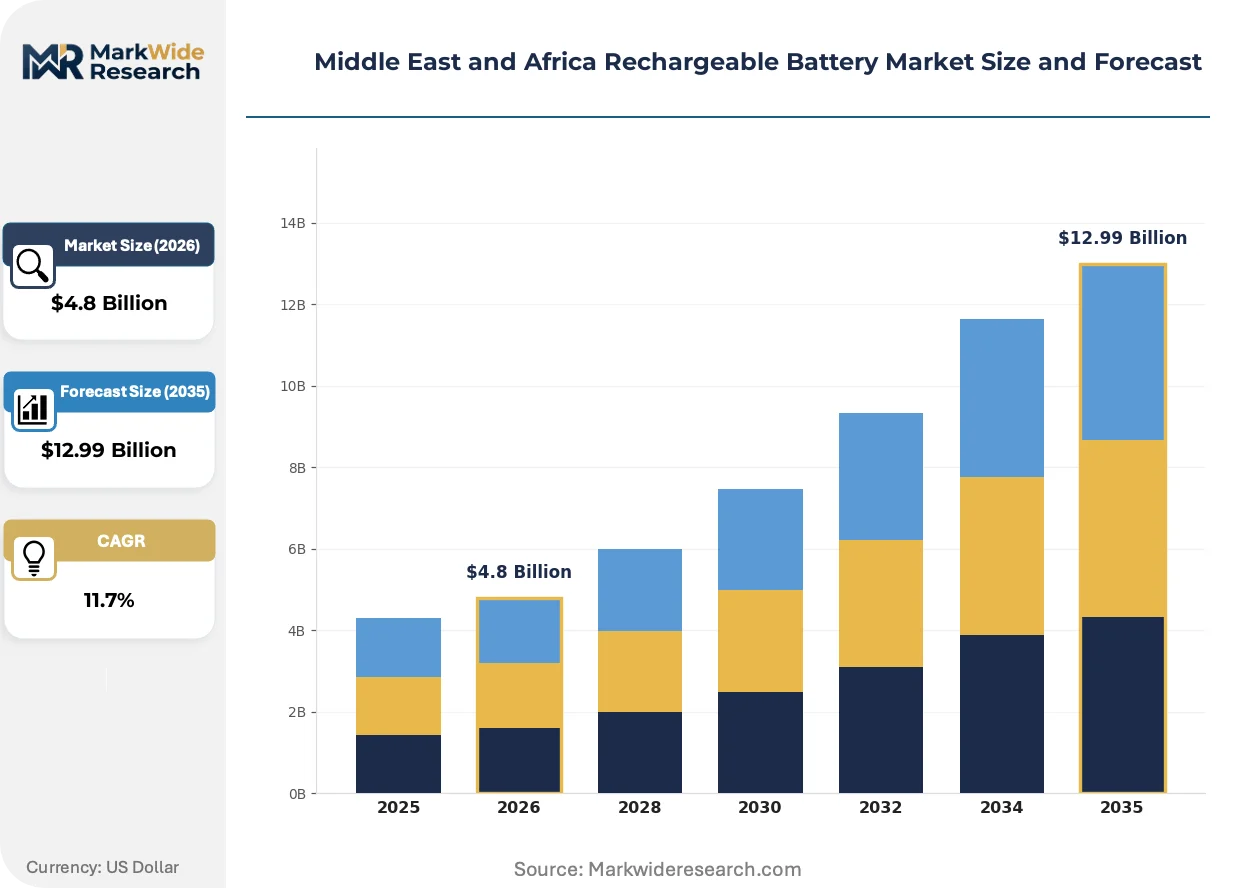
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Nickel-Cadmium End User: Consumer Electronics, Automotive, Industrial, Renewable Energy Deployment: Stationary, Portable, Mobile, Off-Grid Technology: Solid-State, Flow Battery, Lithium Polymer, Advanced Lead-Acid |
| Companies Covered | BYD Company Ltd, EnerSys, Panasonic Holdings Corporation, Exide Industries Ltd, Duracell Inc., Samsung SDI Co., Ltd., LG Energy Solution, Ltd., Contemporary Amperex Technology Co. Limited, Middle East Battery Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Rechargeable Battery Market Trends and Innovations
Technology roadmaps across the Middle East and Africa are diverging between premium nickel-cobalt-manganese chemistries for passenger electric vehicles and cost-optimized lithium iron phosphate systems for stationary storage, with regulatory pressure accelerating both tracks simultaneously.
Lithium iron phosphate cathode chemistry is bifurcating the stationary storage value pool. The material delivers 4,000-plus cycle life at 80% depth of discharge, enabling decade-long service contracts. Saudi gigawatt-hour solar parks and UAE commercial microgrids are adopting it at scale for frequency regulation and peak shaving. This chemistry is bifurcating procurement teams into automotive-grade specification holders and utility-grade cost optimizers with incompatible supplier qualification criteria.
South Africa's National Energy Regulator enforces grid connection codes mandating frequency response capabilities from battery assets. The rules require sub-second reaction times and sustained output duration minimums. Developers in the Western Cape and Gauteng provinces are retrofitting power conversion systems and control software to comply, with non-compliant assets facing curtailment penalties.
Direct procurement from cell manufacturers is displacing distributor intermediaries for utility-scale tenders. Saudi Arabia's Quality of Life Program and renewable energy localization rules favor assembly partners with domestic manufacturing commitments. Developers in Riyadh and Jeddah are negotiating long-term offtake agreements directly with cell producers, compressing margin pools for regional trading houses that previously dominated battery import channels.
Middle East and Africa Rechargeable Battery Market Segmentation
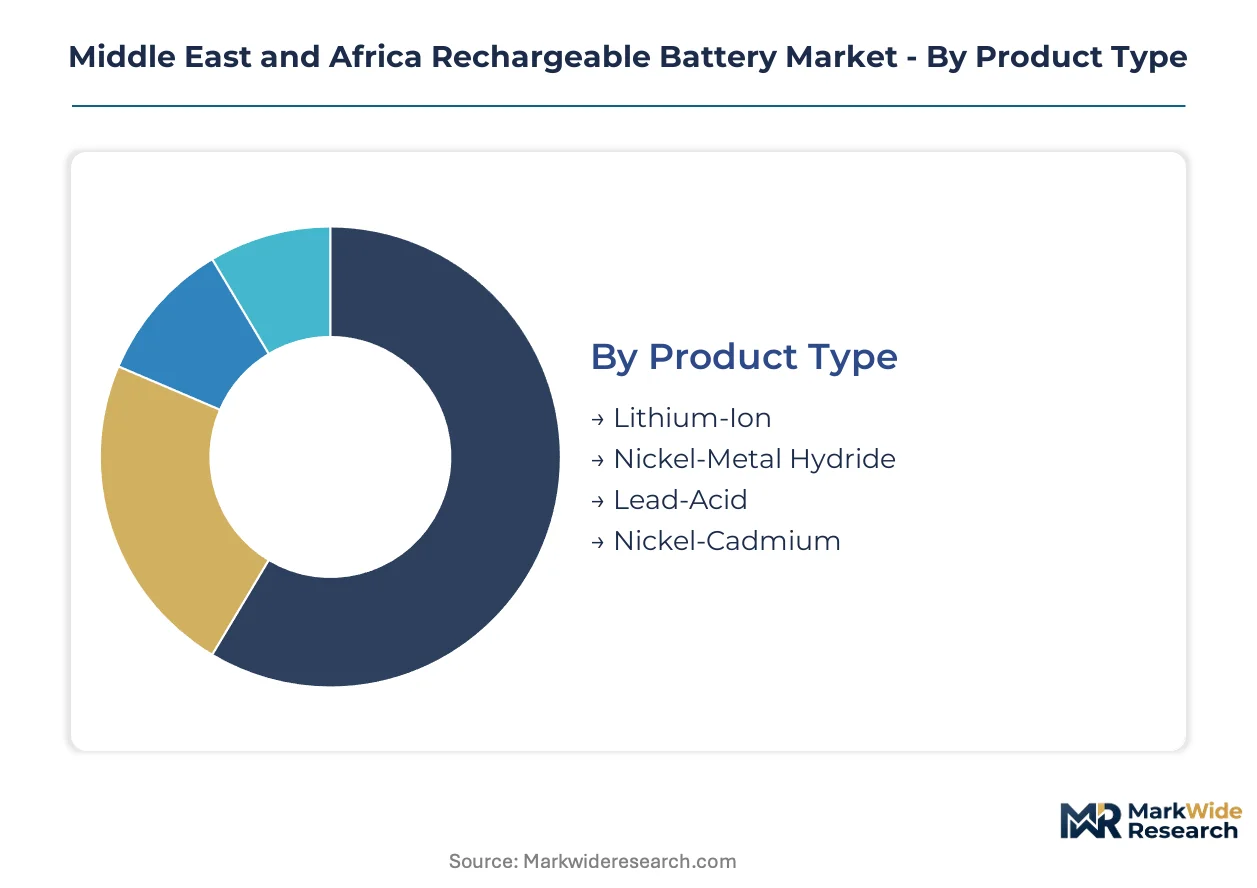
Segmentation reveals how procurement channels bifurcate between utility-scale tenders and distributed commercial sales across the Middle East and Africa. Understanding these flows helps suppliers align certification investments with actual revenue pathways rather than theoretical addressable markets.
Product Type:
Lithium-Ion chemistry moves predominantly through direct manufacturer-to-developer contracts for gigawatt-hour solar parks, while Lead-Acid retains distributor networks for backup power in capital-constrained segments.
- Lithium-Ion:Nickel-cobalt-manganese and lithium iron phosphate variants achieve 150-250 Wh/kg energy density with cycle lives exceeding 4,000 charges. Demand concentrates in Saudi Arabia and UAE grid-scale storage tenders where frequency response mandates require sub-second reaction capabilities.
- Lead-Acid:Advanced valve-regulated designs deliver reliable backup power at lower upfront cost. Banking and hospital infrastructure across Nigeria and Kenya procure through regional distributors where lithium capital constraints persist.
- Nickel-Metal Hydride:Mature chemistry serves hybrid vehicle auxiliary systems and industrial forklifts in South African manufacturing zones.
- Nickel-Cadmium:Aviation and rail signaling applications in Egypt and Morocco sustain residual demand despite environmental handling restrictions.
Lithium-Ion dominates installed base in utility-scale deployments. Lead-Acid is where price-sensitive backup expansion concentrates.
End User:
Automotive and renewable energy segments command premium pricing through performance-based specifications, while consumer electronics and industrial buyers negotiate on total cost of ownership metrics.
- Renewable Energy:Grid-scale battery parks buffer intermittent solar generation across the Gulf Cooperation Council states. Saudi Arabia's tendering rounds bundle gigawatt-hour storage with photovoltaic capacity, creating multi-year offtake visibility.
- Automotive:Passenger electric vehicle contracts specify nickel-cobalt-manganese cathodes for energy density, while two-wheeler assembly in Tunisia adopts cylindrical lithium-ion formats for cost optimization.
- Industrial:Material handling equipment and telecom tower operators in Nigeria prioritize cycle life metrics over energy density.
- Consumer Electronics:Smartphone and laptop manufacturers in Morocco source lithium polymer cells through established Asian supply chains.
Renewable Energy commands the steepest expansion trajectory as solar-plus-storage procurement accelerates. Automotive maintains premium pricing power through chemistry differentiation.
Deployment:
Stationary assets generate recurring revenue through grid services contracts, while portable and mobile segments compete on unit economics and replacement cycle frequency.
- Stationary:Grid-forming inverters with synthetic inertia capabilities open frequency response revenue streams. South Africa's National Energy Regulator enforces connection codes mandating sustained output duration minimums.
- Off-Grid:Solar-plus-storage microgrids serve rural electrification across Kenya and Tanzania where distribution infrastructure remains underdeveloped.
- Portable:Consumer power banks and professional tools populate retail channels in UAE and South African urban centers.
- Mobile:Electric two-wheeler battery swapping stations in Morocco require rapid-exchange form factors and standardized connector protocols.
Stationary deployment anchors revenue stability through long-term service contracts. Off-Grid represents the fastest-climbing volume opportunity as rural electrification programs scale.
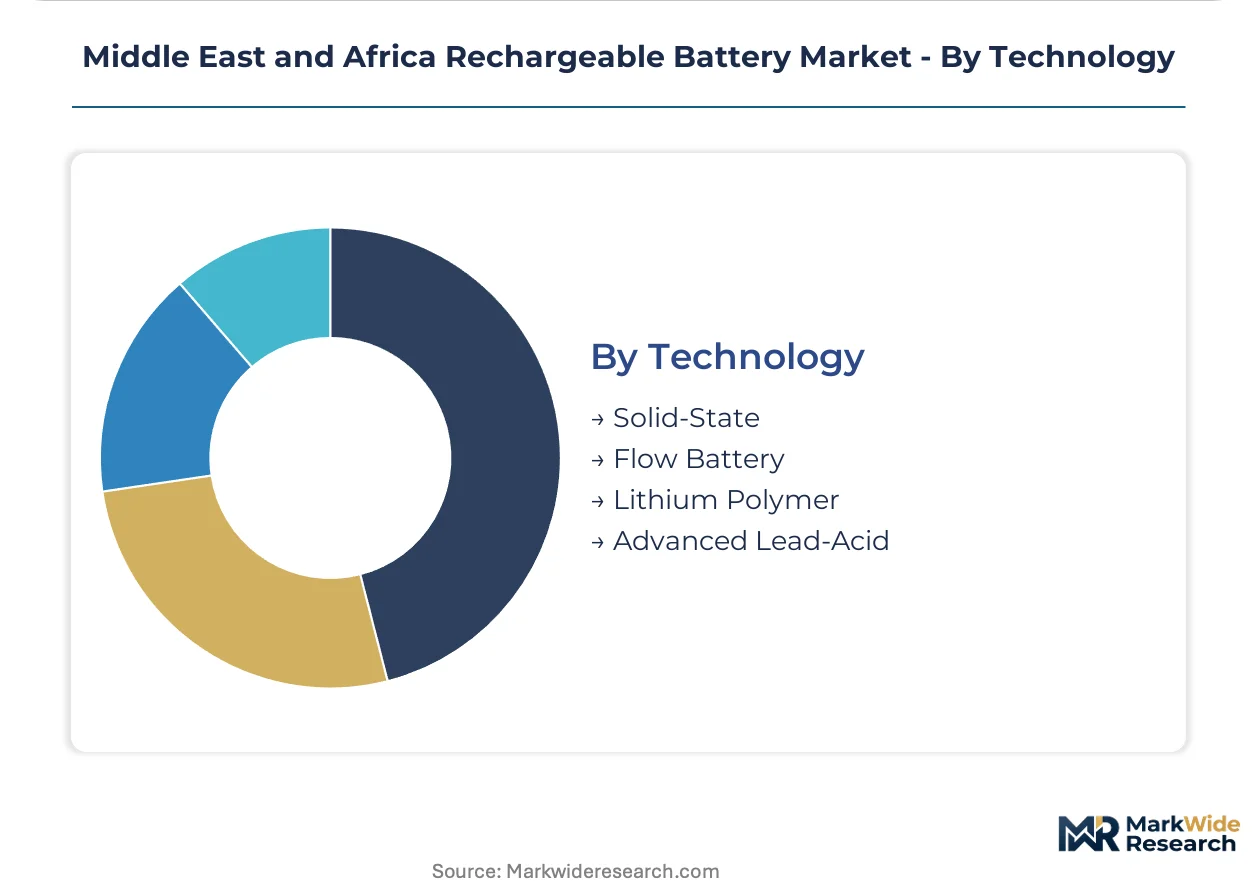
Technology:
Solid-state and flow battery technologies attract venture financing for next-generation positioning, while lithium polymer and advanced lead-acid defend incumbent revenue through manufacturing scale.
- Solid-State:Ceramic electrolyte architectures promise enhanced thermal stability and energy density. Early pilot deployments in UAE luxury electric vehicle segments test manufacturing scalability.
- Flow Battery:Vanadium redox systems deliver unlimited cycle life for daily cycling applications. South African mining operations evaluate long-duration storage for off-grid power stability.
- Lithium Polymer:Pouch cell formats enable flexible form factors for consumer electronics and medical devices in Egyptian assembly plants.
- Advanced Lead-Acid:Carbon-enhanced negative electrodes extend cycle life in partial state-of-charge operation. Telecom tower operators in Kenya adopt these for diesel displacement.
Advanced Lead-Acid dominates near-term installed base in price-sensitive backup applications. Solid-State is where technology leadership investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing capacity clusters in East Asia, forcing Middle Eastern and African developers to navigate shipping cost volatility and currency mismatch when sourcing lithium-ion systems for grid-scale storage projects.
South Africa
Telecom tower electrification and mining sector microgrids drive lithium iron phosphate procurement across the Western Cape and Gauteng provinces. The National Energy Regulator enforces grid connection codes mandating sub-second frequency response capabilities from battery assets. Developers in Johannesburg and Cape Town are retrofitting power conversion systems to comply with sustained output duration minimums or face curtailment penalties.
United Arab Emirates
Commercial rooftop solar-plus-storage installations and passenger electric vehicle charging networks accelerate demand in Dubai and Abu Dhabi. The Emirates Authority for Standardization and Metrology certifies thermal runaway containment standards for imported cells, extending qualification timelines for new suppliers. Gigawatt-hour storage tenders bundled with photovoltaic capacity create multi-year offtake visibility for battery developers in the Emirates.
Saudi Arabia
Grid-scale battery parks buffering intermittent solar generation dominate procurement in Riyadh and Jeddah. The Quality of Life Program and renewable energy localization rules redirect procurement toward assembly partners with domestic manufacturing commitments. Developers are negotiating long-term offtake agreements directly with cell producers, compressing margin pools for regional trading houses that previously dominated import channels.
Morocco
Electric two-wheeler assembly plants and battery swapping station networks drive cylindrical lithium-ion format demand in Casablanca and Tangier. The government tenders charging infrastructure for passenger vehicle fleets alongside renewable energy expansion programs. BYD Company Ltd leverages integrated cell-to-pack architecture to dominate utility-scale tenders while local assembly partnerships satisfy domestic content requirements.
Egypt
New consumer protection regulations on battery warranties and telecom tower backup power expansion reshape supplier qualification criteria in Cairo and Alexandria. Mandatory warranty disclosures create first-mover advantage for suppliers with established service networks. Assembly plants in the Suez Canal Economic Zone evaluate lithium polymer pouch cells for consumer electronics and medical device manufacturing.
Middle East and Africa Rechargeable Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa rechargeable battery market. Integrated Asian cell manufacturers with captive cathode supply chains dominate utility-scale tenders through direct procurement relationships, while regional trading houses and local assemblers defend residual positions in price-sensitive backup power segments. Three archetypes define competitive positioning: integrated cell-to-pack specialists, chemistry-agnostic system integrators, and distributor-dependent local assemblers. Capacity expansion through domestic manufacturing commitments and strategic partnerships with state-backed renewable energy programs represent the dominant competitive moves reshaping market access.
Within the integrated manufacturing tier, BYD Company Ltd and Contemporary Amperex Technology Co. Limited anchor direct procurement channels for gigawatt-hour storage projects across the Gulf Cooperation Council states. Samsung SDI Co., Ltd. occupies a position exemplifying premium chemistry specialization through nickel-cobalt-manganese supply relationships with energy developers. These three entities represent the technology-credential archetype competing against cost-optimized lithium iron phosphate specialists for stationary storage contracts and electric mobility infrastructure tenders.
| Leading Market Players |
|---|
| BYD Company Ltd |
| EnerSys |
| Panasonic Holdings Corporation |
| Exide Industries Ltd |
| Duracell Inc. |
| Samsung SDI Co., Ltd. |
| LG Energy Solution, Ltd. |
| Contemporary Amperex Technology Co. Limited |
| Middle East Battery Company |
| Others |
Pricing and Supply Chain Analysis
The UAE's Emirates Authority for Standardization and Metrology certification requirements for thermal runaway containment standards simultaneously gate supplier qualification and stratify pricing tiers across imported lithium-ion cell portfolios. Battery developers in Dubai and Abu Dhabi face extended qualification timelines that compress margins for new market entrants while insulating incumbent suppliers with established certification records.
Pricing Analysis
The Emirates Authority for Standardization and Metrology dictates the pricing tier structure through mandatory thermal containment testing that separates automotive-grade specification holders from utility-grade cost optimizers. Three-tier pricing structure across premium, standard, and economy levels reflects cathode chemistry differentiation, with nickel-cobalt-manganese cells commanding brand premiums against lithium iron phosphate alternatives. Pricing pressure stems from direct procurement trends as Saudi developers negotiate long-term offtake agreements with East Asian cell manufacturers, bypassing regional distributor markups. Telecom tower operators in Nigeria exhibit highest price sensitivity due to diesel displacement economics, while Gulf utility-scale tenders demonstrate lowest sensitivity given frequency response revenue guarantees.
Supply Chain Analysis
Red Sea shipping lane congestion and container availability constraints at Jeddah and Jebel Ali ports inflate inbound logistics costs for Middle Eastern battery developers sourcing from East Asian manufacturing clusters. Cell production concentrates in China, South Korea, and Japan, with cathode active material processing anchored in Indonesian nickel and Congolese cobalt supply chains. Raw material dependencies span lithium carbonate from Chilean and Australian brine operations, graphite anodes from Chinese synthetic production, and electrolyte salts from Japanese chemical specialists. Single-source vulnerability concentrates in cathode precursor refining capacity, exposing margin risk to nickel and cobalt price volatility. Distribution runs through direct manufacturer-to-developer contracts for gigawatt-hour tenders, while regional trading houses retain residual channels for lead-acid backup power in capital-constrained segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in underpenetrated commercial and industrial solar-plus-storage segments where standardized product architectures have not yet consolidated procurement patterns. Telecom tower electrification and rural microgrid deployment across East Africa create addressable niches outside utility tender cycles.
For Market Incumbents: Secure frequency response capability certification ahead of South Africa's National Energy Regulator connection code enforcement deadlines. Deepen backward integration into cathode active material supply through offtake agreements with Indonesian nickel and Congolese cobalt processors, insulating margin positions against raw material cost volatility from emerging chemistry-agnostic system integrators. For New Entrants and Emerging Players: Anchor in Tunisia's electric two-wheeler assembly corridor where cylindrical lithium-ion format demand outpaces established supplier presence. Target Jordan's underpenetrated commercial rooftop solar-plus-storage segment through direct sales channels bypassing utility procurement cycles, leveraging standardized battery management system firmware to reduce middleware development costs for legacy SCADA integration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across lithium iron phosphate stationary storage manufacturing as cell-to-pack architectures reduce assembly steps and equipment requirements. Long-term viability favors assembly partners with domestic manufacturing commitments in Saudi Arabia and Morocco that satisfy localization rules while maintaining technology licensing relationships with East Asian cell producers. Monitor Egypt's consumer protection regulation enforcement on mandatory warranty disclosures as inflection indicator for service network valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Adoption | BYD's integrated manufacturing approach dominates Moroccan utility tenders through cost-optimized thermal management. |
| Domestic Manufacturing Commitment | Saudi Arabia's Quality of Life Program redirects procurement toward assembly partners with localized production facilities. |
| Frequency Response Capability Certification | South Africa's National Energy Regulator mandates sub-second reaction times for grid connection code compliance. |
| Cathode Supply Agreement | Samsung SDI sustains premium positioning through nickel-cobalt-manganese relationships with Gulf energy developers. |
| Battery Swapping Infrastructure | Morocco's charging network tenders for two-wheeler fleets require rapid-exchange form factors and standardized connectors. |
Research Methodology
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base for this analysis. Primary interviews with procurement leads at Saudi and UAE renewable energy developers combined with secondary validation from IEA reports, EIA data, FERC filings, and project development databases. Bottom-up capacity installation tracking across gigawatt-hour storage tenders triangulated against top-down renewable energy procurement mandate analysis.
Sensitivity analysis tested forecast robustness across alternative lithium-ion cell cost decline trajectories and solar photovoltaic capacity expansion scenarios. Segmentation dimensions modeled include product chemistry, end-use application, deployment configuration, and technology maturity across the projection horizon. CAGRs derived from installed base growth rates and replacement cycle frequencies, with inputs from cathode material price elasticity coefficients and grid connection code enforcement timelines.
Decision-makers should treat outputs as directional under base assumptions of continued lithium-ion cost decline and Gulf Cooperation Council solar-plus-storage procurement mandate expansion; material deviation would warrant model refresh. Forecasts reflect assumptions regarding nickel and cobalt supply concentration, shipping cost normalization, and regulatory enforcement consistency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Middle East and Africa SLI Battery Market
Batteries
Sweden Rechargeable Battery Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
Stretchable Battery Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
SLI Battery Market
Batteries
Wide Temperature Battery Market
Batteries
Liquid Metal Battery Market
Batteries
United States Household Battery Market
Batteries
Norway Rechargeable Battery Market
Batteries
Submarine Batteries Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
Japan Rechargeable Battery Market
Batteries
Nickel-Based Battery Charger Market
Batteries
India Micro Batteries Market
Batteries
Drone Lithium Battery Charger Market