
 Spain Organic Food Market | 2026-2036
Spain Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Organic Food Market Insights
The EU Green Deal is pivoting Spanish agricultural policy toward regenerative practices and reduced chemical inputs. Hipp leverages its infant nutrition specialization to anchor premium shelf positions in Iberian retail channels. Smileat competes through direct-to-parent digital subscriptions for organic baby food. Groots differentiates with vertical farming operations supplying pesticide-free leafy greens to Barcelona restaurants.
Organic food comprises agricultural products cultivated without synthetic pesticides, genetically modified organisms, or artificial fertilizers, certified under EU organic standards requiring minimum 95% organic ingredients in processed goods. Fruits and vegetables dominate volume throughput due to Spain's Mediterranean growing climate and established export infrastructure. Dairy commands margin concentration through artisan cheese and yogurt value-addition. Online Retail captures the fastest expansion trajectory as subscription models and quick-commerce platforms reduce price premiums versus conventional channels.
Spain's Ministry of Agriculture enforces EU organic regulations through the CAECV (Comité de Agricultura Ecológica de la Comunidad Valenciana) and equivalent regional bodies, mandating traceability from farm to retail shelf. EFSA guidelines on pesticide residue thresholds shape import acceptance criteria for non-EU organic suppliers. Stakeholders must monitor evolving EU organic logo enforcement and regional subsidy reallocations under the Common Agricultural Policy reform to secure compliant supply positions.
Market Dynamics
The EU Green Deal is redirecting Spanish agricultural subsidies toward regenerative farming, tightening organic certification compliance through regional enforcement bodies and reshaping procurement relationships between cooperatives and retail chains.
Growth Catalysts
- EU Green Deal agricultural subsidies:Spain's Ministry of Agriculture channels CAP payments toward organic conversion, lowering transition costs for Andalusian olive growers and Extremaduran livestock cooperatives.
- Catalonia's per-capita consumption premium:Barcelona's metropolitan demand density supports dedicated organic distribution centers, reducing last-mile logistics costs for fresh produce.
- Blockchain traceability platforms:CAECV-mandated digital documentation systems are compressing certification verification timelines from farm to retail shelf.
Market Restraints
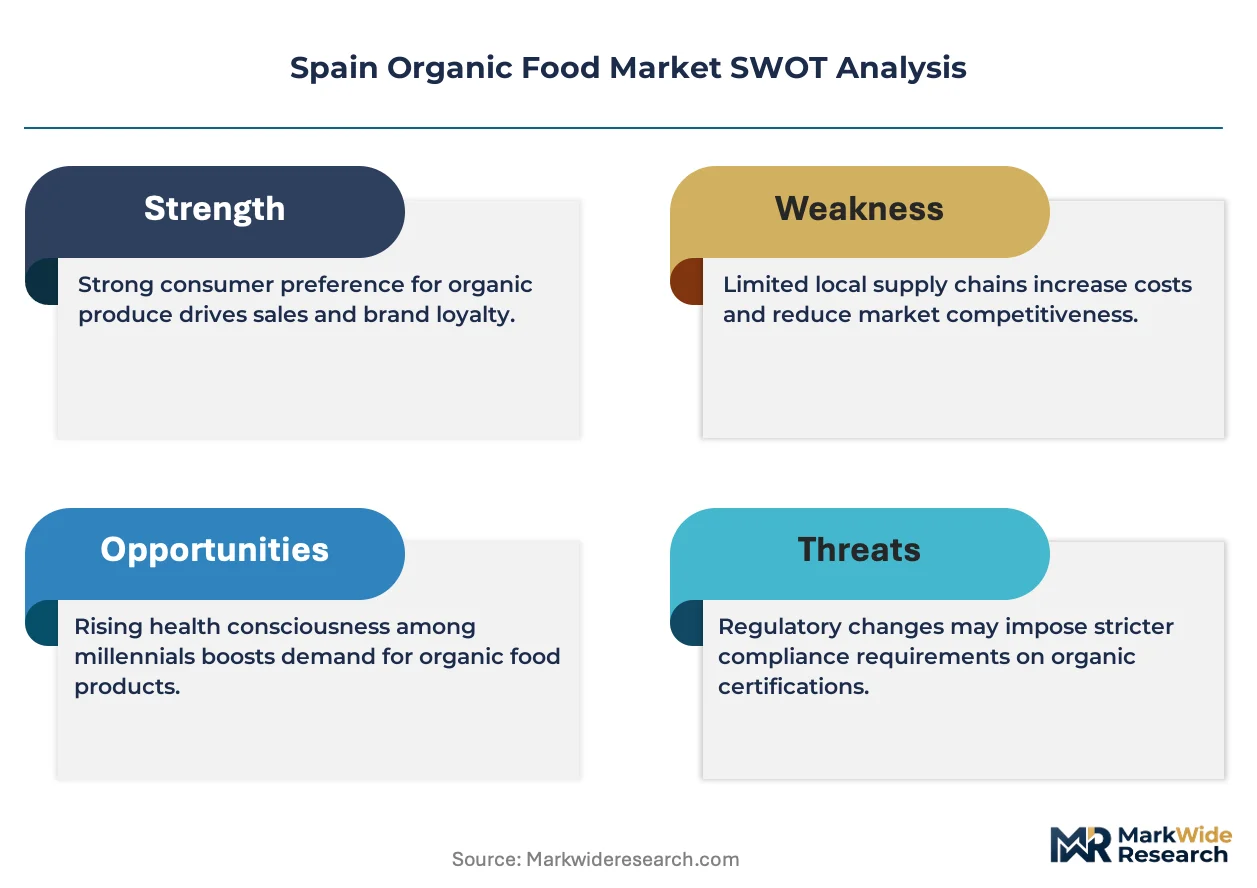
- Organic input cost volatility:Approved fertilizer and non-synthetic pest management supplies concentrate among Dutch and German specialty chemical suppliers, exposing Spanish growers to euro-denominated price swings.
- Valencian citrus supply concentration:CAECV-certified orange and mandarin production clusters in Castellón province, creating weather-dependent volume risk for juice processors.
- Conventional price substitution:Discount retail chains in Madrid and Barcelona metro areas capture price-sensitive households with private-label conventional produce.
Strategic Opportunities
- Basque Country institutional procurement:San Sebastián and Bilbao school district feeding programs mandate organic ingredient minimums, creating contracted offtake for regional dairy cooperatives.
- Quick-commerce channel expansion:Barcelona-based rapid delivery platforms are building dark-store networks dedicated to fresh organic produce, bypassing traditional supermarket slotting fees.
- Common Agricultural Policy eco-scheme payments:2023-2027 CAP tranche increases per-hectare organic premiums, accelerating conversion in underpenetrated Castilla-La Mancha cereal zones.
Industry Challenges
- CAECV certification timeline compression:Three-year conversion periods for permanent crops delay revenue recognition for new almond and vineyard entrants.
- Cooperative management capability gaps:Smallholder associations in Galicia and Asturias lack financial planning expertise to navigate EU organic logo compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Organic Food Market |
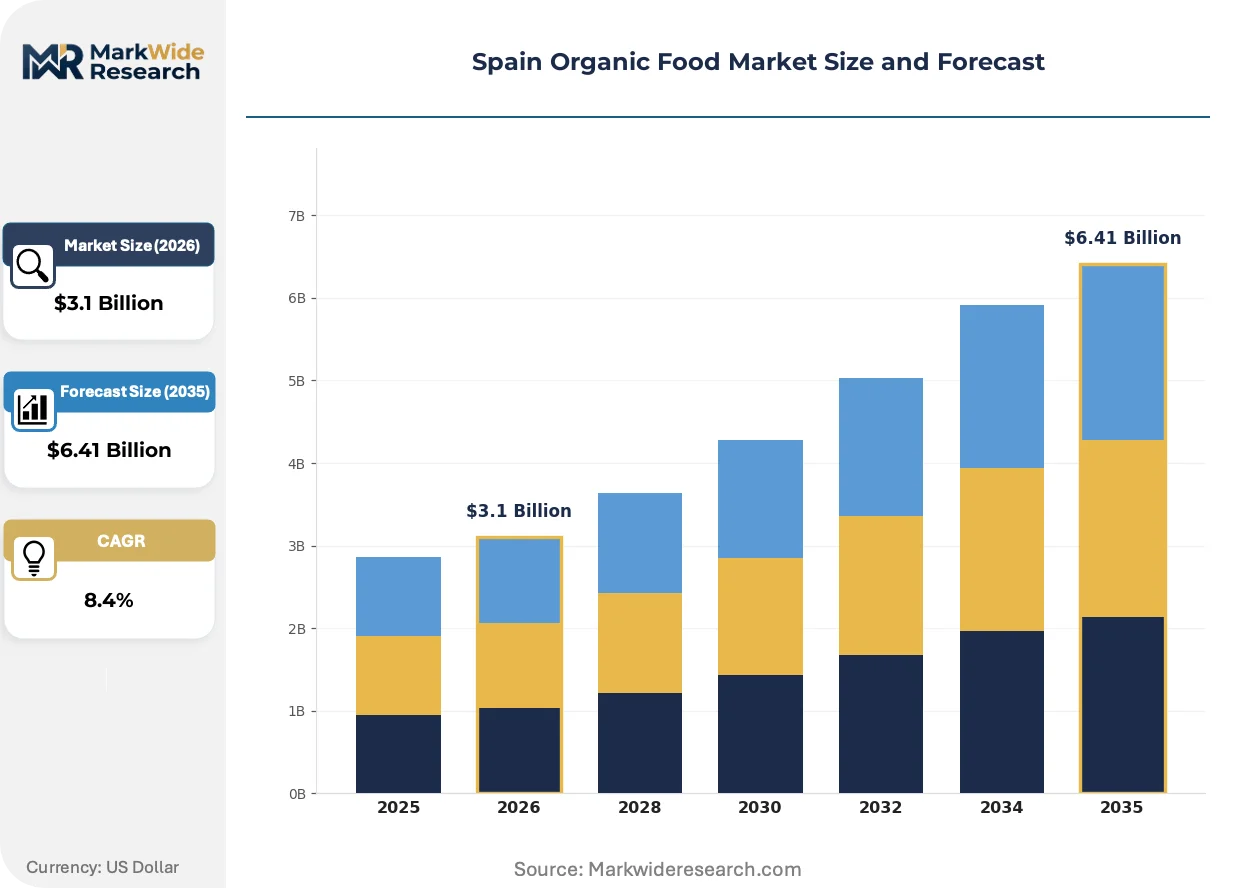
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy, Grains Distribution Channel: Supermarkets, Farmers' Markets, Online Retail, Health Stores Customer Type: Health-Conscious Consumers, Families, Vegetarians, Organic Enthusiasts Price Tier: Premium, Mid-range, Discounted, Organic Bundles |
| Companies Covered | Alimentaria Peñasanta SA, Smileat, East West Tea Co LLC, FARM4GLOBE, Biofood Network, Otsuka Holdings Co Ltd, Groots, Green in Blue, Hipp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Organic Food Market Trends and Innovations
Spanish organic supply chains are digitizing traceability infrastructure while retail formats fragment across quick-commerce, subscription boxes, and specialized supermarket formats, compressing traditional wholesale intermediation.
Precision fermentation for organic-compliant dairy alternatives is integrating into Barcelona food-tech clusters, enabling whey and casein replication without livestock methane footprints. Local ingredient suppliers are piloting enzymatic processes at pilot scale. This technology is integrating into R&D roadmaps of major Iberian dairy processors seeking extended shelf-life organic yogurt lines.
EFSA pesticide residue threshold enforcement is tightening import acceptance for non-EU organic suppliers, particularly Moroccan citrus and Argentinian wine entering Valencia and Barcelona ports. Spanish border inspection posts are expanding laboratory testing capacity. Andalusian organic avocado importers are diversifying toward certified Colombian and Peruvian origins to reduce rejection risk.
Subscription-based direct-to-parent organic baby food models are displacing conventional retail stocking in Madrid and Barcelona metropolitan zones. Digital-native entrants bypass supermarket slotting fees through recurring revenue relationships. Young professional households in Catalonia display highest adoption velocity for weekly curated organic produce boxes.
Spain Organic Food Market Segmentation
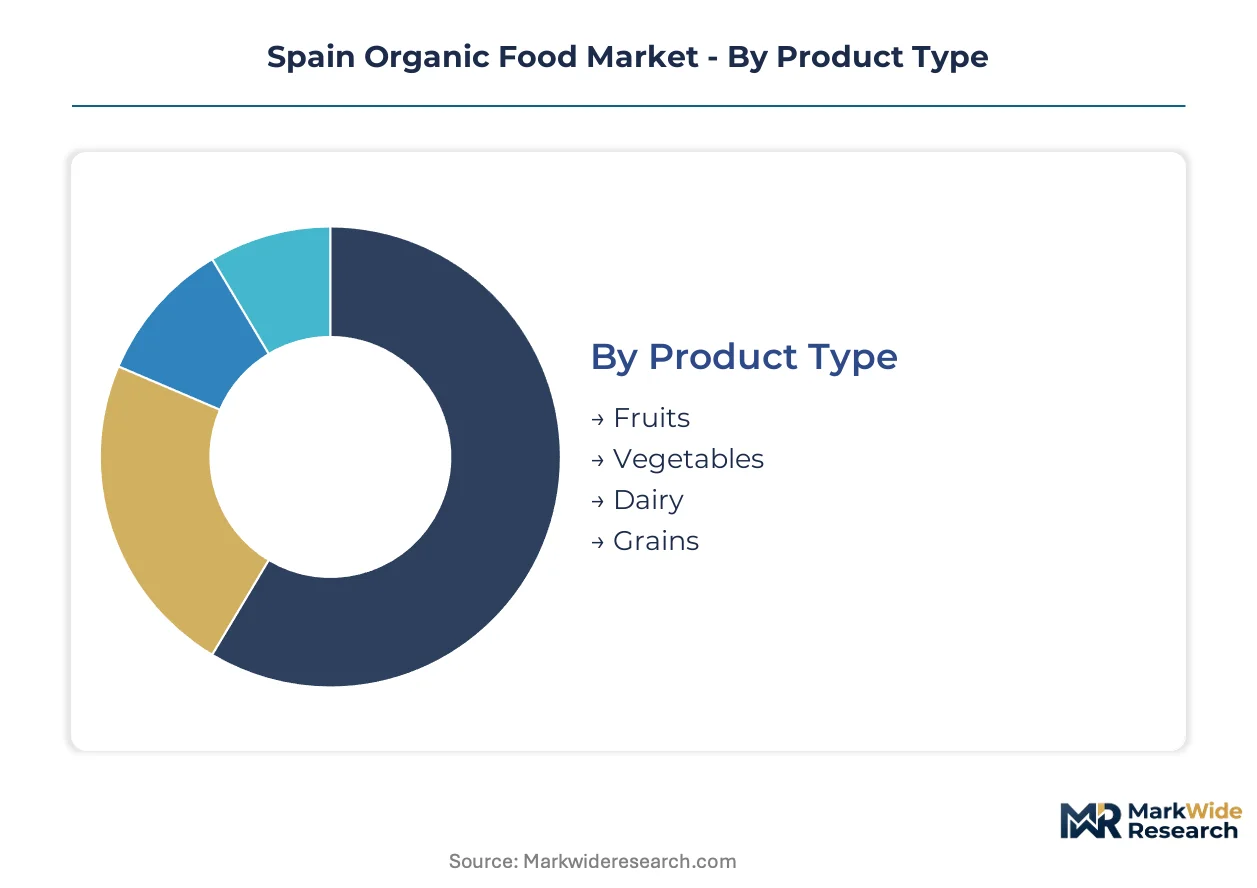
Organic food segmentation in Spain reflects divergent procurement behaviors across retail formats and household priorities. Channel selection and price sensitivity fragment the addressable market into distinct competitive arenas with separate margin profiles.
Product Type:
Buyers in this category differentiate by freshness requirements and processing tolerance, with Mediterranean climate advantages shaping regional supply concentration.
- Fruits:Citrus and stone fruits dominate volume through Valencian and Murcian growing belts. CAECV-certified orange exports to northern Europe subsidize domestic retail pricing. Weather volatility in Castellón province concentrates supply risk for juice processors.
- Vegetables:Leafy greens and tomatoes command the steepest expansion trajectory through Barcelona quick-commerce channels. Groots supplies pesticide-free produce to restaurant clusters via vertical farming operations. Greenhouse production in Almería extends seasonal availability.
- Dairy:Artisan cheese and yogurt value-addition captures margin concentration in Basque Country cooperatives.
- Grains:Cereal production in Castilla-La Mancha accelerates conversion under CAP eco-scheme payments.
Volume sits with Fruits; growth tilts toward Vegetables.
Distribution Channel:
Channel economics separate by slotting fee burden and last-mile cost structure, with digital-native formats compressing traditional wholesale margins.
- Supermarkets:Dedicated organic shelf space expands across Madrid, Barcelona, and Valencia chains. Slotting fees and promotional calendars favor established suppliers with multi-SKU portfolios. Private-label conventional produce creates price-floor pressure.
- Online Retail:Subscription models and quick-commerce platforms reduce price premiums versus conventional channels. Dark-store networks in Barcelona bypass supermarket intermediation. Young professional households in Catalonia drive weekly curated box adoption.
- Farmers' Markets:Direct producer relationships dominate in San Sebastián and Bilbao metropolitan zones.
- Health Stores:Specialized retail concentrates in affluent Barcelona neighborhoods with supplement cross-selling.
Supermarkets anchor current throughput; Online Retail climbs the fastest.
Customer Type:
Household composition and dietary restriction severity determine purchase frequency and basket composition.
- Families:Infant nutrition specialization anchors premium positioning through Iberian retail channels. Smileat competes via direct-to-parent digital subscriptions bypassing conventional stocking.
- Health-Conscious Consumers:Per-capita consumption exceeds national averages in Catalonia and Basque Country. Barcelona metropolitan demand density supports dedicated organic distribution centers.
- Vegetarians:Plant-forward diets concentrate in Madrid and Barcelona urban cores.
- Organic Enthusiasts:Certification literacy drives CAECV logo preference and traceability platform engagement.
Families represent the revenue base; Health-Conscious Consumers gain share fastest.
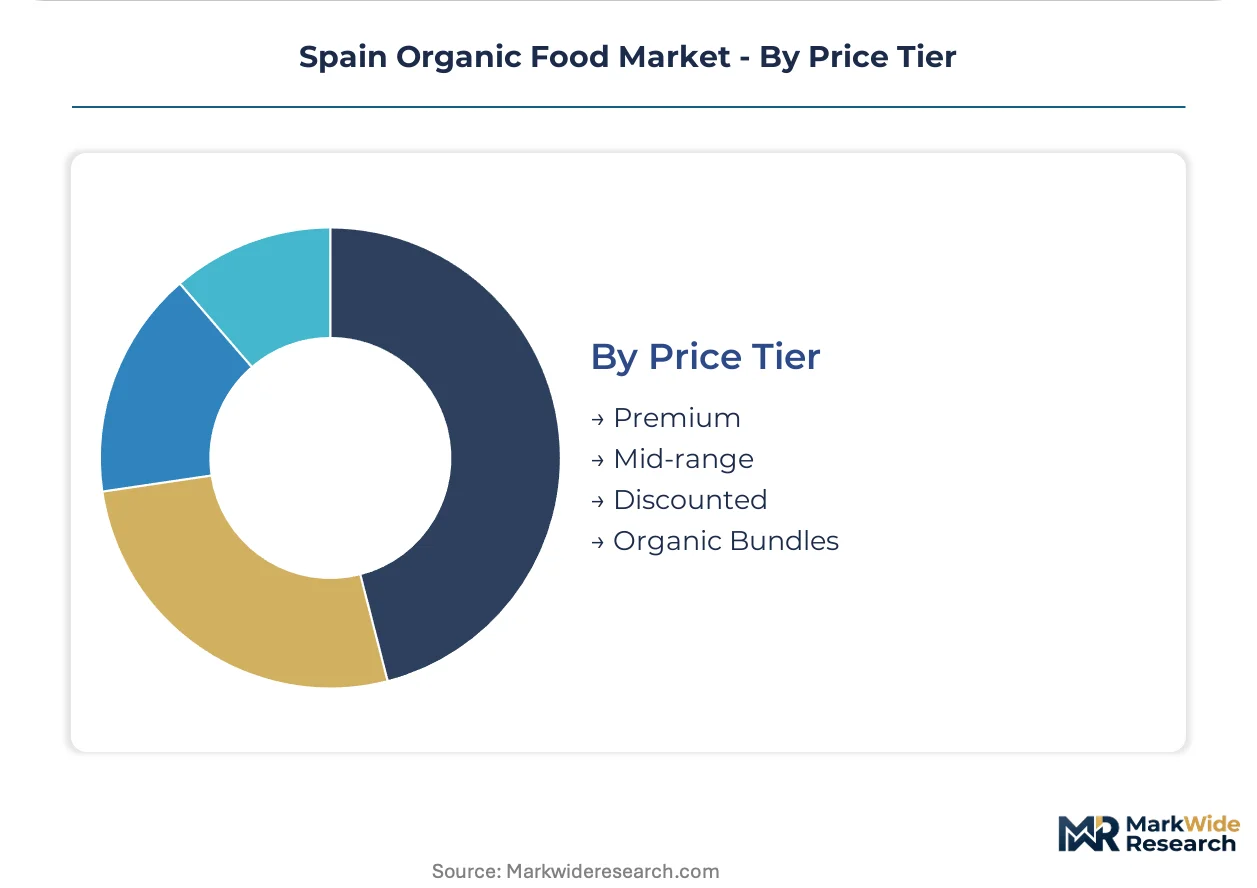
Price Tier:
Willingness-to-pay stratifies by income bracket and perceived health benefit intensity, with bundling strategies capturing volume at lower per-unit margins.
- Premium:Artisan positioning and limited-batch releases dominate in San Sebastián restaurant supply and specialty retail. Basque Country school district feeding programs mandate organic minimums, creating contracted offtake.
- Mid-range:Supermarket organic lines balance accessibility with margin preservation through scaled procurement.
- Discounted:Price-sensitive households in Madrid and Barcelona metro areas migrate toward private-label conventional alternatives.
- Organic Bundles:Weekly curated produce boxes reduce per-item handling costs and improve inventory predictability for Catalan cooperatives.
Mid-range captures volume concentration; Premium expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barcelona anchors Spain's organic food demand density through its metropolitan distribution infrastructure and quick-commerce platform concentration. Catalonia's per-capita consumption premium exceeds national averages, while Madrid and Valencia follow with expanding supermarket organic shelf space.
Catalonia
Barcelona's metropolitan zone drives the steepest consumption velocity through young professional households adopting weekly curated produce boxes. The regional government enforces EU organic regulations through Catalan agricultural bodies, mandating traceability from farm to retail. Dark-store networks dedicated to fresh organic produce bypass traditional supermarket intermediation across the Barcelona metro corridor.
Madrid
Supermarket chains expand dedicated organic shelf space across the capital's retail corridors, capturing families through infant nutrition specialization. Spain's Ministry of Agriculture channels CAP payments toward organic conversion, lowering transition costs for regional suppliers. Discount retail chains in the metro area capture price-sensitive households with private-label conventional alternatives.
Basque Country
San Sebastián and Bilbao school district feeding programs mandate organic ingredient minimums, creating contracted offtake for regional dairy cooperatives. Artisan cheese and yogurt value-addition captures margin concentration through cooperative structures. Per-capita organic consumption exceeds national averages, supported by direct producer relationships at metropolitan farmers' markets.
Valencia
CAECV-certified orange and mandarin production clusters in Castellón province supply juice processors and export channels to northern Europe. The Comité de Agricultura Ecológica de la Comunidad Valenciana enforces blockchain traceability platforms, compressing certification verification timelines. Weather-dependent volume risk concentrates supply exposure for citrus-dependent operations.
Andalusia
Andalusian olive growers receive redirected EU Green Deal subsidies toward regenerative farming practices and organic conversion. EFSA pesticide residue threshold enforcement shapes import acceptance criteria at Valencia and Barcelona ports for non-EU suppliers. Organic avocado importers diversify toward certified Colombian and Peruvian origins to reduce rejection risk.
Spain Organic Food Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and distribution channel access. The market structures around three distinct tiers: multinational infant nutrition specialists commanding supermarket shelf space, digital-native subscription services bypassing retail intermediation, and vertical farming operators supplying restaurant clusters. Strategic moves concentrate on quick-commerce partnerships and CAP eco-scheme alignment for supply security.
Within the infant nutrition tier, Hipp and Smileat exemplify divergent channel strategies, with the former anchoring premium retail positions and the latter occupying direct-to-parent digital subscriptions. Groots represents the vertical farming archetype, supplying pesticide-free leafy greens to Barcelona restaurant clusters through controlled-environment operations. Alimentaria Peñasanta SA sits within the diversified dairy cooperative structure, while East West Tea Co LLC occupies the beverage specialization niche.
| Leading Market Players |
|---|
| Alimentaria Peñasanta SA |
| Smileat |
| East West Tea Co LLC |
| FARM4GLOBE |
| Biofood Network |
| Otsuka Holdings Co Ltd |
| Groots |
| Green in Blue |
| Hipp |
| Others |
Pricing and Supply Chain Analysis
EU organic logo enforcement gates qualified supply and premium-tier pricing access for Spanish processors, compressing margins for non-compliant operators while rewarding CAECV-certified cooperatives with shelf-space premiums in Barcelona and Madrid retail corridors.
Pricing Analysis
Certification-grade anchoring determines value capture across the Spanish organic food sector. Three-tier pricing structure across premium, standard, and economy levels stratifies by EU organic logo compliance, artisan provenance, and channel control. Cost compression in the mid-range tier is intensifying because private-label conventional alternatives from discount chains capture price-sensitive households. Families purchasing infant nutrition products display lowest price sensitivity, while young professional households in Catalonia show moderate elasticity toward weekly curated produce subscriptions.
Supply Chain Analysis
Single-source vulnerability sits with Dutch and German specialty chemical suppliers of approved organic fertilizers and non-synthetic pest management inputs. Spanish growers draw from concentrated Iberian citrus belts, Almería greenhouse complexes, and Basque dairy cooperatives for finished goods. Tariff exposure on euro-denominated input purchases creates margin volatility for Andalusian olive and Extremaduran livestock operators. Distribution runs through supermarket chain procurement divisions, quick-commerce dark-store networks, and direct-to-parent digital subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spanish organic food has become a vertical-integration race, with players pursuing backward integration into CAECV-certified farm operations to secure compliant supply positions under tightening EU Green Deal subsidy conditions.
For Market Incumbents: Anticipate margin compression from digital-native subscription services by securing exclusive organic ingredient offtake agreements with Castellón citrus cooperatives and Basque dairy associations. Invest in blockchain traceability infrastructure to compress CAECV certification verification timelines and defend supermarket shelf-space positioning against quick-commerce entrants.
For New Entrants and Emerging Players: Capture white-space opportunity in Castilla-La Mancha cereal conversion under CAP eco-scheme payments, where organic penetration remains underdeveloped relative to Catalonia and Basque Country. Target contracted institutional procurement in San Sebastián and Bilbao school feeding programs as a go-to-market anchor.
For Investors and Strategic Acquirers: Basque Country cooperative management capability gaps widening into acquisition vulnerability is the leading indicator that consolidation-ready dairy and livestock associations will trade at favorable multiples. Focus diligence on CAECV compliance cost structures and EU organic logo enforcement exposure across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Operations | CAECV-certified acreage secures compliant supply positions under tightening EU organic regulations. |
| Quick-Commerce Dark-Store Partnership | Barcelona-based rapid delivery platforms bypass supermarket slotting fees for fresh produce access. |
| Blockchain Traceability Deployment | Digital documentation systems compress certification verification timelines from farm to retail shelf. |
| Institutional Procurement Contracting | Basque school district feeding programs mandate organic minimums, creating reliable offtake volumes. |
| Premium Infant Nutrition Line Extension | Hipp's specialization anchors shelf positioning in Iberian retail channels against digital-native competitors. |
Research Methodology
EU agricultural subsidy filings, CAECV certification databases, and Spanish customs trade records formed the secondary backbone, cross-referenced with primary interviews of organic cooperative managers, supermarket category buyers, quick-commerce platform operators, and regional agricultural enforcement officers. Bottom-up volume modeling of citrus, dairy, and cereal throughput triangulated against top-down CAP payment allocation data.
Historical trendline analysis of organic conversion rates and per-capita consumption patterns anchored the projection framework across the modeling period. Segmentation dimensions included product type, distribution channel, customer archetype, and price tier, with CAGRs derived from regression analysis of certified acreage expansion and retail shelf-space allocation trends. Forecast inputs incorporated EU Green Deal subsidy trajectory assumptions and EFSA pesticide residue threshold enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CAP reform negotiations, weather volatility in Castellón citrus belts, and cooperative management capability development in Galicia and Asturias. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
Organic Coconut Syrup Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
Australia Organic Beverages Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
Japan Organic Food Market