
 Global Organic Food Market | 2026-2036
Global Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Food Market Outlook
Buyer concentration among large-format retailers and direct-to-consumer platforms is pivoting as independent health stores and community-supported agriculture networks fragment traditional procurement channels. Whole Foods Market controls premium shelf space through its Whole Trade Guarantee program. Danone S.A. leverages its dairy specialization to anchor organic supply contracts across European cooperatives. Nature's Path Organic Foods competes through family-owned brand authenticity and gluten-free product depth.
Organic food comprises agricultural products cultivated without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, relying instead on crop rotation, biological pest control, and composting to maintain soil ecology and nutrient density for human consumption. Organic dairy commands margin pools due to extended certification timelines and herd conversion costs that limit supply elasticity. Online distribution channels represent the fastest-growing segment as cold-chain logistics and subscription models reduce friction for recurring produce purchases. Grains and cereals remain mature categories with price-sensitive consumers driving volume through private-label supermarket offerings.
The USDA National Organic Program, EU Organic Regulation 2018/848, and China's GB/T 19630 standards collectively define permissible inputs, inspection frequencies, and labeling requirements that determine market access for exporters. FDA and EFSA residue monitoring programs reinforce consumer trust through enforcement actions against fraudulent organic claims. Stakeholders must monitor evolving equivalency agreements between certifying regimes to anticipate which production regions gain or lose competitive access.
Market Dynamics
Certification-driven supply chain traceability is compressing procurement timelines as the EU Green Deal and USDA organic standards tighten documentation requirements for cross-border organic shipments.
Growth Catalysts
- EU Green Deal enforcement:The European Commission's Farm to Fork strategy mandates organic cultivation targets that redirect agricultural subsidies toward certified producers, expanding contract acreage across German and French cooperatives.
- Millennial household formation:First-time homebuyers in urban China and the United States prioritize organic grocery budgets, creating recurring revenue streams for direct-to-consumer subscription platforms.
- Cold-chain logistics maturation:Refrigerated last-mile networks reduce spoilage rates for perishable organic produce, enabling regional distributors to serve secondary cities previously outside fresh delivery radii.
Market Restraints
- Organic input cost volatility:Approved natural fertilizers and biological pest control agents carry price premiums over synthetic alternatives, squeezing margins for grain farmers during commodity downturns.
- Heritage supply concentration:Certified organic seed stock remains concentrated among Dutch and Austrian breeding cooperatives, creating germplasm access bottlenecks for North American and Asian expansion.
- Conversion timeline rigidity:USDA organic certification requires 36 months of documented chemical-free cultivation before harvest eligibility, freezing land productivity during transition periods.
Strategic Opportunities
- Indian domestic cultivation:FSSAI organic labeling harmonization with EU equivalency agreements positions Maharashtra and Karnataka as export-ready production zones for European retailers.
- Regenerative agriculture stacking:Carbon credit certification layered atop organic standards attracts ESG-mandated institutional capital into Brazilian and Australian pastoral operations.
- Blockchain traceability integration:Distributed ledger verification of farm-to-retail documentation commands shelf-space premiums in Japanese and South Korean premium grocery channels.
Industry Challenges
- Inspector workforce scarcity:Accredited organic certifiers require agronomy degrees plus audit training, creating recruitment bottlenecks as inspection demand outpaces credentialing pipeline capacity.
- Legacy ERP integration:Smallholder cooperatives operate on paper-based record systems that resist digitization, complicating batch-level traceability for export compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Food Market |
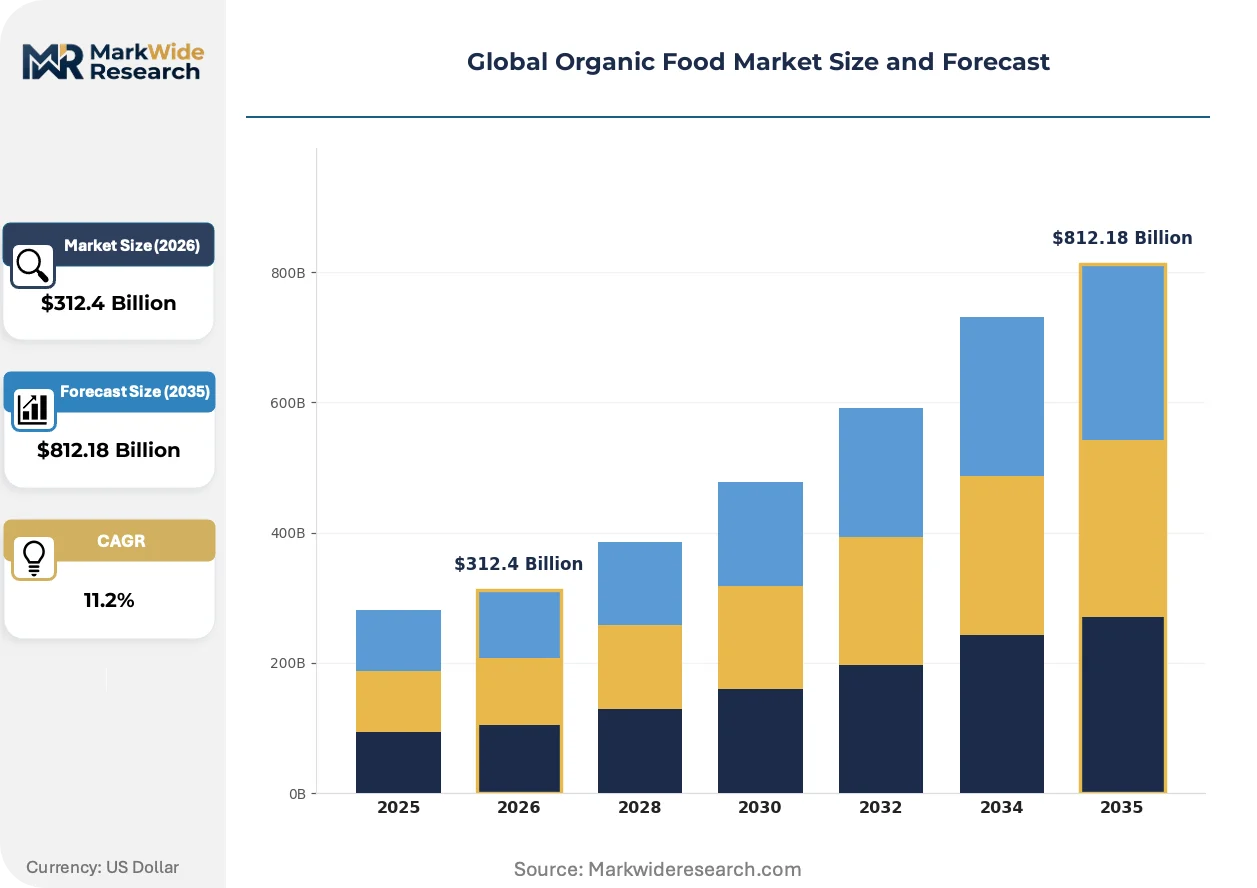
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $812.18 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Dairy Packaging Type: Bags, Boxes, Bottles, Jars End User: Retailers, Wholesalers, Restaurants, Consumers Distribution Channel: Online, Supermarkets, Farmers' Markets, Health Stores |
| Companies Covered | The Hain Celestial Group, Whole Foods Market, Danone S.A., Nature's Path Organic Foods, Organic Valley, Nestlé S.A., Conagra Brands Inc., Amy's Kitchen, General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Food Market Strategic Shifts
Digital verification protocols and biological input innovation are displacing conventional assurance methods while reshaping how organic integrity is communicated to end consumers.
Hyperspectral imaging systems deployed at packing facilities is automating real-time detection of pesticide residue and ripeness markers, eliminating manual sampling bottlenecks. Large-format retailers in Germany and California are adopting these systems to reduce third-party laboratory testing costs. The technology is automating quality assurance workflows that previously delayed shipment releases by 48-72 hours.
China's GB/T 19630 standard revisions are tightening permissible additive lists for processed organic foods, forcing reformulation of shelf-stable dairy and beverage categories. Domestic manufacturers face six-month re-certification cycles that disrupt production scheduling. Infant formula and ready-to-drink segments are accelerating clean-label development to preempt compliance deadlines.
Community-supported agriculture memberships are displacing traditional wholesale intermediaries for vegetable and fruit categories in metropolitan France and the Pacific Northwest. Urban households commit to seasonal harvest shares that guarantee offtake for peri-urban growers. This channel rotation is most pronounced among dual-income households seeking provenance transparency without supermarket markup.
Global Organic Food Market Segmentation
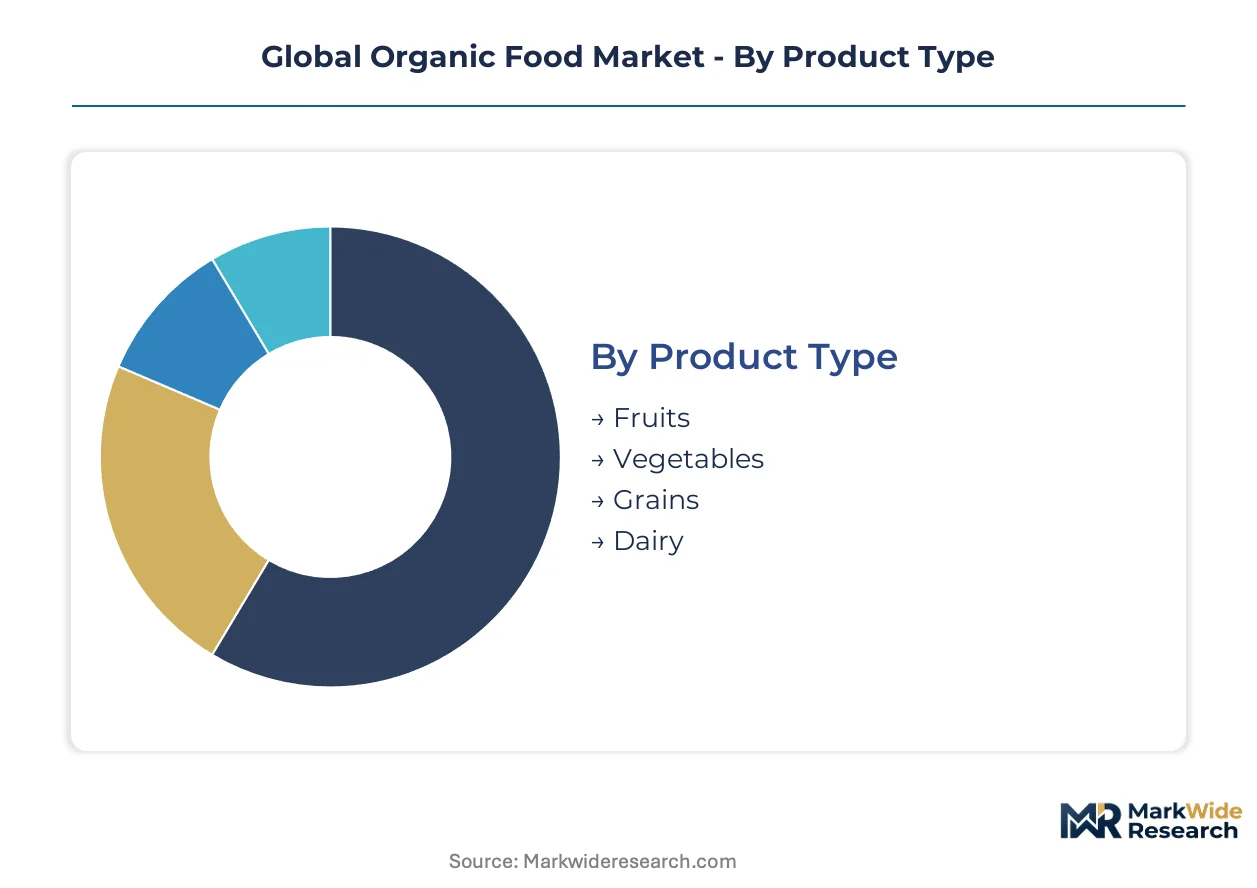
Segmentation in organic food markets reveals how certification requirements, perishability constraints, and channel economics partition commercial opportunity. Product type determines margin structure through input cost differentials. Packaging and distribution choices reflect the tension between shelf-life extension and consumer preference for minimal processing.
Product Type:
Certification complexity and biological input requirements create divergent margin profiles across agricultural categories.
- Dairy:Extended herd conversion timelines and veterinary protocol restrictions compress supply elasticity. German and French cooperatives anchor European production, while Chinese infant formula manufacturers drive import demand for certified organic milk powder.
- Fruits:Perishability demands cold-chain infrastructure investment that favors proximity to urban consumption clusters. California's Central Valley and Spain's Valencia region dominate export supply, with hyperspectral imaging systems now automating residue detection at packing facilities.
- Vegetables:Community-supported agriculture networks in France and the Pacific Northwest are displacing wholesale intermediaries for seasonal harvest categories.
- Grains:Price-sensitive consumers drive volume through private-label supermarket offerings, with Dutch and Austrian breeding cooperatives controlling certified organic seed stock access.
Dairy leads on scale through margin pool concentration; fruits lead on momentum through cold-chain logistics maturation.
Packaging Type:
Material specifications interact with organic integrity standards to determine shelf-access economics and consumer trust signaling.
- Bottles:Beverage and liquid dairy segments require oxygen barrier properties that complicate recyclable material selection. China's GB/T 19630 standard revisions are forcing reformulation of shelf-stable organic beverages with tightened permissible additive lists.
- Bags:Flexible packaging dominates grain and produce categories where weight reduction reduces freight cost burden. German retailers are adopting compostable film specifications that exceed EU baseline requirements.
- Boxes:Corrugated formats serve community-supported agriculture subscription deliveries and direct-to-consumer platforms in metropolitan France.
- Jars:Glass containers command premium positioning for preserves and fermented categories, though weight penalties limit e-commerce viability.
Bottles capture the steepest expansion trajectory through ready-to-drink organic beverage proliferation; bags retain volume leadership in commodity grain distribution.
End User:
Procurement scale and specification stringency fragment demand across institutional and household channels.
- Retailers:Large-format supermarkets and direct-to-consumer platforms consolidate procurement through Whole Trade Guarantee-style programs that mandate batch-level traceability documentation.
- Consumers:Health-conscious millennial and Gen Z households in urban China and the United States prioritize organic grocery budgets, creating recurring revenue for subscription platforms.
- Restaurants:Farm-to-table establishments in California and the Pacific Northwest source through peri-urban grower networks that bypass certified wholesale infrastructure.
- Wholesalers:Traditional intermediaries face margin compression as blockchain traceability integration enables producers to command shelf-space premiums directly.
Retailers anchor procurement volume; consumers are gaining share fastest through digital channel migration.
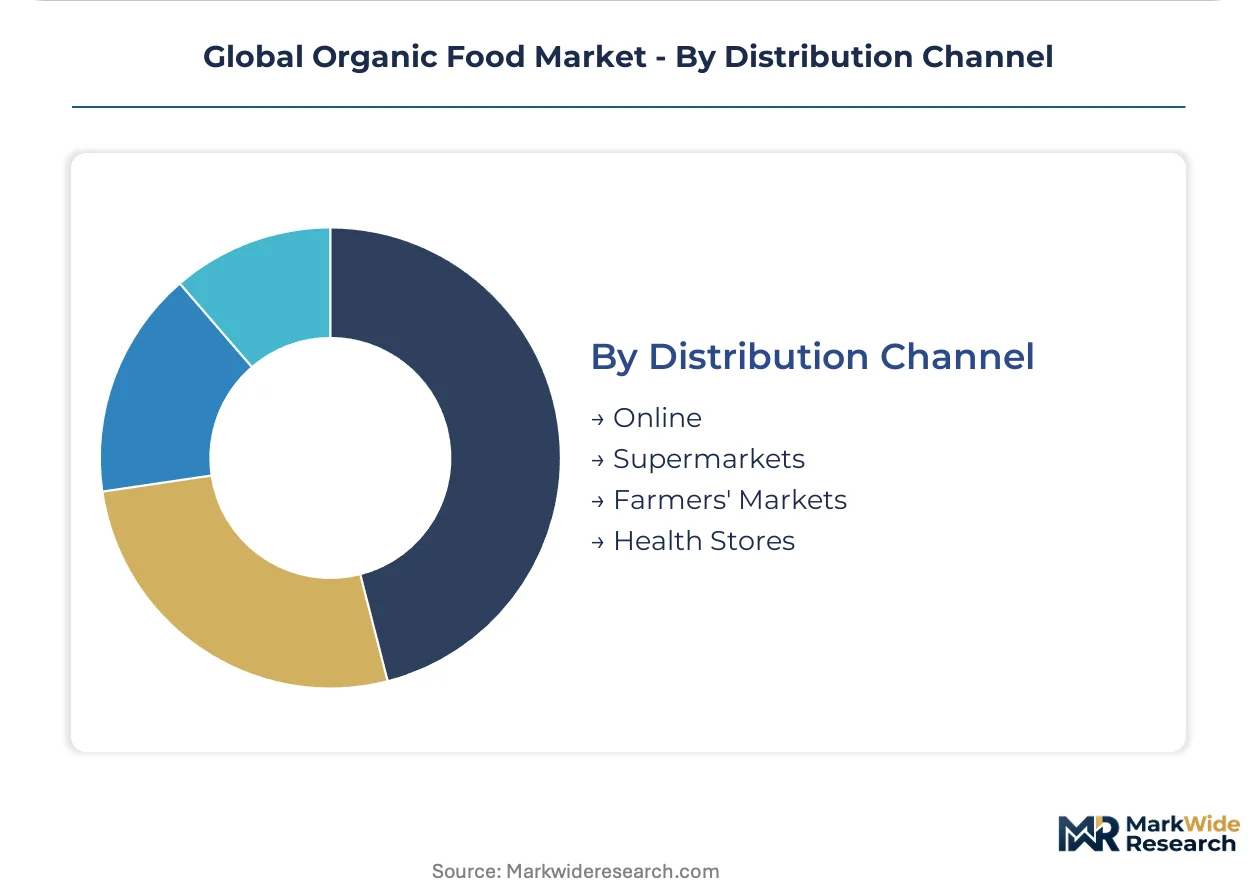
Distribution Channel:
Last-mile configuration determines spoilage exposure and certification documentation handoff integrity.
- Online:Subscription models and refrigerated last-mile networks reduce friction for recurring produce purchases. Japanese and South Korean premium grocery channels are adopting distributed ledger verification systems that command documentation premiums.
- Supermarkets:Private-label offerings dominate grains and cereals, while premium shelf space allocation depends on third-party certification status under USDA or EU Organic Regulation standards.
- Farmers' Markets:Direct producer-consumer contact supports price realization for smallholders operating outside cooperative structures, particularly in Germany and France.
- Health Stores:Independent retail networks fragment traditional procurement channels through specialized supplement and allergen-free product depth.
Supermarkets retain volume concentration; online channels show the most rapid ascent through cold-chain infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cooperative-driven organic sector contrasts with China's state-coordinated expansion, revealing divergent pathways toward similar certification density targets. National regulatory frameworks and retail infrastructure maturity determine how quickly consumer demand translates into cultivated acreage.
United States
Millennial household formation in metropolitan corridors drives subscription platform adoption for recurring produce deliveries. The USDA National Organic Program mandates 36-month conversion timelines that freeze land productivity during transition periods. California's Central Valley anchors fruit and vegetable export supply, with hyperspectral imaging systems now automating residue detection at packing facilities.
Germany
The EU Green Deal's Farm to Fork strategy redirects agricultural subsidies toward certified producers across German cooperatives. EFSA residue monitoring programs reinforce consumer trust through enforcement actions against fraudulent organic claims. Bavaria and North Rhine-Westphalia concentrate dairy processing infrastructure where extended herd conversion timelines compress supply elasticity.
China
Urban middle-class expansion prioritizes organic infant formula and ready-to-drink beverages as dietary upgrade markers. GB/T 19630 standard revisions tighten permissible additive lists, forcing six-month re-certification cycles for processed food manufacturers. Yangtze River Delta municipalities deploy cold-chain logistics networks that reduce spoilage rates for perishable produce deliveries to secondary cities.
France
Community-supported agriculture networks displace wholesale intermediaries for vegetable categories among dual-income households seeking provenance transparency. EU Organic Regulation 2018/848 defines inspection frequencies and labeling requirements that determine market access for exporters. The Île-de-France and Provence-Alpes-Côte d'Azur regions concentrate peri-urban grower networks that bypass certified wholesale infrastructure for farm-to-table procurement.
India
FSSAI organic labeling harmonization with EU equivalency agreements positions Maharashtra and Karnataka as export-ready production zones for European retailers. Domestic cultivation expansion targets redirect agricultural investment toward certified acreage as middle-class grocery budgets mature. The country's national food regulator enforces batch-level traceability documentation that complicates smallholder cooperative compliance.
Global Organic Food Market Competitive Environment
North American retailers anchor one tier; European dairy specialists hold differentiated positions through cooperative supply contracts. The vendor base distributes across family-owned authenticators, multinational portfolio diversifiers, and private-label supermarket channels. Three archetypes dominate: premium-shelf-space guarantors, supply-contract anchors, and direct-to-consumer subscription platforms. Competitive moves concentrate on M&A consolidation for brand portfolios and backward integration into certified organic seed stock access.
Within the multinational diversified tier, Danone S.A. and Nestlé S.A. occupy positions shaped by dairy specialization and portfolio breadth respectively. Among retailer-anchored channels, Whole Foods Market exemplifies premium shelf-space allocation through certification-mandated programs. The Hain Celestial Group and Nature's Path Organic Foods represent family-owned authenticity archetypes competing through specialized product depth rather than scale economies.
| Leading Market Players |
|---|
| The Hain Celestial Group |
| Whole Foods Market |
| Danone S.A. |
| Nature's Path Organic Foods |
| Organic Valley |
| Nestlé S.A. |
| Conagra Brands Inc. |
| Amy's Kitchen |
| General Mills Inc. |
| Others |
Value Chain & Pricing Dynamics
Accredited organic certifier workforce concentration in the EU and North America creates labor-cost differentials that widen pricing-tier spreads between premium certified products and transitional conventional alternatives. German inspection cooperatives command rate premiums that propagate through dairy and produce categories, while Asian certification bodies compress margins through competitive audit pricing.
Pricing Analysis
Capacity additions in India's Maharashtra and Karnataka growing regions are reshaping price floors for export-grade organic grains and spices. Three-tier pricing structure across premium EU-certified, standard USDA-organic, and economy private-label tiers reflects certification depth and traceability documentation completeness. Cost compression in the economy tier is intensifying because supermarket chains are consolidating private-label procurement volumes. Grain and cereal buyers exhibit the highest price sensitivity, while infant formula purchasers demonstrate the lowest.
Supply Chain Analysis
Reverse-logistics flows for organic products center on composting returns and packaging recovery programs mandated by German and French retailer sustainability protocols. Primary cultivation concentrates in Germany, the United States, and China, with secondary processing clustering in the Netherlands and California. Biological input supply draws from approved natural fertilizer producers in Austria and biological pest control specialists in India. Single-source vulnerability permeates certified organic seed stock access through Dutch and Austrian breeding cooperatives. Distribution runs through cooperative aggregation networks that consolidate smallholder volumes for export compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Organic Food Market functions as a stable compounder anchored by irreversible dietary upgrade trends among urban middle-class households across multiple continents.
For Market Incumbents: Lock in multi-year supply contracts with German and French dairy cooperatives before EU Green Deal subsidy redirection escalates input competition. Deepen backward integration into certified organic seed stock access through equity stakes in Dutch breeding operations. Channel control through direct-to-consumer subscription platforms defends margin position against private-label supermarket encroachment. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for peri-urban vegetable growers in France and the Pacific Northwest seeking to bypass wholesale intermediaries. Target community-supported agriculture networks among dual-income households seeking provenance transparency without supermarket markup. Blockchain-enabled traceability documentation serves as the primary go-to-market differentiation for Japanese and South Korean premium grocery channel access. For Investors and Strategic Acquirers: European dairy specialists are the most active acquirer in this space, consolidating cooperative supply contracts to secure margin pool concentration. Acquisition target archetypes include family-owned organic brands with gluten-free or allergen-free product depth and established EU equivalency certifications. Watch FSSAI-EU organic labeling harmonization progress as the signal for Indian export-ready production zone viability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Seed Stock | Captures germplasm access bottlenecks that constrain North American and Asian expansion timelines. |
| Blockchain Traceability Integration | Commands shelf-space premiums in Japanese and South Korean premium grocery documentation channels. |
| Direct-to-Consumer Subscription Launch | Reduces friction for recurring produce purchases among millennial households in urban China and the United States. |
| Regenerative Agriculture Certification Stacking | Attracts ESG-mandated institutional capital into Brazilian and Australian pastoral carbon credit markets. |
| Cold-Chain Logistics Network Expansion | Enables regional distributors to serve secondary cities previously outside fresh organic delivery radii. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with organic certification body executives, cooperative procurement managers, supermarket category buyers, cold-chain logistics operators, and FSSAI regulatory affairs specialists cross-validate secondary data from USDA National Organic Program filings, EU Organic Regulation compliance databases, GB/T 19630 standard revision notices, customs trade records, and EFSA residue monitoring reports.
Historical trendline analysis of certified acreage expansion, conversion timeline completion rates, and channel shift velocities informs projection modeling across the analysis window. Segmentation dimensions include product type, packaging format, end-user archetype, and distribution channel, with regional regulatory cluster variations explicitly modeled. CAGRs derive from elasticity-adjusted demand curves incorporating household formation demographics and dietary upgrade propensity indices.
EU-India equivalency agreement delays, inspector workforce credentialing bottlenecks, and biological input price volatility are the dominant revision risks to modeled outputs. Practitioners should monitor these triggers for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Global Organic Packaged Food Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
Natural Food and Drinks Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Canada Organic Food Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
Organic Yogurt Market
Organic Food and Beverages
Organic Coconut Sugar Market