
 United States Organic Food Market | 2026-2036
United States Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
United States Organic Food Market Intelligence
The USDA National Organic Program is restructuring procurement standards across the United States organic food supply chain by tightening supply chain integrity enforcement and strengthening audit requirements for imported organic commodities. Organic Valley leverages its cooperative ownership model to sustain price premiums for dairy producers across the Upper Midwest. Nature's Path anchors organic breakfast and snack categories through vertical integration into grain sourcing and domestic milling operations. Horizon Organic competes on scale by controlling fluid milk distribution through major retail partnerships nationwide.
Organic food comprises agricultural products cultivated without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, meeting USDA National Organic Program standards for soil health, animal welfare, and processing integrity; certification requires third-party verification of production practices and annual inspections to maintain market access. Fruits and vegetables occupy the largest volume share within product type segments due to established consumer familiarity and year-round retail availability through diversified sourcing. Dairy commands premium margin pools driven by constrained organic milk supply and processor concentration in Wisconsin and Vermont. Distribution through supermarkets dominates value capture, though online stores represent the fastest-growing channel as direct-to-consumer fulfillment infrastructure matures.
The USDA National Organic Program sets product standards and market access rules, while the FDA governs food safety and labeling claims for organic packaged goods; state-level organic programs in California and Washington impose additional inspection density that shapes regional compliance costs. The Federal Trade Commission monitors green marketing claims to prevent consumer deception in organic product advertising. Stakeholders must monitor evolving domestic supply chain verification requirements and assess whether backward integration into organic feed and seed production reduces exposure to import-dependent input costs.
Market Dynamics
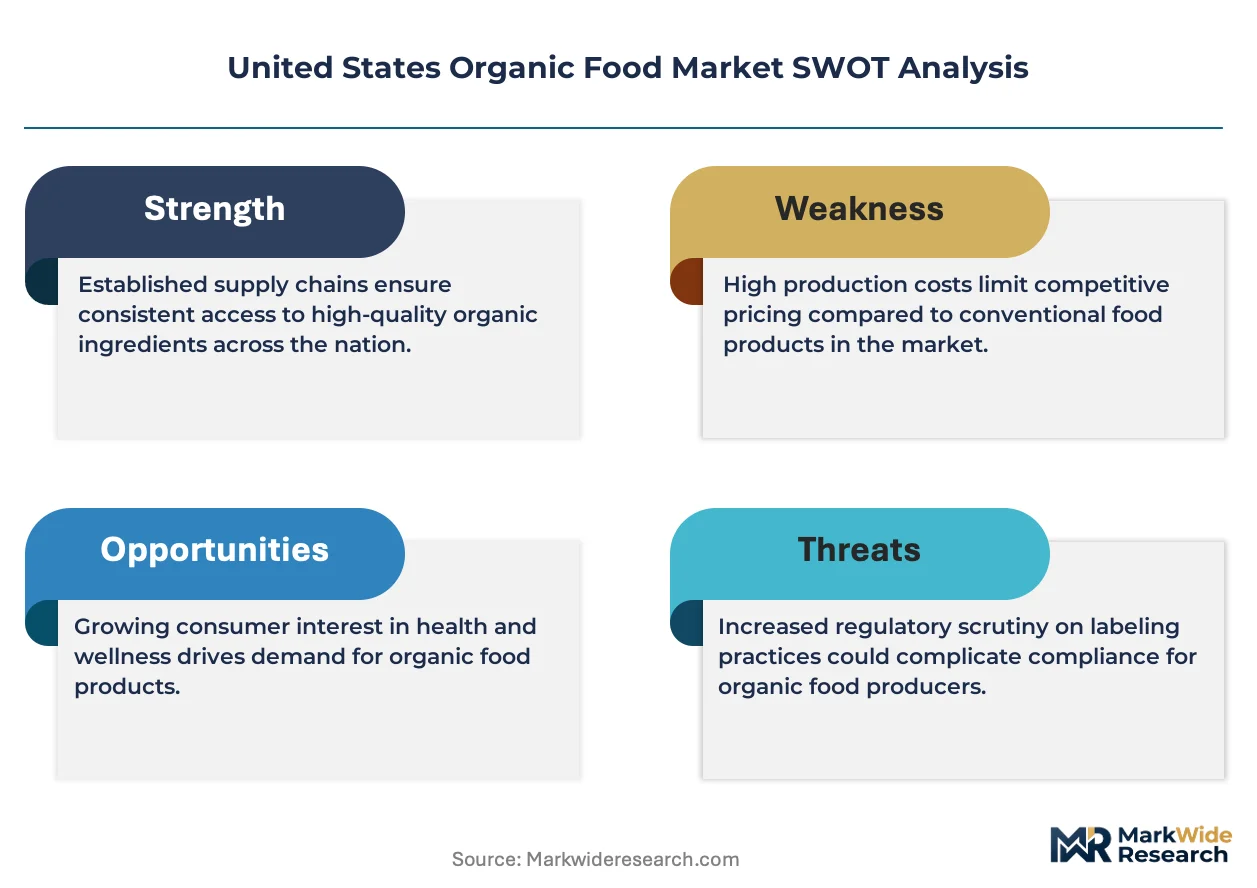
The USDA National Organic Program's supply chain integrity enforcement is compressing market access timelines while concentrating procurement authority among vertically integrated processors capable of meeting audit density requirements across multiple state jurisdictions.
Growth Catalysts
- Strengthened Organic Fraud Prevention Rule:The USDA's enhanced traceability mandates are eliminating gray-market organic imports and redirecting volume toward domestic certified producers in California's Central Valley.
- Institutional foodservice procurement:K-12 school districts and hospital systems are mandating certified organic ingredients in volume contracts, creating anchored demand pools independent of retail price sensitivity.
- Soil health measurement protocols:Regenerative agriculture verification technologies are extending organic premium capture into carbon credit markets through third-party soil carbon quantification.
Market Restraints
- Organic feed input cost volatility:Domestic organic grain production deficits force reliance on imported organic soy and corn, exposing processors to currency and freight cost swings from Argentine and Ukrainian suppliers.
- Processor concentration in fluid milk:Wisconsin and Vermont dairy cooperatives control over two-thirds of organic milk bottling capacity, creating procurement bottlenecks for new brand entrants.
- Three-year organic transition barrier:The USDA's land conversion timeline blocks conventional farmers from capturing organic premiums during price spike windows, constraining supply elasticity.
Strategic Opportunities
- Texas and Florida underpenetration:Sun Belt metropolitan areas show organic penetration rates half those of coastal markets, presenting first-mover retail positioning opportunities in Houston and Miami corridors.
- Direct-to-consumer subscription fulfillment:Cold-chain logistics maturation enables farm-branded organic produce to bypass supermarket slotting fees through weekly box delivery models.
- Inflation Reduction Act conservation incentives:USDA EQIP and CSP program expansions are subsidizing organic transition costs for mid-scale row-crop operators in the Corn Belt.
Industry Challenges
- Certified organic inspector shortage:Accredited third-party auditor capacity constraints are extending certification renewal timelines from 90 to 180 days, freezing product launches during peak harvest windows.
- Legacy ERP integration with traceability platforms:Small and mid-sized processors face six-figure system overhauls to comply with USDA's electronic organic integrity certificate requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Organic Food Market |
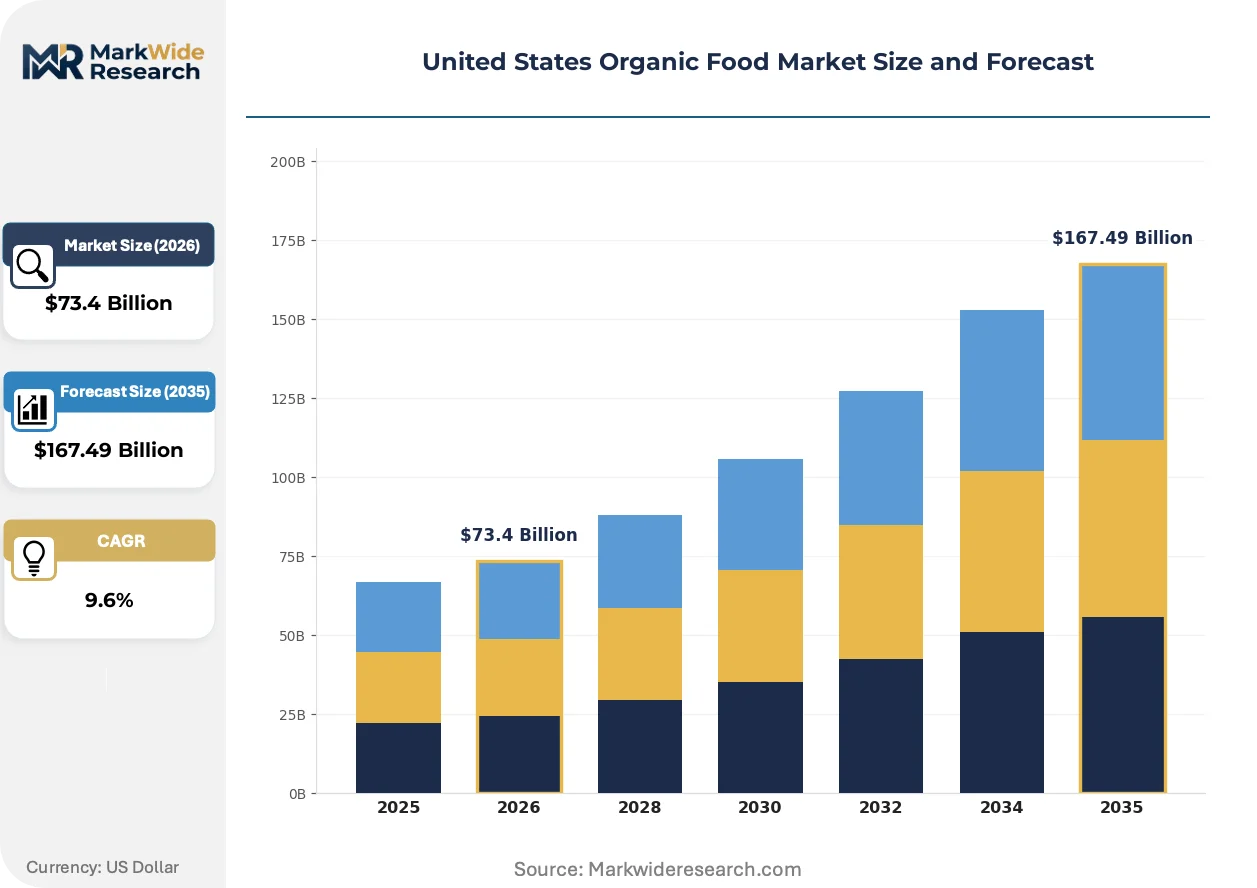
| Market Size in 2026 | $73.4 Billion |
| Market Size in 2035 | $167.49 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Dairy Distribution Channel: Supermarkets, Online Stores, Farmers' Markets, Health Food Stores End User: Households, Restaurants, Cafés, Institutions Price Tier: Premium, Mid-Range, Economy, Discounted |
| Companies Covered | Nature's Path, Farmer Focus, Organic Valley, Navitas Organics, Mary's Gone Crackers, Eden Foods, Stonyfield, UNFI, Horizon Organic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Organic Food Market Strategic Shifts & Innovations
Blockchain-enabled provenance tracking is penetrating organic supply chains at the farm-processor interface, while plant-based organic alternatives and precision fermentation technologies are fragmenting traditional category boundaries.
Blockchain-based organic certificate verification is rewriting how supply chain participants authenticate origin claims. Major retailers including Kroger and Whole Foods Market are mandating distributed ledger integration for private-label organic suppliers by 2026. This technology is compressing fraud detection timelines from months to hours while raising compliance costs for non-integrated producers.
The USDA's Strengthening Organic Enforcement final rule imposes mandatory organic fraud prevention plans and supplier verification protocols on all certified operations. Processors must now document chain-of-custody at each ownership transfer, with civil penalties reaching $15,000 per violation. California and Washington state organic programs are layering additional inspection density requirements that extend compliance timelines for multi-state distributors.
Consumer willingness-to-pay for hyperlocal organic certification is fragmenting national brand loyalty into zip-code-specific purchasing patterns. Community-supported agriculture subscriptions and farmers market pre-order platforms are capturing produce dollars previously directed toward supermarket organic private labels. This behavioral shift concentrates in Pacific Northwest and New England metropolitan corridors where local organic supply exceeds national brand distribution density.
United States Organic Food Market Segmentation
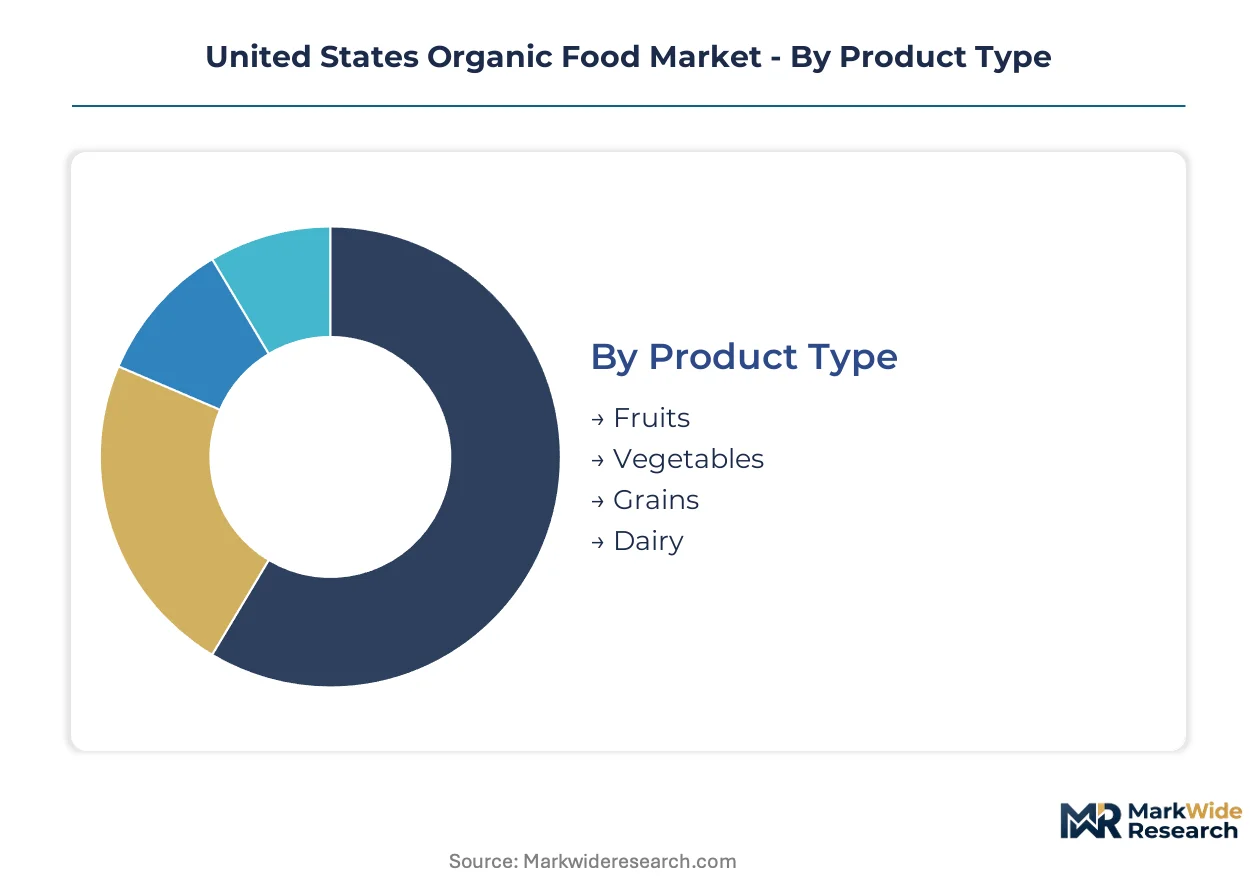
Segmentation in the United States organic food market reveals how procurement authority and price sensitivity diverge across buyer types and channels. Understanding these fault lines exposes where margin pools concentrate and where new entrants face structural barriers to volume capture.
Product Type:
Buyers differentiate by perishability constraints, certification complexity, and supply chain length from farm to final processing.
- Fruits:Tree and vine crops dominate organic acreage in California's Central Valley, with strawberries and apples commanding year-round retail shelf space through diversified hemispheric sourcing. Washington State apple cooperatives and Florida citrus packers anchor domestic supply, though Mexican blueberry imports fill winter demand gaps that strain cold-chain integrity.
- Vegetables:Leafy greens and brassicas rotate through Arizona's Yuma Valley and California's Salinas corridor on seasonal schedules that shape national availability windows. Controlled-environment agriculture in Texas and New York is displacing field-grown lettuce in Northeast retail contracts.
- Grains:Organic corn and soy deficits force processors toward Argentine and Ukrainian suppliers, exposing flour millers to currency volatility.
- Dairy:Wisconsin and Vermont cooperatives control fluid milk bottling capacity, creating procurement bottlenecks for new brand entrants.
Vegetables lead volumes today; grains are gaining share fastest as regenerative agriculture verification extends organic premiums into carbon credit markets.
Distribution Channel:
Channel selection determines compliance burden, traceability investment, and access to price-sensitive versus premium-loyal customer bases.
- Supermarkets:Kroger and Whole Foods Market mandate blockchain-enabled provenance tracking for private-label organic suppliers, compressing fraud detection timelines while raising compliance costs for non-integrated producers. Slotting fees and promotional allowances concentrate procurement authority among vertically integrated processors capable of meeting audit density requirements.
- Online Stores:Direct-to-consumer fulfillment infrastructure matures fastest in Pacific Northwest and New England corridors where cold-chain logistics enable farm-branded produce to bypass supermarket gatekeepers. Subscription box models capture produce dollars previously directed toward retail private labels.
- Farmers' Markets:Hyperlocal certification fragments national brand loyalty into zip-code-specific purchasing patterns concentrated in metropolitan areas with surplus local organic supply.
- Health Food Stores:Independent retailers in college towns and affluent suburbs curate specialty organic SKUs with higher margin tolerance than mass-market channels.
Supermarkets dominate value capture today; online stores are expanding most quickly as last-mile cold-chain infrastructure matures.
End User:
Volume commitment, price elasticity, and specification rigor separate institutional buyers from household consumers.
- Households:Pacific Northwest and New England metropolitan consumers show willingness-to-pay premiums for hyperlocal organic certification that fragments national brand loyalty.
- Restaurants:Fast-casual chains and fine-dining groups mandate certified organic ingredients in procurement contracts independent of retail price sensitivity.
- Cafés:Coffee shop operators prioritize organic dairy and plant-based alternatives in beverage programs that compete on sustainability credentials.
- Institutions:K-12 school districts and hospital systems anchor demand pools through volume contracts that bypass retail margin structures, with USDA procurement guidelines tightening organic verification requirements for federal nutrition programs.
Households anchor volume today; institutions are climbing the fastest as federal nutrition program guidelines tighten organic verification requirements.
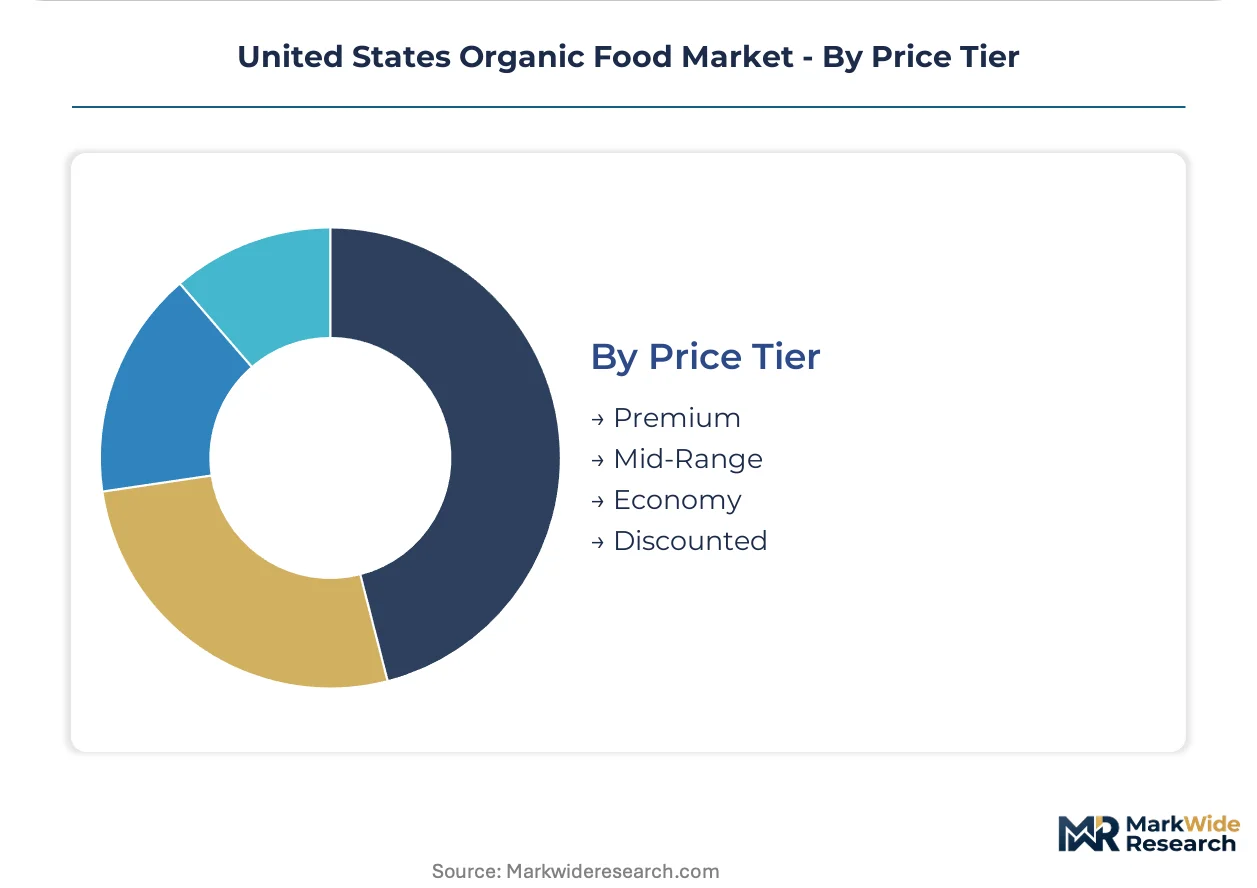
Price Tier:
Premium capture depends on certification density, origin specificity, and supply chain transparency investment.
- Premium:Regenerative organic certified and biodynamic labels command shelf space in Whole Foods Market and specialty retailers, with soil health measurement protocols extending value capture into carbon credit markets through third-party quantification.
- Mid-Range:USDA Organic certified products without additional sustainability claims occupy mainstream supermarket placement, balancing accessibility with margin preservation.
- Economy:Private-label organic lines at Aldi and Walmart compress producer margins while expanding category penetration to price-sensitive demographics.
- Discounted:Close-dated and imperfect-grade organic produce moves through salvage grocery channels and food rescue networks with minimal traceability documentation.
Mid-Range leads volumes today; Premium is gaining share fastest as regenerative agriculture verification technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic food production clusters around specialized agronomic talent pools in California's Central Valley, Wisconsin's dairy belt, and Vermont's pasture networks, with processing infrastructure following raw material gravity toward these concentrations.
California
Strawberry and leafy green demand from Los Angeles and San Francisco metro areas anchors acreage expansion in Monterey and Fresno counties. The California Department of Food and Agriculture layers additional organic inspection density atop federal USDA requirements, extending compliance timelines for out-of-state distributors. Salinas-based processors control national vegetable washing and bagging capacity, with blockchain-enabled provenance tracking now mandatory for private-label suppliers to Whole Foods Market.
Wisconsin
Organic dairy procurement from Chicago and Minneapolis retail corridors concentrates fluid milk bottling authority in La Crosse and Madison cooperative networks. The Wisconsin Department of Agriculture, Trade and Consumer Protection administers state-level organic certification parallel to USDA oversight, creating dual audit burdens for new entrants. Dane County processing clusters face inspector shortages that stretch certification renewals from 90 to 180 days during peak harvest windows.
Vermont
Premium organic milk demand from Boston and New York City households sustains pasture-based dairy operations in Addison and Franklin counties. The Vermont Agency of Agriculture, Food and Markets enforces animal welfare standards exceeding federal NOP baselines, shaping regional compliance cost structures. Burlington-area cooperatives anchor Northeast fluid milk distribution through captive supply agreements with regional retail chains.
Texas
Underpenetrated Houston and Dallas-Fort Worth metro corridors present organic penetration rates half those of coastal markets, attracting first-mover retail positioning from national distributors. The Texas Department of Agriculture administers organic certification with streamlined timelines that compress market access relative to California and Washington. Controlled-environment agriculture in Austin and San Antonio corridors is displacing field-grown lettuce in regional retail contracts through year-round supply reliability.
Washington
Apple and cherry demand from Seattle-Tacoma and Portland metro areas sustains organic tree fruit acreage in Yakima and Wenatchee valleys. The Washington State Department of Agriculture imposes additional inspection density requirements that raise compliance costs for multi-state distributors relative to federal baselines. Spokane-area grain processors face organic corn and soy deficits that force reliance on Argentine and Ukrainian suppliers, exposing operations to currency volatility.
United States Organic Food Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the organic food supply chain, with cooperative ownership structures and private-label manufacturing networks fragmenting procurement authority. Vertically integrated processors controlling captive feed supply and bottling capacity command pricing leverage over brand-dependent entrants. Three archetypes dominate: dairy cooperatives with captive milk supply, grain millers with backward integration into seed sourcing, and produce packers with controlled-environment agriculture assets. Competitive moves concentrate on M&A to secure organic acreage and strategic partnerships to bypass supermarket slotting fees.
Among cooperative-structured producers, Organic Valley and Stonyfield exemplify the dairy archetype through member-owned supply pools that sustain price premiums for pasture-based operations. Horizon Organic occupies a position within the scale-driven tier, leveraging nationwide retail distribution partnerships to capture fluid milk volume. Nature's Path represents the vertically integrated grain processor archetype, with in-house milling operations and domestic sourcing networks that reduce exposure to import-dependent organic commodity costs.
| Leading Market Players |
|---|
| Nature's Path |
| Farmer Focus |
| Organic Valley |
| Navitas Organics |
| Mary's Gone Crackers |
| Eden Foods |
| Stonyfield |
| UNFI |
| Horizon Organic |
| Others |
Cost & Logistics Intelligence
Premium-mid-economy pricing differentiation across USDA Organic, Regenerative Organic Certified, and private-label tiers manifests in divergent supply chain configurations that concentrate procurement authority among vertically integrated processors capable of absorbing compliance cost burdens while squeezing margin pools for non-integrated brand entrants dependent on third-party bottling and milling capacity.
Pricing Analysis
Certification-bundled versus unbundled service splits dominate organic food pricing, with USDA Organic baseline certification commanding standard shelf placement while Regenerative Organic Certified and biodynamic labels extract tiered premiums through carbon credit eligibility and enhanced traceability documentation. Price differentiation hinges on third-party audit density and origin specificity, with Pacific Northwest hyperlocal certifications sustaining 15-30 point premiums over commodity organic. Cost compression in private-label tiers intensifies as Aldi and Walmart expand organic SKU counts, squeezing producer margins. Institutional buyers in K-12 and hospital systems exhibit lowest price sensitivity due to federal nutrition program mandates, while economy-tier household consumers drive volume but resist premium capture.
Supply Chain Analysis
Inspector shortages across California, Wisconsin, and Washington extend certification renewal timelines, constraining processor capacity expansion and concentrating organic dairy bottling authority in La Crosse and Madison cooperative networks. Raw material flows draw from Argentine organic soy, Ukrainian corn, and domestic Central Valley produce, exposing millers to currency volatility and freight cost swings. Single-source vulnerability concentrates in Wisconsin and Vermont fluid milk processing, where two-thirds of national bottling capacity rests on cooperative ownership structures. Distribution runs through Kroger and Whole Foods Market private-label procurement gatekeepers, with direct-to-consumer subscription models fragmenting last-mile control in Pacific Northwest and New England corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States organic food market represents a late-cycle quality story as institutional procurement mandates in K-12 school districts and hospital systems shift demand toward premium certification tiers that reward supply chain transparency investment.
For Market Incumbents: Extend backward integration into organic feed and seed production to reduce exposure to Argentine and Ukrainian import volatility, while consolidating inspector capacity through multi-state certification reciprocity agreements. Horizon Organic and Organic Valley must defend against precision fermentation dairy alternatives by locking pasture-based supply through long-term cooperative member contracts. Captive bottling capacity in Wisconsin and Vermont remains the priority lever for margin defense. For New Entrants and Emerging Players: Sun Belt metropolitan buyers in Houston and Dallas-Fort Worth corridors present underpenetrated demand pools with organic adoption rates half those of coastal markets. Controlled-environment agriculture operators in Austin and San Antonio can bypass supermarket slotting fees through direct-to-institutional contracts with Texas hospital systems. Farm-branded subscription box models offer the most penetrable go-to-market angle for produce entrants seeking to circumvent Kroger and Whole Foods Market procurement gatekeepers. For Investors and Strategic Acquirers: Consolidation pressure builds where organic inspector shortages and ERP traceability upgrade requirements strand sub-scale processors without capital for USDA Strengthening Organic Enforcement compliance. Mid-scale grain millers with in-house milling and domestic sourcing networks offer the strongest acquisition target archetype. Watch organic fraud enforcement penalty accumulation as an inflection indicator for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feed Supply | Captive organic corn and soy production insulates processors from Argentine currency volatility and Ukrainian supply disruptions. |
| Blockchain Provenance Platform Deployment | Kroger and Whole Foods Market mandates compress fraud detection timelines while raising barriers for non-integrated suppliers. |
| Controlled-Environment Agriculture Expansion | Texas and Arizona indoor farming displaces field-grown lettuce through year-round supply reliability and reduced water intensity. |
| Direct-to-Institutional Contracting | K-12 and hospital volume contracts bypass retail margin structures and anchor demand independent of consumer price sensitivity. |
| Regenerative Organic Certification Investment | Soil carbon quantification protocols extend premium capture into voluntary carbon credit markets for verified sequestration. |
Research Approach
Multiple input streams — structured interviews with organic processors and cooperative executives, regulatory filings with USDA National Organic Program and state agriculture departments, and retail procurement database analysis — were reconciled through bottom-up volume triangulation against top-down expenditure estimates. Primary fieldwork engaged dairy cooperative board members, grain miller procurement leads, supermarket category buyers, and third-party organic certification auditors. Secondary validation drew from USDA NOP enforcement action records, FDA food safety guidance documents, Federal Trade Commission green marketing complaint filings, and customs trade data on organic commodity imports.
Data-stream reconciliation anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, distribution channel, end user, and price tier. CAGRs were derived from trend extrapolation of historical volume and value trajectories, adjusted for regulatory enforcement intensity and supply chain integrity rule implementation timelines. Forecast inputs incorporated organic transition cost subsidies under Inflation Reduction Act conservation programs and cold-chain logistics maturation curves for direct-to-consumer fulfillment.
Underlying measurement precision varies by segment; fruits and vegetables carry tighter precision than grains due to established retail scanner data availability, while dairy projections hinge on cooperative production reporting consistency. Forecasts reflect assumptions regarding inspector capacity expansion and blockchain traceability adoption rates. Material deviation in organic fraud enforcement penalty structures or import tariff schedules on Argentine and Ukrainian feed grains warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
Organic Cocoa Market
Organic Food and Beverages
Spain Organic Food Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Organic Honey Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Organic Juice Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Germany Organic Food Market