
 United States Organic Skin Care Market | 2026-2036
United States Organic Skin Care Market Size, Share, and Industry Trends Forecast 2026-2036
United States Organic Skin Care Market Analytics
Professional spa and dermatology clinic procurement is consolidating around multi-brand distributors that service regional chains. Beautycounter leverages direct-to-consumer channel control to bypass traditional retail markups. Dr. Bronner's Magic Soaps, Inc. anchors its position through backward integration into organic ingredient sourcing. Herbivore Botanicals differentiates via minimalist formulation architecture and transparent supply chain communication.
United States organic skin care encompasses topical formulations manufactured with certified organic agricultural ingredients, typically requiring minimum organic content thresholds and prohibiting synthetic pesticides, genetically modified organisms, and petroleum-derived compounds in production. These products serve consumer demand for dermal applications with reduced chemical exposure profiles and verified environmental stewardship claims. Moisturizers occupy the largest revenue pool within product type segmentation due to daily-use frequency and premium pricing tolerance. Essential oils and plant extracts command disproportionate margin contribution within ingredient type categories, reflecting consumer willingness to pay for perceived therapeutic efficacy. Women remain the dominant end user segment, though men represent the fastest-growing demographic as gendered skincare barriers erode.
The USDA National Organic Program governs certification thresholds and labeling claims, while the FDA exercises oversight of cosmetic safety and marketing representations under the Federal Food, Drug, and Cosmetic Act. State-level regulations, including California's Proposition 65 chemical disclosure requirements, impose additional compliance burdens that favor established operators with dedicated regulatory affairs capacity. Stakeholders must monitor evolving clean beauty legislation in Congress and statehouses, as expanded ingredient disclosure mandates could reshape competitive positioning for brands with complex international supply chains.
Market Dynamics
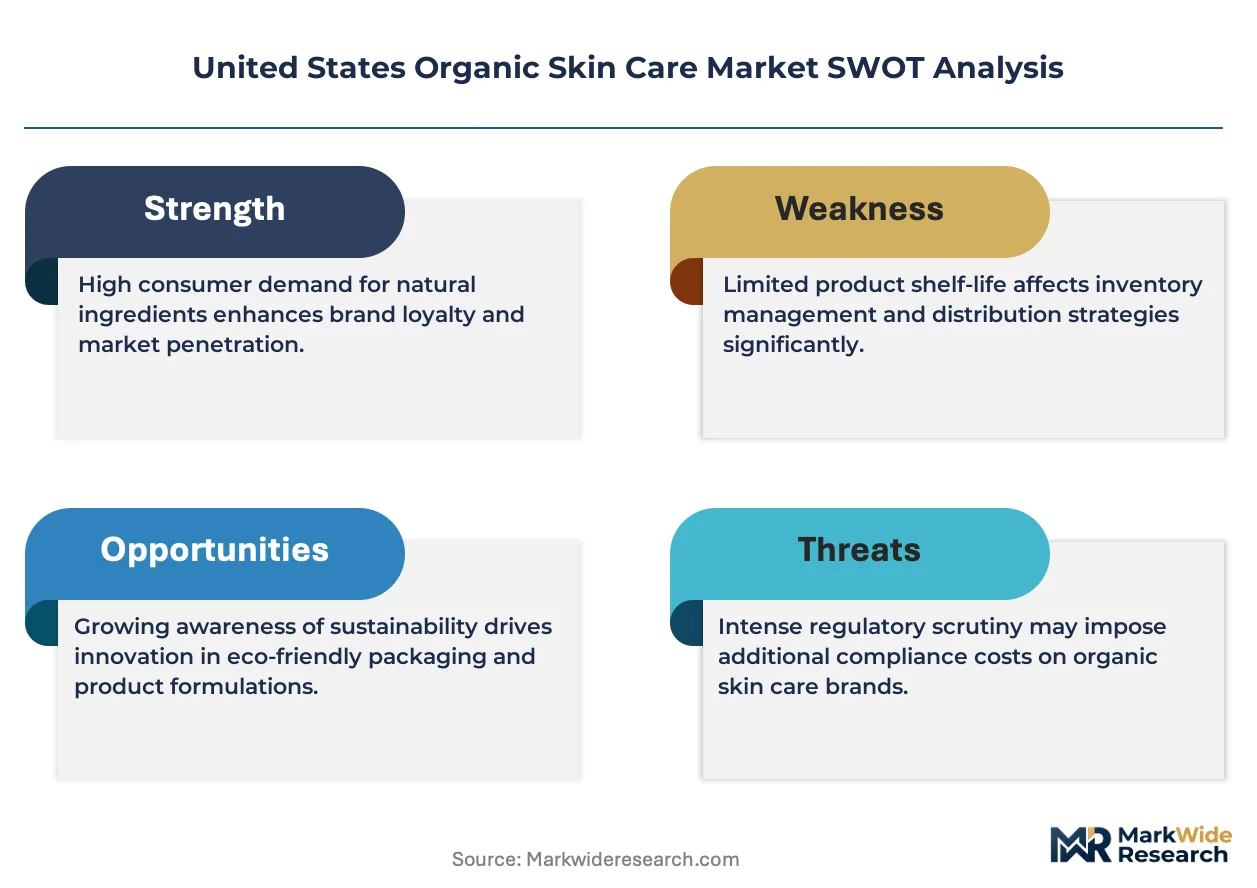
Clean beauty certification mandates from the USDA National Organic Program are compressing formulation timelines while elevating compliance costs, forcing mid-tier brands to consolidate or exit as larger operators absorb regulatory capacity investments.
Growth Catalysts
- USDA Organic Certification Thresholds:The USDA National Organic Program's strict ingredient sourcing protocols create defensible moats for certified producers. This regulatory scaffolding blocks commodity competitors from making verified organic claims.
- Millennial and Gen Z Urban Demand:Concentrated purchasing power in California, New York, and Texas metropolitan corridors sustains premium pricing tolerance. Daily-use moisturizer penetration among these demographics anchors recurring revenue pools.
- Backward Integration into Organic Agriculture:Captive supply of certified organic raw materials insulates margins from agricultural commodity volatility. Control over shea butter, jojoba, and botanical extract sourcing secures formulation consistency.
Market Restraints
- Organic Ingredient Cost Volatility:Climate-sensitive agricultural yields for lavender, rosehip, and sea buckthorn create input price instability. Weather disruptions in key growing regions compress gross margins unpredictably.
- Certification Timeline Friction:The USDA National Organic Program's multi-year accreditation process delays market entry for new formulations. This temporal barrier favors incumbents with established certification pipelines.
- Synthetic Retinol Substitution Threat:Lab-derived vitamin A compounds offer comparable efficacy at lower cost points. Price-sensitive segments increasingly tolerate non-organic active ingredients in anti-aging applications.
Strategic Opportunities
- Men's Grooming Penetration:Gendered skincare barriers are eroding fastest among millennial men in Texas and Florida urban centers. This demographic represents underexploited white space for organic moisturizers and cleansers.
- Dermatology Clinic Channel Expansion:Professional spa and clinic procurement is consolidating around multi-brand distributors. Early positioning with regional chain buyers secures institutional volume commitments.
- California Proposition 65 Compliance Differentiation:Chemical disclosure mandates beyond federal requirements favor operators with dedicated regulatory affairs capacity. Transparent supply chain communication converts compliance burden into marketing advantage.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Organic-compatible preservation systems and emulsion stability require specialized cosmetic chemistry expertise. Competition for formulators with USDA Organic Program experience intensifies compensation pressure.
- Multi-Jurisdictional Labeling Complexity:Divergent state-level chemical disclosure requirements create packaging fragmentation. California's Proposition 65 mandates conflict with other state labeling norms, forcing SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Organic Skin Care Market |
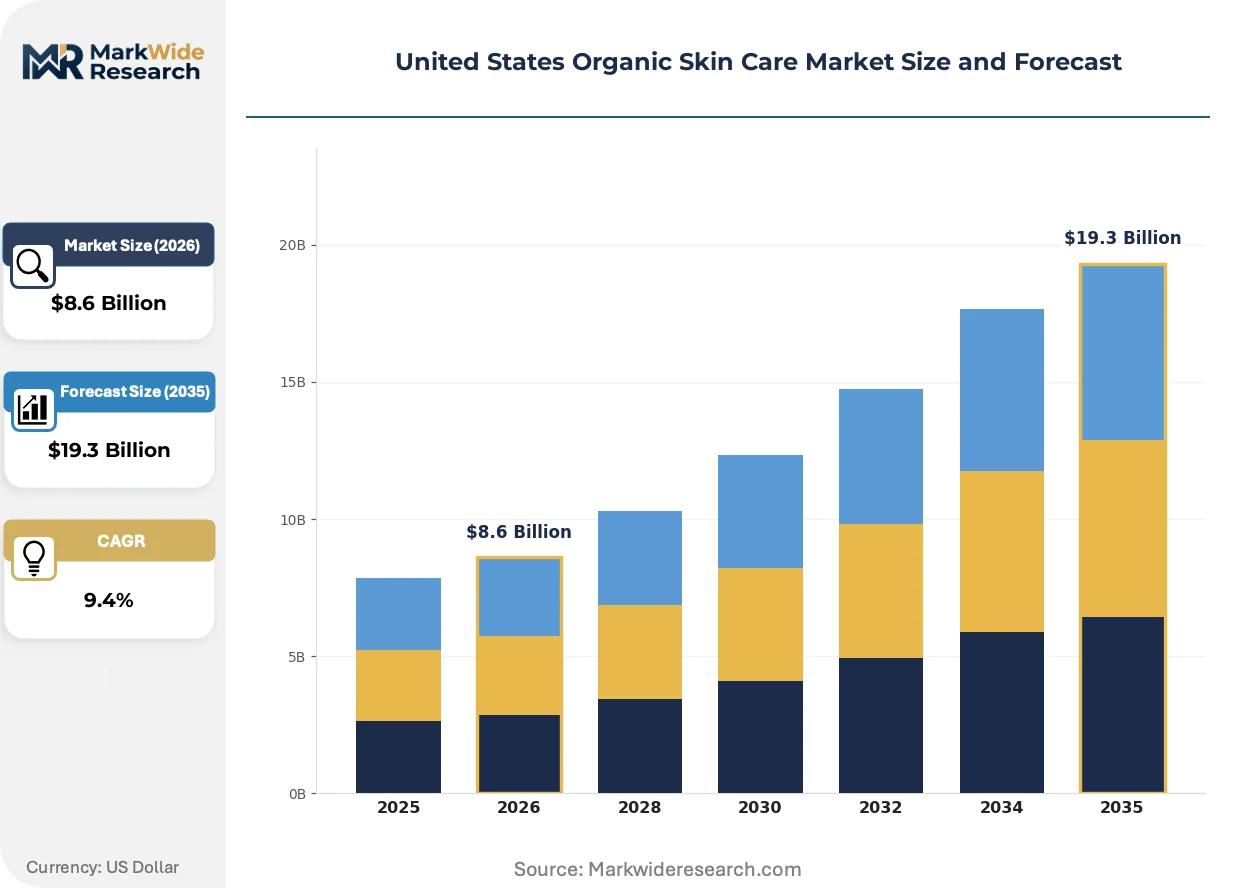
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $19.3 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Cleansers, Exfoliators Ingredient Type: Essential Oils, Plant Extracts, Botanicals, Natural Preservatives End User: Women, Men, Teens, Professionals Packaging Type: Bottles, Jars, Tubes, Pouches |
| Companies Covered | Beautycounter, Herbivore Botanicals, Dr. Bronner's Magic Soaps, Inc., OSEA, True Botanicals, The Honest Company, Inc., Weleda Inc., Indie Lee, Juice Beauty, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Organic Skin Care Market Evolving Landscape
Biotechnology-derived organic actives and AI-powered personalization engines are compressing product development cycles while fragmenting consumer expectations around efficacy proof and ingredient transparency.
Fermentation-based biotechnology is automating the production of bio-identical compounds previously extracted from rare botanicals. Mid-tier brands in California and New York are adopting cell-cultured squalane and lab-fermented hyaluronic acid to bypass agricultural supply constraints. This technology is automating cost reduction in premium organic segments while challenging traditional extraction-based supply chains.
The FDA's evolving oversight of cosmetic safety under the Federal Food, Drug, and Cosmetic Act is tightening marketing claim substantiation requirements. Brands must now maintain clinical documentation for terms like "clinically proven" that previously circulated unchecked. Moisturizer and serum categories with anti-aging positioning face the steepest compliance retrofit costs.
Direct-to-consumer subscription models are displacing traditional retail markups in urban millennial purchasing patterns. Beautycounter's channel control strategy demonstrates how bypassing Sephora and Ulta shelf fees redirects margin toward customer acquisition. This disintermediation concentrates most visibly in California and New York, where digital-native consumers prioritize convenience over tactile pre-purchase evaluation.
United States Organic Skin Care Market Segmentation
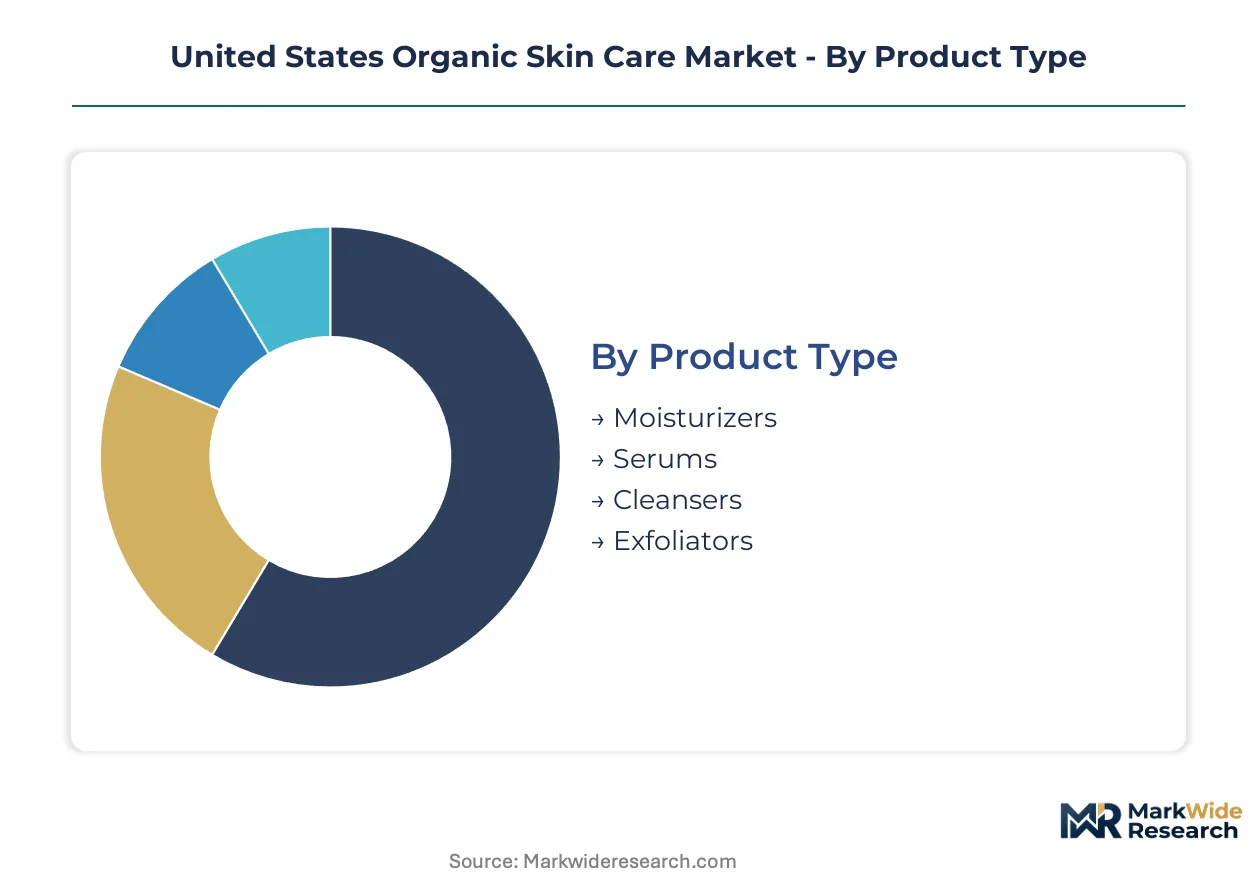
Segmentation in United States organic skin care reveals how formulation chemistry, procurement patterns, and channel economics create distinct competitive arenas. Each axis exposes different margin pressures and regulatory exposure profiles that shape operator strategy.
Product Type:
Formulation complexity and daily-use frequency determine pricing power and certification burden across topical categories.
- Moisturizers:Emulsion-based formulations combining water-phase and oil-phase organic ingredients require sophisticated preservation systems. Daily application rituals among California and New York urban millennials sustain premium price tolerance and subscription renewal rates.
- Serums:Concentrated active delivery vehicles with minimal water content emphasize bioactive density over volume. Anti-aging positioning among Texas and Florida professionals drives concentrated demand for vitamin C and peptide variants despite higher per-ounce pricing.
- Cleansers:Surfactant systems derived from coconut and sugar cane replace synthetic foaming agents.
- Exfoliators:Physical and enzymatic variants compete on gentleness claims for sensitive skin segments.
Mature deployment sits with moisturizers. Newer deployment is concentrated in serums.
Ingredient Type:
Raw material sourcing geography and agricultural yield volatility create divergent margin profiles across input categories.
- Essential Oils:Steam-distilled aromatic compounds from lavender, tea tree, and rosehip require climate-stable growing regions. California's Central Valley and Pacific Northwest cultivation zones supply domestic producers seeking reduced import dependency.
- Plant Extracts:Solvent-free concentration methods preserve polyphenol and flavonoid integrity. Demand from dermatology clinic channels in Texas and Florida favors standardized extract potency for professional treatment protocols.
- Botanicals:Whole-plant powders and freeze-dried preparations offer formulation versatility.
- Natural Preservatives:Rosemary extract and grapefruit seed derivatives replace synthetic parabens in clean-label formulations.
Established volume concentrates in essential oils. Expanding most quickly are plant extracts.
End User:
Gendered purchasing rituals and professional application contexts fragment marketing investment and channel selection.
- Women:Multi-step regimen adherence supports cross-selling of complementary products across moisturizers, serums, and cleansers. Urban coastal concentrations in California and New York sustain highest per-capita spending on USDA-certified organic tiers.
- Men:Simplified routine preferences favor all-in-one moisturizers with SPF integration. Texas and Florida metropolitan corridors show steepest adoption curves as gendered skincare stigma erodes among millennials.
- Teens:Acne-focused organic formulations compete with conventional benzoyl peroxide products on irritation reduction claims.
- Professionals:Spa and clinic workers purchase institutional volumes for treatment applications.
Volume leadership rests with women. Gaining share fastest are men.
Packaging Type:
Material sustainability claims and dispensing precision requirements drive format selection and regulatory compliance burden.
- Bottles:Glass and post-consumer recycled plastic formats dominate serum and oil presentations. California's Proposition 65 chemical disclosure mandates favor suppliers with transparent packaging material sourcing documentation.
- Jars:Wide-mouth configurations accommodate thick cream and balm textures. Airless pump variants address preservative-free formulation stability concerns in professional spa environments.
- Tubes:Aluminum and sugarcane-derived plastics serve travel-size and sample formats.
- Pouches:Flexible refill formats reduce shipping weight for direct-to-consumer subscription models.
Established infrastructure favors bottles. Emerging adoption centers on pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban coastal metros concentrate purchasing power for certified organic formulations. State-level disclosure mandates and agricultural sourcing corridors reshape competitive positioning across sub-regional markets.
California
Los Angeles and San Francisco Bay Area consumers drive premium moisturizer subscription volumes. Proposition 65 chemical disclosure requirements exceed federal standards and favor operators with dedicated compliance infrastructure. Central Valley organic agriculture clusters supply domestic lavender and botanical extracts to regional formulators.
New York
Manhattan and Brooklyn demographics sustain highest per-capita spending on USDA-certified organic tiers. State-level clean beauty legislation pending in Albany threatens additional labeling burdens for interstate brands. Hudson Valley cultivation cooperatives are expanding cold-pressed oil production for local skincare manufacturing.
Texas
Dallas-Fort Worth and Houston millennial men represent the fastest-growing demographic for simplified organic grooming routines. FDA oversight of cosmetic marketing claims under the Federal Food, Drug, and Cosmetic Act shapes professional clinic procurement standards. Austin's direct-to-consumer brand density is compressing traditional retail channel relevance.
Florida
Miami and Tampa professionals drive dermatology clinic channel demand for standardized botanical extracts. State agricultural extension programs support organic sea buckthorn and citrus cultivation for cosmetic applications. Palm Beach spa procurement consolidation favors multi-brand distributors with regional logistics capacity.
Pacific Northwest
Seattle and Portland consumers prioritize transparent supply chain communication and packaging sustainability claims. USDA National Organic Program certification requirements anchor formulation standards for regional clean beauty brands. Willamette Valley organic herb cultivation supports domestic essential oil distillation capacity.
United States Organic Skin Care Market Competitive Landscape
California-based direct-to-consumer specialists anchor one tier; legacy natural product manufacturers with captive agriculture hold formulation consistency advantages. The vendor base stratifies across certification-heavy premium positioning, minimalist clean-label architecture, and scale-driven mass-market penetration. Three archetypes dominate: vertically integrated agriculture-to-shelf operators, digital-native subscription brands, and multi-channel clean beauty platforms. Competitive moves concentrate on backward integration into organic ingredient sourcing and professional channel distributor consolidation.
Within the vertically integrated tier, Dr. Bronner's Magic Soaps, Inc. exemplifies captive supply chain control over organic raw materials. Beautycounter and Herbivore Botanicals occupy positions at the digital-native and minimalist-formulation extremes respectively, representing divergent paths to consumer trust building through channel control and transparent ingredient architecture.
| Leading Market Players |
|---|
| Beautycounter |
| Herbivore Botanicals |
| Dr. Bronner's Magic Soaps, Inc. |
| OSEA |
| True Botanicals |
| The Honest Company, Inc. |
| Weleda Inc. |
| Indie Lee |
| Juice Beauty, Inc. |
| Others |
Value Network & Pricing Analysis
Captive supply of certified organic raw materials anchors both margin stability and pricing power for established operators, insulating them from agricultural commodity volatility while compressing entry economics for aspirants lacking backward integration into shea butter, jojoba, and botanical extract sourcing.
Pricing Analysis
Volume leadership sits with mass-market moisturizers while margin concentration favors serum and essential oil tiers. Three-tier pricing structure across USDA-certified premium, clean-label standard, and conventional economy levels separates segments by certification burden and ingredient provenance. Pricing pressure stems from lab-derived retinol substitutes eroding organic premium justification in anti-aging applications. Texas and Florida millennial men exhibit highest price sensitivity, whereas Manhattan and Los Angeles urban women sustain lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Pacific Northwest and California Central Valley lavender cultivation, where climate-sensitive yields create unpredictable input availability. Domestic sourcing draws from Oregon, Washington, and California agricultural clusters, supplemented by Moroccan argan and Madagascan vanilla imports. Tariff exposure on botanical extracts from key growing regions threatens margin compression. Distribution runs through direct-to-consumer subscription platforms, professional spa distributors, and Sephora-Ulta retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USDA National Organic Program certification capacity constraints prop pricing power by throttling new entrant supply, creating a supply-constrained market structure favoring incumbents with established accreditation pipelines.
For Market Incumbents: Anchor market position through captive cultivation expansion in California Central Valley and Pacific Northwest growing regions. Deepen backward integration into organic agriculture to defend against synthetic retinol substitution threats in anti-aging segments. Prioritize regulatory affairs capacity investment to convert California Proposition 65 compliance burden into marketing differentiation.
For New Entrants and Emerging Players: Capture white space in Texas and Florida millennial men's grooming routines, where gendered skincare barriers erode fastest. Target simplified moisturizer-SPF combinations for this demographic's preference for minimal-step regimens. Deploy direct-to-consumer subscription models to bypass Sephora and Ulta shelf fee structures that compress margins for unproven brands.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multi-brand clean beauty platforms seeking USDA certification infrastructure. Five-to-ten year viability hinges on regulatory moat durability rather than brand equity alone. Monitor FDA marketing claim substantiation enforcement intensity as inflection indicator for compliance cost trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Agriculture | Captive supply of shea butter and jojoba insulates margins from climate-driven yield volatility. |
| Direct-to-Consumer Channel Launch | Bypassing Sephora and Ulta shelf fees redirects margin toward customer acquisition in California and New York. |
| USDA Organic Certification Investment | Regulatory scaffolding blocks commodity competitors from making verified organic claims. |
| Dermatology Clinic Distributor Partnership | Professional channel consolidation favors early positioning with regional multi-brand buyers. |
| Men's Grooming Line Extension | Texas and Florida millennial men represent fastest-growing demographic with underexploited white space. |
Research Methodology
Document review covered FDA cosmetic safety guidance, USDA National Organic Program certification standards, California Proposition 65 chemical disclosure requirements, and state-level clean beauty legislation, complemented by interviews with organic formulation chemists, brand regulatory affairs directors, Sephora category buyers, professional spa procurement managers, and Central Valley organic agriculture cooperatives. Secondary validation drew from customs records, Nielsen retail audit data, and SEC filings of publicly traded personal care companies. Bottom-up demand modeling and top-down supply capacity estimates underwent cross-referencing triangulation.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to construct analytical framework projections across the analysis window. Segmentation dimensions modeled include product type, ingredient category, end-user demographic, packaging format, and regional metropolitan corridor. CAGRs were derived from regression analysis of historical penetration rates and demographic spending elasticity. Key inputs included USDA certification pipeline capacity constraints and FDA marketing claim enforcement intensity.
The model holds under stable USDA accreditation timelines and continued California Proposition 65 enforcement; deviation in federal clean beauty legislation or climate disruption in Pacific Northwest growing regions would shift trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Japan Organic Food Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
Organic Food and Beverages Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Spain Organic Food Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Global Organic Packaged Food Market
Organic Food and Beverages
Global Natural and Organic Food Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Australia Organic Beverages Market