
 Organic Soy Products Market | 2026-2036
Organic Soy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Soy Products Market Analytics
Subscription-based replenishment services for organic soy milk and tofu are expanding the recurring revenue layer beyond one-time retail purchases. SunOpta Inc leverages its vertically integrated supply chain from organic soybean sourcing to finished beverage production. The Hain Celestial Group, Inc anchors its portfolio with branded organic soy milk lines distributed through mass retail and natural channels. Archer Daniels Midland Company competes as a bulk ingredient supplier, extending its reach into organic soy protein isolates for food manufacturers.
Organic soy products comprise non-genetically modified soybeans cultivated without synthetic pesticides or fertilizers, processed into food-grade proteins, oils, and fibers with specified nitrogen solubility indices for functional applications. These materials serve as emulsifiers, texturizers, and complete protein sources across human nutrition, personal care formulations, and livestock feed compounding. Soy milk and tofu command the largest share of consumer-facing revenue, while soy flour and tempeh represent faster-growing niches driven by clean-label bakery and fermented-food trends. The powder and liquid forms dominate industrial procurement, though granulated isolates are gaining traction in nutraceutical encapsulation where solubility standards are stringent.
The USDA National Organic Program and EU Organic Regulation define cultivation and labeling standards that determine market access for imported soybeans and finished goods. The FDA and EFSA evaluate health claims and allergen labeling requirements that shape product positioning and reformulation costs. Stakeholders must monitor evolving maximum residue limits under the EU Green Deal and state-level organic certification variations across the United States. Forward-looking participants should track how tightening traceability mandates will reconfigure sourcing relationships between North American growers and Asian processing hubs.
Market Dynamics
The EU Green Deal's tightening pesticide residue thresholds for organic imports are redirecting procurement toward certified domestic growers, compressing sourcing windows and elevating traceability costs across the value chain.
Growth Catalysts
- EU Farm to Fork Strategy:Mandates for reduced chemical inputs in food production accelerate organic soybean acreage expansion across Germany, France, and Italy.
- Plant-based meat analogue demand:Food manufacturers in Germany and the Netherlands widen formulation trials with organic soy protein isolates for clean-label burger and sausage applications.
- Fermented-food wellness trend:Tempeh production capacity is scaling in Denmark and Belgium as retail chains allocate dedicated chilled-set space.
Market Restraints
- Organic soybean input cost volatility:Weather-driven yield fluctuations in Ukraine and Russia elevate price instability for European crush facilities.
- Single-source dependency risk:Organic lecithin supply concentrates among a limited set of Black Sea region processors.
- Protein functionality gaps:Organic soy isolates exhibit lower nitrogen solubility indices than conventional equivalents, limiting application in high-performance emulsification.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Romania show accelerating retail velocity for organic soymilk as modern trade formats expand.
- Regenerative agriculture certification overlap:The EU's Carbon Farming Initiative creates dual-certification premiums for organic soybeans meeting soil carbon sequestration protocols.
- Direct-to-consumer fermentation kits:Subscription models for home tempeh and natto production bypass conventional retail margin structures.
Industry Challenges
- Multi-year organic conversion timelines:Farmers face 24-36 month certification gaps without revenue continuity during soil transition periods.
- Cross-border traceability system integration:Blockchain-based provenance tracking requires interoperability between national organic certification databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Soy Products Market |
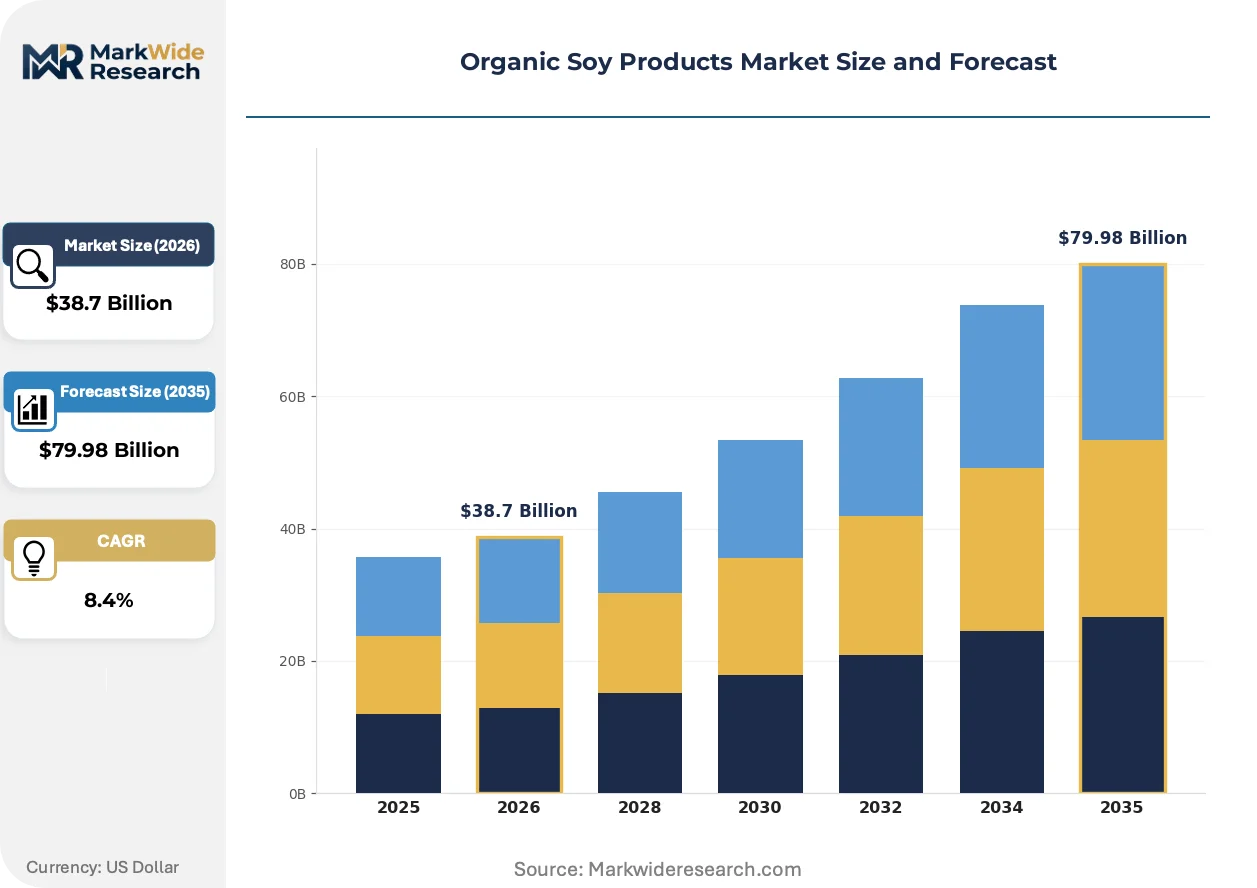
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Milk, Tofu, Tempeh, Soy Flour Application: Food & Beverages, Nutraceuticals, Personal Care, Animal Feed Form: Liquid, Solid, Powder, Granulated Distribution Channel: Supermarkets, Online Stores, Health Food Shops, Farmers' Markets |
| Companies Covered | SunOpta Inc, The Hain Celestial Group, Inc, Archer Daniels Midland Company, Cargill, Inc, Devansoy Inc, The Scoular Company, Harvest Innovations, Eden Foods, Inc, Nasoya Foods, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Soy Products Market Evolving Landscape
Processing technology and certification protocols are reshaping competitive advantage in organic soy, with functionality and transparency emerging as the primary axes of differentiation.
High-pressure processing is converging with enzymatic modification to improve organic soy protein solubility without synthetic chemical inputs. Nutraceutical encapsulators in Switzerland and Germany are piloting these hybrid systems for protein-fortified functional beverages. The structural consequence is compressing the performance gap between organic and conventional isolates.
REACH chemical registration requirements and the EU F-Gas Regulation are tightening solvent recovery mandates for organic soy oil extraction facilities. German and Dutch processors face capital outlays for closed-loop hexane recovery systems. The edible oil segment is responding by accelerating investment in mechanical pressing alternatives.
Retail procurement patterns are consolidating toward vertically integrated private-label suppliers with captive organic acreage. German discounters and premium chains alike are shortening supplier lists to those offering batch-level DNA verification. This concentration is most visible in the refrigerated tofu and soymilk categories where shelf-space allocation now favors integrated players.
Organic Soy Products Market Segmentation
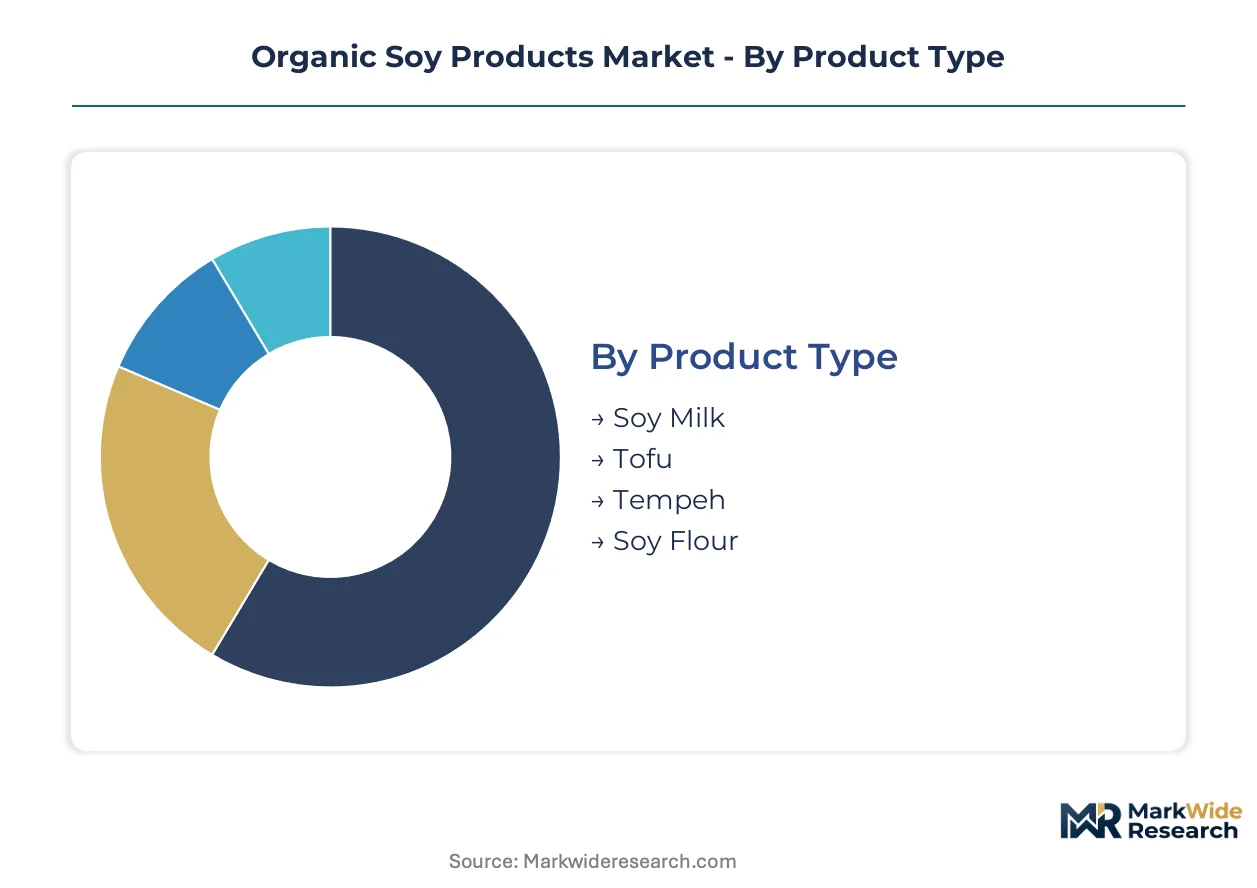
Organic soy products fragment across four distinct category axes, each reflecting divergent buyer priorities from functional performance to procurement convenience. Manufacturers must calibrate formulation, packaging, and channel strategy against these segment boundaries to capture value.
Product Type:
Buyers in this category differentiate by processing intensity and perishability tolerance, with shelf-stable formats commanding premium positioning against fresh alternatives.
- Soy Milk:Ultra-high temperature processed beverages with specified protein dispersion stability above 95%. German and Dutch retail chains now allocate dedicated chilled and ambient shelf blocks for barista-grade formulations. Demand concentrates in North American mass-market channels where barista functionality drives repeat purchase.
- Tofu:Coagulated protein curds with moisture content ranging from soft (85% water) to extra-firm (70% water). Japanese and Korean restaurant supply chains in Los Angeles and New York specify texture profiles for specific culinary applications. Clean-label positioning in European premium retail is displacing conventional tofu volumes.
- Tempeh:Whole-bean fermented cakes with Rhizopus oligosporus inoculation, offering complete protein with fiber retention. Danish and Belgian production facilities are scaling capacity for European retail distribution.
- Soy Flour:Defatted or full-fat milled meal with specified particle size distributions for bakery and extrusion applications. Clean-label bakery trends in France and Italy are accelerating procurement.
Soy milk leads volumes today; tempeh is gaining share fastest.
Application:
End-use concentration determines specification stringency, with pharmaceutical-grade isolates demanding nitrogen solubility indices that food applications rarely require.
- Food & Beverages:Formulations spanning meat analogues, dairy alternatives, and bakery applications with emulsification and texturization requirements. German plant-based meat manufacturers specify organic isolates for clean-label burger applications.
- Nutraceuticals:Protein fortification of functional beverages and meal replacements with stringent heavy metal and microbial specifications. Swiss encapsulation facilities pilot high-pressure processed organic isolates.
- Personal Care:Lecithin-derived emollients and protein hydrolysates for hair and skin conditioning. EU REACH registration requirements are elevating documentation burdens.
- Animal Feed:Organic soy meal for livestock compounding with specified amino acid profiles. Premium layer hen operations in the Netherlands specify organic feed for egg certification.
Food and beverages dominates current procurement; nutraceuticals shows the steepest expansion trajectory.
Form:
Logistics economics and reconstitution behavior separate buyers, with powder formats offering freight efficiency against liquid convenience premiums.
- Liquid:Ready-to-consume beverages and culinary preparations with aseptic packaging requirements. German discounters and premium chains alike are consolidating supplier lists toward integrated private-label producers.
- Solid:Refrigerated or frozen tofu and tempeh blocks with defined shelf-life parameters. Retail velocity in Polish and Romanian modern trade formats is accelerating.
- Powder:Spray-dried protein isolates and flours with specified bulk density for industrial handling. Industrial procurement from North American and European food manufacturers concentrates here.
- Granulated:Agglomerated isolates for nutraceutical encapsulation where solubility standards are most stringent. Swiss and German pilot facilities are testing hybrid enzymatic modification systems.
Powder commands industrial procurement volumes; granulated formats are climbing the fastest in nutraceutical applications.
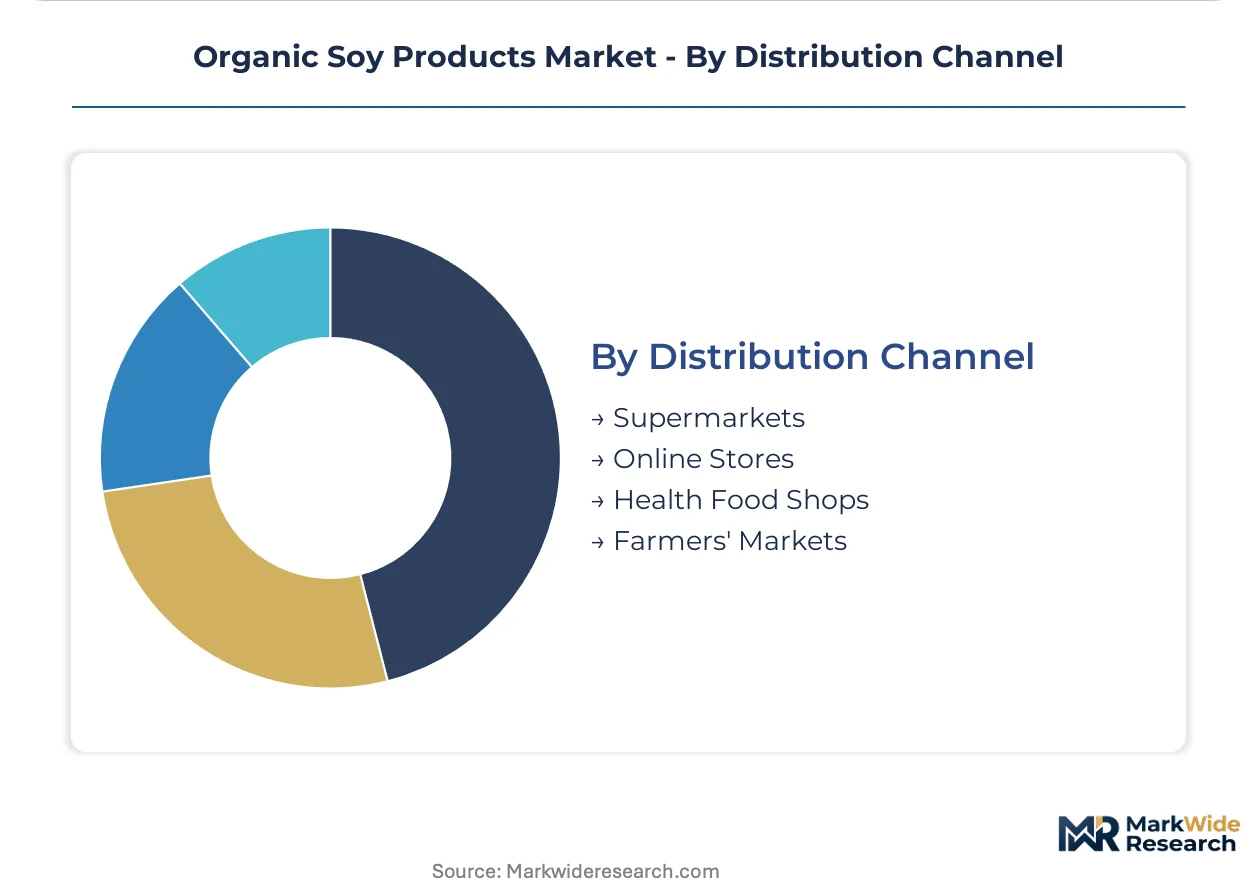
Distribution Channel:
Buyer proximity to production and information requirements shape channel selection, with traceability demands highest in direct and specialty formats.
- Supermarkets:Mass retail with refrigerated and ambient shelf allocation determined by scan velocity. German retail chains have widened shelf space for organic tofu and tempeh lines.
- Online Stores:Subscription-based replenishment services for organic soy milk and tofu expanding recurring revenue beyond one-time purchases. Direct-to-consumer fermentation kits for home tempeh production bypass conventional margin structures.
- Health Food Shops:Specialty retail with educated staff and batch-level provenance verification. DNA verification capabilities now influence supplier selection.
- Farmers' Markets:Direct producer-consumer interfaces with minimal intermediation. Regional organic certification visibility drives purchase decisions.
Supermarkets anchor volume today; online stores are expanding most quickly through subscription mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands retail shelf space for organic tofu and tempeh while the United States drives mass-market procurement of organic soy proteins for plant-based meat analogues.
Germany
Retail chains have widened refrigerated shelf allocations for organic tofu and tempeh lines as consumer demand for fermented foods accelerates. The EU Green Deal and Farm to Fork strategy mandate reduced chemical inputs, tightening pesticide residue thresholds for organic imports. Production facilities in Bavaria and North Rhine-Westphalia are scaling capacity to meet domestic sourcing requirements.
United States
Food and beverage manufacturers expand procurement of organic soy proteins for plant-based meat analogues across mass retail and foodservice channels. The USDA National Organic Program defines cultivation and labeling standards that determine market access for domestic and imported soybeans. Processing clusters in the Midwest and California anchor organic soy milk and isolate production for national distribution.
Netherlands
Plant-based meat manufacturers in the Netherlands widen formulation trials with organic soy protein isolates for clean-label burger and sausage applications. EFSA allergen labeling requirements shape product positioning and reformulation costs for exporters. Rotterdam and Amsterdam serve as distribution hubs connecting North American organic soybean imports to European processing facilities.
Denmark
Tempeh production capacity is scaling as retail chains allocate dedicated chilled-set space for fermented organic soy products. REACH chemical registration requirements elevate documentation burdens for lecithin-derived ingredients in personal care applications. Copenhagen anchors Nordic distribution networks for organic soy beverages and fermented foods.
France
Clean-label bakery trends accelerate procurement of organic soy flour for extrusion and particle-size-specific applications in artisan and industrial baking. The EU Organic Regulation determines labeling standards for imported organic soybeans and finished goods. Lyon and Paris metropolitan areas concentrate food manufacturing demand for organic soy isolates and emulsifiers.
Organic Soy Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated players capturing refrigerated shelf space while bulk ingredient suppliers serve industrial formulation demand. The vendor base concentrates around three strategic archetypes: captive organic acreage operators, toll-processing specialists, and branded portfolio companies. M&A activity targets organic certification assets and fermentation technology capabilities. Capacity expansion focuses on high-pressure processing lines for protein isolate functionality improvement.
Among North American branded specialists, SunOpta Inc and The Hain Celestial Group, Inc exemplify the integrated supply chain archetype spanning organic soybean sourcing through finished beverage production. Archer Daniels Midland Company occupies a position as a bulk ingredient supplier extending into organic soy protein isolates for food manufacturers. These three companies represent the dominant competitive configurations: backward integration into captive organic acreage, branded mass-market distribution, and industrial-scale ingredient supply.
| Leading Market Players |
|---|
| SunOpta Inc |
| The Hain Celestial Group, Inc |
| Archer Daniels Midland Company |
| Cargill, Inc |
| Devansoy Inc |
| The Scoular Company |
| Harvest Innovations |
| Eden Foods, Inc |
| Nasoya Foods, Inc |
| Others |
Value Network & Pricing Analysis
EU Farm to Fork Strategy mandates for reduced chemical inputs are compressing certified organic acreage availability, forcing processors to bid up contract premiums with German and French growers and widening price spreads against conventional soy inputs.
Pricing Analysis
Capacity additions in Denmark and Belgium are reshaping price floors for fermented organic soy products. Three-tier pricing structure across premium certified-organic, transitional-organic, and conventional-conversion tiers reflects certification grade and traceability depth. Pricing pressure stems from weather-driven yield volatility in Black Sea sourcing regions. Industrial food manufacturers exhibit highest price sensitivity due to formulation cost targets, while nutraceutical encapsulators absorb premiums for solubility-guaranteed isolates.
Supply Chain Analysis
Direct-to-processor channels handle hyperscale demand from German and Dutch plant-based meat manufacturers. Raw material flows draw from organic soybean cultivation in Germany, France, and Italy, with lecithin processing concentrated in Black Sea facilities. Supply chain risk centers on single-source dependency for organic lecithin extraction capacity. Distribution runs through Rotterdam and Amsterdam hubs connecting North American imports to European crush facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic soy products market compounds steadily as regulatory tailwinds from the EU Green Deal entrench domestic sourcing requirements across member states.
For Market Incumbents: Extend backward integration into captive organic acreage in Bavaria and North Rhine-Westphalia to defend against traceability cost inflation. Secure multi-year offtake agreements with regenerative-certified growers before Carbon Farming Initiative premiums fully price into land values. Invest in high-pressure processing lines to close nitrogen solubility gaps versus conventional isolates. For New Entrants and Emerging Players: Begin with direct-to-consumer fermentation kits for home tempeh production, bypassing retail margin structures entirely. Poland and Romania offer the most penetrable geography as modern trade formats expand shelf space. Anchor go-to-market strategy through subscription-based replenishment mechanics that build recurring revenue visibility. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale organic certification assets in Eastern Europe where EU subsidy flows are accelerating conversion timelines. Five-to-ten year viability rests on securing processing capacity with dual organic-regenerative certification. Monitor EU maximum residue limit enforcement actions as the inflection signal for sourcing relationship reconfigurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acreage | Captive supply from German growers satisfies EU Farm to Fork traceability mandates. |
| High-Pressure Processing Capacity Expansion | Hybrid enzymatic systems close organic isolate solubility gaps for Swiss nutraceutical buyers. |
| Regenerative Agriculture Dual Certification | Carbon Farming Initiative premiums reward soil carbon sequestration protocols in French operations. |
| Direct-to-Consumer Fermentation Kit Launch | Subscription models bypass conventional retail margin compression in Danish markets. |
| Blockchain Traceability System Deployment | Batch-level DNA verification meets German discounter procurement consolidation requirements. |
Research Methodology
Multiple input streams — primary interviews with organic certification officers, plant-based food formulators, and agricultural procurement leads; secondary validation against EU organic trade databases, USDA National Organic Program filings, and customs import records; plus industry association acreage reports — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from ingredient procurement directors across the projection horizon. Segmentation dimensions modeled include product type, application end-use, physical form, and distribution channel, with regional regulatory cluster overlays for EU member state variations. CAGRs were derived from trend extrapolation moderated by acreage conversion timelines and processing capacity buildout schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption to Black Sea organic lecithin flows and abrupt EU pesticide residue threshold accelerations. Forecasts reflect base-case assumptions regarding certification timeline stability and consumer willingness-to-pay premiums. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Australia Organic Beverages Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
Organic Food and Beverages Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Organic Fast Food Market
Organic Food and Beverages
Organic Yogurt Market