
 Organic Acai Juice Market | 2026-2036
Organic Acai Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Acai Juice Market Analysis
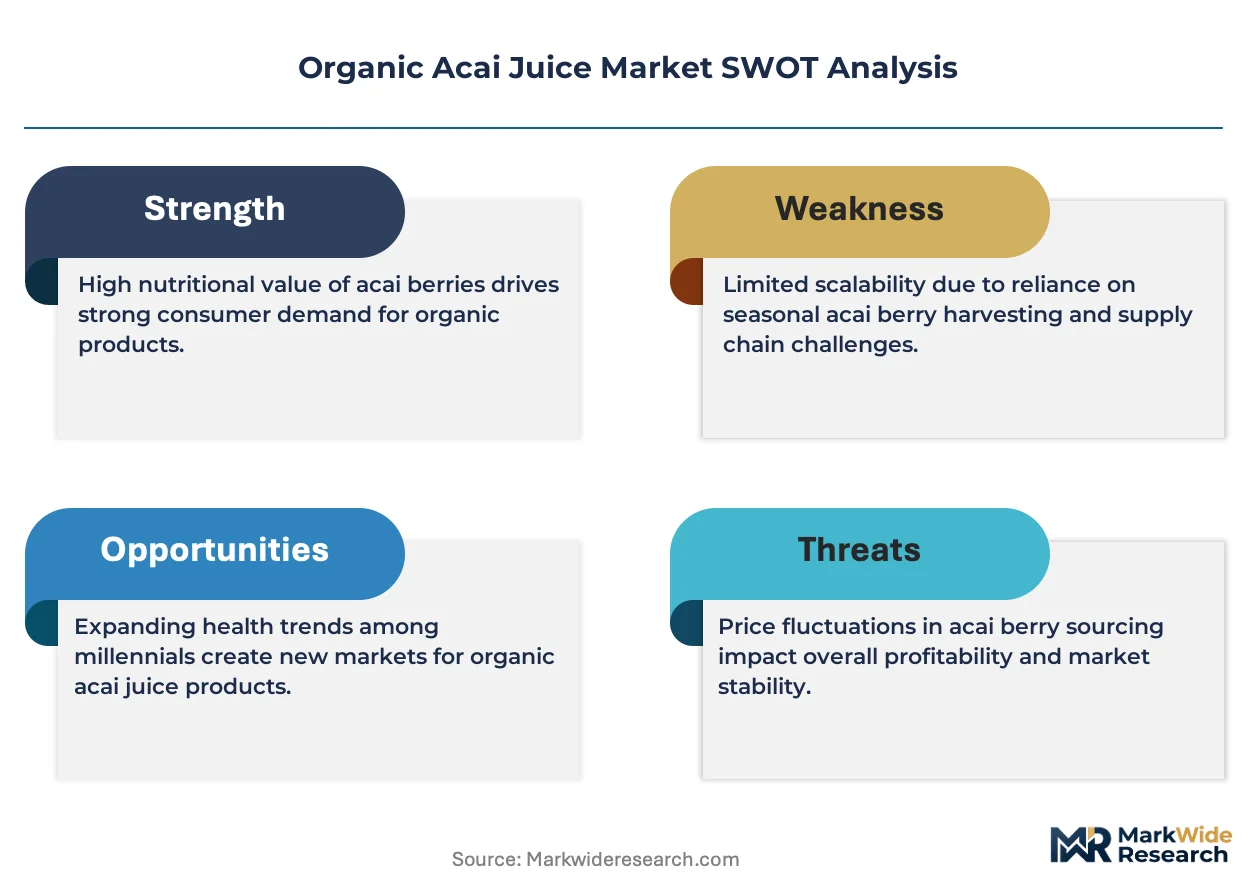
A wide capital-intensity divergence between players is reorganizing competitive hierarchy in organic acai juice. Sambazon leverages its captive Brazilian supply network to control raw material flows from the Amazon basin. Holland & Barrett Retail Limited anchors its position through dedicated shelf space across hundreds of UK health stores. Nativo Acai differentiates via specialized relationships with fitness centers and boutique wellness channels.
Organic acai juice is a dark purple beverage extracted from Euterpe oleracea berries, typically containing anthocyanin levels above standard fruit juices and processed through flash pasteurization or cold-press methods to preserve antioxidant activity; it serves functional beverage and nutritional supplement applications. Juice blend formulations capture the broadest consumer base by masking acai's earthy intensity with complementary fruits. Bottles dominate packaging type due to premium positioning and resealability for health enthusiasts. Online stores represent the fastest-expanding distribution channel as direct-to-consumer subscription models gain traction among repeat buyers.
USDA Organic certification governs domestic market access for products sold in the United States, while EU Organic Regulation and EFSA labeling requirements shape European commercialization standards. These frameworks elevate compliance costs but simultaneously filter out non-certified competitors, tightening legitimate supply. Stakeholders must monitor evolving organic integrity enforcement and emerging sustainability audits as baseline requirements for shelf placement expand.
Market Dynamics
Captive sourcing networks in Brazil's Amazon basin are compressing margins for non-integrated processors while health-conscious consumers demand traceable supply chains. This upstream concentration forces mid-tier brands to accept price volatility or exit.
Growth Catalysts
- EU Organic Regulation:Mandatory certification requirements filter out uncertified competitors, tightening legitimate supply and elevating price premiums for compliant producers across European retail channels.
- Fitness center distribution:Boutique wellness channels and specialized gym partnerships create direct access to health enthusiasts seeking functional post-workout recovery beverages.
- Cold-press processing:Non-thermal extraction methods preserve anthocyanin bioactivity, enabling premium positioning against heat-treated commodity juices in functional beverage aisles.
Market Restraints
- Para state supply concentration:Raw acai berry sourcing clusters in a single Brazilian region, exposing processors to climate disruption, logistics bottlenecks, and localized price shocks.
- USDA Organic compliance costs:Certification audits, documentation requirements, and annual inspections impose fixed cost burdens that disproportionately squeeze small-batch producers.
- Flash pasteurized substitutes:Lower-cost conventional berry blends with synthetic fortification capture price-sensitive consumers in mass retail channels.
Strategic Opportunities
- Direct-to-consumer subscriptions:Online stores with recurring delivery models lock in repeat buyers and bypass retail slotting fees that erode margins in conventional grocery.
- EFSA health claim pathways:Pending antioxidant benefit approvals would unlock premium positioning in European markets currently restricted by functional food labeling constraints.
- Flash-freeze pulp formats:Frozen single-serve packets target home smoothie preparation, expanding beyond ready-to-drink into ingredient applications for health-focused households.
Industry Challenges
- Organic integrity verification:Supply chain documentation gaps and fraudulent certification schemes threaten consumer trust and invite enforcement actions from USDA and EU control bodies.
- Cold-chain capex requirements:Maintaining sub-zero temperatures from harvest through distribution demands refrigerated transport fleets and specialized storage infrastructure that strains working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Acai Juice Market |
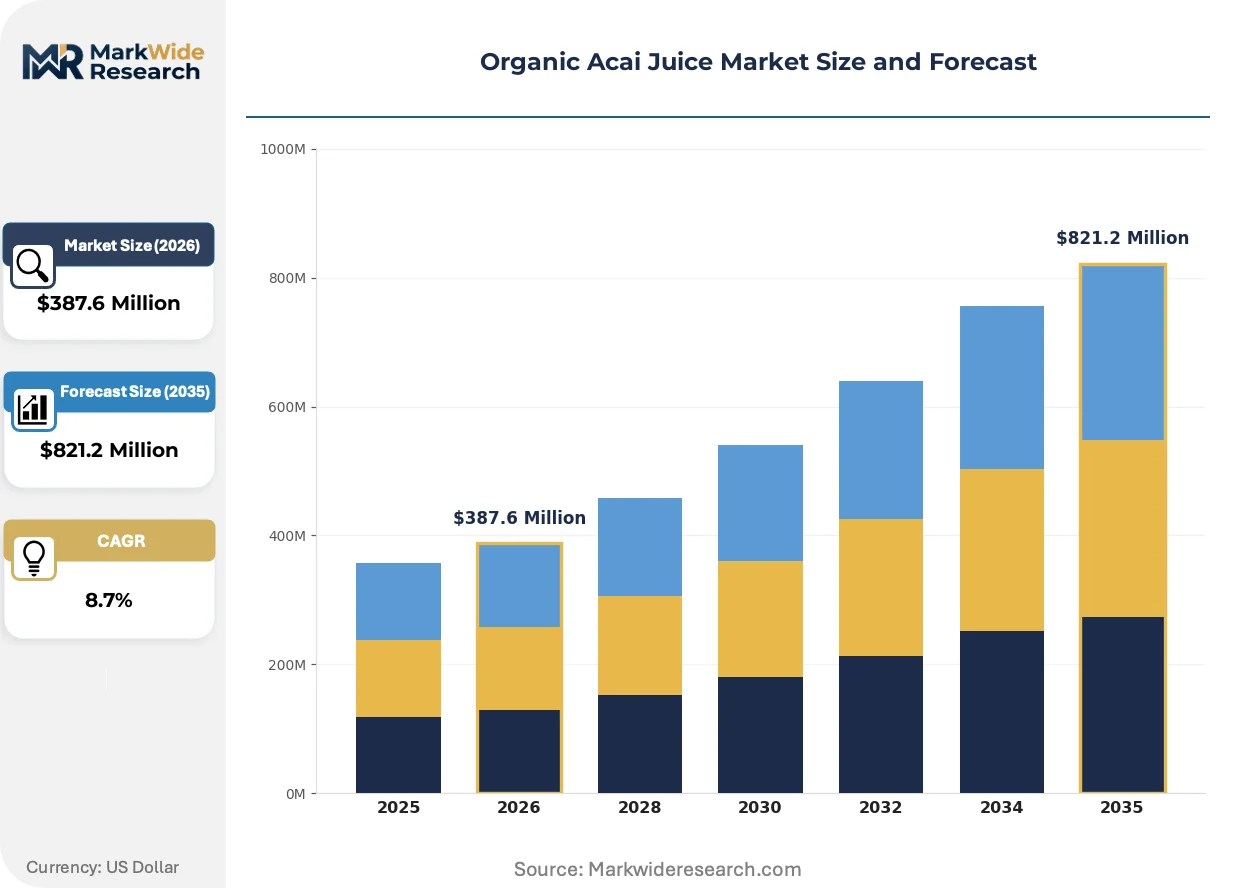
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Juice, Juice Blend, Concentrate, Powder Packaging Type: Bottles, Tetra Packs, Cans, Pouches Distribution Channel: Retail Stores, Online Stores, Wholesale, Direct Sales End User: Health Enthusiasts, Fitness Centers, Restaurants, Bakeries |
| Companies Covered | Sambazon, Acai Roots, R.W. Knudsen Family, Mama Toucan’s, Organique Acai, The Berry Company Limited, Nativo Acai, Holland & Barrett Retail Limited, Zola, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Acai Juice Market Emerging Trajectories
Processing technology and certification protocols are reshaping how organic acai juice moves from harvest to consumption. Three convergent developments are compressing legacy production models while opening new premium tiers.
High-pressure processing (HPP) systems are miniaturizing from industrial-scale batch units to modular line extensions suitable for mid-volume co-packers. Regional juice processors in Florida and California are adopting these compact systems to offer toll pasteurization services, lowering entry barriers for brands seeking extended shelf life without thermal degradation. This equipment diffusion is fragmenting processing capacity away from concentrated mega-facilities.
EFSA's evolving stance on polyphenol health claims is tightening substantiation requirements for antioxidant marketing in European markets. Manufacturers must now compile clinical trial dossiers or retreat to generic wellness positioning, compressing margins for brands dependent on functional differentiation. German and Dutch retailers are responding by demanding third-party ORAC verification before granting premium shelf placement.
Subscription-based replenishment cycles are displacing intermittent grocery purchasing among core health enthusiasts. Direct-to-consumer platforms capture recurring revenue while gathering consumption data that informs flavor development and seasonal promotions. This pattern is most pronounced in US coastal metropolitan markets where delivery logistics density supports same-day fulfillment.
Organic Acai Juice Market Segmentation
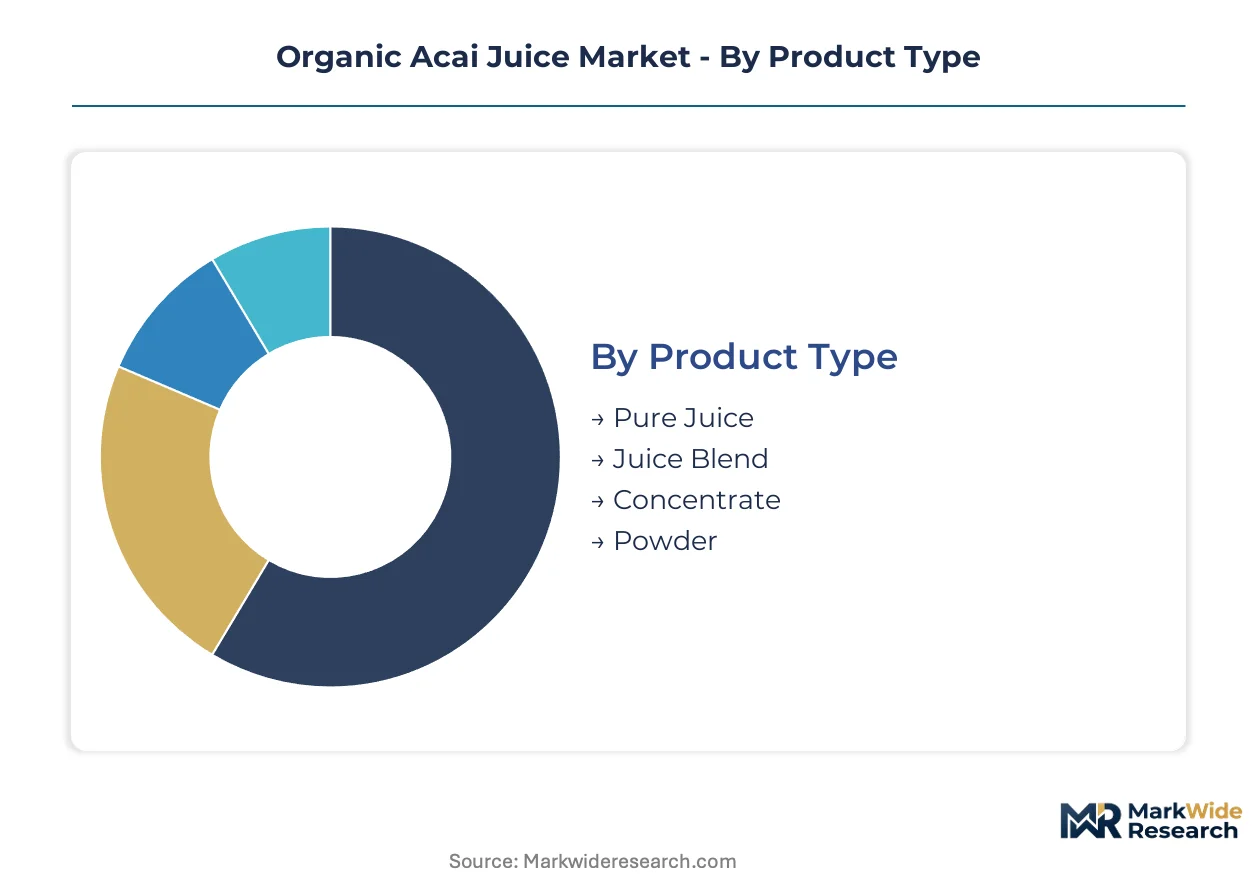
Organic acai juice segmentation reflects divergent compliance burdens and channel economics. Product formulation, packaging durability, and end-user sophistication create distinct margin profiles that reward specialized positioning over undifferentiated volume plays.
Product Type:
USDA Organic and EU Organic Regulation impose tiered certification costs that stratify formulation economics across product types.
- Juice Blend:Formulations combine acai puree with complementary fruits such as blueberry or pomegranate to mask earthy intensity while maintaining anthocyanin thresholds. Mass-market penetration concentrates in US coastal metropolitan areas where wellness-oriented households prioritize palatability over single-ingredient purity. Blended formats absorb certification costs across higher volumes, preserving retailer margins.
- Pure Juice:Unadulterated acai extraction delivers maximum antioxidant concentration per serving, typically exceeding 15,000 ORAC units per 100ml. Demand clusters among dedicated health enthusiasts in Germany and the Netherlands where EFSA labeling scrutiny elevates premium positioning for unprocessed claims. Cold-press processing requirements constrain supply elasticity.
- Concentrate:Reduced-water formulations enable efficient cold-chain logistics from Brazil's Para state to North American and European processing facilities.
- Powder:Lyophilized formats bypass liquid cold-chain requirements entirely, targeting home smoothie preparation and nutritional supplement compounding.
Established volume favors juice blends; emerging adoption favors pure juice formats.
Packaging Type:
Packaging durability and resealability determine channel access and price realization across temperature-controlled supply chains.
- Bottles:Glass and premium PET containers dominate health store and specialty retail placement due to resealability and shelf presence. Fitness center vending and boutique wellness channels in California and Florida specify bottle formats for post-workout consumption occasions. Premium positioning supports 40-60% price elevation over tetra alternatives.
- Pouches:Flexible single-serve formats reduce shipping weight and storage footprint for direct-to-consumer subscription models. Online stores with recurring delivery infrastructure favor pouches for last-mile efficiency in dense urban markets. Steepest expansion trajectory among packaging types as fulfillment economics improve.
- Tetra Packs:Aseptic carton technology extends ambient shelf stability for conventional grocery distribution.
- Cans:Aluminum formats target convenience store and grab-and-go channels with established recycling infrastructure.
Resealability commands premium placement; lightweight formats gain share fastest in digital channels.
Distribution Channel:
Channel selection determines working capital intensity and customer data access for repeat purchase cultivation.
- Online Stores:Direct-to-consumer platforms with subscription replenishment cycles capture recurring revenue while bypassing retail slotting fees. US metropolitan markets with same-day fulfillment density support highest penetration among health enthusiasts seeking convenience without quality compromise. Customer data informs flavor development and seasonal promotion timing.
- Retail Stores:Dedicated shelf space in health-focused chains anchors brand visibility and trial conversion among new category entrants. UK and German retailers demand third-party organic certification verification before granting premium positioning.
- Wholesale:Bulk distribution to food service and ingredient manufacturers concentrates in Brazil-to-Portugal shipping lanes.
- Direct Sales:Producer-to-consumer relationships at farmers markets and wellness events build authentication narratives for traceable sourcing.
Recurring revenue favors online stores; trial conversion favors physical retail presence.
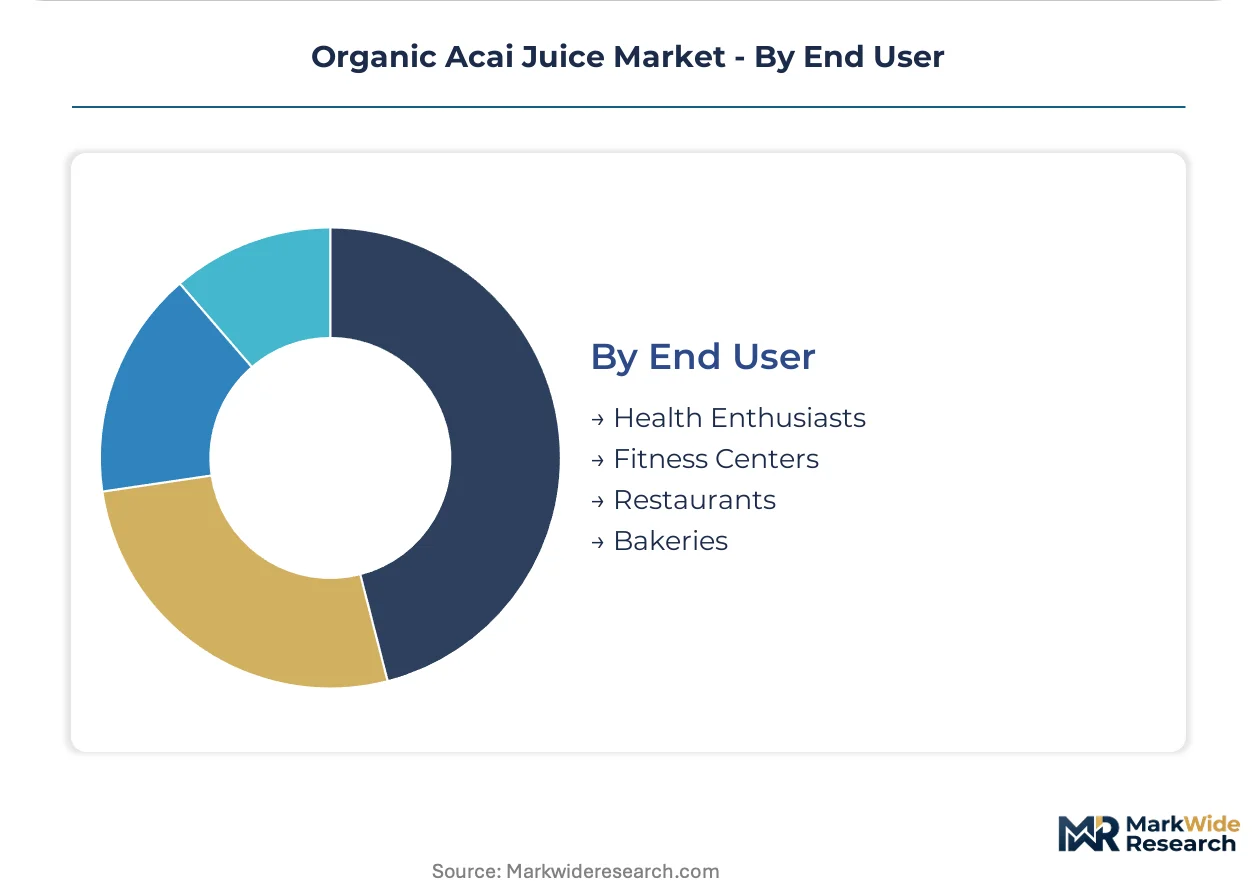
End User:
End-user sophistication determines formulation requirements and price elasticity across consumption occasions.
- Health Enthusiasts:Dedicated wellness consumers prioritize antioxidant bioactivity and supply chain traceability over price minimization. Home preparation habits in US and European metropolitan areas drive demand for frozen pulp and powder formats beyond ready-to-drink. Post-workout recovery and morning ritual occasions support premium subscription pricing.
- Fitness Centers:Boutique gym partnerships and specialized wellness channels create direct access for functional beverage positioning. California and Florida operators specify cold-press processing and third-party ORAC verification for member-facing retail.
- Restaurants:Smoothie bars and health-focused cafes incorporate acai as signature ingredient for menu differentiation.
- Bakeries:Artisan producers utilize acai powder for natural coloration and antioxidant marketing in premium pastry lines.
Subscription loyalty favors health enthusiasts; volume concentration favors fitness center partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German and Dutch buyers accept substantial premiums for certified organic traceability. Brazilian consumers remain highly price-sensitive despite domestic sourcing proximity.
United States
Health enthusiasts in California and Florida drive premium juice blend consumption through fitness center channels and direct-to-consumer subscriptions. FDA labeling requirements and USDA Organic certification govern interstate commerce, filtering out uncertified imports. Los Angeles and Miami metropolitan clusters anchor cold-press processing capacity and boutique wellness retail placement.
Germany
Discerning consumers in Berlin and Hamburg prioritize unadulterated pure juice formats with verified ORAC antioxidant ratings. EFSA health claim regulations and EU Organic Regulation shape permissible marketing language, compressing margins for brands lacking clinical substantiation. The Hamburg port cluster handles bulk concentrate imports from Brazil's Para state for redistribution across Northern Europe.
Brazil
Domestic consumption concentrates in São Paulo and Rio de Janeiro metro areas where acai pulp remains a traditional breakfast staple at accessible price points. ANVISA food safety standards and organic certification protocols from the Ministry of Agriculture govern export-grade processing. The Amazon basin's Para state anchors raw berry harvesting with Belém serving as the primary logistics hub for international shipment.
United Kingdom
London and Southeast England health stores cultivate repeat purchase loyalty through dedicated shelf space and subscription box partnerships. UK Food Standards Agency regulations and post-Brexit organic equivalence agreements with the EU create compliance complexity for continental suppliers. Holland & Barrett's retail network concentrates distribution power in suburban shopping centers.
Netherlands
Amsterdam and Rotterdam buyers exhibit strong preference for sustainable packaging formats in online subscription channels. EFSA labeling requirements and national organic authority controls enforce strict substantiation standards. The Rotterdam port infrastructure enables efficient cold-chain transshipment of frozen pulp to German and Belgian processing facilities.
Organic Acai Juice Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes. Captive sourcing networks in Brazil's Amazon basin confer upstream cost advantages on vertically integrated processors. Mid-tier brands without backward integration face margin compression from price volatility. Three archetypes dominate: Amazon-based harvester-processors with captive berry supply, European health retail chains with dedicated shelf space control, and direct-to-consumer specialists with subscription infrastructure. Competitive moves concentrate on securing certified organic supply contracts and expanding cold-chain distribution partnerships.
Within the Amazon-sourced tier, Sambazon anchors upstream control through Brazilian harvesting operations. Among European retail specialists, Holland & Barrett Retail Limited occupies a position exemplifying health store channel dominance. Nativo Acai represents the boutique wellness archetype with fitness center distribution focus. These three entities illustrate how geographic positioning and channel specialization stratify competitive advantage without requiring identical operational models.
| Leading Market Players |
|---|
| Sambazon |
| Acai Roots |
| R.W. Knudsen Family |
| Mama Toucan's |
| Organique Acai |
| The Berry Company Limited |
| Nativo Acai |
| Holland & Barrett Retail Limited |
| Zola |
| Others |
Supply Flow & Price Mechanics
Forty-five-day harvest-to-processing lead times in Brazil's Para state tether pricing power to Amazon basin logistics capacity, compressing margins for non-integrated brands while rewarding Sambazon's captive sourcing networks with cost insulation against spot-market volatility.
Pricing Analysis
Subscription renewal revenue drives lifetime value across direct-to-consumer channels, with three-tier pricing structure across premium, standard, and economy levels separating cold-press pure juice from flash-pasteurized blends and synthetic-fortified substitutes. USDA Organic and EU Organic certification tiers command 25-40% premiums over uncertified alternatives. Pricing pressure stems from flash-pasteurized commodity substitutes capturing price-sensitive mass retail shoppers. Fitness centers and health enthusiasts exhibit lowest price sensitivity, while conventional grocery buyers in Brazil and Southeast Asia show highest elasticity.
Supply Chain Analysis
Strategic stockpiling of frozen pulp inventory dominates processor preferences, with just-in-time fresh-berry processing limited to Belém-hub facilities serving domestic Brazilian breakfast markets. Raw acai berry supply concentrates in Brazil's Para state, with secondary sourcing from Amazonas and Amapá regions. Processing capacity clusters in Florida and California for North American distribution, with Hamburg and Rotterdam anchoring European cold-chain logistics. Single-region harvest concentration creates climate disruption vulnerability. Distribution runs through refrigerated container networks from Amazon ports to Miami, Hamburg, and Rotterdam transshipment hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent organic acai juice processors face substitution pressure from synthetic antioxidant fortification in conventional berry blends, requiring defensive positioning around traceability narratives and certification integrity to maintain premium tier access.
For Market Incumbents: Compound defensive moats through backward integration into Para state harvesting cooperatives and EFSA health claim dossier investment, neutralizing synthetic-fortified substitute threats while locking in supply security against climate volatility. For New Entrants and Emerging Players: USDA Organic certification fast-track through accredited third-party auditors opens white-space penetration in US metropolitan subscription channels, with flash-freeze pulp formats for home smoothie preparation offering lowest competitive density against established ready-to-drink brands. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underperforming wellness beverage divisions, where organic acai assets trade at valuation discounts to pure-play functional beverage multiples. Watch EFSA polyphenol health claim approvals as inflection signal for European premium tier expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Refrigerated logistics alliances with Port of Belém operators secure harvest-to-shelf temperature integrity for EU and US compliance. |
| EFSA Health Claim Dossier Submission | Clinical substantiation of anthocyanin antioxidant benefits unlocks premium positioning in German and Dutch retail channels. |
| Direct-to-Consumer Subscription Platform | Recurring revenue models bypass slotting fees at Holland & Barrett and other health retail chains while capturing consumption data. |
| Backward Integration into Para Cooperatives | Captive sourcing from Amazon basin harvesting networks insulates margin pressure from spot-market berry price volatility. |
| Flash-Freeze Pulp Format Expansion | Frozen single-serve packets target home preparation occasions beyond ready-to-drink, expanding addressable market into ingredient applications. |
Methodological Framework
A standing panel of organic certification auditors, cold-chain logistics operators, health retail category buyers, and fitness center procurement managers provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with Sambazon supply chain directors and Nativo Acai distribution partners alongside secondary validation through USDA Organic Integrity Database records, EU TRACES certification tracking, and ANVISA export registration filings. Bottom-up volume modeling triangulated against top-down category spending estimates from Nielsen retail audit data and customs trade statistics.
Consistency checks validated volume and value outputs against external benchmarks including Circana functional beverage consumption indices and IRI refrigerated juice category performance metrics. Segmentation modeling spanned product formulation tiers, packaging durability requirements, distribution channel economics, and end-user sophistication levels across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable functional beverage categories, with cold-press processing capacity expansion and EFSA regulatory timeline uncertainty incorporated as scenario variables.
Decision-makers should treat outputs as directional under assumptions of sustained EU Organic Regulation enforcement and stable Brazil-US-EU trade corridor access; material deviation would warrant model refresh. Revision becomes warranted when EFSA health claim approvals or ANVISA export protocol changes cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Organic Fruit Powder Market
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
Australia Organic Food Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
Non-GMO Food Market