
 Australia Organic Beverages Market | 2026-2036
Australia Organic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Organic Beverages Market Intelligence
Skilled agronomists certified in organic cultivation is unwinding supply bottlenecks across Australia's fragmented producer base. Planet Organic Co Pty Ltd leverages its direct farmer partnerships to secure consistent raw material flows. The Coca-Cola Company anchors its position through controlled distribution into mainstream retail channels. República Organic differentiates via single-origin sourcing credentials that resonate with premium buyers.
Organic beverages comprise drinks manufactured from ingredients grown without synthetic pesticides, genetically modified organisms, or artificial fertilizers, typically requiring certification under the National Standard for Organic and Bio-Dynamic Produce. These products serve consumers seeking reduced chemical exposure and transparent supply chains in functional refreshment categories. Organic tea and coffee dominate current revenue pools due to established premium pricing and habitual consumption patterns, while organic soft drinks represent the fastest-expanding segment as sugar-conscious younger demographics reject conventional carbonated alternatives. Supermarkets control volume throughput, though health stores capture disproportionate margin through personalized curation and loyalty programs.
FSANZ governs compositional standards and labeling claims, while the Department of Agriculture enforces import integrity through biosecurity and organic equivalence agreements. ACCC scrutiny of greenwashing claims tightens marketing compliance costs for brands lacking third-party certification. Stakeholders must monitor evolving certification reciprocity negotiations between Australia and major trading partners to secure competitive ingredient sourcing.
Market Dynamics
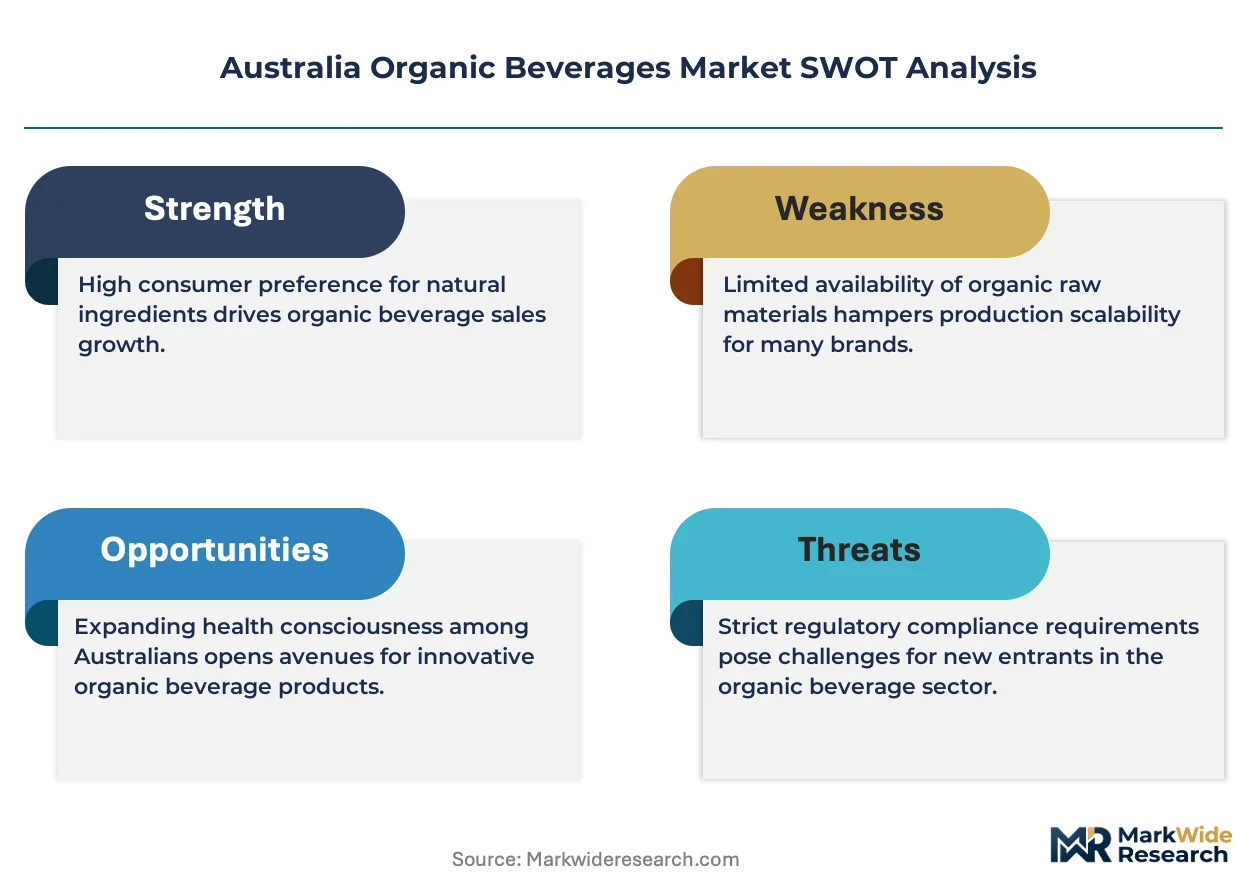
Certification bottlenecks under Australia's National Standard for Organic and Bio-Dynamic Produce are compressing supplier margins while concentrating procurement power among vertically integrated processors who control accredited farm networks.
Growth Catalysts
- FSANZ compositional standards:Clear labeling frameworks reduce consumer confusion and accelerate shelf placement decisions for certified brands entering mainstream retail.
- Queensland specialty coffee roasting clusters:Regional processing infrastructure expansion cuts transport costs for northern growers seeking Melbourne and Sydney distribution.
- Cold-pressed extraction methods:Non-thermal processing preserves volatile organic compounds in juice applications, extending premium positioning beyond traditional pasteurized alternatives.
Market Restraints
- Imported organic concentrate dependency:Australian beverage manufacturers rely on Brazilian and Vietnamese coffee bean supplies exposed to climate-induced crop volatility.
- ACCC greenwashing enforcement:Aggressive scrutiny of uncertified "natural" claims elevates compliance costs for mid-tier brands lacking third-party verification.
- Shelf-life limitations:Absence of synthetic preservatives constrains distribution radius for unpasteurized kombucha and raw juice products.
Strategic Opportunities
- Western Australia underpenetration:Perth's isolation from eastern supply chains creates whitespace for regional bottling facilities serving mining camp and coastal tourism channels.
- Direct-to-cafe subscription models:Roasters bypassing wholesale distributors capture recurring revenue from independent Melbourne and Brisbane espresso bars.
- Biodynamic certification tiering:Demeter-standard products command additional price premiums above baseline organic credentials in Sydney's eastern suburbs.
Industry Challenges
- Agronomist certification scarcity:The Department of Agriculture accredits fewer than 200 organic cultivation specialists nationwide, constraining farm conversion timelines.
- Legacy ERP integration:Batch traceability requirements for organic chain-of-custody documentation clash with outdated inventory systems at regional cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Organic Beverages Market |
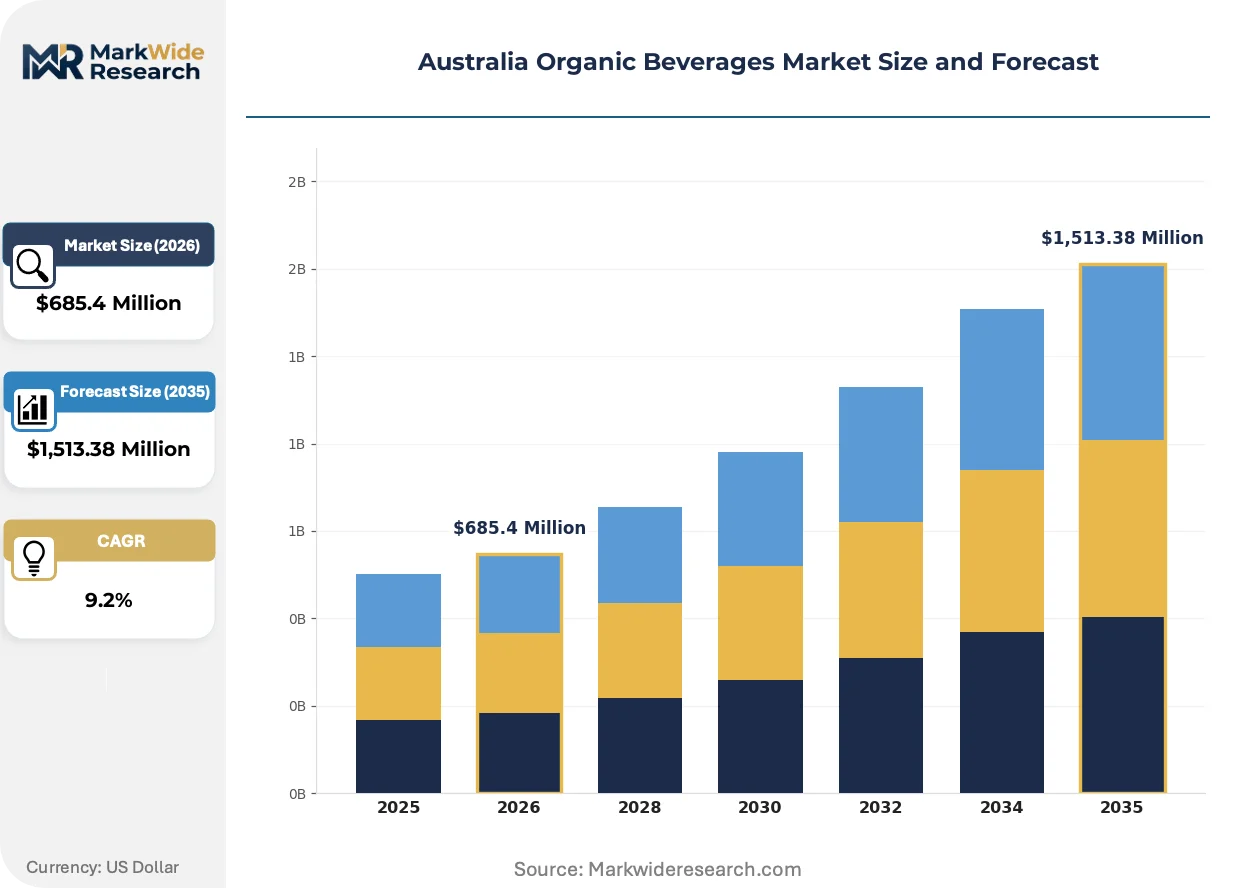
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,513.38 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tea, Coffee, Juice, Soft Drinks Distribution Channel: Supermarkets, Health Stores, Online Retail, Specialty Shops Consumer Segment: Health-Conscious Individuals, Families, Millennials, Seniors Packaging Type: Glass Bottles, Cartons, Cans, Pouches |
| Companies Covered | The Hain Celestial Group Inc, Planet Organic Co Pty Ltd, The Coca-Cola Company, República Organic, Montville Coffee Pty Ltd, PepsiCo Inc, Byron Bay Coffee Company, Tea Tonic Pty Ltd, Danone SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Organic Beverages Market Strategic Shifts & Innovations
Clean-label fermentation science and regenerative agriculture verification are redefining competitive differentiation beyond basic organic certification. Producers now compete on soil health metrics and carbon-negative processing claims.
Precision fermentation for dairy-free milk bases is fragmenting traditional plant-milk categories. Oat and almond processors in Victoria and New South Wales face displacement from lab-cultured protein beverages targeting barista-grade foam stability. Specialty cafes in Melbourne's inner north are trialing these alternatives at 15% price premiums.
The National Standard for Organic and Bio-Dynamic Produce is tightening equivalence requirements for imported ingredients. Australian bottlers must now re-certify overseas supply chains previously grandfathered under mutual recognition agreements. This compresses margin for brands reliant on Sri Lankan tea and Indonesian coconut water concentrates.
Subscription-based beverage curation is displacing supermarket bulk purchasing among urban millennials. Melbourne-based services deliver personalized organic coffee rotations matched to taste profiles, capturing pantry space from incumbent retail brands. New South Wales and Victoria account for disproportionate uptake of these direct relationships.
Australia Organic Beverages Market Segmentation
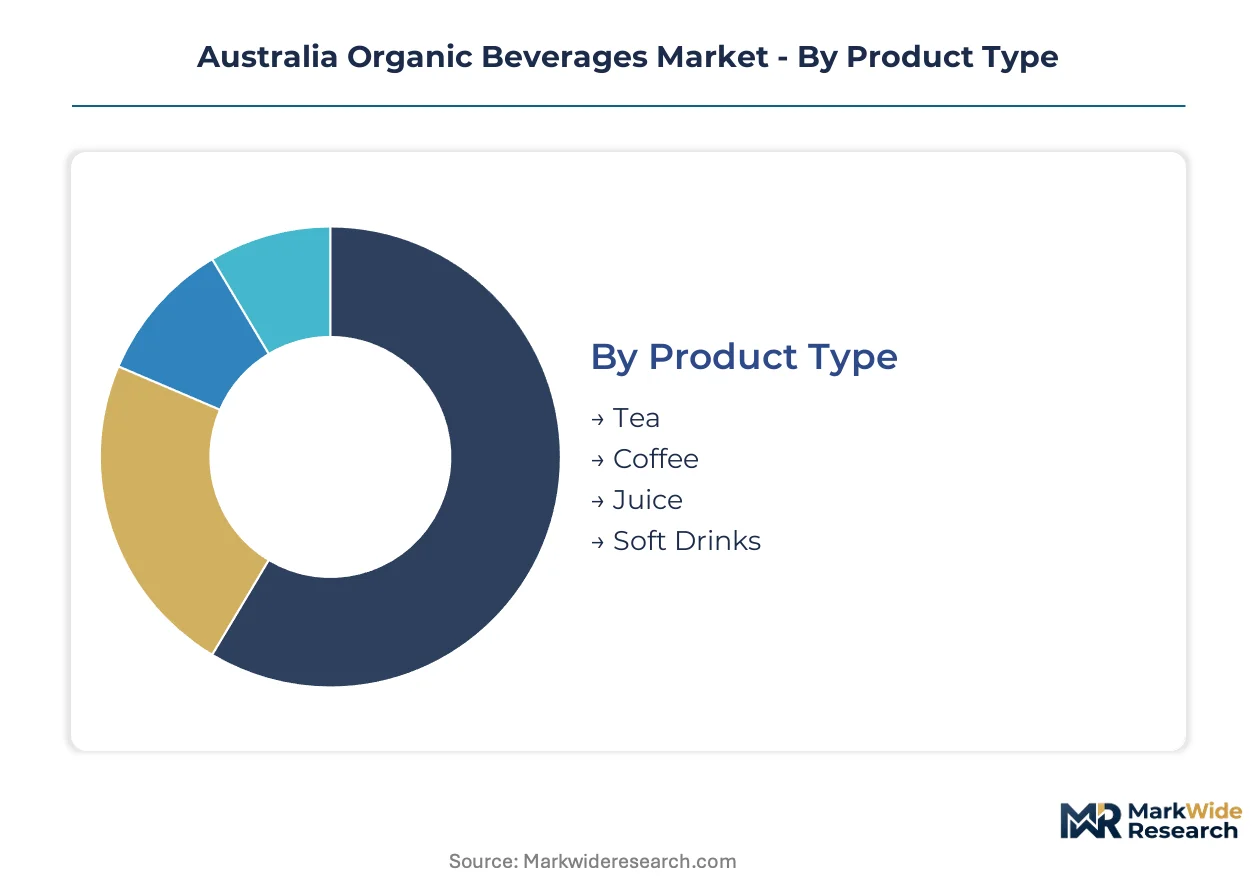
Organic beverage segmentation in Australia tracks how certification tiers and channel access shape purchasing behavior. Distinct consumer cohorts cluster around specific product formats and retail environments, creating identifiable revenue pools for targeted positioning.
Product Type:
Channel placement varies sharply across beverage categories, with habitual consumption formats dominating mainstream retail while experimental segments concentrate in specialty channels.
- Tea:Camellia sinensis and herbal infusions certified under the National Standard for Organic and Bio-Dynamic Produce command established shelf space in Coles and Woolworths. Victorian and New South Wales households drive repeat purchases through familiar brewing rituals.
- Coffee:Single-origin arabica and robusta blends roasted in Queensland and Melbourne clusters anchor cafe distribution networks. Melbourne's inner-north espresso bars source directly from accredited roasters, bypassing wholesale markups.
- Juice:Cold-pressed fruit and vegetable extracts with FSANZ-compliant labeling occupy refrigerated health store sections. Shelf-life constraints limit supermarket penetration for unpasteurized variants.
- Soft Drinks:Sugar-free carbonated alternatives with natural sweeteners capture younger demographics rejecting conventional soda. Convenience stores and petrol station fridges represent emerging placement territory.
By volume, Coffee leads. By growth pace, Soft Drinks is ahead.
Distribution Channel:
Margin structures diverge across channels, with personalized service environments capturing premium pricing while high-throughput formats optimize unit economics.
- Supermarkets:Coles and Woolworths control mass-market volume through centralized procurement and promotional slotting fees. FSANZ labeling compliance enables rapid shelf placement for certified entrants.
- Health Stores:Independent retailers like Flannerys and Go Vita curate assortments around loyalty programs and staff recommendations. New South Wales and Victoria account for disproportionate store density.
- Online Retail:Subscription services and direct-to-consumer platforms bypass retail margin stacking. Melbourne-based coffee roasters leverage this channel for recurring revenue from interstate customers.
- Specialty Shops:Organic grocers and farmers market stalls emphasize provenance storytelling and tasting events. Perth's isolation from eastern supply chains creates regional whitespace for local bottlers.
Supermarkets move the most units. Online Retail is expanding most quickly.
Consumer Segment:
Purchasing frequency correlates with life stage and health priority intensity, shaping product format preferences and price sensitivity thresholds.
- Health-Conscious Individuals:Active lifestyle consumers prioritizing clean-label ingredient transparency. Kombucha and functional shots concentrate in this cohort.
- Families:Household purchasers seeking reduced chemical exposure for children. Carton-packaged organic juices dominate this segment's basket composition.
- Millennials:Urban professionals driving cafe culture adoption and subscription service uptake. Sydney and Melbourne millennials show highest per-capita organic beverage expenditure.
- Seniors:Mature consumers with established brand loyalties and digestive sensitivity concerns. Herbal tea and low-acid coffee variants resonate here.
Families generate the largest transaction sizes. Millennials show the steepest spending growth trajectory.
Packaging Type:
Material selection reflects shelf-life requirements, sustainability positioning, and channel-specific handling constraints.
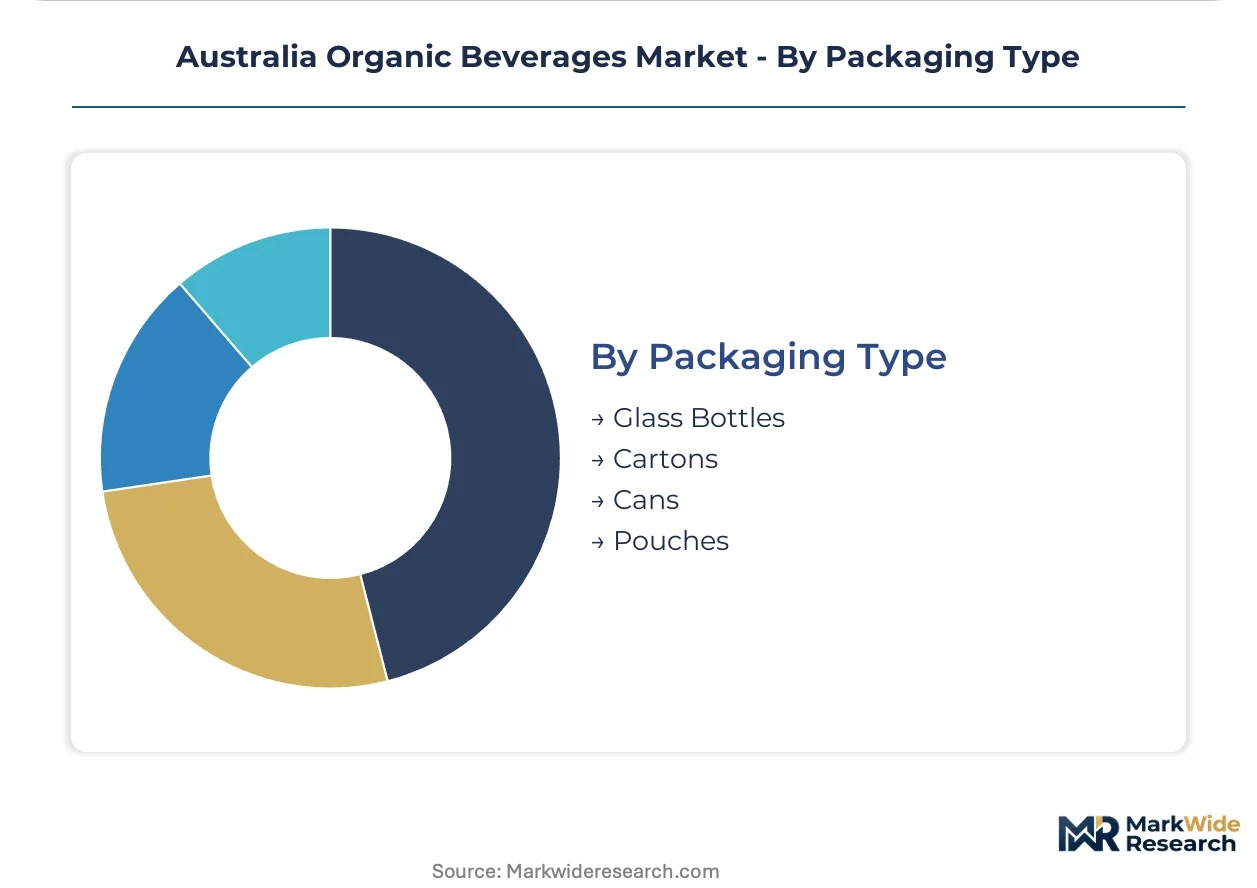
- Glass Bottles:Premium positioning for kombucha, cold-press juices, and craft soft drinks. Returnable bottle schemes in South Australia and Queensland reduce per-unit environmental cost.
- Cartons:Aseptic packaging for UHT milk alternatives and long-life juices. Tetra Pak dominance in this category creates supplier concentration risk.
- Cans:Aluminum formats for carbonated soft drinks and sparkling waters. Recycling infrastructure maturity supports circular economy claims.
- Pouches:Flexible packaging for children's beverages and on-the-go consumption. Limited adoption outside specialty channels due to premium pricing.
Cartons lead by volume. Glass Bottles command the highest price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSANZ compositional standards and the National Standard for Organic and Bio-Dynamic Produce anchor regulatory frameworks across Australia's organic beverage landscape. State-level agricultural policies and urban consumption clusters drive divergent growth trajectories.
New South Wales
Sydney's eastern suburbs and inner-west cafe corridors concentrate premium organic coffee and kombucha demand. The NSW Department of Primary Industries administers organic certification audits alongside federal equivalence requirements. Northern Rivers hinterland farms supply cold-pressed juice processors serving Sydney's health-conscious households.
Victoria
Melbourne's inner-north espresso bar culture sustains direct-trade relationships with accredited organic roasters. Sustainability Victoria coordinates regional food hub infrastructure supporting farm-to-bottle supply chains. Yarra Valley and Mornington Peninsula clusters host biodynamic wine producers diversifying into organic non-alcoholic beverages.
Queensland
Brisbane's subtropical climate drives coconut water and tropical juice consumption among active lifestyle consumers. The Queensland Department of Agriculture and Fisheries manages organic producer registration under national accreditation protocols. Sunshine Coast hinterland operations supply northern markets with reduced transport costs to Melbourne and Sydney distribution networks.
Western Australia
Perth's geographic isolation from eastern supply chains creates whitespace for regional bottling facilities. The Western Australian Department of Primary Industries and Regional Development enforces biosecurity protocols affecting imported organic concentrate flows. Margaret River and Swan Valley producers serve mining camp and coastal tourism channels with limited interstate competition.
South Australia
Adelaide's container deposit legislation incentivizes returnable glass bottle schemes for premium kombucha and craft soft drinks. Primary Industries and Regions SA oversees organic integrity within the state's wine-centric agricultural economy. Adelaide Hills growers supply small-batch processors targeting farmers market and specialty retail channels.
Australia Organic Beverages Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across Australia's organic beverage sector. Vertically integrated roasters with direct farmer partnerships control premium raw material flows, while multinational beverage conglomerates leverage established distribution infrastructure for mass-market penetration. Three strategic archetypes dominate: accredited organic specialists, diversified natural products portfolios, and conventional beverage giants with organic line extensions. Competitive dynamics center on certification credibility maintenance and channel access expansion through strategic retail partnerships.
Among diversified natural products portfolios, The Hain Celestial Group Inc represents the specialist multinational archetype with concentrated organic credentials. Planet Organic Co Pty Ltd exemplifies domestic vertically integrated operations leveraging direct farmer partnerships. The Coca-Cola Company anchors the conventional giant archetype, utilizing controlled distribution networks to secure mainstream retail placement for certified product lines.
| Leading Market Players |
|---|
| The Hain Celestial Group Inc |
| Planet Organic Co Pty Ltd |
| The Coca-Cola Company |
| República Organic |
| Montville Coffee Pty Ltd |
| PepsiCo Inc |
| Byron Bay Coffee Company |
| Tea Tonic Pty Ltd |
| Danone SA |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles for imported organic coffee concentrates compress margin flexibility for Australian bottlers while amplifying procurement power among roasters with backward integration into accredited farm networks. This lead-time exposure concentrates pricing leverage with vertically integrated processors who control certified cultivation partnerships across Queensland and Victoria.
Pricing Analysis
Sydney-to-Perth price spreads of 15-20% for identical organic kombucha SKUs reflect transport cost absorption patterns rather than brand premium differentiation. Three-tier pricing structure across biodynamic, certified organic, and transitional organic levels anchors the dominant model, with FSANZ compliance tier and Demeter certification status as primary price differentiation drivers. Cost compression in the transitional organic tier is intensifying because imported concentrate dependency exposes bottlers to Brazilian real volatility. Families purchasing carton-packaged juices show highest price sensitivity, while biodynamic-certified buyers in Melbourne's inner north exhibit lowest elasticity.
Supply Chain Analysis
Sixty-day lead times for Sri Lankan tea leaf shipments and Vietnamese coffee bean consignments constrain just-in-time production scheduling for Australian processors. Geographic supply concentration centers on Brazil, Vietnam, and Sri Lanka for raw agricultural inputs, with Victorian and New South Wales roasting clusters providing downstream processing infrastructure. Raw material dependencies rest on organic coffee arabica, Camellia sinensis cultivars, and tropical fruit concentrates. Single-source vulnerability for Demeter-certified biodynamic inputs creates supply chain risk. Distribution runs through Coles and Woolworths centralized procurement for mass-market volume, with direct-to-cafe subscription channels capturing premium margin in Melbourne and Sydney.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based beverage curation platforms are reshaping customer acquisition economics, with interoperability between roaster ERP systems and cafe point-of-sale networks enabling seamless reorder automation that locks in recurring revenue streams.
For Market Incumbents: Secure direct farmer partnerships in Queensland and northern New South Wales to lock in accredited organic supply before agronomist certification scarcity worsens conversion timelines. Invest in cold-pressed extraction capacity to defend against precision-fermented dairy alternatives that threaten traditional plant-milk positioning. Channel control through exclusive Coles and Woolworths promotional slotting remains critical for mass-market volume defense.
For New Entrants and Emerging Players: Lead with biodynamic certification tiering to capture Sydney eastern suburbs premium positioning above baseline organic competitors. Target Western Australia's underpenetrated Perth market with regional bottling facilities serving mining camp and coastal tourism channels. Direct-to-cafe subscription models bypassing wholesale distributors offer the most penetrable go-to-market angle for Melbourne and Brisbane espresso bar networks.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational beverage conglomerates seeking to divest non-core organic line extensions that lack certification credibility depth. Long-term viability across the next decade hinges on soil health metric verification capabilities and carbon-negative processing claims that extend beyond basic organic certification. Watch for Department of Agriculture equivalence reciprocity negotiations with major trading partners as the signal indicating inflection in competitive ingredient sourcing costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodynamic Certification Investment | Demeter-standard credentials command 15% price premiums in Sydney's premium postcodes. |
| Cold-Pressed Extraction Scale-Up | Non-thermal processing preserves volatile compounds for kombucha and raw juice differentiation. |
| Direct-to-Cafe Subscription Launch | Melbourne roasters bypass wholesale markups to capture recurring revenue from espresso bars. |
| Western Australia Bottling Facility | Perth's isolation creates whitespace for regional facilities serving mining and tourism channels. |
| Farmer Partnership Backward Integration | Planet Organic's direct partnerships secure consistent raw material flows amid certification scarcity. |
Research Approach
Cross-validation between primary interviews with organic roaster operations managers, cafe procurement leads, and FSANZ regulatory affairs specialists and secondary validation against Department of Agriculture certification databases, ACCC enforcement records, and Coles/Woolworths supplier disclosure filings anchors the qualitative findings. Bottom-up demand modeling from state-level consumption clusters and top-down supply assessment from accredited farm network capacity complete the triangulation.
Sensitivity analysis across certification tier penetration rates, import concentrate price volatility bands, and subscription service adoption curves informs the analytical framework. Segmentation dimensions modeled include product type, distribution channel, consumer life stage, and packaging format across the projection horizon. CAGRs derive from regression analysis against historical organic certification growth patterns and millennial cohort expenditure elasticity. Industry-specific forecast inputs incorporate National Standard for Organic and Bio-Dynamic Produce equivalence negotiation timelines and precision fermentation technology disruption curves.
The analysis sits within stated boundaries; outcomes outside sustained FSANZ labeling compliance and stable Brazilian-Vietnamese agricultural export flows would require recalibration. Forecasts reflect documented assumptions regarding certification reciprocity maintenance and agronomist training pipeline expansion. Climate-induced crop volatility in tropical supplier regions and ACCC greenwashing enforcement intensity represent specific risk factors that could revise projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Maple Syrup Market
Organic Food and Beverages
Organic Juice Market
Organic Food and Beverages
Global Organic Food Market
Organic Food and Beverages
Organic Soy Products Market
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Organic Goji Berry Market
Organic Food and Beverages
Canada Organic Food Market
Organic Food and Beverages
Organic Yogurt Market
Organic Food and Beverages
Organic Drinks Market
Organic Food and Beverages
Organic Stevia Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
Organic Acai Juice Market
Organic Food and Beverages
Organic Cocoa Market