
 Asia-Pacific Organic Food Market | 2026-2036
Asia-Pacific Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Organic Food Market Analytics
India's Punjab-Haryana organic corridor is fragmenting as smallholder collectives and contract farming networks multiply across the Indo-Gangetic plain. 24 Mantra Organic leverages its integrated farm-to-retail chain to control quality consistency across South Indian sourcing belts. Sresta Natural Bioproducts anchors its position through millet and grain specialization, while Ausnutria Dairy (China) dominates organic infant formula manufacturing with captive pasture operations in Shaanxi and Heilongjiang.
Asia-Pacific organic food encompasses crops, livestock products, and processed items cultivated without synthetic pesticides, genetically modified organisms, or artificial fertilizers, maintaining soil health through crop rotation and biological pest management. The primary commercial purpose centers on delivering certified chemical-residue-free nutrition to health-conscious consumers and premium foodservice operators. Fruits and vegetables occupy the largest volume share due to daily consumption frequency and visible freshness cues, while dairy commands margin concentration through organic infant formula exports from China and Australia. E-commerce distribution is expanding fastest as Alibaba, JD.com, and regional platforms build cold-chain last-mile networks into Southeast Asian cities.
India's FSSAI enforces organic certification and labeling standards that block uncertified products from formal retail channels. China's SAMR and GB standards govern organic claims and production facility audits, while Japan's JAS organic mark governs import eligibility for Australian beef and Chinese tea. Australia's TGA-aligned export certification system enables quota-free EU market access. Stakeholders must monitor divergence between national organic standards as bilateral recognition agreements reshape cross-border sourcing economics.
Market Dynamics
India's FSSAI organic labeling rules are tightening compliance requirements and forcing supply chain consolidation across the Indo-Gangetic plain. Smallholder collectives face exclusion from formal retail channels without certification, while contract farming networks multiply to aggregate compliant volume.
Growth Catalysts
- Export quota liberalization:Australia's TGA-aligned certification system enables quota-free EU market access for organic dairy producers. Infant formula manufacturers leverage this pathway for premium positioning.
- E-commerce cold-chain expansion:Alibaba and JD.com are building last-mile refrigerated networks into Southeast Asian cities. Urban household penetration for fresh organic vegetables rises as delivery windows compress.
- GB standards harmonization:China's SAMR organic production facility audits are streamlining cross-provincial compliance. Shaanxi and Heilongjiang pasture operations benefit from unified national benchmarks.
Market Restraints
- Input cost volatility:Organic feed grain prices fluctuate with conventional commodity markets plus organic premium spreads. Livestock producers face margin compression during drought cycles in Australian sourcing belts.
- Supply concentration risk:Tier-one Chinese cities dominate premium organic vegetable demand. Geographic demand clustering creates last-mile bottlenecks when cold-chain capacity saturates.
- Certification timeline friction:India's FSSAI three-year conversion period for conventional farmland blocks rapid supply expansion. Smallholders abandon organic transition mid-cycle due to revenue gaps.
Strategic Opportunities
- Southeast Asian underpenetration:Vietnamese and Indonesian urban middle-class expansion outpaces certified organic supply. Early entrants capture shelf-space premiums before local production scales.
- Millet specialization:Sresta Natural Bioproducts anchors grain diversification as climate-adaptive cropping gains policy support. India's millet mission aligns with organic rotation requirements.
- Blockchain traceability convergence:Distributed ledger technology integrates with existing certification databases. Chinese infant formula exporters deploy transparent sourcing narratives for parental trust.
Industry Challenges
- Auditor capacity constraints:India's accredited organic certification bodies face inspection backlogs as FSSAI rules tighten. Farm-level compliance verification delays market entry.
- Legacy ERP integration:South Indian farm-to-retail chains struggle to retrofit batch-traceability modules into existing inventory systems. 24 Mantra Organic's integrated model remains an exception.
- Soil health expertise scarcity:Biological pest management and crop rotation planning require agronomist training that outpaces agricultural university output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Organic Food Market |
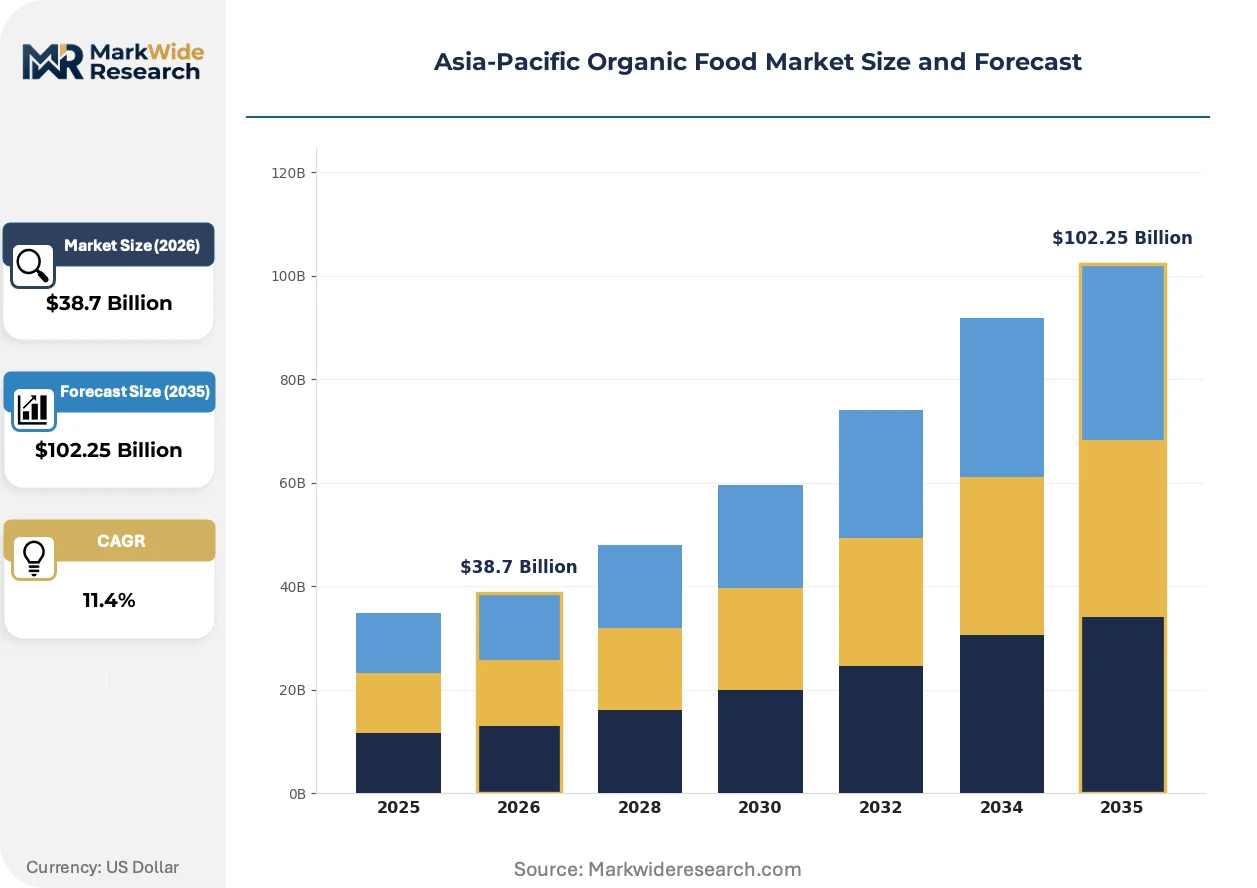
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy, Grains Distribution Channel: Supermarkets, Organic Stores, E-commerce, Direct Sales End User: Households, Restaurants, Cafes, Food Manufacturers Certification: USDA Organic, EU Organic, JAS, Others |
| Companies Covered | General Mills, Amy’s Kitchen, White Wave Foods, Sresta Natural Bioproducts, 24 Mantra Organic, Hain Celestial, Organic Valley, Ausnutria Dairy (China), United Natural Foods, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Organic Food Market Evolving Landscape
Digital traceability infrastructure is compressing certification-to-consumer transparency cycles across Asia-Pacific organic supply chains. Three developments are reshaping competitive positioning: laboratory verification methods, regulatory data-sharing mandates, and direct-to-pantry subscription models.
Blockchain-enabled provenance tracking is rendering obsolete paper-based audit trails for organic infant formula exports. Australian dairy cooperatives and Chinese captive pasture operators adopt distributed ledger verification at batch level. SAMR's data-sharing requirements accelerate platform standardization, compressing third-party verification costs.
Japan's JAS organic mark revision tightens residue testing protocols for imported Australian beef and Chinese tea. Export-oriented producers face laboratory capacity investments to maintain eligibility. Australian organic certifiers expand spectroscopy and DNA-verification partnerships to preempt compliance failures.
Direct-to-pantry subscription models displace traditional supermarket organic vegetable procurement in Shanghai and Beijing tier-one districts. JD.com's membership programs aggregate household demand into predictable harvest commitments. Japanese urban households show parallel behavioral shifts through Seikatsu Club cooperative purchasing.
Asia-Pacific Organic Food Market Segmentation
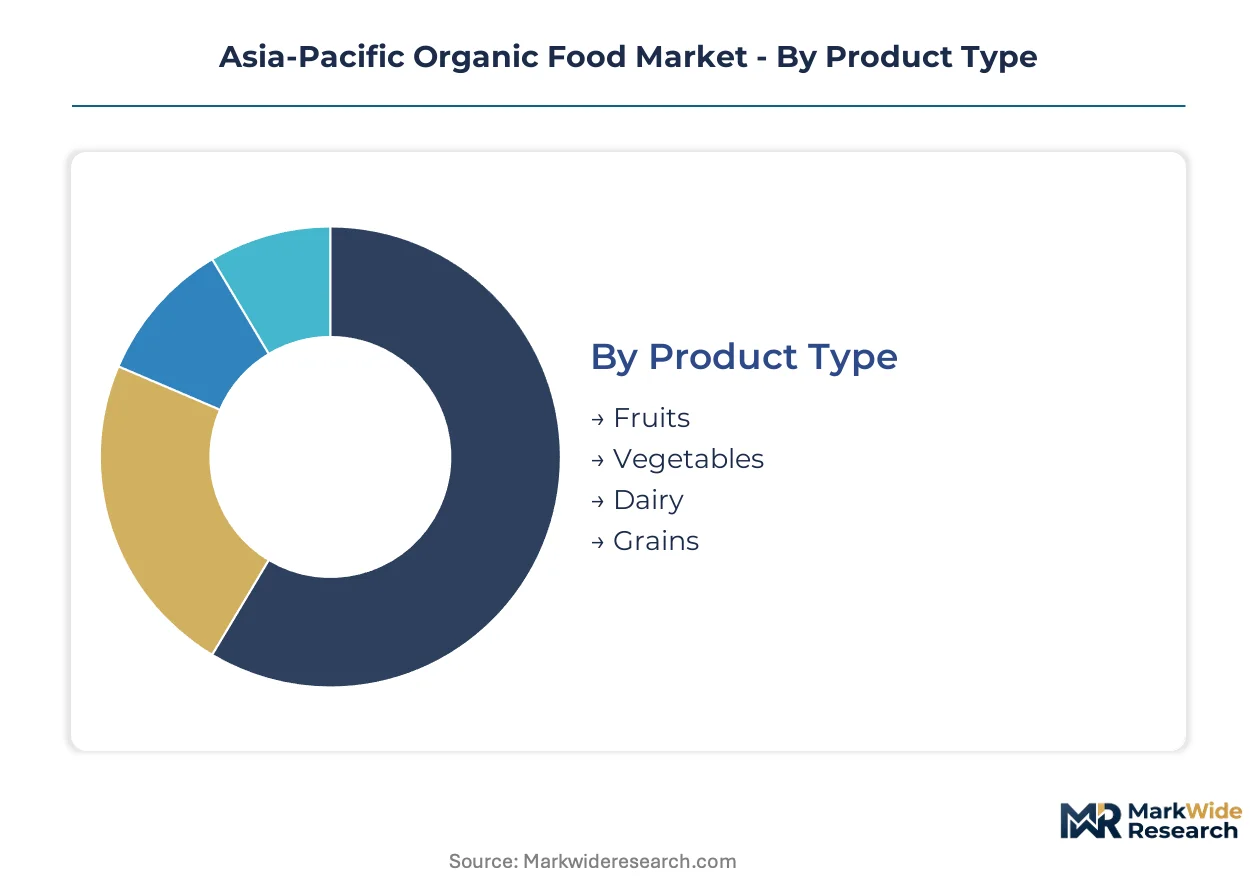
Asia-Pacific organic food segmentation reveals distinct procurement patterns across product categories and channel structures. Certification alignment determines cross-border trade eligibility while distribution infrastructure shapes urban penetration depth.
Product Type:
Fruits and vegetables dominate daily consumption frequency with visible freshness cues driving purchase decisions. Dairy commands premium positioning through infant formula exports and pasture-based supply chains.
- Fruits:Citrus, tropical varieties, and pome fruits cultivated without synthetic pesticides command shelf premiums in Shanghai and Beijing tier-one retail. Australian mango and dragon fruit exports leverage TGA-aligned certification for EU market access.
- Vegetables:Leafy greens, root vegetables, and solanaceous crops form the volume backbone of Chinese urban household procurement. Punjab-Haryana smallholder collectives aggregate compliant tomatoes, spinach, and okra for South Asian supermarket chains.
- Dairy:Milk, yogurt, and cheese produced from certified organic pasture operations. Shaanxi and Heilongjiang captive farms supply Ausnutria Dairy's infant formula manufacturing.
- Grains:Rice, wheat, and millet rotations maintain soil health across Indo-Gangetic plains. Sresta Natural Bioproducts specializes in climate-adaptive millet diversification.
The dominant share belongs to vegetables, while dairy is closing the gap fastest through export quota liberalization.
Distribution Channel:
Channel selection reflects cold-chain maturity and last-mile density across metropolitan clusters. E-commerce platforms compress delivery windows for fresh produce while traditional retail maintains price-sensitive volume.
- Supermarkets:Modern trade formats in tier-one Chinese cities and Indian metros stock certified organic sections with JAS, EU Organic, and FSSAI-compliant SKUs. 24 Mantra Organic controls dedicated shelf space through integrated farm-to-retail contracts.
- E-commerce:Alibaba and JD.com deploy refrigerated last-mile networks into Southeast Asian cities. JD.com membership programs aggregate household demand into predictable harvest commitments with batch-level traceability.
- Organic Stores:Specialty retailers curate premium assortments for health-conscious consumers. Japanese Seikatsu Club cooperatives and Australian independent grocers emphasize direct farmer relationships.
- Direct Sales:Farm-gate procurement and subscription boxes bypass intermediary margins. Direct-to-pantry models displace traditional supermarket procurement in Beijing and Shanghai districts.
Supermarkets retain volume leadership, though e-commerce is expanding most quickly through cold-chain infrastructure investment.
End User:
End-user segmentation tracks consumption occasion and ingredient processing depth. Household procurement prioritizes visible freshness while foodservice and manufacturing demand consistent certified supply.
- Households:Urban middle-class families in Chinese tier-one cities and Indian metros drive premium organic vegetable demand. Parental concern over chemical residues concentrates spending on infant formula and fresh produce.
- Restaurants:Premium foodservice operators in Tokyo, Sydney, and Singapore source certified organic ingredients for menu differentiation. JAS organic mark eligibility governs import sourcing for Japanese establishments.
- Cafes:Specialty coffee and health-focused chains procure organic dairy and plant-based alternatives. Australian organic milk supplies boutique roasting operations across Melbourne and Sydney.
- Food Manufacturers:Processed organic product makers require consistent certified input supply. Infant formula manufacturers dominate this segment through captive pasture operations and export-oriented production.
Households command the largest demand share, while food manufacturers are gaining ground fastest through export-oriented dairy processing.
Certification:
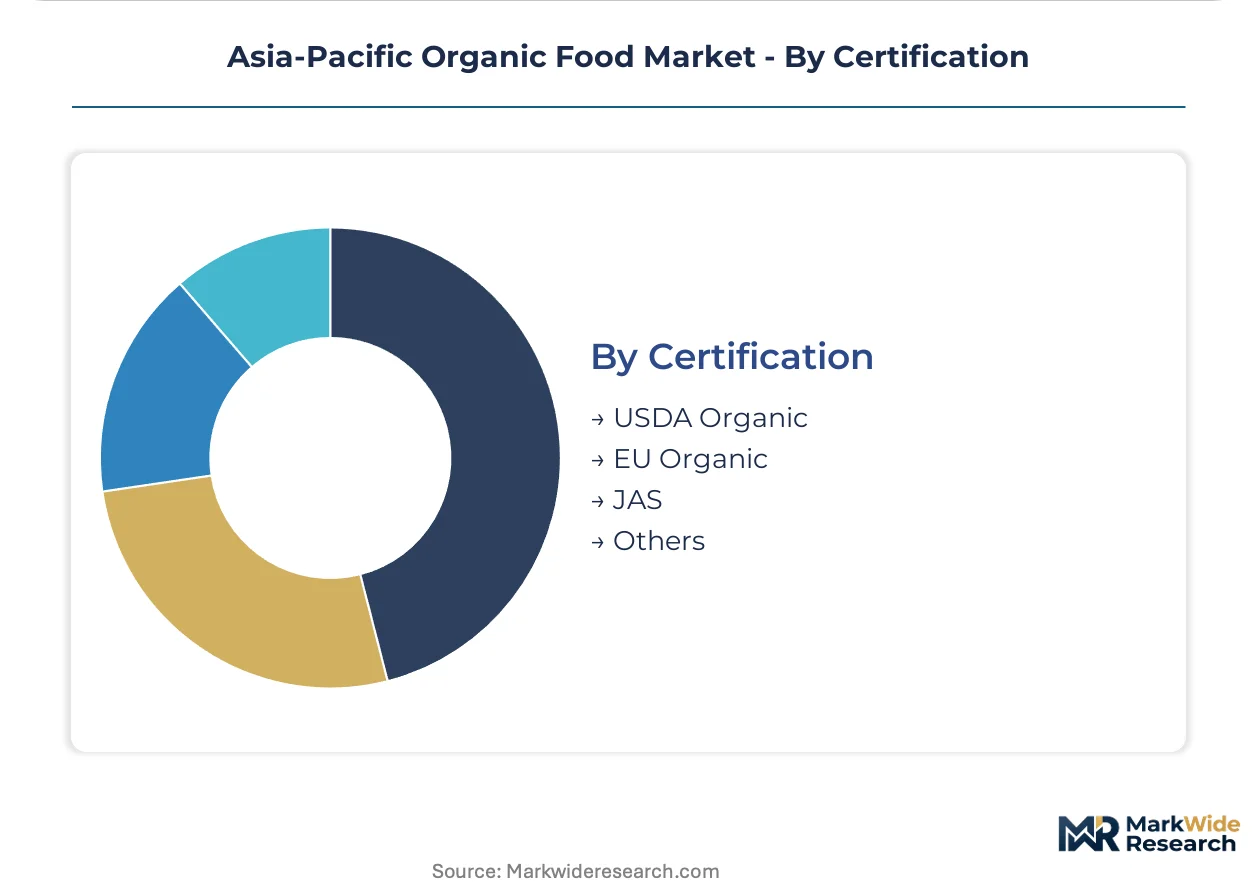
Certification type determines market access and price realization across bilateral recognition agreements. Divergent national standards create compliance complexity for multi-territory suppliers.
- USDA Organic:United States Department of Agriculture standards govern eligibility for North American export markets. Australian dairy cooperatives maintain USDA certification alongside TGA alignment for diversified market access.
- EU Organic:European Union regulations enable quota-free market entry for certified producers. Australia's TGA-aligned export certification system satisfies EU organic equivalence requirements.
- JAS:Japanese Agricultural Standards organic mark governs import eligibility for Australian beef and Chinese tea. Residue testing protocol revisions demand laboratory capacity investment from export-oriented producers.
- Others:India's FSSAI organic labeling rules, China's GB standards under SAMR, and Australian domestic certifications complete the regulatory landscape. FSSAI's three-year farmland conversion period blocks rapid supply expansion for uncertified smallholders.
EU Organic holds the widest export recognition, though JAS is tightening requirements fastest through revised residue testing mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's refrigerated container throughput underwrites China's dominance in organic food trade flows across the Asia-Pacific basin. Cold-chain rail links from Shaanxi pasturelands to coastal processing zones enable just-in-time infant formula exports. Australian dairy cooperatives leverage Fremantle Port's direct EU shipping lanes for quota-free organic access.
China
Tier-one urban households in Shanghai and Beijing drive premium organic vegetable procurement through JD.com membership programs. SAMR's GB standards harmonization streamlines cross-provincial compliance audits for Heilongjiang pasture operators. The Yangtze River Delta cold-chain network compresses delivery windows for fresh produce into Southeast Asian markets.
India
Punjab-Haryana smallholder collectives aggregate compliant tomatoes and spinach for South Asian supermarket chains. FSSAI's three-year farmland conversion period blocks rapid supply expansion, forcing contract farming network multiplication. The Indo-Gangetic plain organic corridor fragments as certification backlogs exclude uncertified producers from formal retail.
Australia
TGA-aligned export certification enables quota-free EU market access for organic dairy producers. Infant formula manufacturers leverage this pathway through captive pasture operations in Victoria and New South Wales. Melbourne and Sydney boutique roasting operations source certified organic milk for specialty coffee differentiation.
Japan
JAS organic mark eligibility governs import sourcing for Tokyo and Osaka premium foodservice operators. Revised residue testing protocols demand laboratory capacity investment from Australian beef and Chinese tea exporters. The Kanto region's Seikatsu Club cooperatives displace traditional supermarket procurement through direct farmer relationships.
Vietnam
Ho Chi Minh City and Hanoi urban middle-class expansion outpaces certified organic supply availability. Alibaba's refrigerated last-mile networks penetrate Mekong Delta sourcing belts for fresh vegetable aggregation. Early entrants capture shelf-space premiums before local production scales to meet demand.
Asia-Pacific Organic Food Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and certification niches. The market structure fragments across farm-to-retail chains, captive pasture operators, and third-party certifiers. Three archetypes dominate: integrated supply chain controllers, export-oriented dairy processors, and grain specialization houses. Competitive moves concentrate on cold-chain infrastructure partnerships and certification database integration.
Among Asia-Pacific-based operators, Sresta Natural Bioproducts and 24 Mantra Organic exemplify the integrated supply chain archetype through South Indian farm-to-retail control. Ausnutria Dairy represents the export-oriented processor tier with Shaanxi and Heilongjiang captive pasture operations. These anchors illustrate how certification alignment and geographic concentration determine competitive positioning.
| Leading Market Players |
|---|
| General Mills |
| Amy's Kitchen |
| White Wave Foods |
| Sresta Natural Bioproducts |
| 24 Mantra Organic |
| Hain Celestial |
| Organic Valley |
| Ausnutria Dairy (China) |
| United Natural Foods |
| Others |
Value Network & Pricing Analysis
Shaanxi and Heilongjiang captive pasture operations anchor organic infant formula supply, concentrating margin capture with export-oriented dairy processors while contract farming networks across the Indo-Gangetic plain compete on thinner spreads.
Pricing Analysis
India's FSSAI organic labeling rules dictate the pricing tier structure across the Asia-Pacific organic food market. Three-tier pricing structure across premium certified, transition-grade, and uncertified conventional levels separates EU Organic and JAS-compliant exports from domestic premium channels and informal farm-gate sales. Price differentiation rests on certification grade and cold-chain delivery cost, with tier-one Chinese urban households showing lowest price sensitivity for infant formula and fresh vegetables. Cost compression in smallholder-sourced grains is intensifying because auditor capacity constraints delay market entry for compliant volume.
Supply Chain Analysis
Extended payment terms from Alibaba and JD.com supply-chain finance facilities ease working capital pressure for South Indian farm-to-retail chains. Geographic supply concentration centers on China, India, and Australia, with raw material dependencies spanning organic feed grains, pastureland access, and biological pest management inputs. Single-source vulnerability runs through Shaanxi captive pasture operations serving infant formula manufacturing. Distribution runs through e-commerce cold-chain networks into Southeast Asian cities alongside traditional supermarket procurement in tier-one Chinese districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific organic food incumbents face substitution pressure from precision-fermented dairy proteins and lab-cultivated meat alternatives that bypass pasture-based supply constraints entirely.
For Market Incumbents: Entrench certification database integration as a defensive moat against blockchain-enabled traceability startups. Capture auditor capacity through exclusive partnerships with FSSAI-accredited bodies before inspection backlogs worsen. Defend against precision-fermented substitutes by emphasizing pasture-provenance narratives in parental marketing for infant formula.
For New Entrants and Emerging Players: Establish a beachhead in Vietnamese and Indonesian urban middle-class procurement before local organic production scales. Target Ho Chi Minh City and Hanoi fresh vegetable segments where Alibaba's cold-chain penetration outpaces certified supply availability. Deploy direct-to-pantry subscription models with batch-level traceability as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed integrated farm-to-retail chains possessing captive South Indian sourcing belts and FSSAI certification infrastructure. Five-to-ten year viability hinges on bilateral recognition agreement expansion between EU Organic, JAS, and emerging national standards. Watch for SAMR data-sharing mandate acceleration as the inflection signal compressing third-party verification costs and favoring platform-scale operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | JD.com's refrigerated last-mile networks enable fresh organic vegetable penetration into Southeast Asian cities. |
| Certification Database Integration | Blockchain convergence with FSSAI and SAMR systems compresses audit-to-shelf transparency cycles for infant formula exporters. |
| Captive Pasture Expansion | Ausnutria Dairy's Shaanxi and Heilongjiang operations secure quota-free EU market access through TGA alignment. |
| Direct-to-Pantry Subscription Launch | Seikatsu Club cooperatives and JD.com membership programs displace traditional supermarket procurement in tier-one districts. |
| Millet Specialization Investment | Sresta Natural Bioproducts anchors climate-adaptive grain diversification aligned with India's organic rotation requirements. |
Research Methodology
A spread of perspectives from organic certification body executives, cold-chain logistics operators, supermarket category buyers, and infant formula regulatory affairs leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FSSAI compliance filings, SAMR audit disclosures, JD.com logistics infrastructure announcements, and Indo-Gangetic plain agricultural trade data. Bottom-up volume aggregation from farm-level production estimates triangulated against top-down demand modeling from urban household penetration surveys.
Demand-supply balance dynamics across product type, distribution channel, end user, and certification alignment governed the analytical framework over the projection horizon. Segmentation dimensions modeled included fruits and vegetables versus dairy versus grains, e-commerce versus supermarket versus direct sales, household versus food manufacturer demand, and EU Organic versus JAS versus FSSAI certification tiers. CAGRs derived from historical trajectory analysis adjusted for regulatory conversion timelines and cold-chain infrastructure buildout schedules. Forecast inputs incorporated auditor capacity expansion rates and bilateral recognition agreement negotiation progress.
Stress conditions across organic feed grain price volatility, FSSAI inspection backlog duration, and precision-fermented substitute adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification harmonization progress and e-commerce penetration rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Non-GMO Food Market
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
Organic Soda Market
Organic Food and Beverages
Organic Fruit Powder Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
Organic Pasta Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Europe Organic Food and Beverages Market
Organic Food and Beverages
Canada Organic Food Market
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Organic Cocoa Market
Organic Food and Beverages
Organic Ice Cream Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
Brazil Organic Food Market