
 France Diagnostic Imaging Equipment Market | 2026-2036
France Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
France Diagnostic Imaging Equipment Market Insights
Oncology applications within hospital networks is pivoting toward AI-enhanced imaging platforms that streamline radiologist workflow and reduce diagnostic latency. Siemens Healthineers leverages its installed base of MRI and CT systems to sustain service revenue streams across France's university hospital centers. GE Healthcare anchors its position through deep integration with digital imaging archives that dominate the public hospital procurement landscape. Philips competes on hybrid imaging modalities that merge functional and anatomical data for complex cardiac cases.
France diagnostic imaging equipment encompasses ionizing and non-ionizing systems that generate visual representations of internal anatomy for clinical diagnosis, with magnetic field strengths in MRI typically ranging from 1.5 to 3 Tesla and CT scanners employing X-ray tube voltages between 80 and 140 kVp to optimize tissue contrast. X-ray systems retain the largest installed footprint across French healthcare facilities due to their lower capital threshold and versatility in emergency settings. Ultrasound segments are capturing expanded utilization in point-of-care cardiology workflows where portability and real-time guidance outperform fixed modalities. AI-enhanced technology layers are concentrating margin pools in software subscriptions and predictive maintenance contracts rather than hardware sales alone.
ANSM governs medical device conformity assessment in France while the EU MDR imposes stricter clinical evidence requirements that lengthen approval timelines for new imaging platforms. CE marking under MDR Article 52 now demands recurring post-market surveillance that pushes manufacturers toward cloud-connected devices capable of remote performance logging. Stakeholders must monitor how France's regional health agencies align hospital capital budgets with MDR transition deadlines and digital health interoperability mandates.
Market Dynamics
France's diagnostic imaging sector is compressing around EU MDR compliance deadlines that force hospital networks into accelerated replacement cycles while AI software layers capture margin pools previously held by hardware vendors.
Growth Catalysts
- EU MDR Article 52:Stricter clinical evidence requirements and recurring post-market surveillance mandates are compelling French hospitals to upgrade aging imaging fleets with cloud-connected devices capable of remote performance logging.
- Oncology screening protocols:Public hospital networks are expanding MRI and CT capacities to support earlier cancer detection programs, with the Paris-Saclay medical cluster and Lyon biotech corridor driving concentrated demand.
- Hybrid imaging modalities:Cardiac departments are merging functional and anatomical data streams from PET-MRI and SPECT-CT systems to reduce diagnostic latency in complex valve and perfusion cases.
Market Restraints
- Helium supply concentration:MRI superconducting magnet cooling depends on helium imports concentrated in Qatar and Algeria, exposing French operators to price volatility and allocation disruptions.
- EU MDR transition friction:Extended approval timelines for new imaging platforms under stricter clinical evidence requirements are delaying product launches and freezing capital allocation decisions.
- CT dose optimization limits:ALARA principles and radioprotection regulations constrain X-ray tube voltage modulation ranges, capping tissue contrast resolution in bariatric and pediatric applications.
Strategic Opportunities
- Occitanie and Grand Est regions:Underpenetrated tertiary care networks outside Paris and Lyon present whitespace for mobile MRI and CT leasing models serving rural oncology screening.
- AI-enhanced workflow platforms:Convergence of deep learning inference engines with DICOM archives is creating subscription revenue streams that decouple vendor economics from hardware replacement cycles.
- Point-of-care ultrasound:Emergency departments and cardiology wards are adopting portable systems for real-time guidance, bypassing traditional radiology department bottlenecks.
Industry Challenges
- Radiologist workforce constraints:Specialized training pipelines for interventional and neuroradiology subspecialties are failing to match imaging volume growth, extending report turnaround times.
- Legacy PACS integration:Digital imaging archive heterogeneity across France's 29 regional health agencies complicates AI platform deployment and data interoperability.
- CE marking timeline compression:Manufacturers face compressed windows to complete MDR technical documentation and notified body conformity assessments before legacy certificate expiration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Diagnostic Imaging Equipment Market |
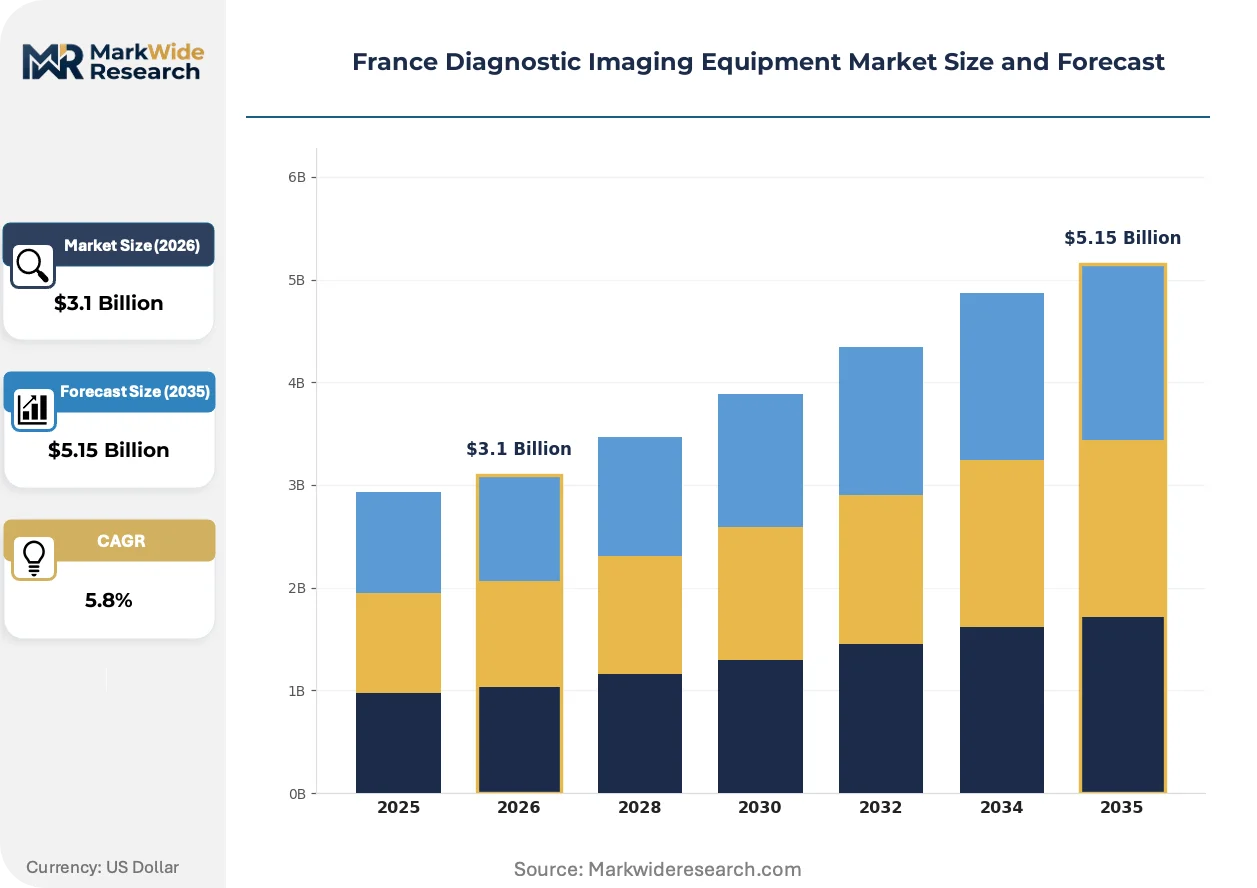
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, MRI, CT Scanner, X-Ray Technology: Digital Imaging, Cloud-Based, 3D Imaging, AI-Enhanced End User: Hospitals, Clinics, Laboratories, Research Institutes Application: Cardiology, Neurology, Orthopedics, Oncology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Hitachi Medical Systems, Samsung Electronics, Hologic, Inc., Agfa-Gevaert N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Diagnostic Imaging Equipment Market Trends and Innovations
AI inference engines are modularizing across imaging modalities, while regulatory pressure from Brussels reconfigures approval pathways and procurement patterns shift toward service-based economics.
Photon-counting CT detector arrays are modularizing spectral imaging capabilities into standard hardware platforms without requiring dedicated dual-source architectures. Academic medical centers in Marseille and Strasbourg are piloting these systems for coronary plaque characterization and renal stone composition analysis. The technology is compressing capital expenditure thresholds by enabling software-upgradable spectral functionality on base scanner configurations.
France's ANSM enforcement of EU MDR post-market surveillance obligations is mandating cloud-connected performance telemetry from installed imaging systems. Manufacturers must now embed remote monitoring agents capable of logging tube utilization, magnet cryogen levels, and detector calibration drift. Public hospital procurement specifications are increasingly weighting native connectivity compliance over raw technical specifications.
After-sales service unbundling is fragmenting vendor-customer relationships as French hospital networks separate equipment maintenance from software subscription agreements. Regional health agencies in Nouvelle-Aquitaine and Hauts-de-France are tendering multi-vendor service contracts through centralized purchasing consortia. Radiology departments are retaining direct relationships with AI platform vendors while outsourcing hardware uptime guarantees to third-party clinical engineering firms.
France Diagnostic Imaging Equipment Market Segmentation
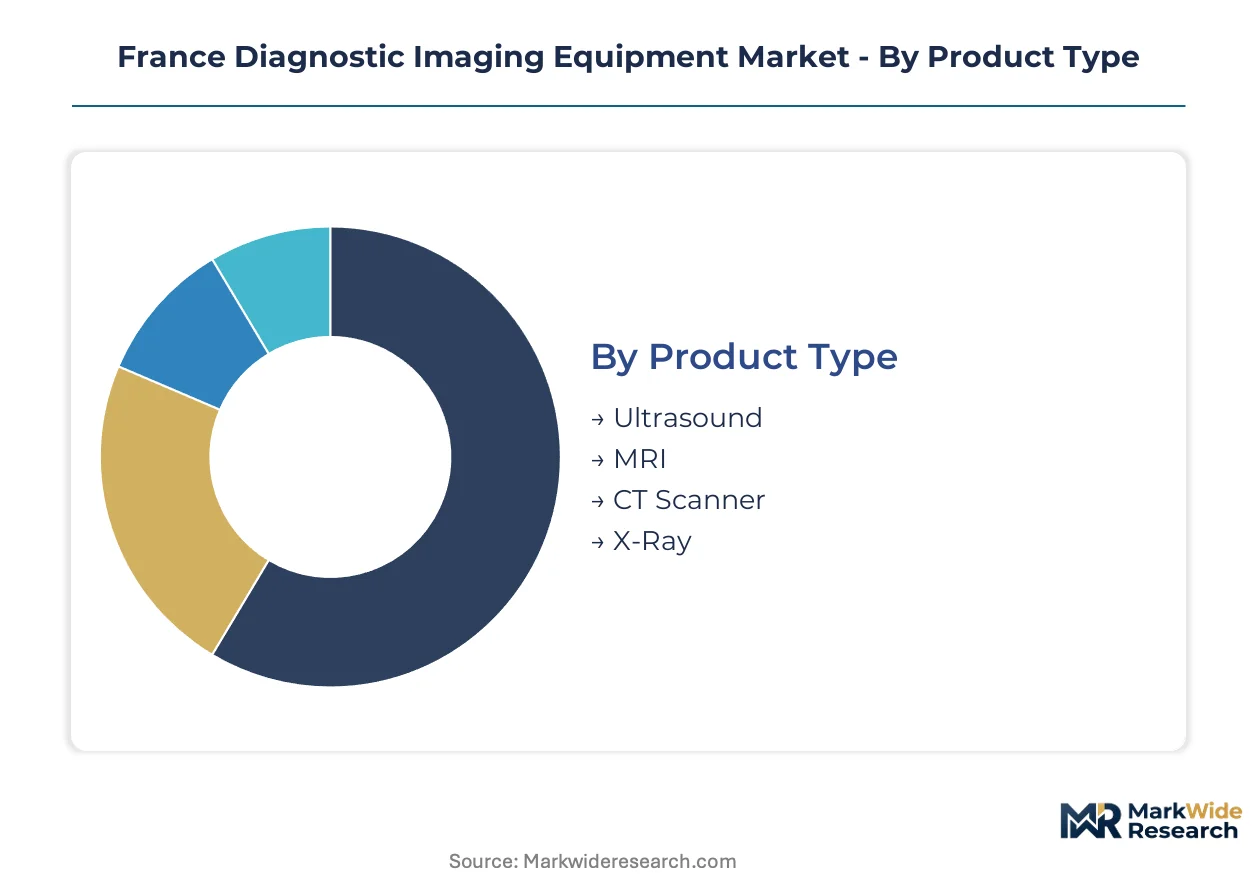
Segmentation reveals how capital intensity, clinical workflow integration, and regulatory compliance reshape procurement priorities across French healthcare networks. Each dimension exposes distinct margin structures and vendor positioning strategies.
Product Type:
Capital intensity varies dramatically across modalities, with superconducting MRI systems demanding tenfold higher upfront investment than portable X-ray units.
- MRI:Superconducting magnets operating at 1.5 to 3 Tesla require cryogenic helium cooling and dedicated shielded suites. University hospital centers in Paris-Saclay absorb the majority of high-field installations as oncology protocols demand sub-millimeter resolution for early-stage tumor characterization.
- CT Scanner:Multi-detector arrays with photon-counting detector layers command premium positioning in cardiac and emergency departments. Lyon biotech corridor facilities are replacing aging 64-slice systems with spectral-capable platforms to support coronary plaque analysis.
- X-Ray:Fixed and mobile radiography systems retain the broadest installed footprint across France's 29 regional health agencies due to lower procurement thresholds and versatility in trauma settings.
- Ultrasound:Portable systems with phased-array probes are penetrating point-of-care cardiology workflows where real-time guidance bypasses radiology department bottlenecks.
X-Ray absorbs the bulk of installed capacity; Ultrasound is expanding most quickly.
Technology:
Revenue models are pivoting from hardware transactions toward recurring software subscriptions as connectivity mandates intensify.
- AI-Enhanced:Deep learning inference engines embedded at the scanner level or layered atop PACS archives automate lesion detection and protocol selection. ANSM post-market surveillance requirements favor cloud-connected AI platforms capable of continuous algorithmic performance logging.
- Cloud-Based:Remote performance telemetry and predictive maintenance contracts are displacing traditional break-fix service agreements. Regional health agencies in Nouvelle-Aquitaine tender multi-vendor connectivity specifications that weight native MDR compliance over raw technical parameters.
- 3D Imaging:Volumetric reconstruction capabilities are standardizing across CT and MRI platforms for orthopedic pre-surgical planning and complex valve assessment.
- Digital Imaging:Flat-panel detector replacement of analog film systems continues in smaller clinics and private imaging centers outside major metropolitan clusters.
Digital Imaging retains the largest legacy installed base; AI-Enhanced platforms are climbing the fastest.
End User:
Procurement authority concentrates in centralized hospital networks with dedicated capital planning committees and EU MDR transition deadlines.
- Hospitals:Public hospital networks command the dominant share of high-value modality procurement, with university hospital centers leading hybrid imaging adoption for cardiac and oncologic applications. ANSM enforcement of MDR Article 52 post-market surveillance is accelerating replacement cycles across these institutions.
- Clinics:Private imaging centers and specialist clinics are capturing expanded ultrasound and point-of-care X-ray volumes as patient pathways decentralize from acute settings.
- Laboratories:Pathology and clinical laboratory networks utilize small-bore MRI and micro-CT systems for preclinical research and specimen analysis.
- Research Institutes:Academic medical centers in Marseille and Strasbourg pilot photon-counting CT and 7 Tesla MRI for coronary plaque characterization and functional neuroimaging protocols.
Hospitals absorb the bulk of installed capacity; Clinics are gaining share fastest.
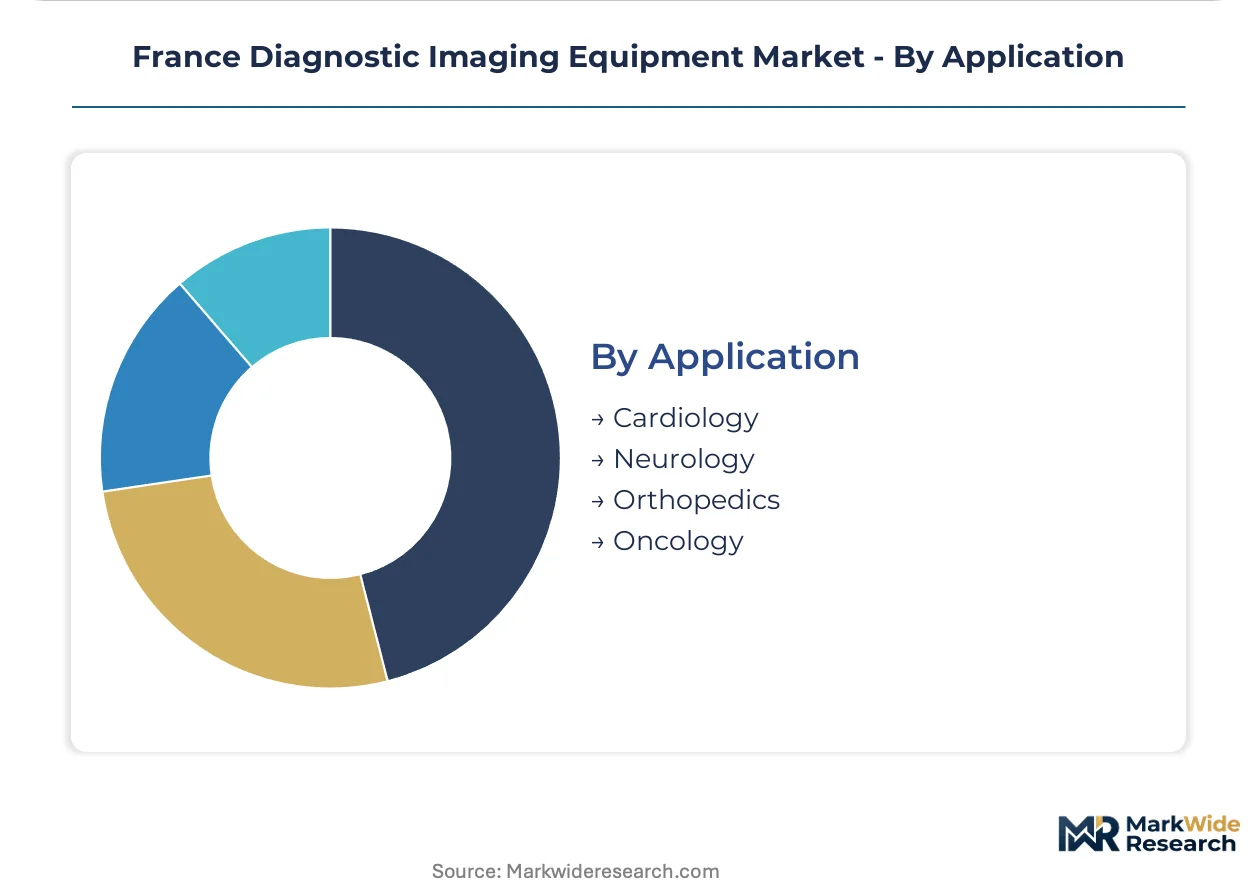
Application:
Clinical urgency and reimbursement intensity determine modality allocation across service lines.
- Oncology:Early detection protocols are driving MRI and CT fleet expansion in public hospital networks. The Paris-Saclay medical cluster concentrates demand for hybrid PET-MRI systems that merge functional and anatomical data streams.
- Cardiology:Complex valve and perfusion cases require spectral CT and cardiac MRI with real-time cine imaging. Emergency departments are adopting portable ultrasound for bedside hemodynamic assessment.
- Neurology:High-field MRI with diffusion tensor imaging capabilities supports stroke network triage and neurodegenerative disease monitoring across France's regional health agencies.
- Orthopedics:Weight-bearing CT and 3D fluoroscopy systems are penetrating sports medicine and arthroplasty planning workflows.
Oncology absorbs the bulk of high-value modality deployment; Cardiology is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France imports the majority of its high-field MRI superconducting magnets and CT detector arrays from German and Dutch manufacturing hubs, while domestic demand concentrates in university hospital centers and regional oncology networks. Production capacity for helium-cooled magnet systems remains concentrated outside French borders, exposing procurement timelines to cross-border logistics constraints.
Île-de-France
The Paris-Saclay medical cluster commands the densest concentration of hybrid PET-MRI and 7 Tesla research systems, driven by Institut Gustave Roussy's expansion of early-stage tumor characterization protocols. ANSM enforcement of EU MDR post-market surveillance obligations accelerates replacement cycles across Assistance Publique-Hôpitaux de Paris networks. Siemens Healthineers and GE Healthcare anchor service operations in the Saclay plateau to support 24-hour uptime guarantees for oncologic emergency imaging.
Auvergne-Rhône-Alpes
Lyon's biotech corridor drives demand for spectral CT and cardiac MRI as Hospices Civils de Lyon replaces aging 64-slice systems with photon-counting platforms. The regional health agency's 2024-2028 capital plan prioritizes MDR-compliant cloud-connected devices capable of remote performance telemetry. Clermont-Ferrand's university hospital pilots AI-enhanced stroke triage networks linking peripheral clinics to tertiary neuroradiology hubs.
Provence-Alpes-Côte d'Azur
Marseille's academic medical centers pilot photon-counting CT for coronary plaque characterization and renal stone composition analysis. The region's oncology screening expansion targets underpenetrated Alpes-Maritimes and Var departments with mobile MRI leasing models. Aix-Marseille University's hospital network embeds EU MDR Article 52 compliance into procurement specifications for all new imaging platforms.
Hauts-de-France
Lille's university hospital center leads adoption of point-of-care ultrasound in emergency departments, bypassing traditional radiology bottlenecks for bedside hemodynamic assessment. The regional health agency tenders multi-vendor service contracts through centralized purchasing consortia, unbundling hardware maintenance from software subscriptions. Calais and Dunkirk peripheral hospitals rely on teleradiology links to Lille for complex neuroradiology case review.
Occitanie
Toulouse's aerospace engineering ecosystem spills over into medical imaging R&D, with academic hospitals piloting 3D fluoroscopy systems for orthopedic pre-surgical planning. The region presents whitespace for mobile CT and MRI leasing models serving rural oncology screening in Aveyron and Lozère. Montpellier's university hospital network negotiates AI platform subscriptions separately from hardware procurement, fragmenting traditional vendor relationships.
France Diagnostic Imaging Equipment Market Competitive Landscape
Top-tier vendors anchor the premium imaging modality tier, while mid-scale specialists and regional service providers occupy maintenance and aftermarket niches. Siemens Healthineers leverages its installed base across French university hospitals to sustain recurring service revenue, while GE Healthcare anchors positions through digital imaging archive integration. Philips competes on hybrid imaging modalities merging functional and anatomical data streams. Strategic moves concentrate on AI software layer acquisitions and predictive maintenance contract unbundling from hardware sales.
Within the diversified medical technology tier, Siemens Healthineers and GE Healthcare exemplify integrated platform vendors with deep PACS archive penetration across French public hospital networks. Koninklijke Philips N.V. occupies a position in hybrid imaging, particularly where cardiac PET-MRI and SPECT-CT convergence reduces diagnostic latency. Fujifilm Holdings Corporation represents the diagnostic film-to-digital transition archetype, with flat-panel detector replacement cycles continuing in smaller clinics outside metropolitan clusters. Canon Medical Systems Corporation and Hitachi Medical Systems sit within the mid-tier modality specialist segment, competing on price-performance ratios for CT and MRI base configurations.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Fujifilm Holdings Corporation |
| Canon Medical Systems Corporation |
| Hitachi Medical Systems |
| Samsung Electronics |
| Hologic, Inc. |
| Agfa-Gevaert N.V. |
| Others |
Pricing and Supply Chain Analysis
EU MDR Article 52 compliance mandates gate qualified supply access for imaging equipment vendors seeking premium-tier positioning in French hospital procurement cycles. Manufacturers embedding native cloud connectivity and remote performance telemetry capture pricing power over break-fix service competitors, while regional health agencies weight MDR conformity above raw technical specifications in capital allocation decisions.
Pricing Analysis
Margin tightening in base-configuration CT and MRI systems reflects helium supply volatility and extended EU MDR approval timelines compressing hardware margins. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by AI software bundling and predictive maintenance contract structures. University hospital centers in Paris-Saclay and Lyon exhibit lowest price sensitivity due to centralized capital budgets and oncology protocol mandates. Private imaging clinics in peripheral regions face acute cost-down pressure, accelerating adoption of refurbished systems and third-party service contracts.
Supply Chain Analysis
France's domestic-content requirements under EU procurement directives reshape sourcing patterns for superconducting MRI magnets and photon-counting CT detector arrays. Production concentrates in Germany, the Netherlands, and Japan, with helium cooling systems drawing from Qatar and Algeria. Supply chain risk centers on single-source vulnerability for liquid helium imports subject to export allocation disruptions. Distribution runs through centralized regional health agency purchasing consortia, fragmenting direct vendor relationships into multi-tier service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into AI software layers and predictive maintenance capabilities determines competitive survival as hardware margins compress across French diagnostic imaging markets. Vendors capturing recurring subscription revenue decouple economics from capital replacement cycles.
For Market Incumbents: Anchor service revenue streams through deep PACS archive integration and MDR-compliant cloud connectivity mandates that lock hospital networks into long-term performance telemetry contracts. Siemens Healthineers and GE Healthcare defend positions by unbundling hardware sales from AI platform subscriptions, while regional health agencies consolidate procurement through multi-vendor service consortia threatening direct relationships. For New Entrants and Emerging Players: Begin with mobile MRI and CT leasing models targeting underpenetrated rural oncology networks in Occitanie and Grand Est, where tertiary care infrastructure gaps exceed capital budget constraints. Portable ultrasound systems for point-of-care cardiology workflows offer the most penetrable entry vector, bypassing radiology department bottlenecks through emergency department procurement channels. For Investors and Strategic Acquirers: ANSM enforcement of EU MDR post-market surveillance obligations is the leading indicator that cloud-connected device capabilities will consolidate vendor economics around software recurring revenue rather than hardware transactions. Acquisition targets should emphasize AI inference engine developers with DICOM archive integration and established hospital pilot programs, with inflection signals tracked through regional health agency connectivity compliance weighting in procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 52 compliance accelerates replacement cycles across Assistance Publique-Hôpitaux de Paris networks. |
| Hospital System Partnership | Deep PACS integration locks university hospital centers into long-term service revenue streams. |
| Software Companion Development | AI-enhanced workflow platforms capture margin pools previously held by hardware vendors alone. |
| Reimbursement Strategy | Alignment with France's national cancer plan drives MRI fleet expansion for early detection protocols. |
| Backward Integration | In-house helium recycling capabilities mitigate supply concentration risk from Qatar and Algeria imports. |
Research Methodology
Multi-period observation of hospital procurement database entries, ANSM device registration filings, and regional health agency capital plan disclosures anchored the trend analysis, supplemented by interviews with hospital biomedical engineers, radiology department heads, GPO contracts managers, and imaging equipment service technicians. Secondary validation drew from EU MDR technical documentation databases, French customs import records for superconducting magnets, and hospital financial disclosure filings. Bottom-up modality installation tracking triangulated against top-down regional health agency budget allocations.
Segment-weighting across product type, technology tier, end-user category, and clinical application dimensions structured the analytical framework. CAGRs derived from installed base growth rates, replacement cycle compression factors, and software subscription penetration curves. Forecast inputs incorporated EU MDR transition deadline impacts on capital allocation timing and helium supply price volatility assumptions.
Underlying measurement precision varies by segment; AI-enhanced platform revenue streams carry tighter precision than legacy hardware transaction estimates given disclosure granularity differences. Forecasts reflect documented assumptions regarding MDR enforcement consistency and regional health agency digital interoperability mandates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
Asia Pacific Magnetic Resonance Imaging (MRI) Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Global Portable Magnetic Resonance Imaging Market
Medical Imaging
Spinal Imaging Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Industrial Radiography Equipment Market